
 Ethylenediamine (EDA) Market | 2026-2036
Ethylenediamine (EDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylenediamine (EDA) Market Foresight
Chinese ethylenediamine producers is expanding captive ethylene oxide supply to secure feedstock economics across the Asia-Pacific basin. Nouryon leverages integrated ethylene amine complexes in the Netherlands to sustain pharmaceutical-grade output for European chelating agent makers. BASF SE anchors its EDA position through backward integration into ethylene oxide and ammonia streams at Ludwigshafen. Dow Chemical Company competes on scale in North American water treatment and agrochemical intermediate channels.
Ethylenediamine is a linear aliphatic diamine with the formula C₂H₈N₂, produced industrially via the reaction of ethylene dichloride with ammonia or through reductive amination of ethanolamine, serving primarily as a versatile chemical intermediate for chelating agents, corrosion inhibitors, and polyamide resins. Industrial-grade material dominates volume throughput due to its ubiquity in water treatment and surfactant manufacturing, while pharmaceutical-grade commands premium positioning amid tightening pharmacopeial standards. Agrochemical synthesis applications are expanding fastest as diamine-based fungicides and herbicide intermediates gain traction in high-intensity farming regions. Electronic-grade EDA occupies a specialized niche where semiconductor wafer cleaning protocols demand sub-ppb metal impurity thresholds.
EPA oversight of ethyleneamines under the Toxic Substances Control Act shapes permissible emission profiles and workplace exposure limits for U.S. manufacturing facilities. REACH registration requirements in Europe mandate comprehensive toxicological dossiers that elevate compliance costs for importers and smaller producers. China's MEE enforces increasingly stringent volatile organic compound controls on amine production clusters in Jiangsu and Shandong provinces. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where capacity investments will face accelerated permitting timelines versus extended compliance burdens.
Market Dynamics
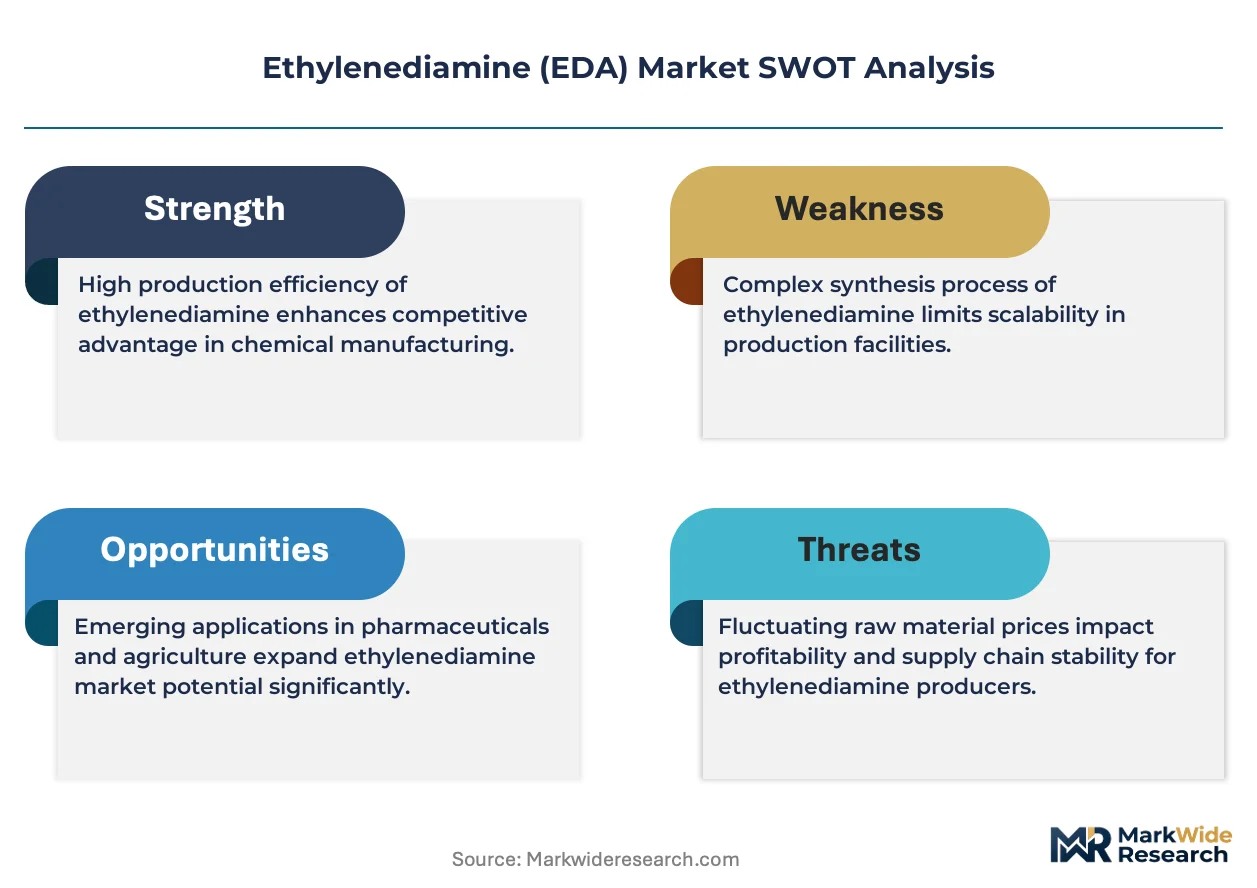
Feedstock economics and regulatory purity mandates are compressing margins for non-integrated producers while rewarding those with captive ethylene oxide supply. The divergence between industrial-grade and pharmaceutical-grade specifications is widening compliance burdens across manufacturing footprints.
Growth Catalysts
- Agrochemical intensification:High-yield farming regions are scaling diamine-based fungicide and herbicide intermediate production. Farmers in intensive cultivation zones demand stronger crop protection chemistries.
- REACH purity escalation:ECHA registration requirements for ethyleneamines are elevating quality thresholds across European chelating agent applications. Importers face expanded toxicological dossier obligations.
- Semiconductor wafer protocols:Electronic-grade EDA with sub-ppb metal impurity specifications is penetrating advanced chip fabrication lines. Cleaning chemistry suppliers are qualifying ultra-high-purity material.
Market Restraints
- Ethylene oxide volatility:Feedstock price swings and supply interruptions constrain cost predictability for non-integrated manufacturers. Captive ethylene oxide production has become a structural necessity.
- Jiangsu-Shandong concentration:Chinese amine production clustering creates geographic supply risk from regional environmental enforcement actions. MEE volatile organic compound controls trigger unplanned output curtailments.
- Monoethanolamine substitution:Alternative chelating agent feedstocks are displacing EDA in select water treatment formulations where metal sequestration efficiency requirements are moderate.
Strategic Opportunities
- India agrochemical formulation:Domestic crop protection manufacturing expansion under PLI scheme incentives creates demand for imported diamine intermediates. CDSCO registration pathways are streamlining for qualified suppliers.
- Carbon capture solvents:EDA derivatives are penetrating post-combustion carbon dioxide absorption systems. Power sector decarbonization projects are piloting amine-based scrubbing chemistries.
- Biocide harmonization:EU BPR approval convergence for diamine-based antimicrobial formulations is opening professional hygiene applications. Formulators are repositioning product lines toward regulated biocidal product categories.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance documentation for pharmaceutical-grade EDA extends qualification cycles. Manufacturers face 18-24 month validation periods for new supply relationships.
- Specialized logistics infrastructure:Corrosive material handling requirements and temperature-controlled transport for electronic-grade product strain distribution networks. Cold chain integrity failures risk batch disqualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylenediamine (EDA) Market |
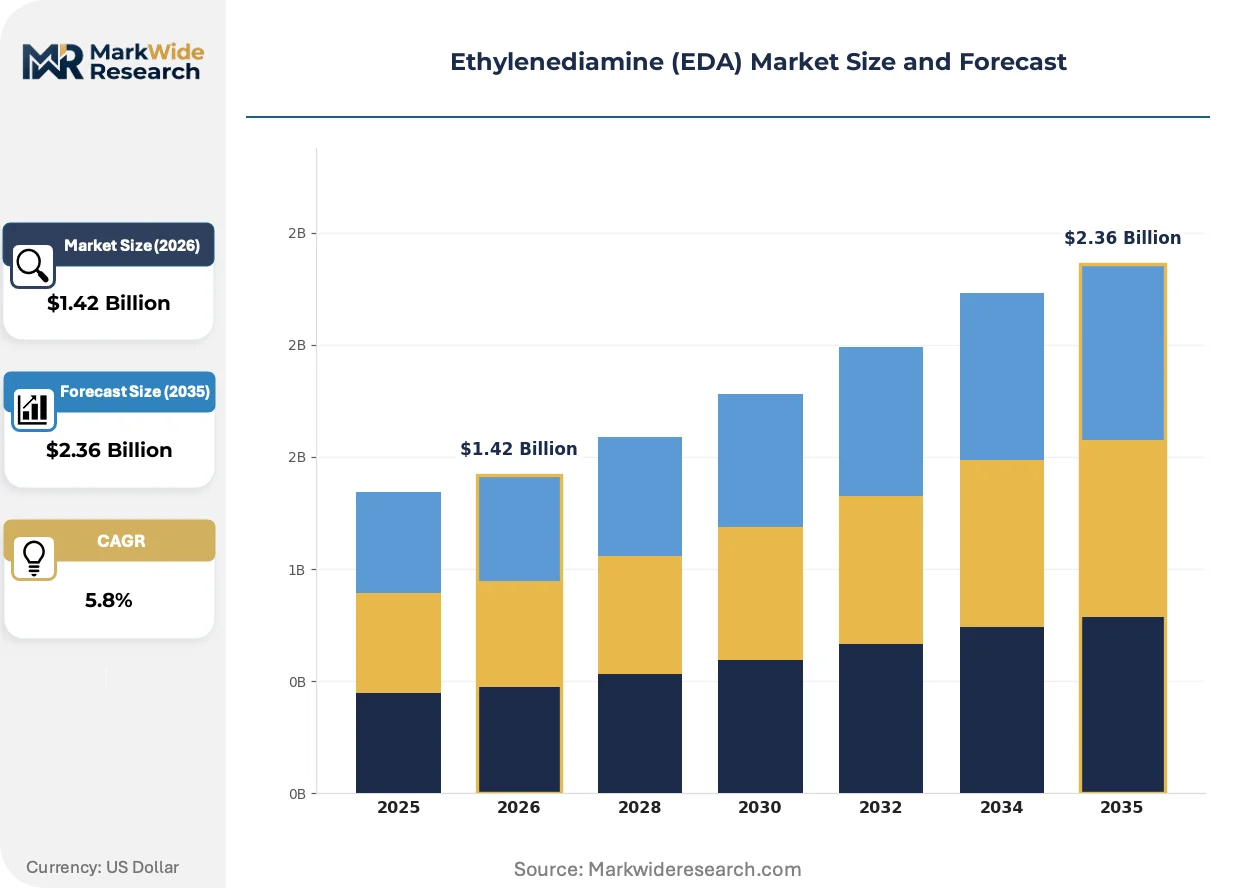
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Electronic Grade, Food Grade, Technical Grade Application: Water Treatment, Surfactants, Agrochemical Synthesis, Rubber Processing, Dye Manufacturing End Use Industry: Textile Manufacturing, Pesticide Production, Polymer Manufacturing, Metalworking Fluids, Paints & Coatings Packaging Type: Drums, Bulk Tanks, Carboys, Intermediate Bulk Containers, Cylinders |
| Companies Covered | Nouryon, Tosoh Corporation, BASF SE, AkzoNobel N.V., Delamine BV, Dow Chemical Company, SABIC, Arkema Group, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylenediamine (EDA) Market Shifts & Advancements
Process intensification and regulatory convergence are reshaping how EDA manufacturers configure production assets and qualify output grades. Technology adoption patterns are splitting between commodity scale and specialty purity plays.
Continuous flow reductive amination technology is absorbing capital investment from batch reactor replacement programs. Pharmaceutical-grade producers in the Netherlands and Germany are retrofitting legacy assets to reduce solvent waste and energy intensity. This process architecture is absorbing regulatory pressure on emission profiles while enabling real-time quality monitoring that batch systems cannot match.
EPA Toxic Substances Control Act oversight of ethyleneamines is tightening workplace exposure limit enforcement across Texas and Louisiana manufacturing corridors. Facilities are installing closed-loop sampling systems and enhanced vapor recovery to preempt citation risk. Agrochemical intermediate channels are absorbing the compliance cost pass-through more readily than water treatment formulators.
Specification-driven procurement is consolidating buyer relationships around dual-source qualified suppliers with demonstrated pharmacopeial compliance. Large chelating agent manufacturers are reducing vendor counts from five to two qualified sources per region. This concentration is most visible in European pharmaceutical and electronics verticals where audit fatigue favors incumbent relationships over price competition.
Ethylenediamine (EDA) Market Segmentation
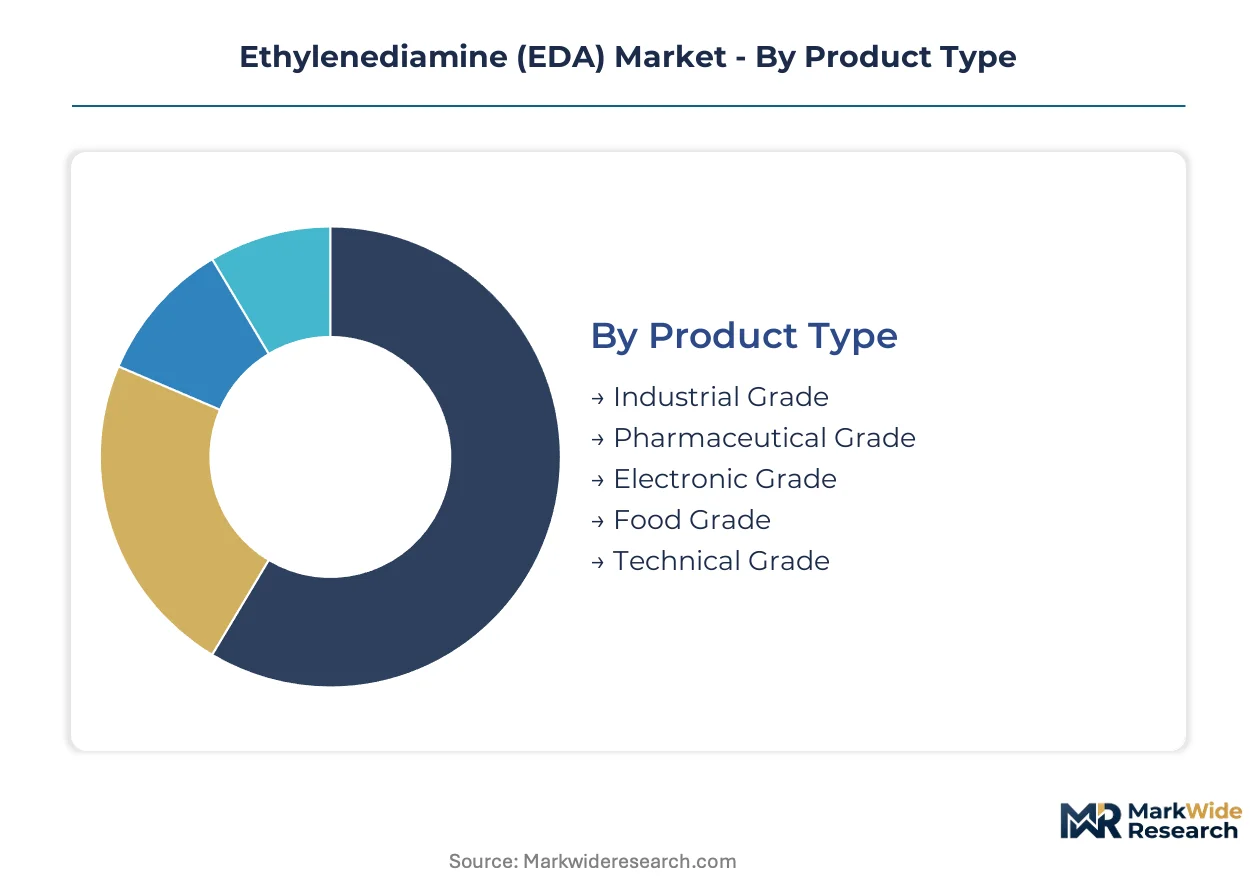
Grade-specific purity thresholds and application-driven specification requirements fragment the EDA landscape into distinct supply tiers. Manufacturers configure production assets around either commodity volume or specialty certification, with limited overlap between operational models.
Product Type:
Capital intensity escalates sharply from industrial-grade bulk production to electronic-grade purification infrastructure requiring sub-ppb metal removal systems.
- Industrial Grade:Standard purity material produced via continuous reductive amination serves water treatment and surfactant channels. Chinese producers in Jiangsu and Shandong provinces dominate volume output for regional chelating agent manufacturers.
- Pharmaceutical Grade:USP and EP-compliant material demands dedicated batch validation lines and 18-24 month qualification cycles. European chelating agent makers in the Netherlands and Germany anchor demand amid REACH purity escalation.
- Electronic Grade:Sub-ppb metal impurity specifications for semiconductor wafer cleaning command premium positioning. Advanced chip fabrication lines in Taiwan and South Korea drive qualification programs.
- Food Grade:FSSAI and FDA-compliant material for food additive applications requires dedicated handling protocols.
- Technical Grade:Intermediate purity tier serves adhesive and sealant manufacturing with moderate metal tolerance.
Industrial grade absorbs the bulk of installed capacity; electronic grade is expanding most quickly.
Application:
Margin profiles diverge between commodity water treatment formulations and regulated agrochemical intermediates subject to EPA and REACH compliance burdens.
- Water Treatment:Chelating agent formulations for boiler and cooling tower applications represent the foundational demand base. Municipal and industrial facilities across the United States specify EDA-based metal sequestration chemistries.
- Agrochemical Synthesis:Diamine-based fungicide and herbicide intermediates are scaling fastest as high-intensity farming regions adopt stronger crop protection chemistries. CDSCO registration pathways in India are streamlining for qualified suppliers.
- Surfactants:Foam control and emulsification applications in personal care and industrial cleaning formulations.
- Rubber Processing:Accelerator applications for tire and industrial rubber manufacturing, concentrated in China.
- Dye Manufacturing:Chromophore intermediate synthesis for textile colorant production.
Water treatment maintains the largest volume footprint; agrochemical synthesis shows the steepest expansion trajectory.
End Use Industry:
Customer concentration varies from fragmented metalworking fluid blenders to consolidated pesticide producers with dual-source qualification requirements.
- Pesticide Production:Formulators of diamine-based crop protection chemistries drive pharmaceutical-grade demand. Large manufacturers are reducing vendor counts from five to two qualified sources per region.
- Polymer Manufacturing:Polyamide resin and epoxy curing agent applications anchor industrial-grade consumption.
- Textile Manufacturing:Dye fixation and fiber treatment applications, concentrated in India and Bangladesh.
- Metalworking Fluids:Corrosion inhibitor formulations for machining and stamping operations.
- Paints & Coatings:Crosslinking agent applications in industrial and marine protective coatings.
Pesticide production commands the highest purity premiums; polymer manufacturing absorbs the greatest total volume.
Packaging Type:
Logistics infrastructure requirements scale from standard drum handling to specialized cold chain systems for electronic-grade material.
- Bulk Tanks:Railcar and tank truck deliveries serve integrated chelating agent producers with captive consumption. Temperature-controlled transport for electronic-grade product strains distribution networks.
- Drums:Standard 200-liter steel packaging dominates industrial-grade channel distribution.
- Intermediate Bulk Containers:Flexible and rigid IBC formats reduce handling costs for mid-volume agrochemical formulators.
- Carboys:Smaller-volume packaging for laboratory and pilot-scale pharmaceutical applications.
- Cylinders:Pressurized containment for specialized gas-phase applications and semiconductor process chemistry.
Bulk tanks handle the majority of tonnage; intermediate bulk containers are gaining share fastest among regional formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide availability near the US Gulf Coast anchors North American production economics, while captive ammonia supply in Ludwigshafen and Rotterdam sustains European output. Chinese producers cluster in Jiangsu and Shandong provinces where MEE environmental enforcement shapes operating rates.
United States
Water treatment formulators in Texas and Louisiana drive industrial-grade consumption for boiler and cooling tower applications. EPA Toxic Substances Control Act enforcement tightens workplace exposure limits across Gulf Coast manufacturing corridors. Houston-area petrochemical complexes host integrated ethylene amine production serving domestic chelating agent manufacturers.
China
Rubber accelerator and chelating agent output in Jiangsu and Shandong provinces absorbs the majority of regional EDA throughput. MEE volatile organic compound controls trigger unplanned output curtailments in concentrated production clusters. Nantong and Zibo industrial zones dominate domestic capacity expansion for agrochemical intermediate channels.
Germany
Pharmaceutical-grade demand from European chelating agent makers concentrates in the Rhine-Neckar industrial region. REACH registration requirements for ethyleneamines elevate toxicological dossier obligations for importers. BASF SE's Ludwigshafen complex anchors backward integration into ethylene oxide and ammonia feedstock streams.
Netherlands
Integrated ethylene amine complexes in Rotterdam sustain pharmaceutical-grade output for chelating agent manufacturers across the European Union. ECHA purity escalation mandates compress margins for non-integrated importers. Nouryon's Delfzijl and Rotterdam assets represent captive feedstock integration at scale.
India
Domestic crop protection manufacturing expansion under PLI scheme incentives creates demand for imported diamine intermediates. CDSCO registration pathways streamline for qualified agrochemical suppliers. Gujarat and Maharashtra industrial corridors absorb inbound pharmaceutical-grade material for pesticide formulation.
Ethylenediamine (EDA) Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and grade certification dimensions. The vendor base splits between consolidated petrochemical conglomerates with captive ethylene oxide supply and specialized amine producers dependent on merchant feedstock markets. Three archetypes dominate: integrated petrochemical majors, regional chelating agent suppliers, and electronic-grade purification specialists. Capacity expansion and pharmacopeial certification represent the dominant competitive moves as buyers consolidate vendor relationships.
Among integrated petrochemical conglomerates, BASF SE and Dow Chemical Company exemplify the captive-feedstock archetype through upstream control over ethylene oxide and ammonia streams. Nouryon occupies a position within the European pharmaceutical-grade tier, leveraging Rotterdam-area integration to serve chelating agent makers under REACH compliance regimes. These three entities represent distinct geographic anchors—German, North American, and Dutch—each embedding regulatory compliance into competitive positioning rather than treating certification as an aftermarket overlay.
| Leading Market Players |
|---|
| Nouryon |
| Tosoh Corporation |
| BASF SE |
| AkzoNobel N.V. |
| Delamine BV |
| Dow Chemical Company |
| SABIC |
| Arkema Group |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
MEE volatile organic compound enforcement in Jiangsu and Shandong provinces gates qualified supply access and premium-tier pricing for pharmaceutical-grade and electronic-grade material. Buyers without dual-source qualification face extended lead times and cost pass-throughs from compliant producers.
Pricing Analysis
After-sales technical support and pharmacopeial compliance documentation are bundled into pharmaceutical-grade and electronic-grade contracts while industrial-grade transactions remain unbundled spot purchases. Three-tier pricing structure across pharmaceutical, industrial, and technical grades separates certification-driven premiums from commodity volume discounts. Price differentiation centers on REACH registration status and captive ethylene oxide supply, with non-integrated producers absorbing cost compression from feedstock volatility. Water treatment formulators exhibit highest price sensitivity due to monoethanolamine substitution options, while semiconductor cleaning chemistry suppliers accept premium positioning for sub-ppb metal impurity guarantees.
Supply Chain Analysis
Skilled process operator availability in Rotterdam, Ludwigshafen, and Texas Gulf Coast petrochemical corridors constrains capacity expansion timelines for continuous flow reductive amination retrofits. Supply concentrates in China, Germany, and the Netherlands, with Chinese Jiangsu-Shandong clusters feeding regional chelating agent and rubber accelerator manufacturers. Raw material dependencies center on merchant ethylene oxide, anhydrous ammonia, and ethanolamine feedstocks. Single-source vulnerability runs through concentrated Chinese production zones exposed to unplanned MEE enforcement curtailments. Distribution runs through bulk tank railcar networks for integrated chelating agent producers and temperature-controlled drum logistics for electronic-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reductive amination technology is displacing legacy batch reactor systems, compressing energy intensity and emission profiles while enabling real-time quality monitoring.
For Market Incumbents: Deploy backward integration into captive ethylene oxide supply to defend margin position against feedstock volatility and monoethanolamine substitution threats in water treatment channels. Expand pharmacopeial certification assets in the Netherlands and Germany to capture REACH-driven vendor consolidation among European chelating agent makers. For New Entrants and Emerging Players: Agrochemical formulators in Gujarat and Maharashtra industrial corridors present the most penetrable entry point, with CDSCO registration streamlining for qualified diamine intermediate suppliers. Target India PLI scheme beneficiaries through technical partnership structures that bypass 18-24 month USP validation cycles required for pharmaceutical-grade positioning. For Investors and Strategic Acquirers: Nouryon's Rotterdam integration strategy is the leading indicator that captive feedstock control and REACH compliance infrastructure will separate viable acquisition targets from stranded merchant-feedstock assets. Long-term viability in this market hinges on electronic-grade purification capability and demonstrated dual-source relationships with Taiwan and South Korea semiconductor fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF SE's Ludwigshafen complex demonstrates how captive feedstock supply insulates margin from merchant market volatility. |
| Continuous Flow Reductive Amination Retrofit | Pharmaceutical-grade producers in the Netherlands are absorbing capital to reduce solvent waste and energy intensity. |
| Pharmacopeial Certification Investment | USP and EP compliance documentation extends qualification cycles but locks in dual-source vendor status with pesticide formulators. |
| Electronic-Grade Purification Scale-Up | Sub-ppb metal removal systems command premium positioning with Taiwan and South Korea semiconductor wafer cleaning protocols. |
| Carbon Capture Solvent Partnership | EDA derivatives in post-combustion amine scrubbing open power sector decarbonization channels beyond traditional chelating agent applications. |
Research Methodology
Independent corroboration across plant managers at integrated ethylene amine complexes, procurement leads at downstream chelating agent manufacturers, and distribution channel partners underwrites the qualitative findings in this study. Primary interviews with technical R&D directors and regulatory affairs specialists at REACH-registered facilities were validated against customs and trade data, Cefic sector reports, and SEC 10-K disclosures from petrochemical conglomerates. Bottom-up capacity and consumption estimates were triangulated against top-down market sizing derived from ethylene oxide derivative consumption patterns.
Comparable-period anchoring to historical ethyleneamine production and consumption trends established the baseline for projections across the analysis window. The analytical framework modeled segmentation dimensions including grade tier (industrial, pharmaceutical, electronic), end-use industry (agrochemical synthesis, water treatment, semiconductor fabrication), packaging format (bulk tank, drum, IBC), and regional production hub concentration. CAGRs were derived from regression analysis of feedstock cost trajectories and regulatory compliance cost pass-through elasticities, with forecast inputs incorporating MEE enforcement intensity scenarios and REACH registration renewal timelines.
Several conditions sit outside the modeled scope, including abrupt feedstock supply disruptions from Gulf Coast weather events and unilateral tariff adjustments affecting ethylene oxide derivative trade flows. Forecasts reflect assumptions regarding continuous technology adoption rates and regulatory enforcement consistency across jurisdictions. Material deviation in MEE curtailment frequency or EPA Toxic Substances Control Act rulemaking velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Global Lactate Salts Market
Chemicals
Ferric Phosphate Market
Chemicals
Aerosol Insecticides Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Aluminum Phosphide Market
Chemicals
Betaine Market
Chemicals
Power Plant Chemicals Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Cummene Derivatives Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Fatty Alcohol Ethoxylates Market