
 Non-GMO Food Market | 2026-2036
Non-GMO Food Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Food Market Analysis
Ingredient traceability revenue is reshaping competitive positioning in packaged food. The Hain Celestial Group leverages its vertically controlled supply chain to secure non-GMO soybean and corn inputs. SunOpta anchors its margin profile through specialized extrusion capabilities for alternative proteins. Nestlé SA competes by extending its verification protocols across multiple beverage and dairy lines.
Non-GMO food denotes products derived from organisms whose genetic material has not been altered through in vitro nucleic acid techniques, with verification typically requiring polymerase chain reaction testing for novel DNA sequences below threshold levels. These products serve consumers seeking to avoid transgenic proteins and associated herbicide residues in daily nutrition. Cereals and snacks occupy mature volume positions where brand loyalty and certification costs have stabilized margin structures. Beverages represent the fastest-growing product type as functional drinks and plant-based milks attract verification-seeking formulations. The Non-GMO Project Verified certification commands premium positioning in retail channels, while USDA Organic overlaps create dual-label strategies that concentrate margin pools in health food store distribution.
The Non-GMO Project Verified standard, USDA National Organic Program regulations, and EU Regulation 1829/2003 on genetically modified food and feed collectively shape ingredient sourcing protocols and label claims across major markets. These frameworks raise compliance costs for imported commodities while creating market access barriers for non-compliant suppliers. Stakeholders must monitor evolving gene-editing definitions as regulators reconsider whether techniques like CRISPR fall outside traditional GMO classifications.
Market Dynamics
Ingredient verification protocols are fragmenting supply chains as retailers demand polymerase chain reaction documentation for every input lot, forcing processors to rebuild procurement systems around identity preservation rather than commodity pooling.
Growth Catalysts
- EU Regulation 1829/2003:Mandatory GMO labeling thresholds below 0.9% drive reformulation across imported packaged goods, expanding addressable market for verified ingredient suppliers.
- Functional beverage formulations:Plant-based protein drinks and adaptogenic blends require non-GMO certification to access premium retail placement in natural channel distribution.
- Japanese consumer label literacy:METI-backed educational campaigns on genome editing versus traditional GMOs create differentiated demand for third-party verified products.
Market Restraints
- Non-GMO soybean premiums:Identity-preserved IP soybeans trade at 15-40% above commodity benchmarks, compressing margins for mid-scale processors without captive origination.
- US Heartland supply concentration:Over 85% of domestic non-GMO corn production clusters in Iowa, Illinois, and Indiana, creating weather and logistics risk for coastal manufacturers.
- Detection cost escalation:Event-specific PCR testing for stacked-trait contamination requires specialized laboratory infrastructure unavailable in many sourcing regions.
Strategic Opportunities
- Indian export channel development:FSSAI alignment with Codex Alimentarius standards positions Indian organic processors to capture European non-GMO feed ingredient demand.
- Gene-editing regulatory arbitrage:USDA SECURE Rule exclusions for certain genome-edited crops create dual-track sourcing strategies separating CRISPR-derived from transgenic inputs.
- Blockchain traceability integration:Distributed ledger verification from farm to retail shelf reduces audit costs while satisfying EU Green Deal due diligence requirements.
Industry Challenges
- PCR technician scarcity:Certified molecular biology analysts capable of event-specific GMO detection command premium wages, constraining laboratory throughput expansion.
- Co-manufacturer certification lag:Third-party production facilities often lack Non-GMO Project Verified status, forcing brand owners to absorb facility audit costs or forfeit contract manufacturing options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Food Market |
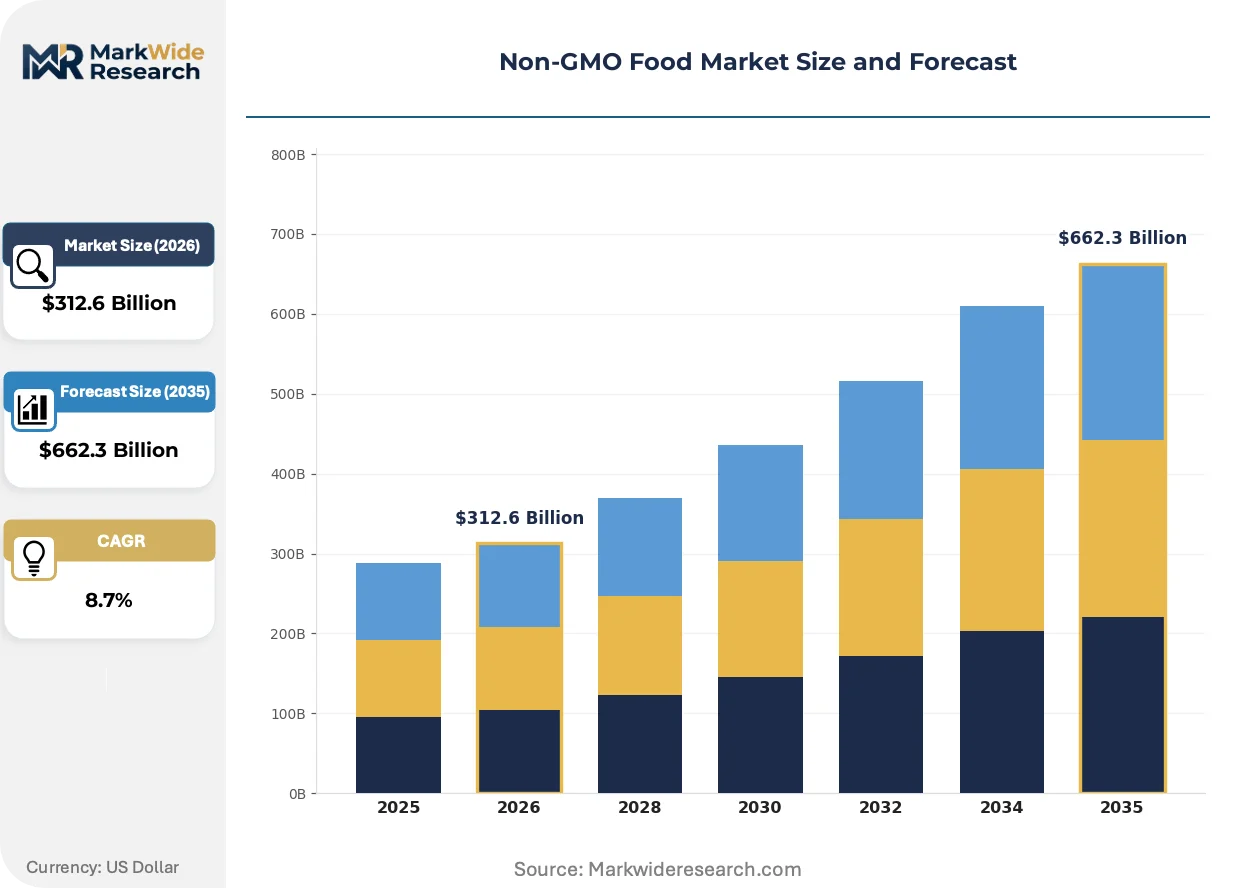
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Snacks, Beverages, Dairy End User: Households, Restaurants, Food Manufacturers, Retailers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales Certification: USDA Organic, Non-GMO Project Verified, ISO 22000, Fair Trade |
| Companies Covered | The Hain Celestial Group, Blue Diamond Growers, Amy's Kitchen, Inc., SunOpta, Organic Valley, Nestlé SA, PepsiCo Inc., General Mills Inc., Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Food Market Emerging Trajectories
Digital verification infrastructure is displacing paper-based chain-of-custody documentation, compressing audit cycles from weeks to hours while enabling real-time ingredient provenance queries by retail buyers and regulators alike.
Blockchain-enabled traceability platforms are virtualizing the documentation layer between grain elevators and finished goods manufacturers. Large retail chains including Costco and Whole Foods Market now require QR-accessible lot histories for verified product placement. This compression of verification latency is forcing commodity traders to invest in sensor networks and distributed ledger infrastructure previously reserved for pharmaceutical cold chains.
EU F-Gas Regulation phase-down schedules are indirectly tightening non-GMO production requirements as controlled-environment agriculture operators seek open-pollinated seed varieties to reduce climate-control energy intensity. Dutch greenhouse operators have begun specifying non-GMO tomato and pepper cultivars to maintain yield stability under reduced refrigeration loads. German retailers are responding by expanding shelf-space allocation for regionally sourced verified produce.
Certification-driven preference rotation is restructuring procurement authority within retail organizations. Category managers at US natural food chains now hold veto power over supplier selection based on Non-GMO Project Verified status, displacing traditional cost-per-case metrics in high-margin perimeter categories. This behavioral shift concentrates volume with multi-certified suppliers capable of delivering organic-plus-non-GMO bundled documentation.
Non-GMO Food Market Segmentation
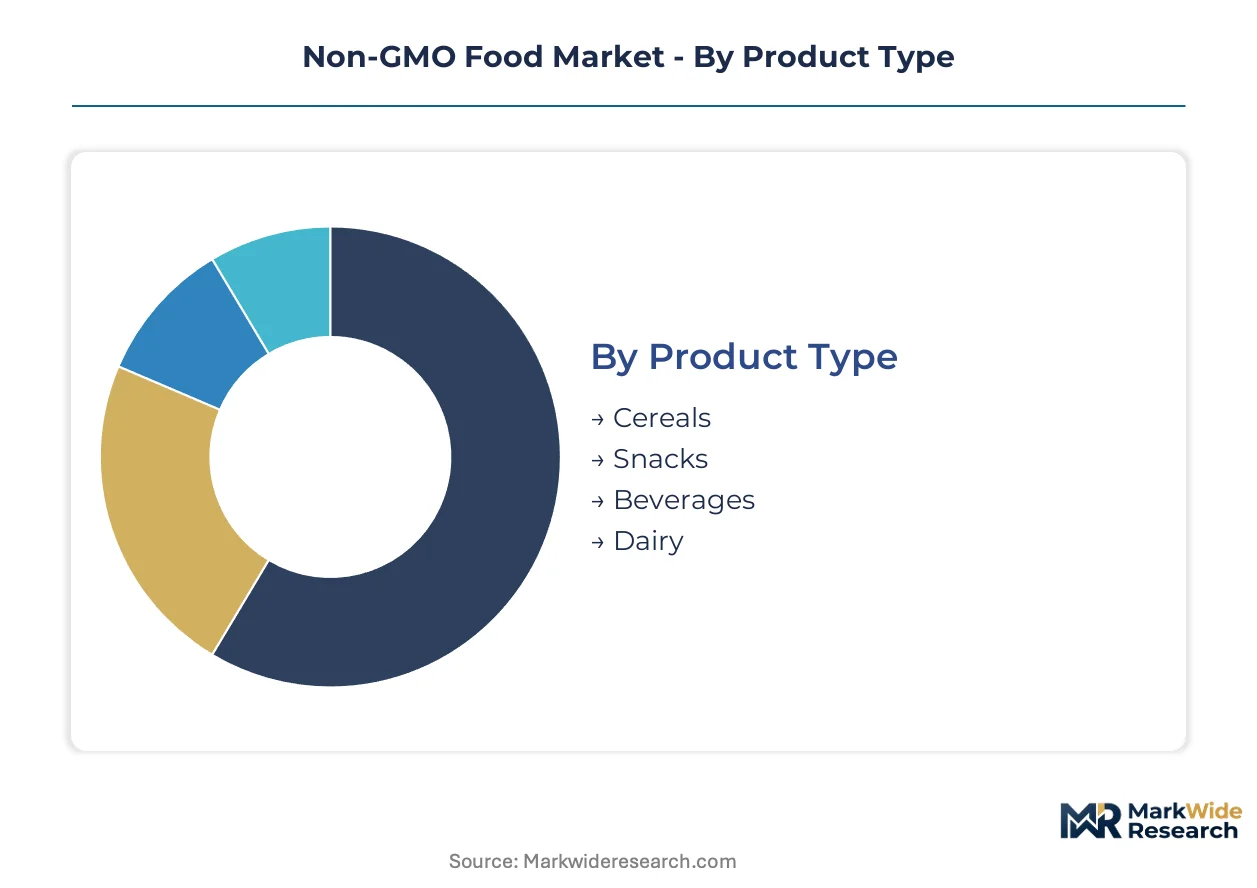
Segmentation in the non-GMO food market determines compliance pathways, margin structures, and channel access. Certification requirements and distribution complexity vary sharply across product categories and buyer types.
Product Type:
End-use applications span breakfast consumption, on-the-go snacking, functional hydration, and protein-based meal components.
- Cereals:Breakfast grains and granolas requiring identity-preserved corn and soy inputs. Demand concentrates in German and US households seeking dual organic-non-GMO labeling for morning meal routines.
- Snacks:Extruded chips, bars, and popcorn products. Japanese convenience retailers and US natural food chains drive specification for verified ingredient sourcing in portable formats.
- Beverages:Plant-based milks, functional drinks, and juices.
- Dairy:Milk, yogurt, and cheese from non-GMO feed-supplied livestock.
The dominant share belongs to Cereals, while Beverages is closing the gap fastest.
End User:
Buyer sophistication ranges from label-conscious consumers to procurement professionals managing multi-tier supply chains.
- Households:Individual consumers purchasing through retail channels. METI educational campaigns in Japan and EU Green Deal awareness programs elevate verification expectations.
- Restaurants:Foodservice operators menuing verified ingredients. Fast-casual chains in the United States specify non-GMO proteins and oils for transparency marketing.
- Food Manufacturers:Industrial processors reformulating packaged goods.
- Retailers:Private label developers and category managers controlling shelf placement.
Households command the volume base, though Food Manufacturers are expanding verification requirements most aggressively.
Distribution Channel:
Channel selection dictates certification visibility, price realization, and traceability documentation intensity.
- Online Retail:E-commerce platforms with filtering and subscription capabilities. German and US direct-to-consumer brands leverage digital verification badges to reduce customer acquisition costs.
- Supermarkets:Mass-market retail with perimeter and center-store placement. Costco and Whole Foods Market mandate QR-accessible lot histories for verified product authorization.
- Health Food Stores:Specialty retail with trained staff and dual-label concentration.
- Direct Sales:Farm-gate and community-supported agriculture models.
Supermarkets retain the largest throughput, yet Online Retail is gaining share fastest among subscription-format functional beverages.
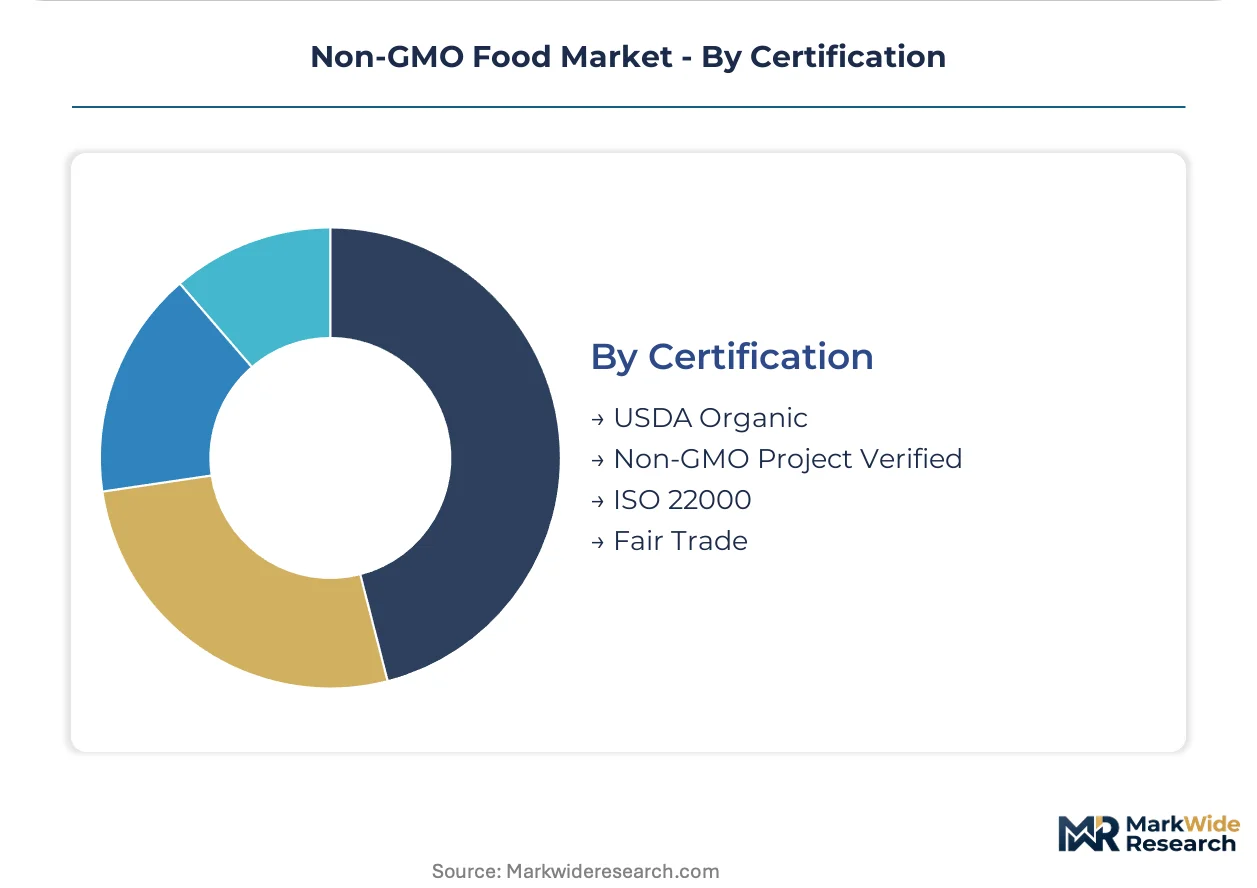
Certification:
Regulatory and voluntary standards create tiered market access with overlapping compliance burdens.
- USDA Organic:Federal program prohibiting GMO inputs with comprehensive production standards. US processors combine this with Non-GMO Project Verified for premium placement in natural channel distribution.
- Non-GMO Project Verified:Third-party standard requiring PCR testing below threshold levels. EU Regulation 1829/2003 alignment expands recognition for this certification in cross-border trade.
- ISO 22000:International food safety management system.
- Fair Trade:Ethical sourcing certification with occasional non-GMO overlap.
Non-GMO Project Verified holds the broadest retail recognition, while USDA Organic carries the strictest production requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across markets. Japanese households absorb substantial verification premiums, while Brazilian consumers demand non-GMO credentials at commodity-equivalent pricing. German buyers occupy the middle ground, trading up selectively within staple categories.
United States
Iowa, Illinois, and Indiana cluster over 85% of domestic non-GMO corn production, creating coastal supply bottlenecks. USDA National Organic Program regulations overlap with Non-GMO Project Verified standards, forcing dual-certification investments from processors serving natural channel distribution. Chicago-based ingredient traders now maintain dedicated identity-preserved handling facilities to service CPG reformulation demand.
Germany
EU Regulation 1829/2003 mandates GMO labeling below 0.9% thresholds, compelling packaged goods importers to source verified supply chains. REWE and Edeka category managers wield veto authority over supplier selection based on third-party certification status. The Lower Saxony corridor hosts specialized laboratories capable of event-specific PCR testing for stacked-trait contamination screening.
Japan
METI-backed educational campaigns on genome editing versus traditional GMOs elevate consumer label literacy beyond regional peers. Convenience retailers specify non-GMO verification for functional beverage placement in premium shelf locations. The Kanto region concentrates demand for third-party verified soy-derived ingredients in plant-based protein formulations.
India
FSSAI alignment with Codex Alimentarius standards positions organic processors to capture European non-GMO feed ingredient demand. Export-oriented soybean crushers in Madhya Pradesh and Maharashtra invest in IP handling infrastructure to access premium EU markets. The Gujarat cluster specializes in identity-preserved cumin and turmeric for verification-seeking spice blenders.
Brazil
Consumer price sensitivity constrains verification penetration outside affluent urban centers. ANVISA maintains GMO labeling requirements that create regulatory alignment with EU export standards. The Rio Grande do Sul corridor preserves non-GMO soybean germplasm for specialty export channels serving German and Japanese buyers.
Non-GMO Food Market Vendor Landscape
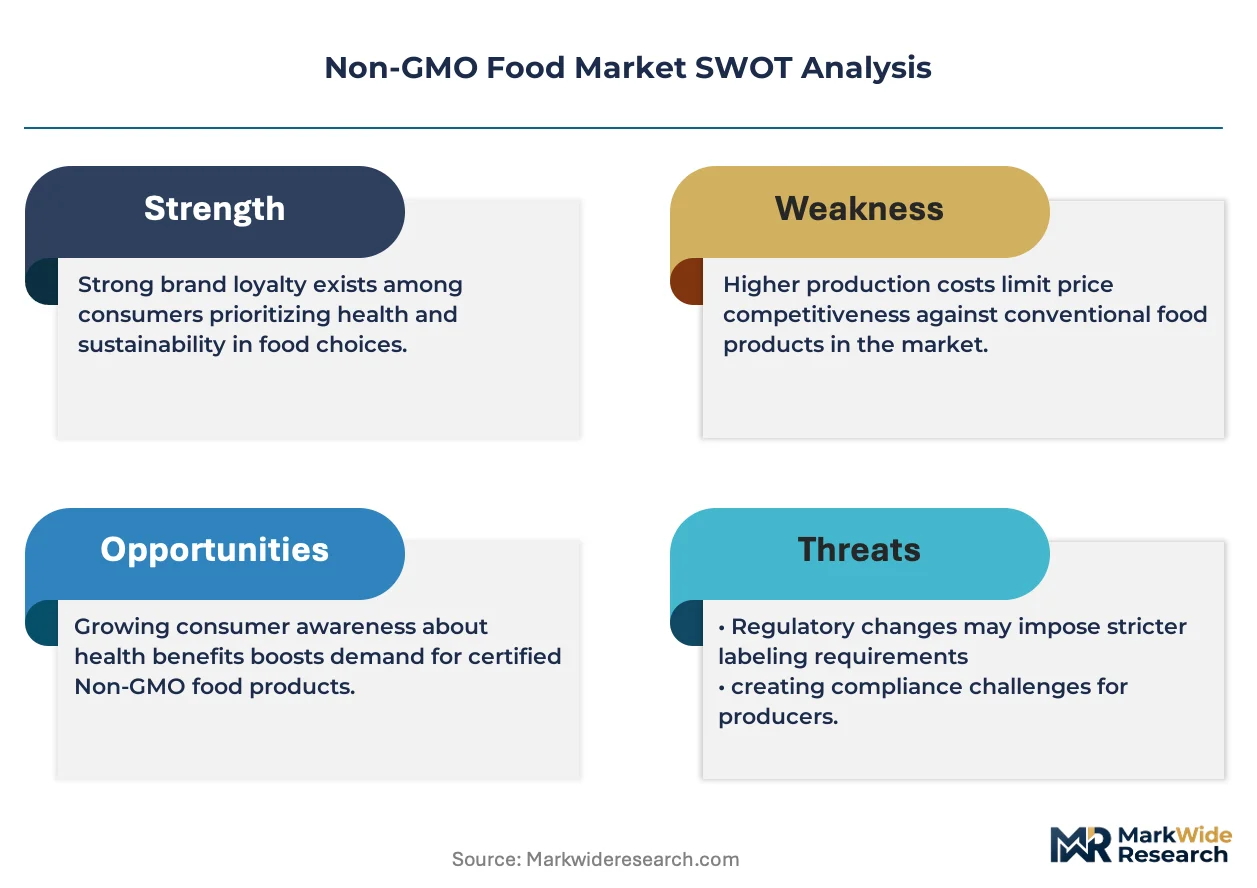
Capability concentration sits with vertically integrated specialists; scale advantage sits with diversified multinationals. The market structures around three tiers: identity-preserved supply chain operators, branded portfolio players, and private-label service providers. Consolidation pressure intensifies as retailers demand bundled organic-plus-non-GMO documentation. Dominant competitive moves include backward integration into captive origination and blockchain-enabled traceability partnerships.
Within the vertically integrated tier, The Hain Celestial Group and SunOpta exemplify supply chain control strategies. Among diversified multinationals, Nestlé SA occupies a position spanning beverage and dairy verification protocols. General Mills Inc. and Kellanova represent scale-driven players reformulating mature cereal and snack portfolios. Organic Valley anchors cooperative-structured dairy verification, while Amy's Kitchen, Inc. exemplifies family-owned positioning in frozen prepared meals.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Blue Diamond Growers |
| Amy's Kitchen, Inc. |
| SunOpta |
| Organic Valley |
| Nestlé SA |
| PepsiCo Inc. |
| General Mills Inc. |
| Kellanova |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Iowa-Illinois-Indiana corn clusters determines both certification-premium spreads and supply chain shape, forcing coastal processors to absorb logistics premiums or forfeit margin to identity-preserved handlers. This concentration dynamic compresses mid-tier pricing power while amplifying volatility exposure for non-captive buyers.
Pricing Analysis
Certification-bundled service contracts drive lifetime value for ingredient traders and CPG brand owners. Three-tier pricing structure across premium, standard, and economy levels separates Non-GMO Project Verified organic bundles from single-certification SKUs and commodity alternatives. Pricing pressure stems from PCR testing cost escalation as event-specific detection requirements multiply. Food manufacturers exhibit highest price sensitivity due to reformulation volume exposure, while Japanese household buyers absorb premiums with minimal elasticity.
Supply Chain Analysis
Extended payment terms from Dutch and German retailers strain working capital for Indian and Brazilian export processors. Geographic supply concentration centers on the United States for corn and soy inputs, India for organic spice derivatives, and Brazil for non-GMO soybean germplasm. Raw material dependencies include identity-preserved grain elevators, PCR-verified seed stock, and specialized extrusion equipment. Single-source vulnerability runs through the Chicago-traded IP handling infrastructure. Distribution runs through Costco and Whole Foods Market QR-mandated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-GMO food market sits in a cyclical recovery phase driven by EU Regulation 1829/2003 enforcement tightening, which compels systematic reformulation across imported packaged goods and sustains demand for verified supply chains.
For Market Incumbents: Pre-empt co-manufacturer certification lag by acquiring or building captive IP handling facilities in Iowa and Illinois corridors. Absorb facility audit costs internally rather than forfeit contract manufacturing flexibility to emerging private-label competitors. Secure backward integration into seed stock development to reduce germplasm licensing exposure. For New Entrants and Emerging Players: Indian organic processors with FSSAI-Codex alignment represent the most penetrable entry point for European non-GMO feed ingredient demand. Brazilian Rio Grande do Sul germplasm specialists targeting German and Japanese buyers offer second white-space opportunity. Lead with blockchain-traceability go-to-market positioning to bypass incumbent paper-documentation advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with captive origination and multi-certification bundling capability. Long-term viability over a 5-10 year window rests on laboratory infrastructure ownership and PCR technician pipeline control. Watch METI genome-editing regulatory clarifications as the signal for CRISPR-derived input arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IP Handling | Captive origination in Iowa-Illinois clusters secures margin control against commodity volatility. |
| Blockchain Traceability Partnership | Costco and Whole Foods Market QR mandates require distributed ledger compliance for shelf placement. |
| Multi-Certification Bundling | USDA Organic plus Non-GMO Project Verified documentation concentrates volume in natural channel distribution. |
| Laboratory Infrastructure Expansion | Event-specific PCR testing capacity alleviates technician scarcity constraining throughput growth. |
| Indian Export Channel Development | FSSAI alignment with Codex standards unlocks European non-GMO feed ingredient premium markets. |
Methodological Framework
Operator-level perspectives from grain elevator managers, CPG procurement directors, retail category buyers, and PCR laboratory technicians anchored the qualitative base. Primary interviews combined with secondary validation against USDA National Organic Program filings, EU Regulation 1829/2003 implementation records, FSSAI export certifications, and customs trade data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Scenario-bracketing around regulatory enforcement intensity and gene-editing definitional shifts bounded the projection range across the analysis window. Segmentation dimensions modeled include product type, certification tier, distribution channel, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for identity-preserved supply expansion rates and PCR testing cost curves.
Practitioners should monitor EU Commission gene-editing reconsiderations and METI educational campaign intensity for early signals of demand inflection. Forecasts reflect assumptions on certification threshold stability and laboratory capacity expansion. Macroeconomic commodity volatility, regulatory reclassification of CRISPR-derived inputs, or detection technology cost disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
South Africa Organic Food Market