
 Japan Organic Food Market | 2026-2036
Japan Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Organic Food Market Insights
Aftermarket service revenue from organic certification consulting is narrowing as producers bring compliance in-house. Ohsawa Japan leverages its long-standing JAS certification expertise to anchor premium positioning in domestic macrobiotic circles. Sokensha competes through specialized organic grain sourcing from Hokkaido cooperatives.
Organic food denotes agricultural products cultivated without synthetic pesticides, chemical fertilizers, or genetically modified organisms, with JAS certification requiring three years of transitional chemical-free soil management. Fruits and vegetables occupy the largest product-type share due to immediate perishability and visible quality differentiation. Online retail represents the fastest-growing distribution channel as urban consumers prioritize convenience and direct farm traceability.
METI oversees organic food labeling enforcement under the JAS Law, while the Ministry of Agriculture, Forestry and Fisheries administers organic production subsidies and export promotion programs. The Consumer Affairs Agency monitors false organic claims through periodic retail audits. Stakeholders must track evolving JAS equivalency negotiations with trading partners to secure import-export channel access.
Market Dynamics
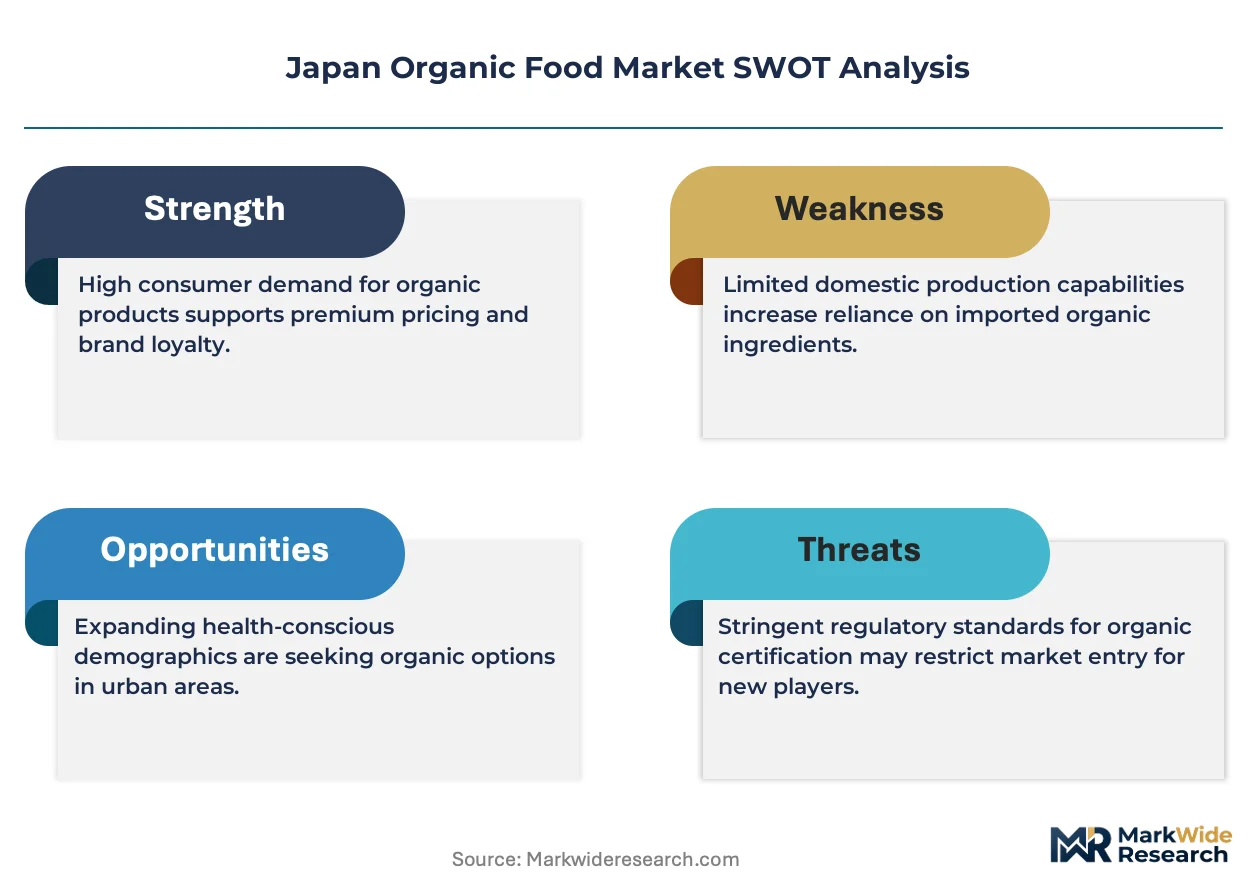
JAS certification compliance costs are compressing producer margins while concentrating market power among vertically integrated cooperatives that control transitional farmland access in Hokkaido and Kyushu.
Growth Catalysts
- Consumer Affairs Agency enforcement:Periodic retail audits for false organic claims are elevating certified product premiums and accelerating shelf-space consolidation for JAS-labeled goods in Tokyo convenience stores.
- Tokyo-Osaka urban corridor:Premium demand concentration in these prefectures is pulling Hokkaido grain cooperatives into direct distribution partnerships, bypassing traditional wholesale layers.
- Online retail infrastructure:Farm-to-table traceability platforms are collapsing information asymmetries between producers and metropolitan households, enabling price premiums previously captured by intermediaries.
Market Restraints
- Transitional soil management costs:The three-year chemical-free period required by JAS rules locks capital in unproductive land, deterring conventional farm conversions in rice-intensive regions.
- Hokkaido cooperative supply concentration:Organic grain sourcing dependence on northern island agricultural unions creates vulnerability to climate-induced yield volatility and shipping disruptions.
- Import equivalency negotiation friction:Unresolved JAS mutual recognition with EU organic standards limits cross-border product flows and traps domestic producers in single-market exposure.
Strategic Opportunities
- Kyushu underpenetration:Southern prefectures show lagging certified organic adoption despite favorable citrus-growing conditions, presenting first-mover positioning for transitional farmland aggregators.
- Direct-to-institutional channels:Hospital and school cafeteria procurement reforms are opening bulk contract pathways previously monopolized by conventional foodservice distributors.
- METI export promotion subsidies:Ministry of Economy, Trade and Industry programs targeting Southeast Asian markets offer co-funding for JAS-certified processors building overseas brand recognition.
Industry Challenges
- Certification auditor scarcity:Limited JAS-accredited inspection body capacity is extending approval timelines for new entrants, creating backlog bottlenecks in peak application seasons.
- Legacy IT integration:Small-scale producers transitioning to online retail face traceability software implementation costs incompatible with existing farm management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Organic Food Market |
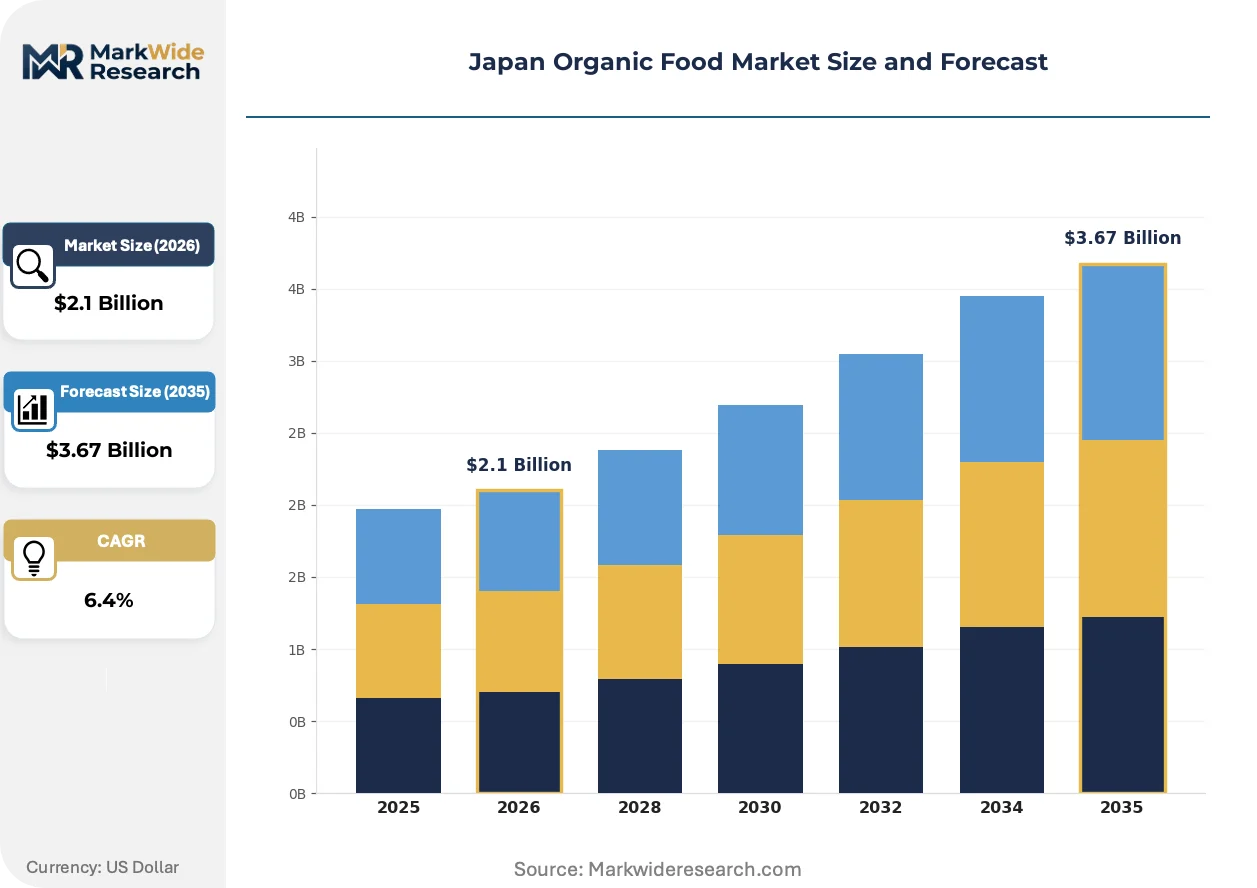
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Supermarkets, Organic Stores, Online Retail, Farmers Markets Customer Type: Health-conscious Consumers, Families, Restaurants, Grocery Chains Packaging Type: Reusable Bags, Biodegradable Containers, Glass Jars, Paper Wrappers |
| Companies Covered | Ohsawa Japan, Sokensha, Alisan, Eden Foods, Danone, General Mills, The Hain Celestial Group, Dole, United Natural Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Organic Food Market Trends and Innovations
Digital traceability infrastructure and regulatory enforcement intensification are restructuring how Japanese organic food moves from soil to consumer, compressing traditional intermediation layers.
Blockchain-enabled supply chain verification is collapsing documentation costs for JAS compliance audits. Hokkaido grain cooperatives are deploying distributed ledger systems to automate batch-level pesticide-free provenance records. The technology is collapsing third-party certification verification timelines from weeks to hours, enabling real-time export documentation for METI-promoted Asian markets.
METI labeling enforcement amendments under the JAS Law are tightening penalty structures for misrepresentation. Retailers now face published sanction lists for false organic claims, shifting inventory procurement toward certified-only suppliers. Tokyo metropolitan supermarkets are responding by segregating JAS-verified SKUs into dedicated fixture sections with enhanced visibility.
Subscription-based produce box models are fragmenting conventional retail channel dominance. Urban households in Osaka and Nagoya are bypassing supermarket intermediaries through direct farm partnerships managed via mobile applications. This channel shift is most visible among dual-income households prioritizing time-saving over price comparison, concentrating recurring revenue with integrated producer-cooperatives that control both cultivation and last-mile logistics.
Japan Organic Food Market Segmentation
Segmentation reveals how JAS certification requirements and distribution infrastructure reshape competitive positioning across product categories. Each dimension exposes distinct margin pressures and channel access patterns that determine producer viability in Japan's concentrated urban markets.
Product Type:
After-sales service intensity varies sharply across organic categories, with perishability driving traceability investment and certification audit frequency.
- Fruits:High perishability demands cold-chain precision and rapid JAS documentation turnover. Tokyo metropolitan retailers prioritize berry and citrus SKUs with visible farm-origin labeling, compressing margins for producers lacking integrated logistics.
- Vegetables:Leafy greens and root vegetables carry the highest certification audit density due to soil-contact contamination risk. Osaka convenience store chains are consolidating shelf space toward single-source vegetable suppliers with blockchain traceability, displacing fragmented wholesale aggregators.
- Grains:Hokkaido cooperatives dominate rice and wheat sourcing through captive farmland access.
- Dairy:Limited domestic organic dairy infrastructure constrains Kyushu and Tohoku expansion.
By volume, Vegetables leads. By growth pace, Fruits is ahead.
Distribution Channel:
Channel selection determines working capital intensity and JAS compliance documentation burden for producers at different scale tiers.
- Online Retail:Direct-to-consumer platforms collapse intermediary margins but impose traceability software costs. Dual-income households in Nagoya and Fukuoka are migrating subscription produce box spending toward integrated producer apps, bypassing supermarket markups entirely.
- Supermarkets:Tokyo and Osaka chains are segregating JAS-verified fixtures under Consumer Affairs Agency enforcement pressure, elevating certified supplier准入 barriers.
- Organic Stores:Macrobiotic specialty retailers anchor premium pricing in urban corridors.
- Farmers Markets:Direct producer-consumer contact limits scale but preserves margin capture for smallholders.
By transaction volume, Supermarkets dominates. By expansion trajectory, Online Retail is climbing the fastest.
Customer Type:
Procurement scale and certification documentation requirements segment customers into distinct service cost tiers.
- Health-conscious Consumers:Individual purchasers prioritize traceability transparency over price elasticity, concentrating spending toward subscription models with farm-visit verification features.
- Families:Multi-person households in Kanagawa and Saitama prefectures drive bulk organic vegetable procurement through online platforms with recurring delivery scheduling.
- Restaurants:Fine-dining establishments in Kyoto and Osaka seek JAS-certified ingredients for menu differentiation.
- Grocery Chains:Centralized procurement departments enforce supplier consolidation toward vertically integrated cooperatives.
By absolute spend, Grocery Chains leads. By margin contribution per transaction, Restaurants is gaining share fastest.
Packaging Type:
Packaging regulation under METI circular economy directives is reshaping material cost structures and shelf-life performance tradeoffs.
- Reusable Bags:Deposit-return systems in Tokyo metropolitan supermarkets reduce single-use waste but impose reverse logistics complexity on producers without dedicated collection infrastructure.
- Biodegradable Containers:PLA and starch-based materials face humidity sensitivity constraints in Japanese summer distribution, limiting adoption to short-radius supply chains.
- Glass Jars:Premium condiment and preserve categories retain glass for perceived quality signaling.
- Paper Wrappers:Dry grain and bakery segments favor kraft-based solutions for compostability compliance.
By deployment scale, Paper Wrappers leads. By regulatory tailwinds, Biodegradable Containers shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Japanese prefectures. Tokyo and Osaka consumers absorb premium organic markups with minimal elasticity. Rural Tohoku and Shikoku buyers remain highly price-responsive, limiting certified product penetration outside metropolitan corridors.
Kanto/Tokyo
Dual-income households in Tokyo, Kanagawa, and Saitama drive subscription produce box adoption. METI labeling enforcement under JAS Law elevates certified supplier准入 barriers for metropolitan retailers. Shibuya and Minato ward supermarkets segregate JAS-verified fixtures, concentrating shelf space toward vertically integrated cooperatives with blockchain traceability.
Kansai/Osaka
Osaka convenience store chains consolidate organic vegetable procurement toward single-source suppliers. The Consumer Affairs Agency's published sanction lists for false claims accelerate inventory shifts toward certified-only goods. Kyoto fine-dining establishments seek JAS-certified ingredients for menu differentiation, pulling premium produce from nearby Shiga and Nara prefectures.
Hokkaido
Hokkaido grain cooperatives dominate organic rice and wheat sourcing through captive farmland access. Ministry of Agriculture, Forestry and Fisheries production subsidies support transitional soil management for conventional farm conversions. Sapporo-based agricultural unions deploy distributed ledger systems to automate pesticide-free provenance records for METI-promoted Asian export markets.
Kyushu
Southern prefectures show lagging certified organic adoption despite favorable citrus-growing conditions in Kumamoto and Miyazaki. Fukuoka metropolitan households mirror Tokyo subscription patterns, but rural areas remain underpenetrated. First-mover transitional farmland aggregators target Kyushu for expansion, capitalizing on lower land costs relative to northern islands.
Chubu/Nagoya
Nagoya dual-income households prioritize time-saving over price comparison, concentrating recurring revenue with integrated producer-cooperatives. Aichi prefecture's automotive supply chain density limits agricultural labor availability, pushing organic operations toward mechanized grain production rather than labor-intensive vegetables. Gifu and Shizuoka tea growers explore organic certification for premium export positioning.
Japan Organic Food Market Competitive Landscape
Long-established domestic specialists and multinational packaged-food conglomerates split the market between certification-native expertise and scale-driven distribution. The competitive terrain favors players controlling transitional farmland access or possessing JAS audit infrastructure. Three archetypes dominate: vertically integrated agricultural cooperatives with captive Hokkaido grain supply; macrobiotic specialty retailers leveraging decades-long certification relationships; and global CPG groups applying overseas organic standards to imported product lines. Dominant competitive moves include direct-to-consumer platform launches and backward integration into farmland aggregation.
Among domestic specialists, Ohsawa Japan anchors premium positioning through long-standing JAS certification expertise in macrobiotic circles. Sokensha competes via specialized organic grain sourcing relationships with Hokkaido cooperatives. Eden Foods represents the import-dependent archetype, occupying shelf space through established North American organic supply chains rather than domestic certification investment. These three exemplify how competitive viability increasingly depends on controlling either farmland access, audit infrastructure, or cross-border equivalency recognition.
| Leading Market Players |
|---|
| Ohsawa Japan |
| Sokensha |
| Alisan |
| Eden Foods |
| Danone |
| General Mills |
| The Hain Celestial Group |
| Dole |
| United Natural Foods |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Hokkaido grain cooperatives is compressing spot premiums for organic rice while simultaneously elevating contract premiums for JAS-certified vegetable producers in Kyushu, creating divergent supplier behavior across product categories.
Pricing Analysis
After-sales service revenue from certification consulting anchors lifetime value for incumbent audit bodies. Three-tier pricing structure across JAS-certified premium, transitional standard, and uncertified economy levels stratifies the market. Price differentiation rests on blockchain traceability integration and METI enforcement compliance tiers. Cost compression in the economy tier is intensifying because conventional farms face three-year soil conversion lockup. Families in Saitama prefecture show highest price sensitivity; Tokyo fine-dining establishments absorb premiums with minimal elasticity.
Supply Chain Analysis
Upstream feedstock from Hokkaido grain cooperatives and Kyushu citrus growers feeds into metropolitan processing hubs. Organic farmland access draws from captive cooperative leases, individual transitional conversions, and Ministry of Agriculture, Forestry and Fisheries subsidy programs. Single-source vulnerability concentrates in Hokkaido cooperative supply for rice and wheat. Distribution runs through vertically integrated producer apps, Tokyo-Osaka supermarket chains, and institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as JAS enforcement intensity normalizes post-regulatory amendment, with Consumer Affairs Agency audit cycles driving predictable compliance investment waves.
For Market Incumbents: Harden JAS audit infrastructure capacity to capture certification backlog bottlenecks during peak application seasons. Deepen backward integration into Kyushu transitional farmland aggregation before land cost arbitrage closes. Threat substitution from direct-to-consumer platforms is elevating channel control as the critical defensive lever. For New Entrants and Emerging Players: Kyushu underpenetration offers first-mover positioning in citrus and vegetable categories with lower land acquisition costs than northern islands. Target hospital and school cafeteria procurement reforms opening bulk contract pathways. Launch farm-to-table traceability platforms with mobile subscription interfaces to bypass supermarket markups entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producer-cooperatives controlling both cultivation and last-mile logistics. Long-term viability over the next decade hinges on captive farmland access and blockchain traceability deployment. Watch for JAS equivalency negotiation breakthroughs with EU organic standards as the inflection signal for cross-border expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Hokkaido cooperatives automate JAS compliance documentation for METI-promoted Asian export markets. |
| Transitional Farmland Aggregation | Kyushu land cost arbitrage enables first-mover positioning before cooperative supply concentration extends southward. |
| Direct-to-Consumer Platform Launch | Dual-income households in Nagoya and Fukuoka bypass supermarket intermediaries through integrated producer apps. |
| Institutional Procurement Partnership | Hospital and school cafeteria reforms open bulk contract pathways previously monopolized by conventional distributors. |
| JAS Certification Infrastructure Expansion | Limited accredited inspection body capacity creates backlog bottlenecks for new entrants during peak seasons. |
Research Methodology
A standing panel of JAS certification auditors, organic cooperative procurement managers, Tokyo supermarket category buyers, and Consumer Affairs Agency enforcement officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against Ministry of Agriculture, Forestry and Fisheries subsidy records, METI labeling enforcement disclosures, and Hokkaido cooperative trade data. Bottom-up producer surveys and top-down retail audit triangulation anchored market sizing.
Scenario-bracketing around JAS equivalency negotiation outcomes and climate-induced yield volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and packaging format, with JAS certification tier as the industry-specific dimension. CAGRs derived from trend extrapolation of certified acreage expansion and urban household subscription adoption, incorporating METI export promotion subsidy disbursement patterns and Consumer Affairs Agency enforcement intensity indices.
The forecast holds incumbent behavior within observed patterns; aggressive farmland aggregation moves by institutional investors or rapid JAS-EU equivalency breakthroughs would shift outcomes beyond modeled ranges. Quarterly review of accredited auditor capacity utilization, Kyushu transitional conversion permit applications, and METI equivalency negotiation communiqués is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Brazil Organic Food Market