
 Organic Stevia Market | 2026-2036
Organic Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Stevia Market Analysis
Retail households is rotating toward food manufacturers as the dominant buyer archetype in organic stevia procurement. PureCircle Ltd leverages its vertical integration from leaf cultivation to refined extracts, sustaining cost advantages across the supply chain. Cargill Incorporated anchors North American distribution through its extensive food-ingredient infrastructure, while GLG Life Tech Corporation specializes in high-purity Reb M and Reb D steviol glycosides for premium formulations.
Organic stevia comprises glycoside compounds extracted from Stevia rebaudiana leaves through water-based or ethanol-assisted processes, yielding sweetening potency up to 300 times that of sucrose with negligible caloric contribution. Powder formulations dominate current volume due to shelf stability and ease of blending into dry mixes, though liquid extracts capture expanding share in ready-to-drink beverages where dissolution speed matters. Bakery applications remain nascent because heat degradation of certain glycosides demands encapsulation investments, concentrating margin pools in beverage and dairy segments where formulation complexity is lower.
The FDA maintains GRAS notification requirements for novel steviol glycosides, while the USDA National Organic Program governs cultivation and processing certification for organic claims. EFSA evaluates acceptable daily intake thresholds under EU food additive regulations, directly influencing product formulation ceilings and labeling strategies. Stakeholders must monitor evolving glycoside-specific approvals and organic equivalency agreements between major producing and consuming jurisdictions to secure uninterrupted market access.
Market Dynamics
Clean-label mandates from the EU Green Deal and FDA guidance on natural claims are compressing formulation timelines, forcing manufacturers to validate organic stevia supply chains before synthetic sweetener bans take full effect.
Growth Catalysts
- EU Green Deal sugar-reduction frameworks:Binding targets for processed food reformulation are accelerating stevia adoption in German and French beverage manufacturing.
- USDA National Organic Program certification:Retail shelf placement premiums for certified organic sweeteners are pulling food manufacturers away from conventional alternatives.
- Japan's sugar tax escalation:METI-aligned industry commitments to reduce caloric sweeteners are opening formulation windows for high-purity Reb M extracts in ready-to-drink products.
Market Restraints
- Leaf supply concentration:Cultivation clusters in Paraguay and China create geographic risk exposure for processors dependent on single-origin biomass.
- Reb M extraction cost structure:Low natural abundance in conventional leaves necessitates bioconversion or precision fermentation investments that compress margins at scale.
- Heat stability limitations:Degradation of certain glycosides above 200°C restricts unprotected stevia use in high-temperature bakery applications without encapsulation capex.
Strategic Opportunities
- India FSSAI clean-label pathway:Emerging processed food export hubs in Maharashtra and Gujarat present first-mover positioning for certified organic supply partnerships.
- Precision fermentation convergence:Biotech-enabled glycoside production is reducing cultivation acreage dependence while maintaining organic certification eligibility.
- Direct-to-manufacturer procurement platforms:Digital marketplaces are collapsing traditional ingredient distributor layers, enabling price transparency and contract flexibility.
Industry Challenges
- Glycoside-specific regulatory lag:EFSA and FDA approval timelines for novel steviol glycosides extend 18-36 months, freezing formulation pipelines.
- Organic equivalency agreement fragmentation:Non-harmonized certification standards between USDA, EU organic, and JAS create duplicate audit burdens for multi-jurisdictional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Stevia Market |
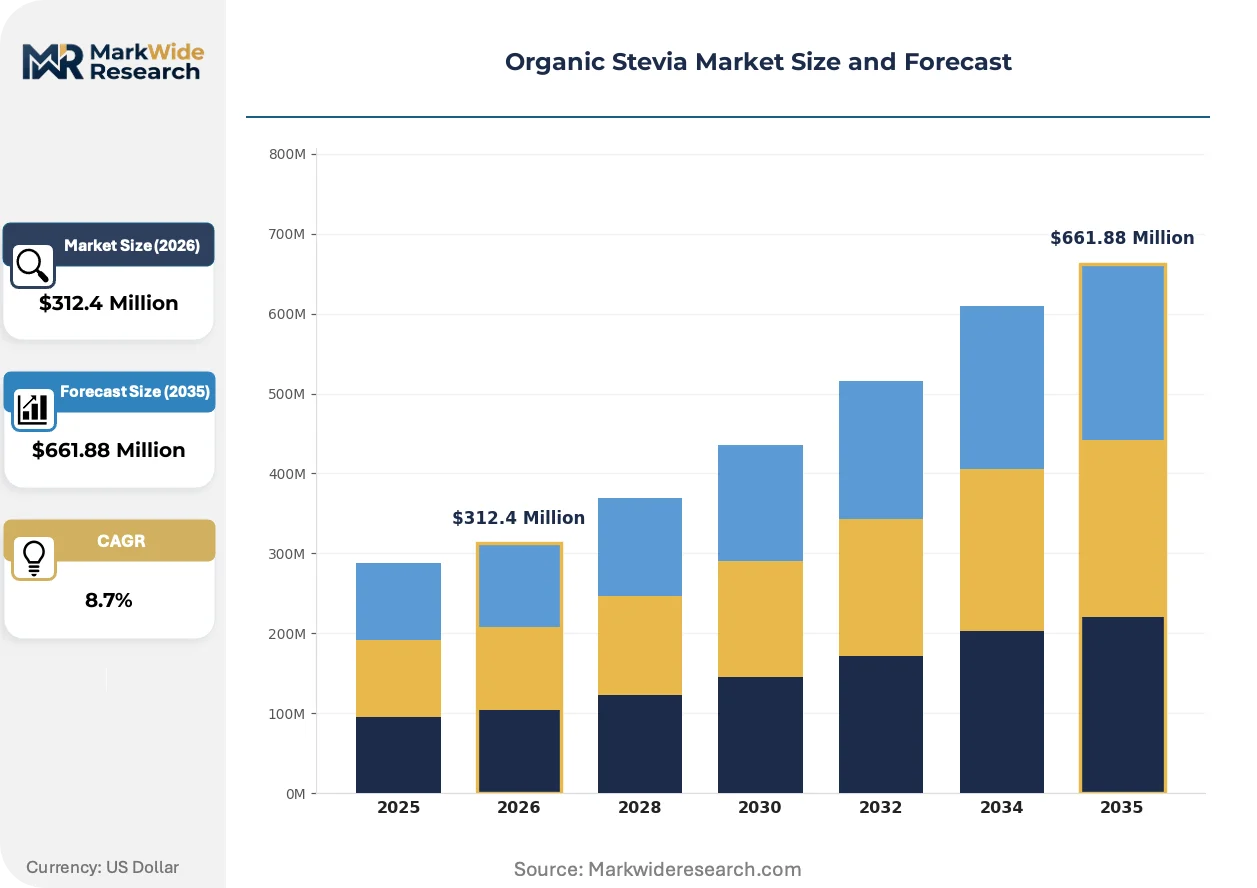
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Tablets Application: Beverages, Bakery, Dairy, Snacks Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales End User: Food Manufacturers, Beverage Companies, Retailers, Households |
| Companies Covered | Ingredion Incorporated, Cargill Incorporated, Tate & Lyle PLC, PureCircle Ltd, Archer Daniels Midland Company, GLG Life Tech Corporation, Sunwin Stevia International Inc, Morita Kagaku Kogyo Co Ltd, Pyure Brands LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Stevia Market Emerging Trajectories
Bioconversion technologies and extraction process intensification are compressing cost curves for rare glycosides, while regulatory harmonization efforts and procurement platform digitization are restructuring how sweetener supply chains validate and transact.
Enzymatic bioconversion of stevioside into Reb M is displacing leaf-sourced extraction as the dominant production pathway for premium formulations. Beverage manufacturers in the United States and Japan are adopting bioconverted glycosides at accelerating rates to meet clean-label commitments without sacrificing taste profiles. This technology is displacing traditional cultivation-heavy supply models and enabling geographic diversification of production assets.
EFSA's evolving guidance on acceptable daily intake thresholds for specific glycosides is tightening formulation ceilings across EU member states. Food manufacturers must now maintain granular glycoside-level documentation to support label claims, increasing compliance overhead. Premium beverage and dairy segments are responding by consolidating supplier relationships with vertically integrated processors capable of batch-level traceability.
Long-term offtake agreements are replacing spot market purchasing among North American and European food manufacturers seeking supply security. Large-scale beverage producers are locking multi-year contracts directly with processors, marginalizing traditional distribution intermediaries. This pattern is most pronounced in Germany and the United States, where sugar-reduction policy timelines create predictable demand visibility.
Organic Stevia Market Segmentation
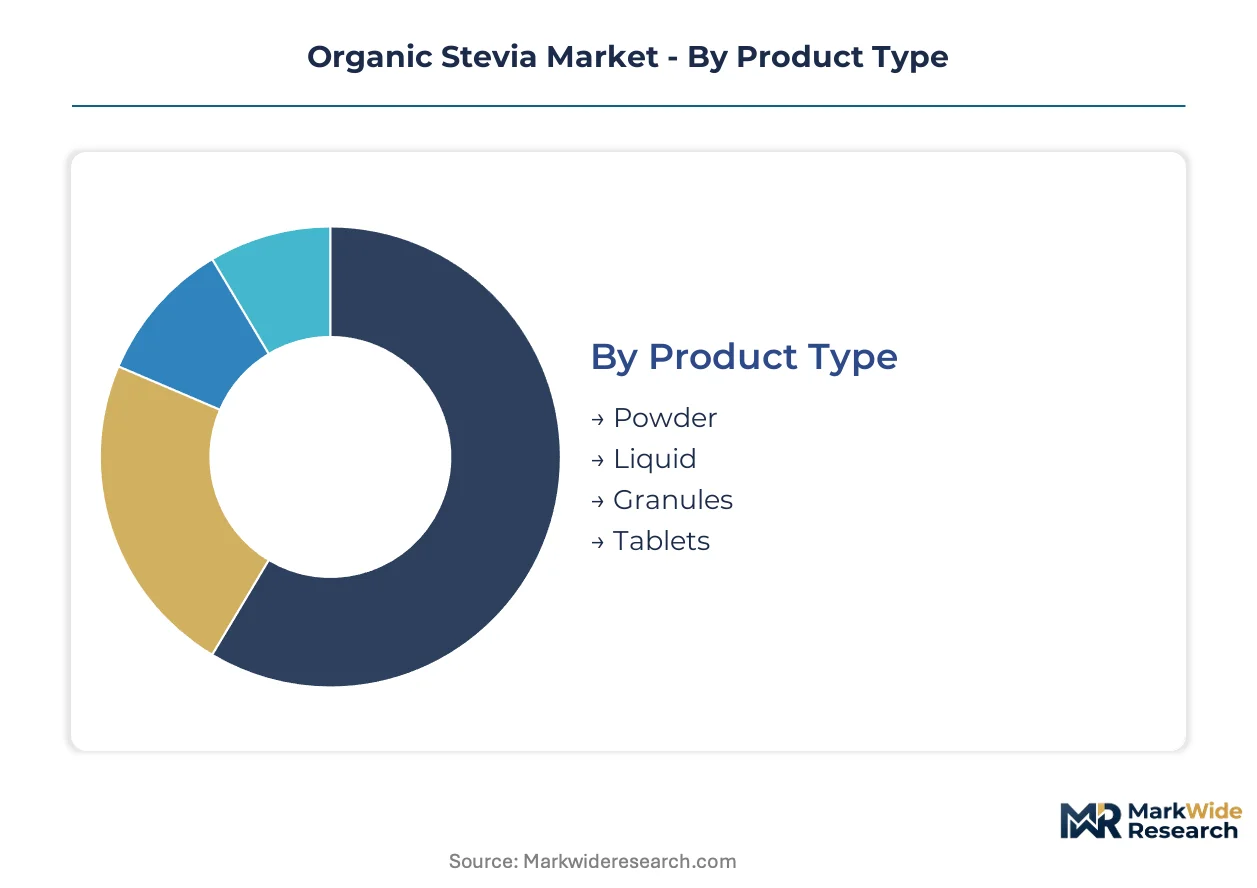
Organic stevia procurement flows through distinct channel configurations depending on formulation requirements and certification complexity. Food manufacturers dominate volume through direct sales arrangements, while retail channels serve fragmented household demand with higher per-unit premiums.
Product Type:
Powder and liquid formulations move through divergent channel mixes, with powder dominating bulk food-manufacturer procurement and liquid extracts penetrating ready-to-drink beverage supply chains.
- Powder:Spray-dried or crystalline extracts deliver shelf-stable sweetness concentration up to 300 times sucrose equivalence. Food manufacturers in the United States and Germany purchase powder through direct sales contracts to secure batch-level organic certification documentation for clean-label compliance.
- Liquid:Aqueous or ethanol-based extracts dissolve rapidly in cold-process beverages, eliminating clumping risks. Japanese beverage companies favor liquid stevia for ready-to-drink tea and coffee formulations where dissolution speed determines production line efficiency.
- Granules:Agglomerated particles improve flowability for tabletop sweetener packaging.
- Tablets:Compressed formats target convenience-oriented retail consumers in health store channels.
By volume, powder leads. By growth pace, liquid is ahead.
Application:
Margin profiles diverge sharply across applications, with beverages capturing scale economies and bakery demanding encapsulation investments that compress returns.
- Beverages:Soft drinks, flavored waters, and dairy alternatives incorporate stevia at formulation levels below sensory threshold limits. Clean-label mandates from the EU Green Deal are accelerating reformulation timelines in German and French manufacturing facilities.
- Bakery:Heat degradation of unprotected glycosides above 200°C necessitates microencapsulation capex that elevates unit costs. Premium cookie and cake manufacturers in Japan absorb these costs to maintain organic positioning in METI-aligned sugar-reduction commitments.
- Dairy:Yogurt and ice cream applications leverage stevia's stability in acidic, low-temperature processing environments.
- Snacks:Energy bars and dried fruit coatings represent emerging adoption with formulation complexity between beverages and bakery.
Beverages command the largest revenue pool. Snacks are climbing the fastest as clean-label snacking trends accelerate.
Distribution Channel:
Channel selection correlates directly with buyer scale and certification verification requirements, fragmenting stevia's route-to-market architecture.
- Direct Sales:Processor-to-manufacturer contracts eliminate distributor margins and enable long-term offtake agreements with locked pricing. North American beverage producers leverage direct procurement to secure supply visibility against sugar-reduction policy timelines.
- Supermarkets:Mass retail placement demands USDA National Organic Program certification and consumer-facing packaging compliance. German supermarket chains are expanding private-label organic sweetener assortments under EU Green Deal sugar-reduction frameworks.
- Online:E-commerce platforms aggregate fragmented household demand with subscription models for repeat purchases.
- Health Stores:Specialty retailers emphasize premium positioning and educational staff engagement for first-time organic adopters.
Direct sales capture the highest volume throughput. Online channels are gaining share fastest among household segments.
End User:
Procurement sophistication varies dramatically across end-user categories, dictating supplier relationship structures and contract terms.
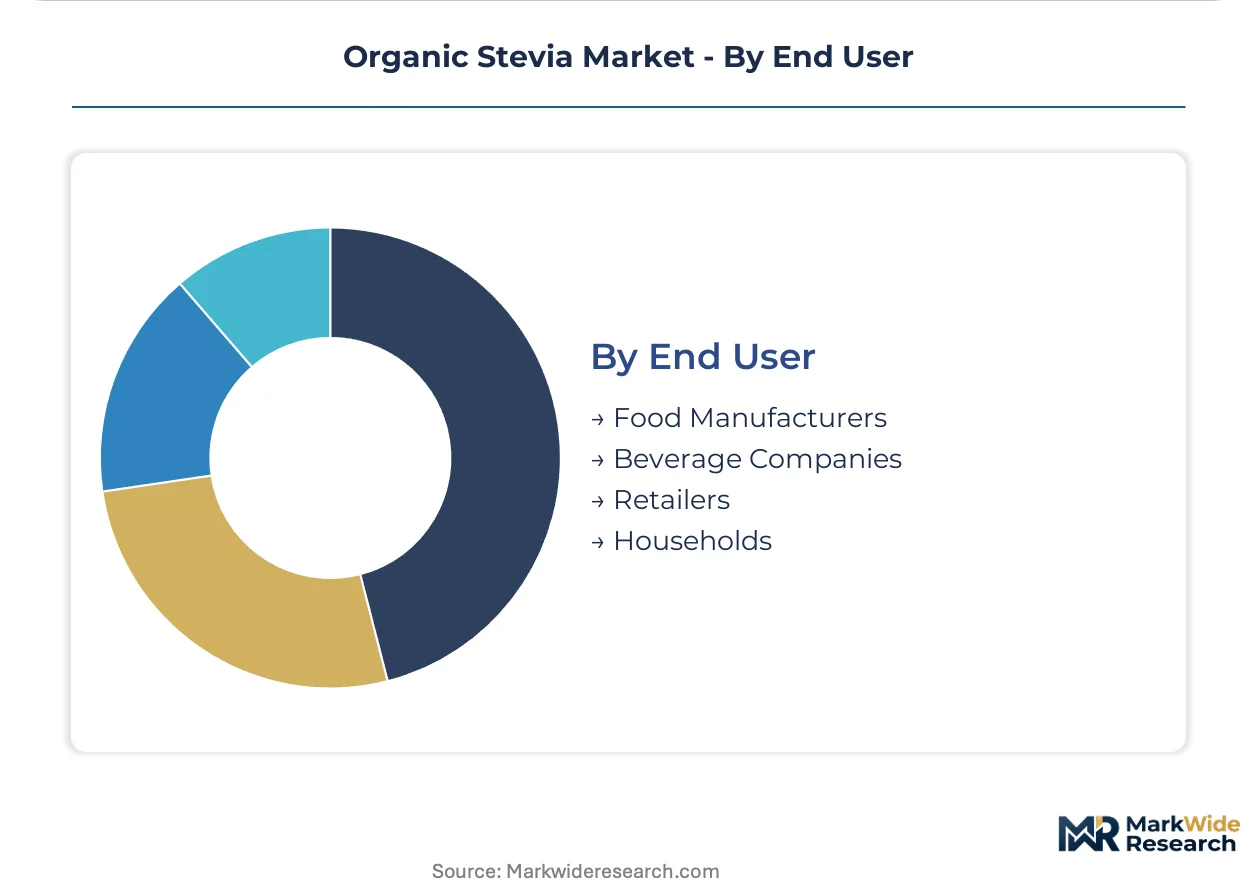
- Food Manufacturers:Baking mix, sauce, and condiment producers require glycoside-specific documentation to support EFSA acceptable daily intake compliance in EU export markets. These buyers consolidate supplier relationships with vertically integrated processors capable of batch traceability.
- Beverage Companies:Formulation teams prioritize Reb M and Reb D glycosides for clean taste profiles without bitter aftertaste. Japanese ready-to-drink manufacturers are locking multi-year contracts directly with bioconversion-enabled processors.
- Retailers:Private-label development teams negotiate specification-controlled supply agreements.
- Households:End consumers purchase through retail channels with price sensitivity moderated by organic certification premiums.
Food manufacturers and beverage companies collectively dominate procurement volume. Beverage companies are expanding their stevia sourcing fastest as sugar-tax escalations tighten formulation windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraguay exports raw stevia leaf biomass to processors in the United States, Germany, and Japan, forming the dominant trade-flow corridor for organic stevia supply chains. Chinese cultivation clusters supplement this flow with intermediate extracts. These three destination markets enforce divergent certification standards that reshape procurement patterns.
United States
Beverage manufacturers in Atlanta and Chicago drive formulation demand for Reb M glycosides. The FDA maintains GRAS notification requirements for novel steviol glycosides, extending approval timelines. California-based organic food brands consolidate supplier relationships to secure USDA National Organic Program certification for clean-label positioning.
Germany
Soft drink producers in Bavaria and North Rhine-Westphalia accelerate reformulation under binding sugar-reduction targets. The EU Green Deal frameworks mandate processed food reformulation with verifiable natural ingredients. Frankfurt-area ingredient distributors are collapsing under direct-procurement pressure from multinational beverage companies.
Japan
Ready-to-drink tea and coffee manufacturers in Tokyo and Osaka prioritize high-purity Reb M and Reb D extracts. METI-aligned industry commitments to reduce caloric sweeteners create predictable demand windows. Nagoya-based processors are locking multi-year offtake agreements with bioconversion-enabled suppliers.
China
Cultivation clusters in Fujian and Yunnan provinces supply intermediate leaf extracts to global processors. The country's national food safety regulator governs export-grade organic certification for international market access. Shanghai-based trading houses are losing margin to direct-procurement platforms linking farmers to overseas manufacturers.
India
Processed food exporters in Maharashtra and Gujarat present emerging demand for certified organic sweeteners. FSSAI clean-label pathways are aligning with EU and US import requirements. Mumbai-area food manufacturers are piloting stevia reformulation for export-oriented snack and beverage production.
Organic Stevia Market Vendor Landscape
Player mix skews toward vertically integrated agricultural processors with captive leaf supply and specialized bioconversion technology providers. The competitive terrain splits between scale-driven commodity suppliers and premium-tier glycoside specialists. Two strategic archetypes dominate: leaf-to-extract integrators controlling cultivation assets, and biotech-enabled processors leveraging precision fermentation for rare glycosides. Capacity expansion and backward integration into leaf sourcing represent the dominant competitive moves.
Within the integrator archetype, PureCircle Ltd and Cargill Incorporated exemplify contrasting scale positions. PureCircle Ltd anchors the premium-tier with vertical control from Paraguayan cultivation through refined extract production. Cargill Incorporated occupies the commodity-scale position, leveraging North American distribution infrastructure for volume throughput. GLG Life Tech Corporation represents the specialization vector, focusing on high-purity Reb M and Reb D glycosides for taste-critical formulations. These three entities collectively illustrate how competitive positioning fragments across supply chain control points rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Incorporated |
| Tate & Lyle PLC |
| PureCircle Ltd |
| Archer Daniels Midland Company |
| GLG Life Tech Corporation |
| Sunwin Stevia International Inc |
| Morita Kagaku Kogyo Co Ltd |
| Pyure Brands LLC |
| Others |
Supply Flow & Price Mechanics
USDA National Organic Program certification gates both supply qualification and price differentiation simultaneously, forcing processors to absorb audit costs that transmit downstream as tiered premiums while locking out uncertified competitors from clean-label procurement channels. Food manufacturers in the United States and Germany pay steeply for batch-level traceability documentation that supports EFSA acceptable daily intake compliance, compressing margins for suppliers unable to deliver certified organic documentation at scale.
Pricing Analysis
Leaf-extracted steviol glycosides command substantial premiums over conventional stevia extracts, while bioconverted Reb M from precision fermentation is compressing that gap as production scales. Contract-based long-term offtake agreements dominate procurement between North American beverage manufacturers and vertically integrated processors, with price differentiation driven by glycoside purity grade and organic certification tier. Cost compression in standard-grade leaf extracts is intensifying because Chinese cultivation expansion has loosened biomass availability. Retail households exhibit highest price sensitivity, while Japanese beverage companies absorb premiums for high-purity Reb M to meet METI-aligned sugar-reduction commitments.
Supply Chain Analysis
Strategic stockpiling of certified organic leaf biomass prevails among processors facing EFSA and FDA approval timelines that freeze formulation pipelines for 18-36 months. Cultivation concentrates in Paraguay and China, with intermediate extraction clusters in Fujian and Yunnan provinces feeding global processors. Supply chains draw from stevia leaf biomass, ethanol and water extraction solvents, and encapsulation materials for heat-sensitive applications. Single-source vulnerability runs through Paraguayan leaf supply exposed to climate volatility and geopolitical friction. Distribution runs through direct processor-to-manufacturer contracts that are marginalizing traditional ingredient distributors in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American and European beverage manufacturers locking multi-year offtake agreements, fragmenting supplier pricing leverage and forcing processors toward consolidation or specialization.
For Market Incumbents: Shield margin position by deepening backward integration into Paraguayan cultivation assets to secure captive leaf supply against biomass price volatility, and accelerate bioconversion capacity buildout to displace leaf-dependent extraction for rare glycosides where precision fermentation cost curves are steepening. Regulatory lag from EFSA and FDA approval timelines for novel steviol glycosides remains the critical threat freezing competitor formulation pipelines. For New Entrants and Emerging Players: Differentiate on bioconversion-enabled glycoside production that sidesteps cultivation acreage constraints and qualifies for organic certification under evolving USDA guidance. White-space targets include India's FSSAI-aligned export processing hubs in Maharashtra and Gujarat, and microencapsulation services for bakery applications where heat stability limitations have suppressed adoption. A direct-to-manufacturer digital procurement platform offers the cleanest go-to-market angle, collapsing distributor layers that incumbent processors still maintain. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food-ingredient conglomerates where stevia assets sit underoptimized within broader sweetener portfolios. Long-term viability hinges on bioconversion technology ownership and organic equivalency agreement navigation across USDA, EU organic, and JAS regimes. Watch for EFSA acceptable daily intake threshold revisions as the inflection signal that reshapes formulation ceilings and supplier consolidation imperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Captive Paraguayan leaf supply secures biomass access against climate and trade disruptions. |
| Bioconversion Capacity Expansion | Precision fermentation for Reb M reduces dependence on geographic cultivation clusters. |
| Organic Certification Investment | USDA National Organic Program compliance unlocks clean-label premium positioning in US retail. |
| Direct-to-Manufacturer Procurement Platform | Digital marketplaces collapse distributor margins and enable price transparency for buyers. |
| Microencapsulation R&D Partnership | Heat-stable glycoside formats open bakery applications previously restricted by degradation limits. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ingredient procurement directors, beverage formulation leads, organic certification auditors, and stevia cultivation operators; and secondary validation through FDA GRAS notifications, USDA National Organic Program certification databases, EFSA food additive evaluations, and customs trade flow records. Bottom-up triangulation against top-down market sizing cross-validated volume estimates across powder, liquid, and granule product categories.
Across the analysis window, the forecasting framework modeled organic stevia demand through segmentation dimensions spanning product formulation type, application category, distribution channel configuration, and end-user procurement sophistication. CAGRs were derived from regression analysis against sugar-reduction policy implementation timelines and clean-label adoption curves. Industry-specific inputs included glycoside-specific approval status across regulatory jurisdictions and bioconversion technology cost trajectories.
Material uncertainties — EFSA acceptable daily intake threshold revisions, organic equivalency agreement renegotiations between major jurisdictions, and precision fermentation scale-up execution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization progress and bioconversion cost compression rates. Revision becomes warranted when bioconverted glycoside production costs cross below leaf-extraction parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Ice Cream Market