
 Organic Fast Food Market | 2026-2036
Organic Fast Food Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Fast Food Market Analysis
Quick-service restaurant distribution is fragmenting as legacy chains lose foot traffic to digitally native organic concepts. The Organic Coup leverages its poultry specialization to anchor West Coast market presence. Nics Organic Fast Food competes through tight supply chain control over certified organic produce. Whole Foods Market sustains prepared-food counter dominance by integrating grocery traffic with grab-and-go meal velocity.
Organic fast food comprises quick-service meals prepared with ingredients certified under national organic standards prohibiting synthetic pesticides, GMOs, and artificial preservatives, with protein sourcing and vegetable washing protocols subject to third-party audit. The segment serves time-constrained consumers seeking verified clean-label nutrition without full-service restaurant time commitments. Burgers and wraps lead menu type revenue due to operational simplicity and protein-centric consumer preference, while vegan ingredient formulations capture the fastest expansion as plant-forward diets shift mainstream. Drive-thru and delivery service models now command margin priority after pandemic-era infrastructure investments reshaped capital allocation across the sector.
The USDA National Organic Program governs certification thresholds for menu claims, while the FDA Food Safety Modernization Act imposes preventive controls on supply chain hazard analysis. State-level California Organic Products Act layering adds compliance cost density for operators serving that market. Stakeholders must monitor whether proposed revisions to organic livestock and handling standards tighten further, as rulemaking momentum signals potential sourcing disruption for multi-state chains.
Market Dynamics
USDA organic certification tightening is compressing supplier eligibility while California's coastal metro clusters concentrate premium quick-service density, forcing chains to rebuild procurement networks around third-party audited protein and produce sourcing.
Growth Catalysts
- USDA National Organic Program:Certification standard revisions are elevating ingredient traceability requirements, filtering out conventional suppliers and creating captive demand for verified organic channels.
- Urban millennial density:North American metropolitan areas concentrate time-constrained consumers seeking clean-label nutrition without full-service restaurant time commitments.
- Plant-forward diet shift:Vegan ingredient formulations capture expansion momentum as protein-centric consumer preference broadens to include plant-based alternatives.
Market Restraints
- Certified organic input cost volatility:Third-party audited vegetable washing protocols and protein sourcing carry persistent premium over conventional supply, compressing unit economics at volume scale.
- California supply concentration:The state's coastal cities anchor premium quick-service density, creating geographic dependency for operators seeking organic ingredient aggregation.
- California Organic Products Act layering:State-level compliance requirements add cost density for multi-state chains serving that market, creating regulatory friction against expansion.
Strategic Opportunities
- Drive-thru infrastructure redeployment:Pandemic-era capital allocation into drive-thru and delivery service models now commands margin priority, enabling format innovation.
- Grab-and-go grocery integration:Prepared-food counter velocity fuses with grocery traffic patterns, creating hybrid channel white space for meal solutions.
- Proposed organic livestock rulemaking:USDA handling standard revisions signal potential sourcing disruption that first-mover chains can exploit through early compliance investment.
Industry Challenges
- Third-party audit talent scarcity:Certified organic supply chain verification requires specialized auditors, creating bottleneck capacity for rapid network scaling.
- Legacy POS integration friction:Digitally native organic concepts face system compatibility challenges when acquiring or partnering with conventional infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Fast Food Market |
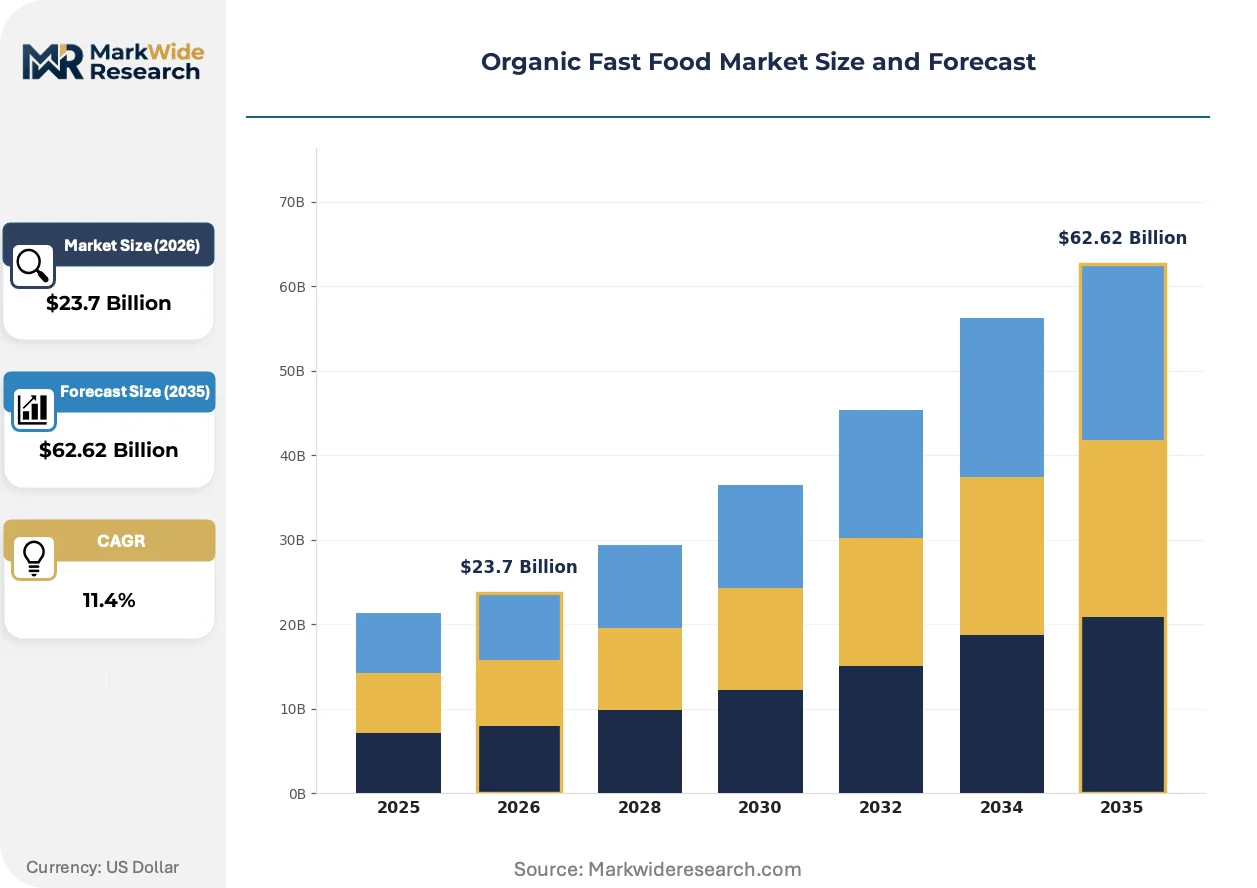
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Menu Type: Burgers, Salads, Wraps, Smoothies Ingredient Type: Vegetarian, Vegan, Gluten-Free, Locally Sourced Service Model: Drive-Thru, Dine-In, Delivery, Catering Consumer Demographic: Health-Conscious, Millennials, Families, Professionals |
| Companies Covered | Whole Foods Market, Nics Organic Fast Food, The Organic Coup, Hormel Foods Corporation, Hain Celestial Group, Kroger Company, Clif Bar & Company, Organic Valley, Dole Food Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Fast Food Market Emerging Trajectories
Operational technology deployment and certification-driven procurement are compressing the gap between premium positioning and quick-service velocity, reshaping how organic chains build trust at scale.
Blockchain-enabled supply chain tracking is digitizing ingredient provenance verification from farm to point-of-sale. West Coast quick-service operators are deploying this technology fastest, responding to California consumer expectation for real-time transparency. The structural consequence is digitizing audit cost reduction while tightening liability exposure for contamination events.
The FDA Food Safety Modernization Act preventive controls mandate hazard analysis across organic supply chains. This industrial consequence forces operators to document critical control points for synthetic pesticide exclusion and GMO prevention. Multi-state chains serving California face the tightest compliance density, responding with dedicated food safety officer expansion.
Subscription-based meal program adoption is rotating demand toward predictable recurring revenue models. Urban millennials in metropolitan clusters are displacing impulse drive-thru visits with pre-ordered weekly organic meal plans. This shift is most visible in California coastal cities where premium quick-service density supports logistics optimization for scheduled delivery windows.
Organic Fast Food Market Segmentation
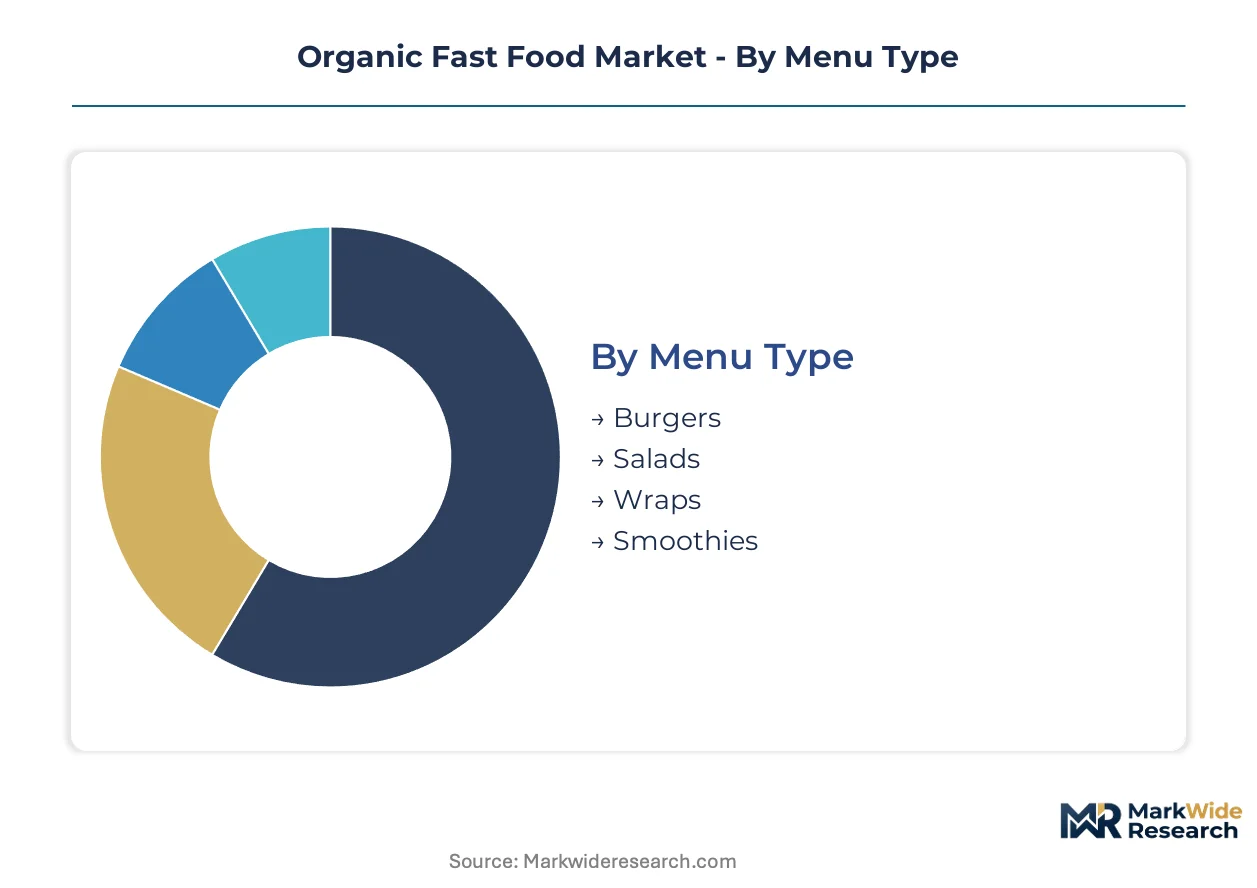
Organic fast food segmentation reveals how certification requirements and service velocity trade-offs reshape competitive positioning across menu formats and ingredient sourcing tiers. Chains must align operational infrastructure with specific consumer occasion patterns rather than pursuing undifferentiated scale.
Menu Type:
After-sales intensity varies sharply across menu categories, with complex protein preparation demanding ongoing supplier audit relationships and simpler formats enabling faster certification turnover.
- Burgers:Ground beef and poultry patty operations require USDA organic livestock verification and third-party handling audits at slaughter and processing stages. Demand concentrates in California coastal metros where premium quick-service density supports dedicated organic protein aggregation infrastructure.
- Wraps:Tortilla-based formats integrate vegetable washing protocols with protein sourcing in single assembly flow, compressing kitchen footprint requirements. Urban millennial clusters in North American metropolitan areas drive adoption for handheld portability without dine-in time commitment.
- Salads:Cold-chain dependency and perishable leaf-greens sourcing elevate spoilage risk and shrinkage costs.
- Smoothies:Frozen fruit and plant-milk blending operations require less protein certification overhead but demand consistent produce quality grading.
By volume, Burgers leads. By growth pace, Wraps is ahead.
Ingredient Type:
Cost tier stratification separates premium-positioned chains from value-oriented competitors based on certification depth and sourcing radius constraints.
- Vegan:Plant-exclusive formulations eliminate livestock audit burdens while introducing novel protein isolation and allergen-cross-contamination controls. California coastal cities anchor demand as plant-forward diets shift mainstream among urban density clusters.
- Vegetarian:Dairy and egg inclusion maintains some animal-protein supply relationships while reducing full livestock certification costs. North American metropolitan areas concentrate time-constrained consumers seeking verified clean-label nutrition without full vegan commitment.
- Gluten-Free:Dedicated prep surfaces and ingredient segregation add operational complexity and kitchen real estate requirements.
- Locally Sourced:Radius-limited procurement tightens supply security during distribution disruption but compresses menu consistency across locations.
By volume, Vegetarian leads. By growth pace, Vegan is climbing the fastest.
Service Model:
Volume throughput potential and margin structure diverge based on real estate format and labor deployment intensity.
- Drive-Thru:Pandemic-era capital allocation into lane infrastructure now commands margin priority through speed-of-service optimization. California's coastal metro clusters concentrate premium quick-service density where drive-thru organic concepts capture commuter traffic patterns.
- Delivery:Third-party platform integration and subscription-based meal program adoption rotate demand toward predictable recurring revenue models. Urban millennial density in metropolitan areas displaces impulse visits with pre-ordered weekly organic meal plans.
- Dine-In:Seated service elevates experience positioning but compresses table turns and hourly revenue per square foot.
- Catering:Bulk-order advance scheduling enables procurement planning and waste reduction but concentrates revenue volatility in corporate event calendars.
By volume, Drive-Thru leads. By expansion trajectory, Delivery is gaining share fastest.
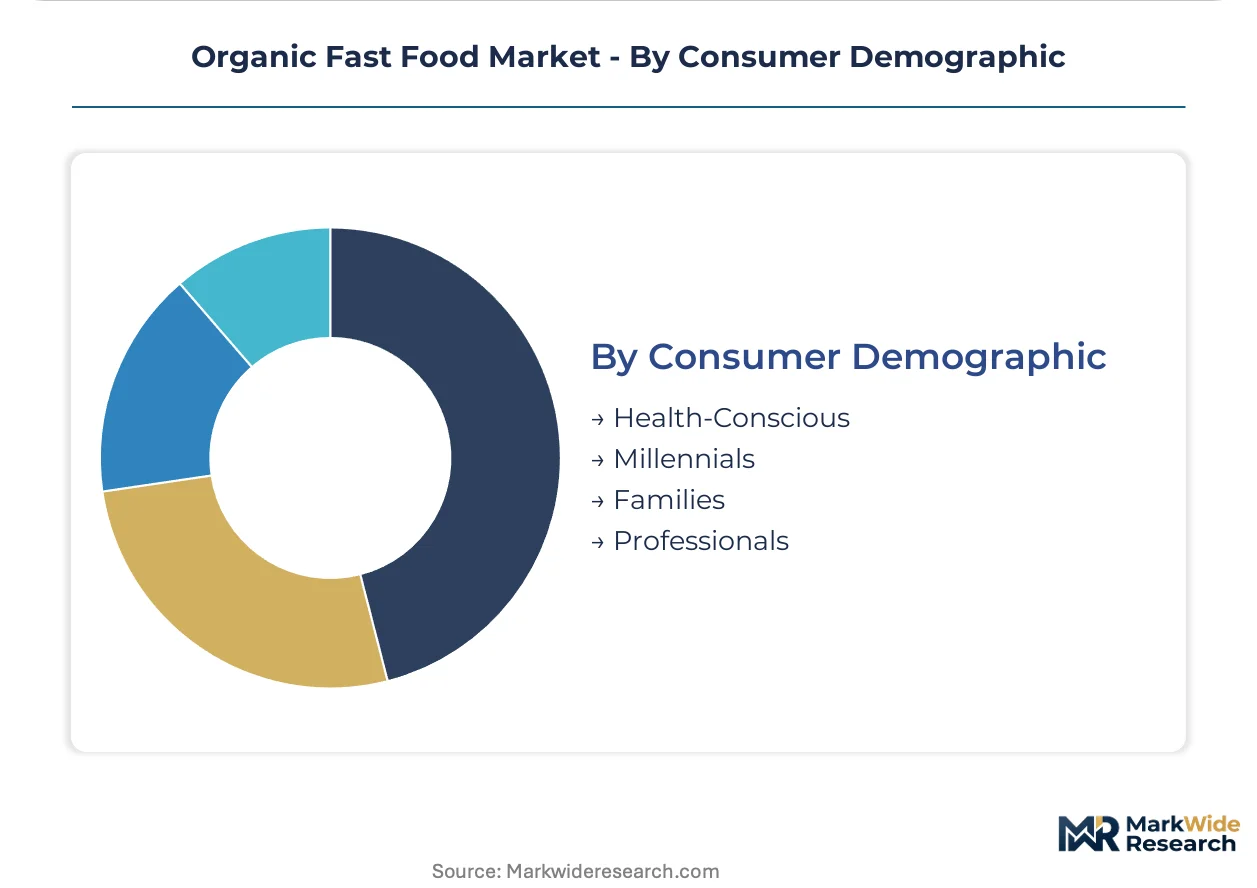
Consumer Demographic:
Customer type concentration determines marketing spend allocation and menu innovation pipeline prioritization.
- Health-Conscious:Certification-verified clean-label seekers accept price premiums for third-party audited ingredient provenance. California coastal cities anchor demand where premium quick-service density outpaces national averages.
- Millennials:Time-constrained urban professionals seeking nutrition without full-service restaurant time commitments concentrate in North American metropolitan areas.
- Families:Multi-portion ordering and kid-friendly menu extensions drive average transaction value but complicate ingredient standardization.
- Professionals:Lunch-hour occasion concentration creates peak demand compression requiring throughput-optimized kitchen design.
By volume, Health-Conscious leads. By growth pace, Millennials is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American organic ingredient import velocity, while Hamburg's container terminals underwrite European distribution networks for certified produce.
United States
Urban millennial density in California's coastal metros drives premium quick-service adoption, with Los Angeles and San Francisco anchoring organic fast-food outlet concentration. The USDA National Organic Program governs certification thresholds for interstate menu claims, tightening livestock and handling standards through ongoing rulemaking. Texas metro corridors including Austin and Dallas-Fort Worth are expanding drive-thru infrastructure for organic concepts targeting commuter traffic patterns.
Germany
Berlin and Hamburg concentrate health-conscious consumer demand for verified clean-label nutrition, with urban professionals seeking time-efficient organic meal solutions. The EU Organic Regulation (2018/848) harmonizes certification requirements across member states while maintaining strict GMO prohibition and synthetic pesticide exclusion. Bavaria's agricultural processing clusters around Munich supply certified organic protein and produce to quick-service operators serving southern German metropolitan areas.
United Kingdom
London's density of time-constrained professionals supports grab-and-go organic meal velocity, with prepared-food counters integrating grocery traffic patterns. The Food Standards Agency enforces organic labeling compliance alongside DEFRA's UK Organic Regulation implementing EU-equivalent standards post-Brexit. Manchester and Birmingham are emerging as secondary hubs where digitally native organic concepts test subscription-based meal program adoption.
Canada
Toronto and Vancouver concentrate health-conscious demographics seeking third-party audited ingredient provenance, with urban millennials displacing conventional quick-service visits. The Canadian Food Inspection Agency administers organic certification through the Canada Organic Regime, maintaining equivalency arrangements with USDA and EU standards. Montreal's food processing infrastructure supports regional organic protein aggregation for Quebec and Ontario quick-service networks.
Australia
Sydney and Melbourne anchor demand for premium quick-service organic options, with coastal metropolitan clusters supporting drive-thru and delivery service model expansion. The Department of Agriculture, Water and the Environment oversees organic certification through the National Standard for Organic and Bio-Dynamic Produce. Brisbane's emerging urban corridors are attracting organic fast-food operators seeking underpenetrated metropolitan density outside the southeastern capital concentration.
Organic Fast Food Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient certification and protein sourcing. The vendor base stratifies across three tiers: grocery-anchored prepared-food platforms, digitally native quick-service chains, and upstream organic ingredient suppliers. Strategic archetypes include certification-heavy poultry specialists, supply-chain-controlled produce operators, and grocery-traffic-integrated meal counters. Dominant competitive moves encompass pandemic-era drive-thru infrastructure redeployment and subscription-based recurring revenue model adoption.
Within the grocery-anchored platform tier, Whole Foods Market exemplifies prepared-food counter dominance through grocery traffic integration. Among digitally native quick-service specialists, The Organic Coup and Nics Organic Fast Food occupy positions representing certification-driven operational models. These three companies anchor competitive positioning archetypes without constituting an exhaustive market map.
| Leading Market Players |
|---|
| Whole Foods Market |
| Nics Organic Fast Food |
| The Organic Coup |
| Hormel Foods Corporation |
| Hain Celestial Group |
| Kroger Company |
| Clif Bar & Company |
| Organic Valley |
| Dole Food Company |
| Others |
Supply Flow & Price Mechanics
Undercapacity in California-certified organic protein processing is elevating spot-market premiums for third-party audited suppliers while compressing margin elasticity for multi-state chains seeking volume scale. This utilization squeeze simultaneously tightens procurement timelines and hardens price floors across premium quick-service tiers.
Pricing Analysis
Volume-discount tiering structures separate national multi-unit operators from regional specialists and single-location independents. Price differentiation rests on USDA organic certification depth and California Organic Products Act compliance layering, with coastal metro density commanding delivery-cost premiums. Cost compression in the standard tier is intensifying because legacy chains are cross-subsidizing organic menu trials through conventional revenue pools. Independent operators show highest price sensitivity due to limited procurement aggregation, while grocery-anchored platforms exhibit lowest sensitivity through traffic-volume leverage.
Supply Chain Analysis
Export-control regime friction on agricultural biotechnology inputs is constraining GMO-prevention verification protocols for imported organic feedstocks. Geographic supply concentration centers on California, Texas, and Florida for domestic organic produce aggregation, with protein sourcing drawing from Midwest livestock processing clusters. Raw material dependencies include third-party certified organic grains, antibiotic-free poultry, and synthetic-pesticide-excluded vegetables. Single-source vulnerability runs through California coastal distribution hubs exposed to climate disruption. Distribution feeds from farm-direct procurement networks into regional commissary kitchens serving quick-service outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through post-pandemic format normalization as drive-thru infrastructure investments mature and subscription meal adoption resets demand patterns toward recurring revenue predictability.
For Market Incumbents: Harden supplier relationship exclusivity through early compliance investment in proposed USDA organic livestock handling revisions. Anchor procurement contracts with third-party audited California protein processors before rulemaking tightens eligibility. Defensive consolidation through backward integration into certified organic vegetable washing facilities mitigates audit-talent scarcity. For New Entrants and Emerging Players: Texas metro corridors outside Austin and Dallas-Fort Worth present geographic underpenetration with commuter traffic density supporting drive-thru format viability. Secondary Canadian markets including Calgary and Ottawa offer regulatory equivalency with lower competitive saturation. Subscription-based meal program adoption provides the most penetrable go-to-market angle through predictable logistics optimization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digitally native chains with subscription meal infrastructure already deployed. Long-term viability over the coming decade favors operators with captive supply relationships and multi-state certification compliance already embedded. Acquisition target archetypes include regional specialists with USDA organic poultry specialization and underutilized drive-thru real estate. The signal to watch is California coastal rent compression indicating saturation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Drive-Thru Infrastructure Expansion | Captures commuter traffic patterns in Texas and Florida metro corridors with lower coastal rent burdens. |
| Subscription Meal Program Launch | Converts impulse drive-thru demand into predictable recurring revenue with optimized delivery window logistics. |
| Backward Integration into Protein Sourcing | Secures third-party audited supply against proposed USDA handling standard revisions tightening eligibility. |
| Blockchain Supply Chain Tracking Deployment | Digitizes farm-to-point-of-sale provenance verification while reducing audit cost exposure for contamination events. |
| Grab-and-Go Grocery Counter Partnership | Fuses prepared-food velocity with existing grocery traffic patterns in Whole Foods Market and Kroger locations. |
Methodological Framework
A spread of perspectives from quick-service operations directors, USDA certification compliance officers, organic supply chain procurement managers, and third-party audit firm partners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA Food Safety Modernization Act documentation, USDA National Organic Program rulemaking dockets, California Department of Food and Agriculture enforcement records, and Canada Organic Regime equivalency filings. Bottom-up outlet density modeling and top-down consumer expenditure triangulation anchored volume estimates.
Demand-supply-balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling spanning menu type, ingredient certification tier, service model format, and metropolitan density cluster. CAGRs were derived from trajectory fitting against historical premium quick-service adoption curves and organic certification growth patterns. Industry-specific forecast inputs included USDA organic livestock handling standard revision timelines and California coastal commercial real estate absorption rates.
Macroeconomic conditions sit as an overlay; deviation in disposable income growth, agricultural input cost volatility, or commercial construction lending availability would shift the trajectory. Forecasts reflect documented assumptions about certification standard stability and consumer willingness-to-pay premiums for verified clean-label nutrition. Material shifts in USDA rulemaking momentum or California regulatory layering would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market