
 Organic Superfood Market | 2026-2036
Organic Superfood Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Superfood Market Insights
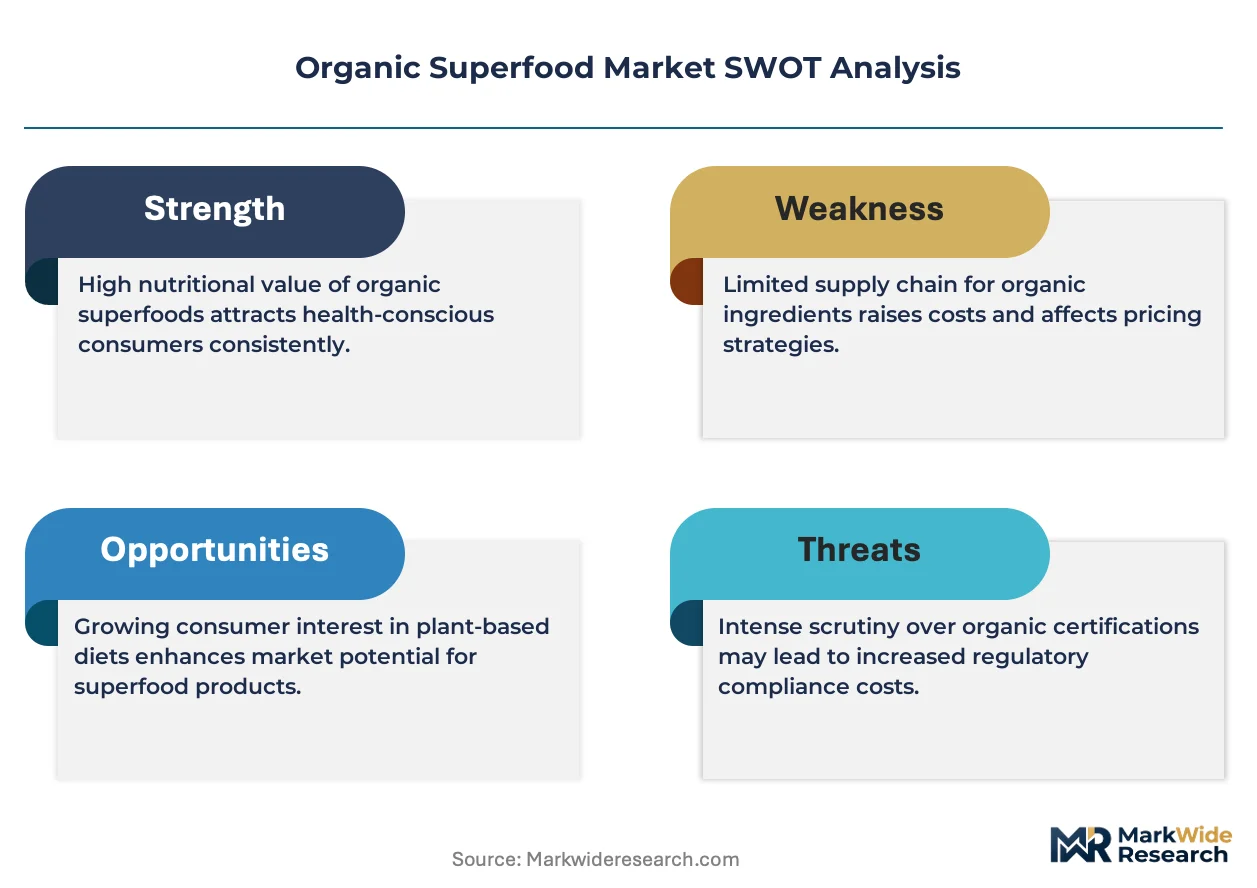
The EU Green Deal is consolidating demand for certified organic superfood supply chains across European retail. Nutiva leverages its long-standing direct sourcing relationships with South American cooperatives to secure organic cacao and hemp seed volumes. The Hain Celestial Group sustains shelf presence through broad portfolio breadth spanning powders, beverages, and snack bars. Nature's Path Organic Foods anchors its position in North American natural channels with zero-trans-fat and non-GMO verified product lines.
Organic superfood denotes plant-derived ingredients cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, typically processed into powders, bars, capsules, or ready-to-drink formats for nutritional supplementation. Products must carry third-party organic certification such as USDA Organic or EU Organic, with cold-press or low-temperature dehydration methods preserving heat-sensitive phytonutrients and enzyme activity. Powder formats dominate current revenue contribution due to versatility in smoothies and meal replacements, while beverage applications capture the fastest expansion as ready-to-drink functional shots penetrate convenience retail. Ingredient sourcing from seeds and grains generates premium margin pools, particularly chia, quinoa, and hemp varieties where supply scarcity supports price premiums over fruit-derived alternatives.
USDA Organic certification governs U.S. market access through strict soil management and prohibited substance lists, while EFSA and EU Organic Regulation enforce comparable standards across member states, creating dual compliance burdens for multinational suppliers. India's FSSAI and BIS frameworks are tightening import testing for heavy metals and microbial contamination in organic superfood shipments, adding documentation requirements for exporters. Stakeholders must monitor evolving residue limits and certification reciprocity agreements to anticipate supply disruptions and redirect procurement before regulatory friction hardens.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is tightening residue limits and traceability mandates, forcing suppliers to restructure procurement networks and absorb compliance costs that reshape competitive positioning across certified organic supply chains.
Growth Catalysts
- EU Organic Regulation enforcement:Retailers in Germany now stock organic superfood lines as standard assortment, creating pull-through demand for certified powders and snack bars across discounter and drugstore channels.
- Functional food applications:Health-conscious consumers are expanding procurement of certified organic powders into meal replacement and smoothie formats, diversifying revenue streams beyond traditional supplement channels.
- Cold-press dehydration methods:Low-temperature processing technology preserves heat-sensitive phytonutrients and enzyme activity, enabling premium positioning for organic superfood products against conventional alternatives.
Market Restraints
- Input cost volatility:Supply scarcity for chia, quinoa, and hemp seed varieties supports price premiums that compress margins when commodity cycles tighten.
- Regulatory friction:India's FSSAI and BIS frameworks are tightening import testing for heavy metals and microbial contamination, adding documentation burdens that delay shipments.
- Substitution threat:Conventional fruit-derived superfood alternatives compete on price in price-sensitive consumer segments where organic certification carries limited willingness-to-pay.
Strategic Opportunities
- Underpenetrated convenience retail:Ready-to-drink functional shots are penetrating convenience retail channels in urban Germany, creating new points of distribution for beverage-format organic superfoods.
- Regulatory tailwind:The EU Green Deal's sustainability mandates are consolidating demand for traceable supply chains, rewarding early movers with certified organic sourcing relationships.
- Technology convergence:Blockchain traceability systems combined with cold-chain logistics are enabling real-time verification of organic claims from South American cooperatives to European retail.
Industry Challenges
- Certification timeline compression:Dual compliance burdens for USDA Organic and EU Organic Regulation require parallel documentation streams that strain quality assurance teams.
- Supply chain reconfiguration friction:Redirecting procurement before regulatory friction hardens demands predictive monitoring of evolving residue limits and certification reciprocity agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Superfood Market |
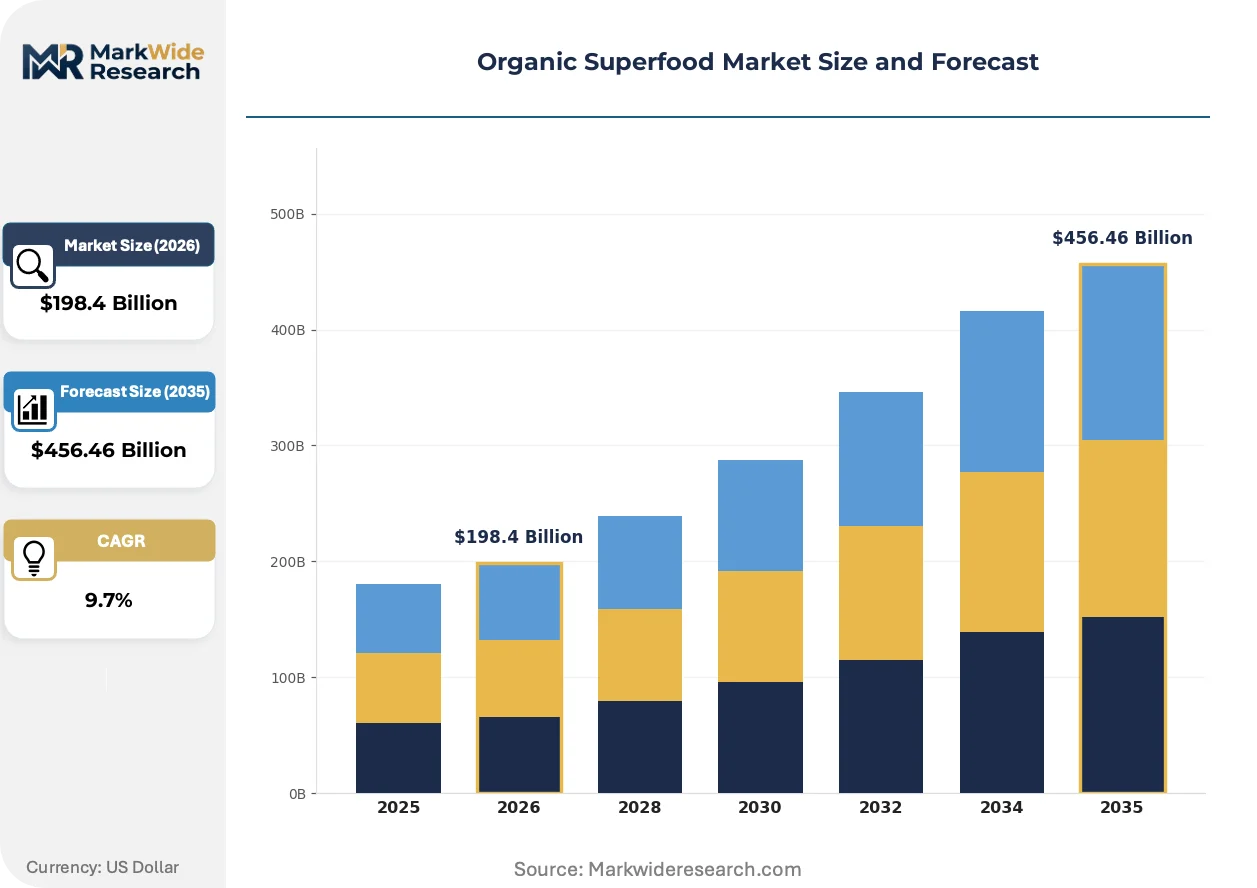
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $456.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Snack Bars, Capsules, Beverages Ingredient Source: Fruits, Vegetables, Grains, Seeds Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales Customer Type: Health-Conscious Consumers, Athletes, Vegans, Fitness Enthusiasts |
| Companies Covered | Sunfood Superfoods, Nutiva, Nature’s Superfoods LLP, Suncore Foods, The Hain Celestial Group, General Mills, Danone, Organic Valley, Nature's Path Organic Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Superfood Market Trends and Innovations
Processing technology and regulatory transparency requirements are actively reshaping how organic superfoods move from cultivation to consumption, compressing traditional supply chain structures while opening new channel access.
Blockchain-enabled traceability platforms are decentralizing verification of organic claims from centralized certifiers to distributed ledger systems. Mid-sized cooperatives in South America are adopting these tools to bypass traditional audit bottlenecks. This technology is decentralizing power over certification timelines from European regulators to origin-country producers, compressing compliance cycles.
EFSA residue limit revisions under the EU Green Deal are mandating stricter testing protocols for imported organic superfoods. Food manufacturers must now maintain parallel documentation for EU Organic Regulation and national frameworks. Powder formats face the tightest scrutiny given their concentration and direct consumption patterns, driving investment in origin-country laboratory capacity.
Consumer verification behavior is shifting from label trust to app-based scanning of batch-specific organic credentials. German discounters are responding by integrating QR-code traceability into private-label superfood lines. This pattern is most visible in Berlin and Hamburg metropolitan areas where smartphone penetration intersects with high organic purchasing frequency.
Organic Superfood Market Segmentation
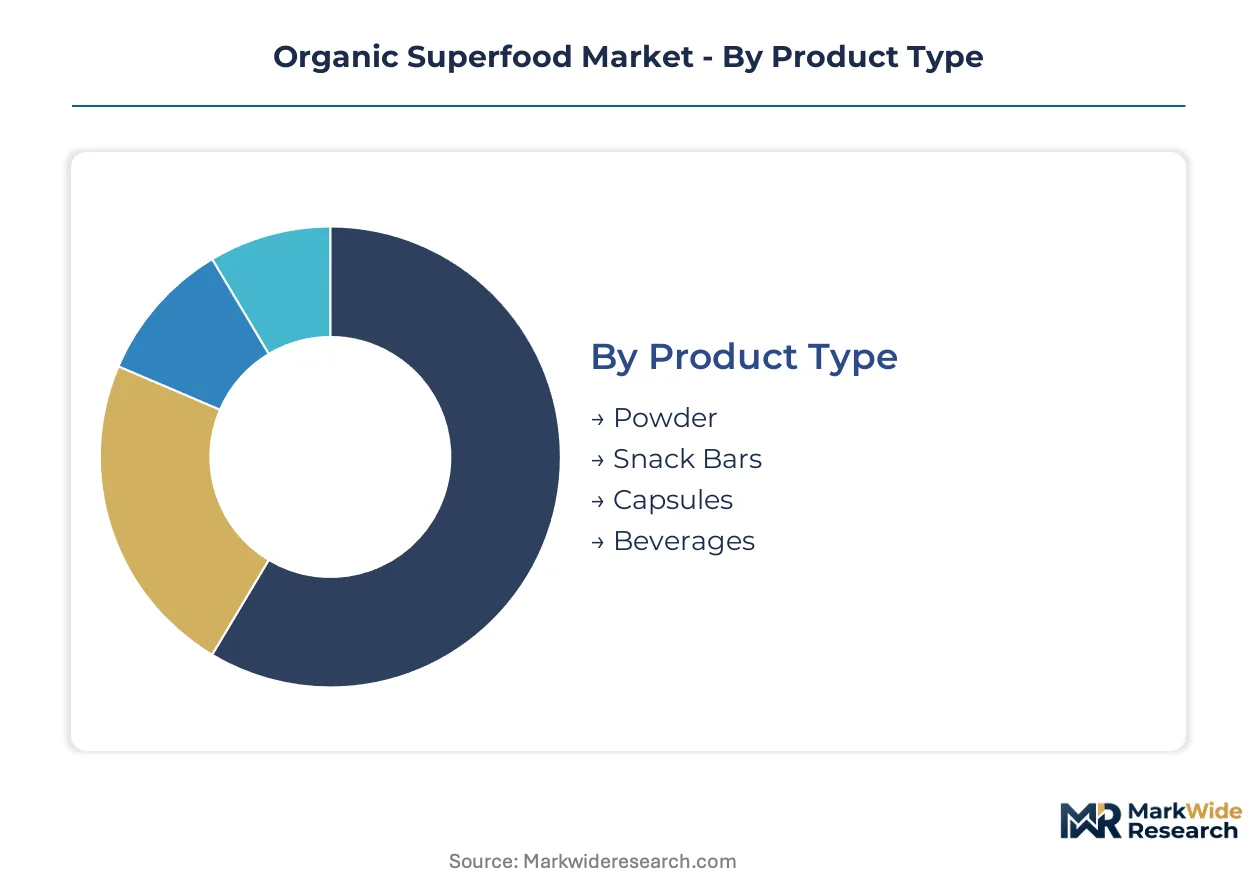
Organic superfood manufacturers configure product portfolios around four distinct segmentation axes. Each axis reveals divergent margin structures, channel access requirements, and compliance burdens that reshape supplier investment priorities.
Product Type:
Processing intensity and shelf-stability requirements differentiate formats across the value chain.
- Powder:Cold-press or low-temperature dehydration preserves heat-sensitive phytonutrients and enzyme activity. German discounters and drugstores stock certified organic powders as standard assortment, pulling volume through functional food applications in smoothies and meal replacements.
- Beverages:Ready-to-drink functional shots penetrate convenience retail in urban Germany, creating new distribution points where cold-chain logistics enable real-time verification of organic claims. This format captures the steepest expansion trajectory as on-the-go consumption displaces traditional supplement occasions.
- Snack Bars:Compressed ingredient matrices with binding agents that must maintain non-GMO verification through supply chain.
- Capsules:Encapsulation technology for targeted dosing in pharmaceutical-adjacent distribution channels.
Powder leads on scale; beverages lead on momentum.
Ingredient Source:
Input scarcity and cultivation geography determine premium capture potential across origin categories.
- Seeds:Chia, quinoa, and hemp varieties command price premiums over fruit-derived alternatives where supply scarcity concentrates procurement leverage with South American cooperatives. EFSA residue limit revisions under the EU Green Deal mandate stricter testing protocols for imported seed volumes.
- Grains:Ancient grain varieties with established organic certification infrastructure in North American and European cultivation zones.
- Fruits:Berry and tropical concentrates facing substitution pressure from conventional alternatives in price-sensitive consumer segments.
- Vegetables:Leafy green powders with shorter harvest windows and higher perishability in raw form.
Seeds dominate margin pools; grains anchor volume stability.
Distribution Channel:
Channel selection dictates certification documentation depth and traceability system requirements.
- Online Retailers:Direct-to-consumer platforms enable batch-specific QR-code traceability that German metropolitan consumers verify through app-based scanning. Blockchain-enabled platforms decentralize organic claim verification from centralized certifiers to distributed ledger systems.
- Supermarkets:Mass retail placement demands parallel USDA Organic and EU Organic Regulation documentation that strains quality assurance teams.
- Specialty Stores:Curated assortment with educated staff supporting premium positioning for cold-processed formats.
- Direct Sales:Subscription models with recurring revenue and lower customer acquisition cost in established organic purchasing households.
Online retailers expand fastest; supermarkets concentrate absolute revenue.
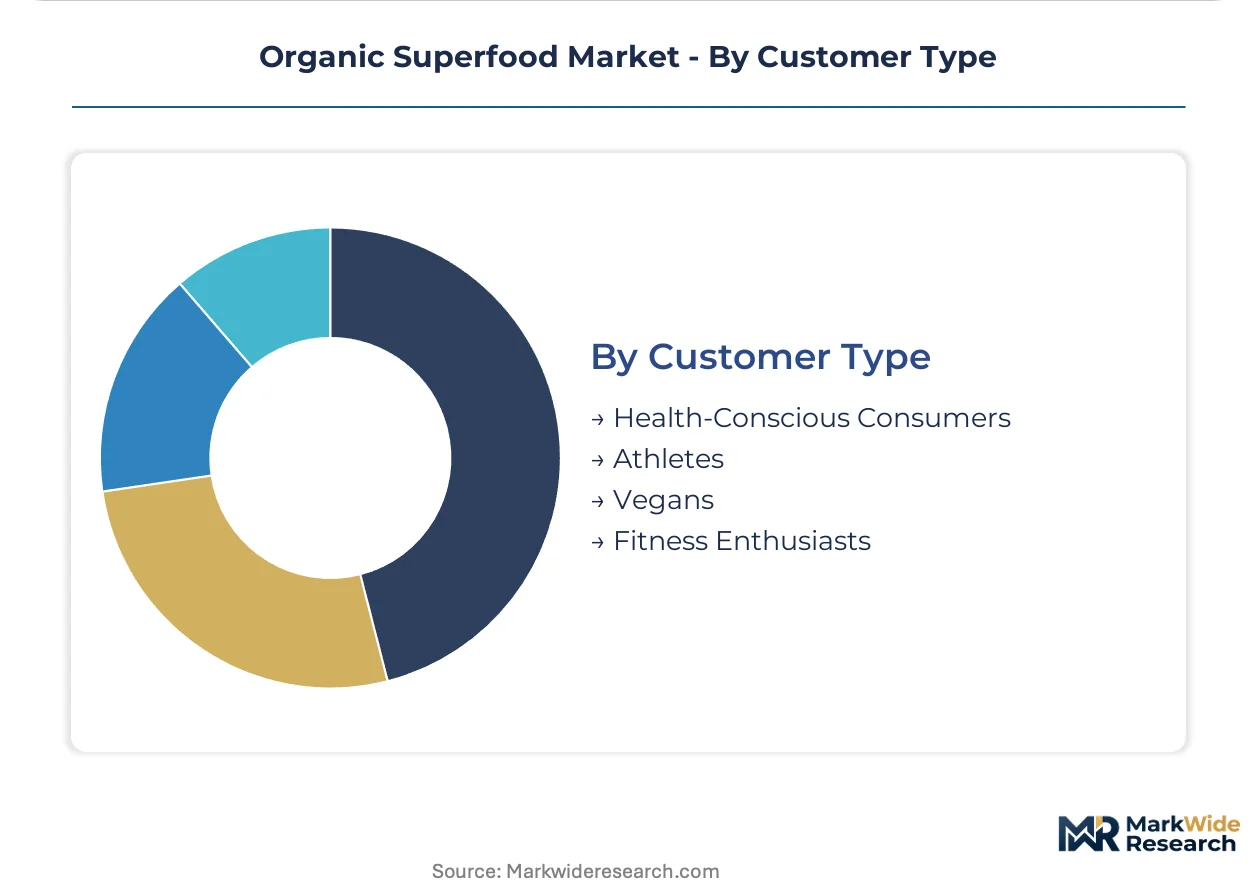
Customer Type:
Usage occasion and nutritional literacy shape product format preferences and willingness-to-pay thresholds.
- Health-Conscious Consumers:Broad demographic spanning meal replacement and preventive supplementation occasions with highest penetration of powder formats.
- Fitness Enthusiasts:Performance-oriented consumption timing around exercise windows favoring ready-to-drink beverages with rapid absorption claims.
- Athletes:Dosing precision requirements and banned-substance testing protocols that favor capsule formats with third-party certification.
- Vegans:Ethical alignment purchasing with non-negotiable organic certification and supply chain transparency demands.
Health-conscious consumers provide the revenue base; fitness enthusiasts drive format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified organic ingredient specialists concentrate procurement teams in Germany, where discounters and drugstores drive shelf-space expansion for superfood powders and snack bars. The EU Green Deal's residue limit tightening pulls compliance talent toward Rotterdam and Hamburg logistics hubs. Cold-chain engineers cluster in Dutch and Danish port cities managing South American seed imports.
Germany
Health-conscious consumers in Berlin and Hamburg metropolitan areas verify batch-specific organic credentials through app-based QR-code scanning. EFSA residue limit revisions under the EU Green Deal mandate stricter testing protocols for imported chia and hemp seed volumes. Munich-based food technologists develop cold-press dehydration methods preserving heat-sensitive phytonutrients for powder formats.
United States
Fitness enthusiasts in California and New York drive ready-to-drink functional shot penetration through convenience retail channels. USDA Organic certification governs market access through strict soil management and prohibited substance lists. Boulder, Colorado anchors natural products innovation clusters where zero-trans-fat and non-GMO verified lines originate.
India
Vegan consumer segments in Maharashtra and Karnataka demand supply chain transparency with non-negotiable organic certification requirements. FSSAI and BIS frameworks tighten import testing for heavy metals and microbial contamination in superfood shipments. Mumbai logistics hubs absorb documentation burdens that delay seed and grain shipments from South American cooperatives.
Brazil
Chia and quinoa cultivation concentrates in Minas Gerais and Rio Grande do Sul where organic certification infrastructure serves European export demand. EU Organic Regulation reciprocity agreements shape cooperative investment in origin-country laboratory capacity. São Paulo-based exporters navigate dual compliance burdens for USDA Organic and EU documentation streams.
Netherlands
Rotterdam port facilities handle bulk organic cacao and hemp seed transshipment from South American cooperatives to German retail. Blockchain traceability platforms decentralize verification from centralized certifiers to distributed ledger systems. Amsterdam food-tech clusters integrate cold-chain logistics with real-time organic claim verification systems.
Organic Superfood Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the organic superfood value chain. Vertically integrated agricultural cooperatives in South America control scarce chia, quinoa, and hemp seed supply against North American and European brands dependent on external procurement. Three strategic archetypes dominate: certified organic specialists with direct cooperative relationships, diversified food conglomerates leveraging broad portfolio breadth, and private-label suppliers serving discounter channels. M&A activity concentrates on traceability technology acquisitions and cold-chain logistics partnerships.
Among certified organic specialists, Nutiva and Nature's Path Organic Foods exemplify direct sourcing archetypes with established cooperative networks. The Hain Celestial Group occupies a diversified portfolio position spanning powders, beverages, and snack bars. Sunfood Superfoods and Suncore Foods sit within the ingredient-focused tier supplying private-label programs. Nature's Superfoods LLP represents UK-structured entities navigating post-Brexit certification reciprocity. General Mills and Danone exemplify conglomerate players extending conventional distribution into organic superfood adjacencies.
| Leading Market Players |
|---|
| Sunfood Superfoods |
| Nutiva |
| Nature's Superfoods LLP |
| Suncore Foods |
| The Hain Celestial Group |
| General Mills |
| Danone |
| Organic Valley |
| Nature's Path Organic Foods |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EU Organic and conventional tiers splits procurement budgets and supplier qualification pipelines across German retail networks. Powder formats command premium positioning through cold-press processing investments, while beverage applications absorb margin compression from cold-chain logistics requirements.
Pricing Analysis
Bundled certification-plus-traceability services separate premium organic superfood tiers from unbundled commodity alternatives in European procurement. Three-tier pricing structure across premium, standard, and economy levels reflects USDA Organic versus EU Organic documentation depth, with German discounters driving standard-tier volume. Pricing pressure stems from chia and hemp seed scarcity in South American cooperatives. Fitness enthusiasts show lowest price sensitivity for ready-to-drink formats; conventional fruit-derived alternatives capture price-sensitive health-conscious segments.
Supply Chain Analysis
Certification gating through EU Organic Regulation and USDA Organic parallel documentation reshapes supplier qualification timelines and procurement network structures. Raw material flows draw from Minas Gerais and Rio Grande do Sul in Brazil for chia and quinoa, with hemp seed sourcing anchored in Canadian prairie cultivation zones. Single-source vulnerability concentrates in South American cooperative structures for premium seed varieties. Distribution runs through Rotterdam port facilities managing bulk transshipment to German retail consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork Strategy compounds demand for certified organic supply chains, tightening residue limits and traceability mandates that reshape procurement economics across European retail.
For Market Incumbents: Deploy blockchain traceability infrastructure to preempt EFSA documentation requirements and compress audit cycles. Secure direct cooperative relationships with Minas Gerais cultivation networks before residue limit revisions harden. Channel control through discounter private-label programs defends against diversified food conglomerates extending into organic adjacencies.
For New Entrants and Emerging Players: Urban convenience retail in Berlin and Hamburg represents underserved distribution infrastructure for ready-to-drink functional shots. Fitness enthusiasts seeking rapid-absorption beverage formats show penetrable willingness-to-pay thresholds. Go-to-market through app-based QR-code verification aligns with metropolitan consumer verification behavior.
For Investors and Strategic Acquirers: Consolidation pressure builds where traceability technology gaps fragment mid-tier supplier compliance capabilities. Long-term viability favors cold-chain logistics partnerships and origin-country laboratory capacity investments. Acquisition targets include cooperatives with established EU Organic certification infrastructure. Watch FSSAI import testing protocol tightening as inflection signal for supply chain reconfiguration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Decentralizes organic claim verification from EFSA audit bottlenecks to distributed ledger systems. |
| Cold-Chain Logistics Partnership | Enables real-time temperature monitoring for beverage-format superfoods entering German convenience retail. |
| Origin-Country Laboratory Investment | Compresses EU Organic Regulation compliance timelines for South American cooperative exporters. |
| Discounter Private-Label Expansion | Captures standard-tier volume through Aldi and Lidl shelf-space allocation for powder formats. |
| Direct Cooperative Sourcing | Secures scarce chia and hemp seed volumes ahead of diversified conglomerate procurement competition. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with organic certification officers, cooperative export managers, German discounter category buyers, and cold-chain logistics engineers with secondary validation. Trade data from customs records, EU Organic Regulation filing databases, and FSSAI import testing disclosure reports anchored supply-side estimates. Nielsen retail audit data and proprietary cultivation yield surveys informed demand-side calibration. Bottom-up cooperative volume aggregation and top-down retail revenue triangulation cross-checked segment outputs.
Historical reference periods anchored volume and value trajectories across the modeling period, with CAGRs derived from segmented regression against certification penetration rates and channel expansion timelines. Segmentation dimensions modeled included product format, ingredient source origin, distribution channel tier, and customer usage occasion. Forecast inputs incorporated EFSA residue limit revision schedules and EU Green Deal implementation pacing.
Underlying measurement precision varies by segment; powder format revenue carries tighter precision than emerging beverage applications due to established retail audit coverage. Forecasts reflect assumptions on certification reciprocity agreement stability and cooperative yield continuity. A model refresh is warranted upon material change in EU Organic Regulation enforcement intensity or FSSAI testing protocol expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Organic Soda Market