
 Europe Organic Food and Beverages Market | 2026-2036
Europe Organic Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Food and Beverages Market Intelligence
Multi-source procurement from certified organic farms is realigning how European retailers secure fresh produce and processed goods. Danone leverages its dairy processing network across France to maintain consistent organic milk supply volumes. Hipp GmbH & Co. Vertrieb KG anchors its competitive position through specialized infant nutrition formulations that command shelf space in German pharmacy and grocery channels. Alnatura Produktions- und Handels GmbH controls its own retail footprint and private-label manufacturing, giving it direct visibility into household purchasing patterns.
Europe organic food and beverages encompass agricultural products and drinks cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, adhering to EU Regulation 2018/848 certification standards that mandate traceable supply chains from soil to shelf. These goods serve commercial and household buyers seeking verified chemical-free nutrition with documented provenance. Dairy products occupy the highest margin pool among product type segments, reflecting the cost premium commanded by grass-fed, antibiotic-free milk sourcing and extended cold-chain logistics. Beverages represent the fastest-growing category as sparkling organic juices, kombucha, and plant-based drinks gain placement in cafés and specialty stores. Households dominate end-user demand, though restaurant procurement is expanding as chefs build menu differentiation around certified organic ingredients.
The EU Green Deal and the Farm to Fork Strategy are mandating pesticide reduction targets that directly expand the economic viability of organic conversion for conventional farmers. EFSA residue monitoring and national enforcement by BfR in Germany and ANSES in France create compliance barriers that favor established certifiers with laboratory and audit infrastructure. REACH chemical restrictions and emerging CSRD sustainability disclosure rules will force ingredient suppliers to document environmental impact across packaging and agricultural inputs. Stakeholders must monitor how the EU's evolving organic logo integrity framework and third-country equivalency negotiations reshape import competition from non-European suppliers.
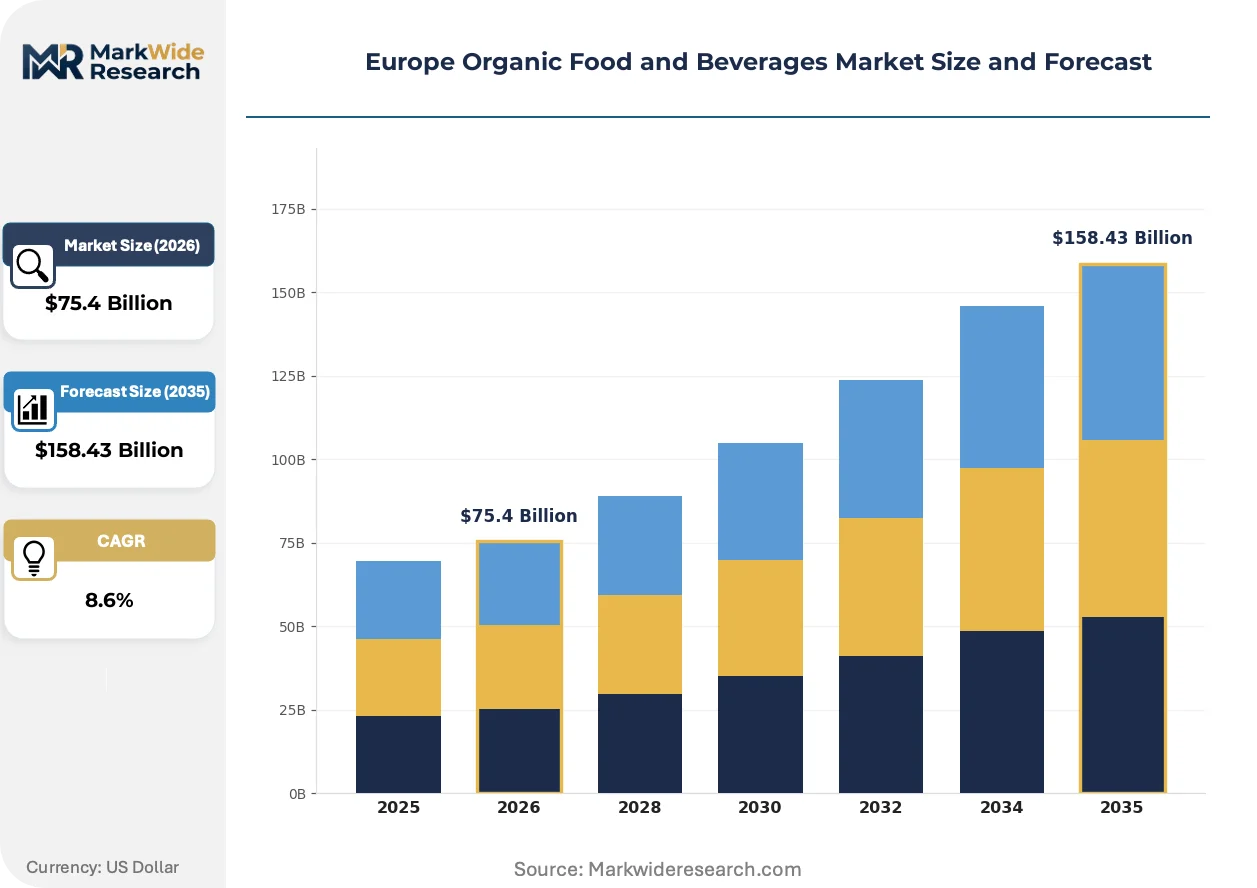
Market Dynamics
EU Regulation 2018/848 certification standards are compressing conversion timelines for conventional farmers while supermarket chains demand traceable supply chains from soil to shelf, creating a structural squeeze on mid-tier producers without captive organic acreage.
Growth Catalysts
- Farm to Fork Strategy:The EU Green Deal's pesticide reduction targets expand economic viability of organic conversion for conventional farmers across France and Germany.
- Discounter channel expansion:German retailers have built dedicated organic supply chains spanning fresh dairy and packaged vegetables that now capture migrating household spending.
- Grass-fed sourcing protocols:Antibiotic-free milk sourcing commands premium positioning in European dairy segments with extended cold-chain logistics.
Market Restraints
- Input cost volatility:Organic feed grain prices fluctuate with weather-dependent yields across Black Sea and Baltic sourcing regions.
- Certification timeline friction:EFSA residue monitoring and national enforcement by BfR and ANSES create multi-year conversion barriers for conventional operators.
- Supply concentration risk:Dedicated organic processing capacity clusters in northern Italy and southern Germany, creating geographic bottlenecks.
Strategic Opportunities
- Portuguese and Spanish acreage:Iberian Peninsula organic cultivation remains underpenetrated relative to German and French market depth.
- CSRD disclosure mandates:Emerging sustainability reporting rules force ingredient suppliers to document environmental impact, favoring early-certified operators.
- Plant-based beverage convergence:Kombucha and sparkling organic juices gain placement in café channels previously dominated by conventional soft drinks.
Industry Challenges
- Auditor capacity scarcity:Laboratory and audit infrastructure required by EU organic logo integrity frameworks faces bottlenecks in eastern European markets.
- Legacy system integration:Conventional dairy processors retrofitting lines for organic segregation encounter workflow friction and capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Food and Beverages Market |
| Market Size in 2026 | $75.4 Billion |
| Market Size in 2035 | $158.43 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy Products, Beverages End User: Households, Restaurants, Retailers, Cafés Packaging Type: Glass, Plastic, Carton, Biodegradable Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Farmers' Markets |
| Companies Covered | General Mills, Hipp GmbH & Co. Vertrieb KG, Danone, Alnatura Produktions- und Handels GmbH, Bjorg Bonneterre et Compagnie, Nestlé, Amy's Kitchen, Green & Blacks, The Hain Celestial Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Food and Beverages Market Strategic Shifts & Innovations
Blockchain-enabled traceability systems are modularizing how European retailers verify provenance claims, while CSRD disclosure requirements and shifting household purchasing patterns are compressing competitive timelines for certification and transparency.
Blockchain-based supply chain verification is modularizing the documentation of organic provenance from farm to retail shelf. German supermarket chains and French dairy cooperatives are deploying these systems to compress audit cycles and reduce certification friction. The technology is modularizing what previously required manual laboratory sampling into automated, immutable record-keeping that lowers compliance costs for multi-site operators.
CSRD sustainability disclosure rules are mandating granular environmental impact documentation across packaging and agricultural inputs. Food manufacturers must now track embedded carbon and water usage through tier-two suppliers, creating compliance overhead that favors vertically integrated producers. Dairy and beverage segments face the steepest reporting burdens due to complex, geographically dispersed sourcing networks.
Household purchasing is rotating toward private-label organic SKUs as discounters expand dedicated shelf space and pharmacy channels stock specialized infant nutrition. German consumers now expect organic certification as a baseline attribute rather than a premium differentiator, compressing price realization for non-certified alternatives. This behavioral shift is most visible in fresh dairy and ready-to-drink beverages where certification-driven preference has become the default selection heuristic.
Europe Organic Food and Beverages Market Segmentation
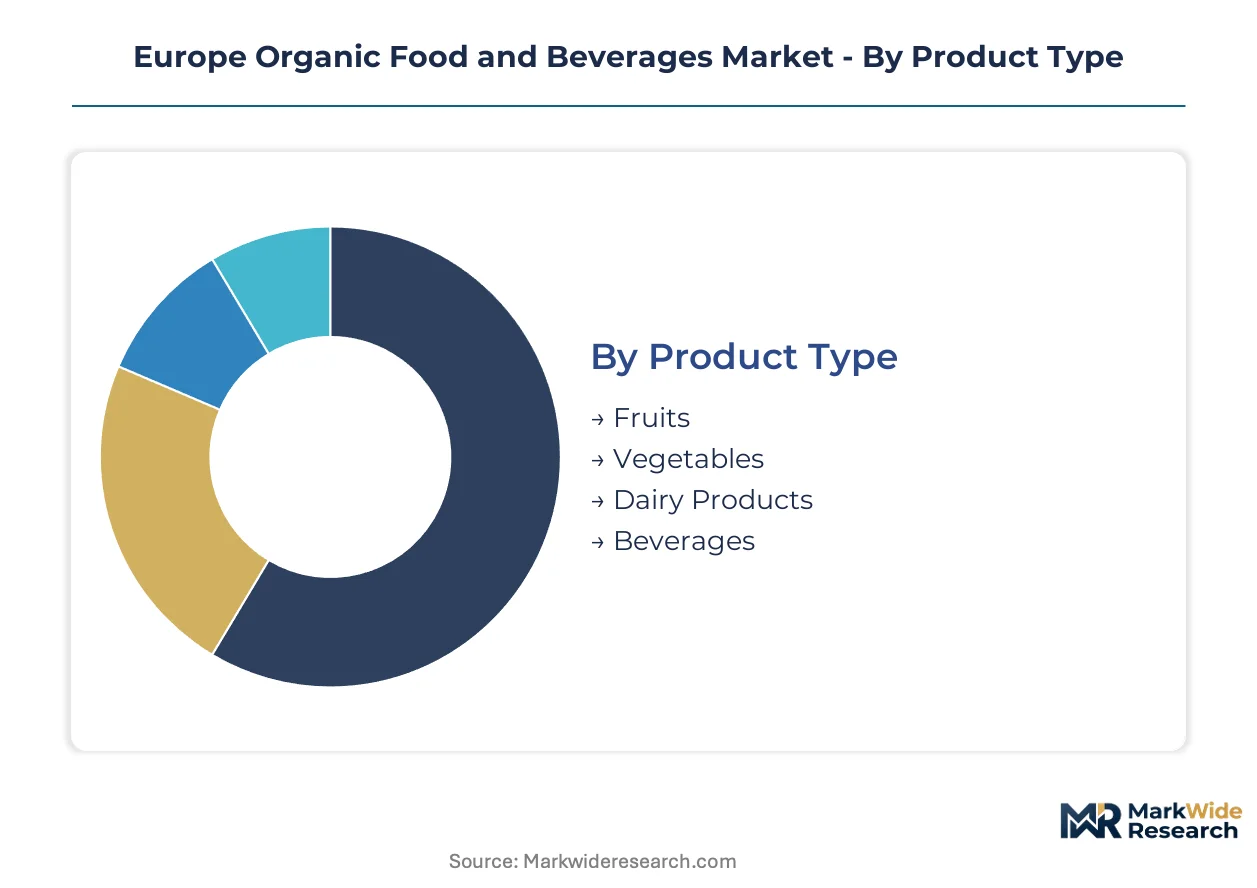
Organic certification requirements create divergent margin structures across product categories, while distribution channel fragmentation forces suppliers to maintain parallel supply chains with distinct handling protocols. Segmentation reveals where household purchasing concentration overlaps with regulatory compliance burdens to reshape competitive positioning.
Product Type:
Standardization dominates at the commodity tier while premium differentiation concentrates in segments with extended cold-chain requirements and specialized sourcing protocols.
- Dairy Products:Grass-fed, antibiotic-free milk sourcing commands the highest margin pool through extended cold-chain logistics and specialized processing infrastructure. German and French retailers capture household spending migration through dedicated organic dairy SKUs that span fresh milk, yogurt, and cheese categories.
- Beverages:Sparkling organic juices, kombucha, and plant-based drinks are gaining placement in café channels previously dominated by conventional soft drinks. Demand is concentrating in German urban centers where discounters and specialty retailers have built dedicated beverage supply chains.
- Fruits:Certified cultivation without synthetic pesticides requires traceable supply chains from soil to shelf under EU Regulation 2018/848.
- Vegetables:Packaged organic vegetables migrate household spending away from conventional produce through supermarket private-label expansion.
Most installed capacity flows through Dairy Products. Expansion is steepest in Beverages.
End User:
Volume concentration sits with direct household consumption while commercial procurement builds menu differentiation around certified ingredients.
- Households:German consumers now expect organic certification as a baseline attribute rather than a premium differentiator, compressing price realization for non-certified alternatives. Discounters and full-service retailers have built dedicated organic supply chains spanning fresh dairy, packaged vegetables, and ready-to-drink beverages.
- Restaurants:Chef-driven menu differentiation around certified organic ingredients is expanding procurement volumes beyond retail channels. French and Italian restaurant operators source through specialized distributors with farm-to-table traceability documentation.
- Retailers:Supermarket chains across Germany, France, and Italy are expanding private-label organic SKUs to capture migrating household spending.
- Cafés:Specialty beverage placement is rotating toward kombucha and sparkling organic juices with verified provenance claims.
Households absorb the majority of volume. Restaurants are climbing the fastest as procurement formalizes around certification requirements.
Packaging Type:
Sustainability disclosure mandates under CSRD rules are forcing documentation of embedded carbon and water usage across material choices.
- Biodegradable:Emerging CSRD sustainability disclosure rules favor packaging with documented environmental impact reduction. German retailers are piloting biodegradable alternatives in fresh produce categories to meet Farm to Fork Strategy waste reduction targets.
- Glass:Premium beverage positioning leverages glass for perceived quality differentiation in sparkling juices and kombucha. Italian and French producers maintain glass lines for export markets requiring extended shelf stability.
- Carton:Extended shelf-life dairy and plant-based beverages deploy carton formats for cold-chain efficiency.
- Plastic:Lightweight formats persist in cost-sensitive segments despite regulatory pressure under REACH chemical restrictions.
Glass retains dominance in premium beverage tiers. Biodegradable formats are gaining share fastest as CSRD compliance tightens.
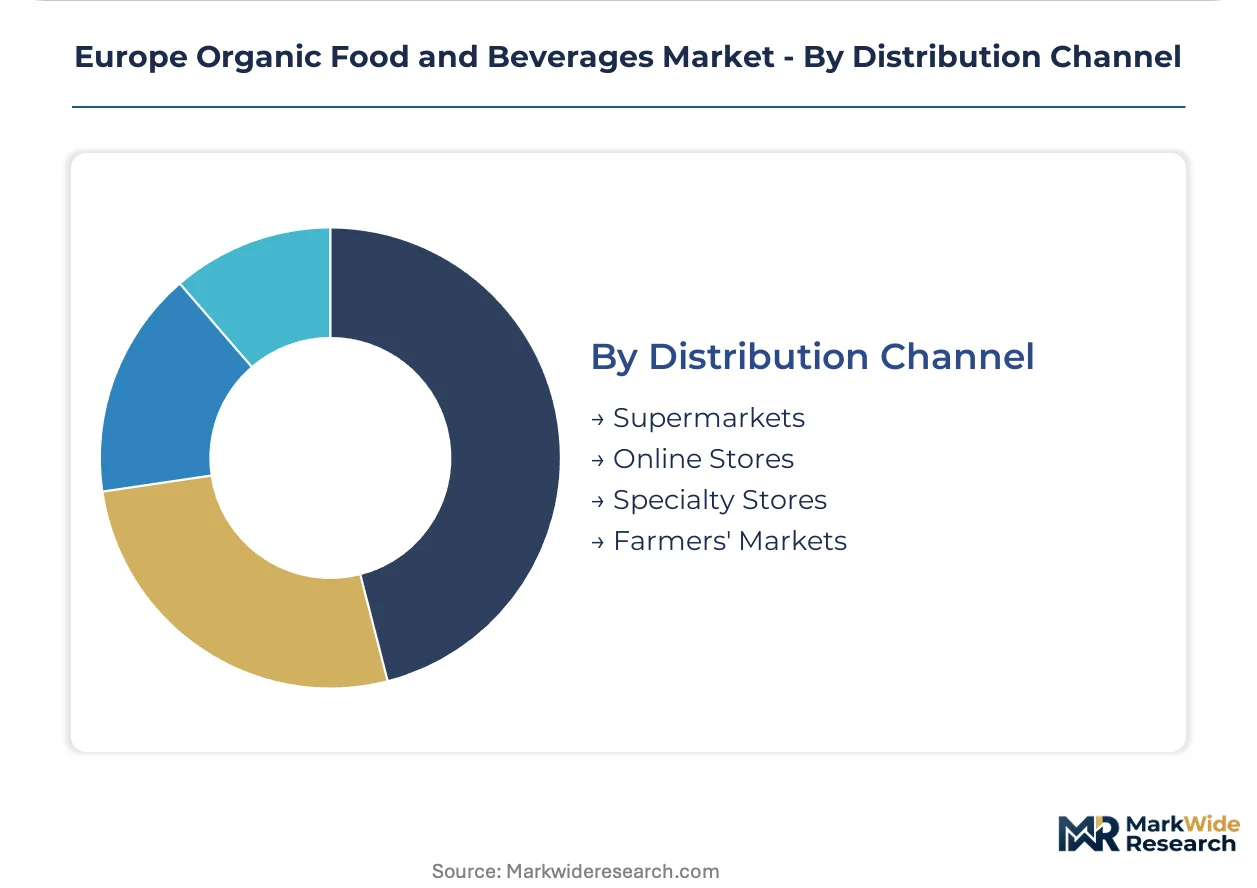
Distribution Channel:
Channel fragmentation requires suppliers to maintain distinct handling protocols for mass retail versus specialty and direct-to-consumer routes.
- Supermarkets:Discounters and full-service retailers in Germany have built dedicated organic supply chains with traceable provenance from certified farms. Private-label expansion is compressing branded shelf space while capturing household spending migration.
- Specialty Stores:Pharmacy channels stock specialized infant nutrition with organic certification as a baseline attribute. Hipp GmbH & Co. anchors competitive position through these formats in German-speaking markets.
- Online Stores:Direct-to-consumer routes are expanding for subscription-based dairy and beverage deliveries with cold-chain guarantees.
- Farmers' Markets:Direct producer-to-consumer sales concentrate in southern Germany and northern Italy with regional organic certification.
Supermarkets control the majority of throughput. Specialty Stores are expanding most quickly as pharmacy and premium grocery channels formalize organic assortment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as farmers migrate toward jurisdictions with faster certification timelines and lower conversion cost burdens. The EU Green Deal harmonizes standards but enforcement capacity varies, creating pockets of competitive advantage for early-converting regions.
Germany
Discounters Aldi and Lidl have built dedicated organic supply chains spanning fresh dairy and packaged vegetables that capture household spending migration. BfR enforces pesticide residue thresholds that favor established certifiers with laboratory infrastructure. Bavaria and Lower Saxony cluster organic processing capacity for milk and infant nutrition, with Danone leveraging its French-German border network to maintain supply volumes.
France
Chef-driven restaurant procurement is formalizing around certified ingredients, expanding volumes beyond retail channels. ANSES monitors residue levels under EU Regulation 2018/848, creating compliance barriers for conventional operators. The Auvergne-Rhône-Alpes region anchors dairy cooperative processing, while Île-de-France supermarkets expand private-label SKUs to defend market share against German discounters.
Italy
Sparkling organic juices and plant-based beverages gain placement in café channels previously dominated by conventional soft drinks. EFSA equivalence negotiations with third-country suppliers reshape import competition for olive oil and wine. Northern Italy clusters dedicated organic processing infrastructure, creating geographic bottlenecks that concentrate margin capture in Emilia-Romagna and Lombardy.
Spain
Iberian Peninsula organic cultivation remains underpenetrated relative to German and French market depth, offering acreage expansion potential. The Farm to Fork Strategy accelerates conversion timelines in Andalusia and Catalonia. Valencia and Murcia develop citrus and vegetable export capacity with traceable supply chains from soil to shelf under tightening EU organic logo integrity frameworks.
United Kingdom
Post-Brexit regulatory divergence creates friction for cross-border organic trade with EU suppliers. The country's national food standards regulator maintains parallel certification requirements that compress conversion timelines for domestic farmers. London and Southeast England concentrate specialty retail and pharmacy channels where Hipp GmbH & Co. anchors competitive position through infant nutrition placement.
Europe Organic Food and Beverages Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue plant-based beverage convergence and CSRD-compliant transparency systems. The vendor base stratifies across three tiers: multinational food conglomerates with dairy processing networks, specialized organic retailers controlling captive supply chains, and regional infant nutrition formulators with pharmacy channel access. Consolidation pressure concentrates in dairy and beverage segments where cold-chain infrastructure demands capital intensity. Dominant competitive moves include backward integration into certified organic acreage and strategic partnerships with blockchain traceability providers.
Within the specialized retailer tier, Alnatura Produktions- und Handels GmbH exemplifies vertical control through captive private-label manufacturing and direct retail footprint visibility. Among infant nutrition specialists, Hipp GmbH & Co. Vertrieb KG occupies a position anchored in German pharmacy and grocery channel relationships. Danone represents the multinational archetype, leveraging cross-border dairy processing networks to maintain consistent organic milk supply volumes across French and German markets.
| Leading Market Players |
|---|
| General Mills |
| Hipp GmbH & Co. Vertrieb KG |
| Danone |
| Alnatura Produktions- und Handels GmbH |
| Bjorg Bonneterre et Compagnie |
| Nestlé |
| Amy's Kitchen |
| Green & Blacks |
| The Hain Celestial Group |
| Others |
Cost & Logistics Intelligence
Organic feed grain futures on the Black Sea exchange cascade through European dairy and meat supply chains, compressing margins at the processor tier while supermarket private-label expansion forces branded players toward certification-driven price differentiation.
Pricing Analysis
Input-cost pass-through from organic soybean and wheat meal prices operates on a 6-12 month lag, creating margin volatility for German and French dairy processors. Three-tier pricing structure across premium grass-fed, standard organic, and economy conventional tiers separates antibiotic-free protocols from baseline EU organic certification. Pricing pressure stems from discounter channel expansion as Aldi and Lidl compress branded shelf space with captive private-label SKUs. Household buyers in Germany exhibit lowest price sensitivity due to certification-as-baseline expectations, while Spanish and Italian retail channels retain higher elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German supermarket chains mandate qualified organic milk suppliers in both Bavaria and northern France, preventing single-origin concentration risk. Geographic supply concentration clusters in Germany, France, and northern Italy for dairy processing, with Spanish and Portuguese acreage expanding for fresh produce. Raw material dependencies center on Black Sea organic grains, Baltic grass seed, and domestic hay supplies. Supply chain risk manifests through EFSA residue testing bottlenecks that delay harvest-to-shelf timelines. Distribution runs through dedicated cold-chain networks serving discounters, with pharmacy channels maintaining parallel handling protocols for infant nutrition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe organic food and beverages market functions as a stable compounder, with EU Green Deal regulatory harmonization creating predictable conversion incentives that compound acreage expansion and household penetration over successive policy cycles.
For Market Incumbents: Lock in certified organic acreage through long-term farm partnerships before Spanish and Portuguese land conversion accelerates. Invest in blockchain traceability infrastructure to compress audit cycles and defend shelf space against private-label encroachment. Prioritize backward integration into grass-fed dairy sourcing to secure margin pools threatened by input cost volatility. For New Entrants and Emerging Players: Capture underpenetrated Iberian Peninsula cultivation through direct farm partnerships in Andalusia and Catalonia. Target plant-based beverage convergence in German café channels where kombucha and sparkling juice placement remains fragmented. Pursue specialty pharmacy distribution for infant nutrition to bypass supermarket private-label dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap producers controlling captive organic acreage and cold-chain infrastructure. Long-term viability rests on CSRD compliance readiness and Farm to Fork Strategy alignment. Watch EFSA third-country equivalency negotiations as the inflection signal for import competition intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Acreage | Danone and Alnatura secure grass-fed milk supply through direct farm contracts in France and Germany. |
| Blockchain Traceability Deployment | German retailers compress EFSA audit cycles with immutable farm-to-shelf documentation systems. |
| Iberian Cultivation Expansion | Spanish and Portuguese operators capture Farm to Fork conversion incentives in underpenetrated southern markets. |
| Pharmacy Channel Penetration | Hipp GmbH anchors infant nutrition placement through specialized distribution bypassing discounter dominance. |
| Plant-Based Beverage Innovation | Kombucha and sparkling juice producers gain café shelf space previously held by conventional soft drinks. |
Research Approach
Direct dialogue with organic dairy processors, supermarket category buyers, farm cooperative managers, and EFSA compliance officers grounded qualitative findings in operational realities across Germany, France, and Italy. Secondary validation drew from EU organic certification databases, BfR and ANSES residue monitoring reports, customs trade records for organic feed grains, and CSRD disclosure filings from listed food manufacturers. Bottom-up acreage and processing capacity estimates triangulated against top-down household expenditure surveys and retail audit data.
Bottom-up modeling of certified organic farm conversions and processing capacity additions across the projection horizon anchored volume forecasts, while top-down expenditure elasticity analysis shaped value projections. Segmentation dimensions spanned product type, end-user channel, packaging format, and distribution route. CAGRs derived from regression analysis against EU Green Deal implementation timelines and Farm to Fork pesticide reduction milestones. Industry-specific inputs included organic feed grain price indices and cold-chain logistics cost benchmarks.
Regulatory enforcement variance, organic feed commodity volatility, and third-country import equivalence decisions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around EU organic logo integrity framework implementation and CSRD disclosure phase-in schedules. Deviation in EFSA third-country equivalency negotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Pasta Market