
 Organic Drinks Market | 2026-2036
Organic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Drinks Market Outlook
Consolidation among specialty grocery retailers and wellness hospitality chains is repositioning volume leverage toward fewer, larger buyers with strict procurement protocols. The Hain Celestial Group leverages its private-label manufacturing scale to serve these consolidated accounts directly. PepsiCo competes through its Naked Juice and KeVita holdings, extending shelf-space negotiations across conventional and natural channels. Suja Life LLC specializes in cold-pressed organic juices, anchoring its presence in premium refrigerated sets where buyer concentration demands consistent supply reliability.
Organic drinks are non-alcoholic beverages produced from agricultural ingredients cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, typically bearing third-party certifications such as USDA Organic or EU Organic logo compliance. Primary commercial purpose centers on delivering perceived health benefits, environmental accountability, and clean-label transparency to consumers seeking alternatives to conventional processed beverages. Juices and teas currently occupy the largest revenue share within product type segmentation, though smoothies demonstrate the fastest velocity in premium channels where ingredient source claims around superfruits and adaptogenic herbs command price premiums. Packaging type segmentation reveals structural tension: bottles retain dominance in refrigerated premium positioning, while cans and Tetrapacks gain ground in mass-market distribution where cost efficiency and logistics optimization override shelf aesthetics.
USDA Organic certification enforced by the USDA's National Organic Program governs ingredient sourcing and processing standards for products sold in the United States, creating compliance cost barriers that filter smaller processors from national retail access. The EU Green Deal and EFSA pesticide residue benchmarks operate in parallel, requiring dual-certification investments for brands pursuing transatlantic distribution. Stakeholders must monitor evolving definitions of organic equivalence between regulatory regimes, as divergence in permitted substances or labeling claims threatens to fragment supply chain planning and inventory allocation across jurisdictions.
Market Dynamics
Consolidation among German organic retailers and wellness hospitality chains is concentrating procurement power into fewer accounts with stringent certification requirements, forcing suppliers to absorb dual USDA-EU compliance costs or exit transatlantic distribution.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Tightening pesticide residue thresholds across European supply chains is accelerating reformulation investments and locking in organic ingredient demand from German processors.
- Specialty café procurement:Wellness-focused hospitality chains are expanding certified organic beverage menus, creating pull-through demand for cold-pressed juice and adaptogenic tea supply contracts.
- Clean-label transparency technology:Blockchain-enabled provenance tracking is absorbing compliance documentation burdens, reducing audit friction for exporters serving multiple certification regimes.
Market Restraints
- Organic ingredient cost volatility:Weather-sensitive superfruit harvests in Peru and India create input price instability that compresses margin buffers for refrigerated juice processors.
- Dual-certification regulatory friction:Diverging permitted substance lists between USDA National Organic Program and EU Organic logo requirements fragment inventory planning for transatlantic brands.
- Glass bottle supply concentration:European container manufacturing clusters in Italy and Germany create logistics vulnerability for premium positioned organic drinks dependent on refrigerated shelf aesthetics.
Strategic Opportunities
- Underpenetrated French market:Organic retail infrastructure outside Paris remains sparse, creating first-mover advantage for brands establishing direct-store-delivery relationships with regional cooperatives.
- Adaptogenic ingredient convergence:Formulation combining ashwagandha and reishi with organic juice bases is opening premium pricing tiers in German pharmacy and wellness channels.
- Refillable bottle deposit systems:Circular packaging mandates in Denmark and Sweden are creating channel innovation opportunities for brands investing in return logistics infrastructure.
Industry Challenges
- Organic certification timeline compression:USDA three-year land conversion requirements delay new supplier onboarding, constraining volume scaling for fast-growing smoothie segments.
- Cold-chain capex intensity:Refrigerated distribution networks for HPP-treated juices demand capital deployment that filters mid-cap processors from national retail access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Drinks Market |
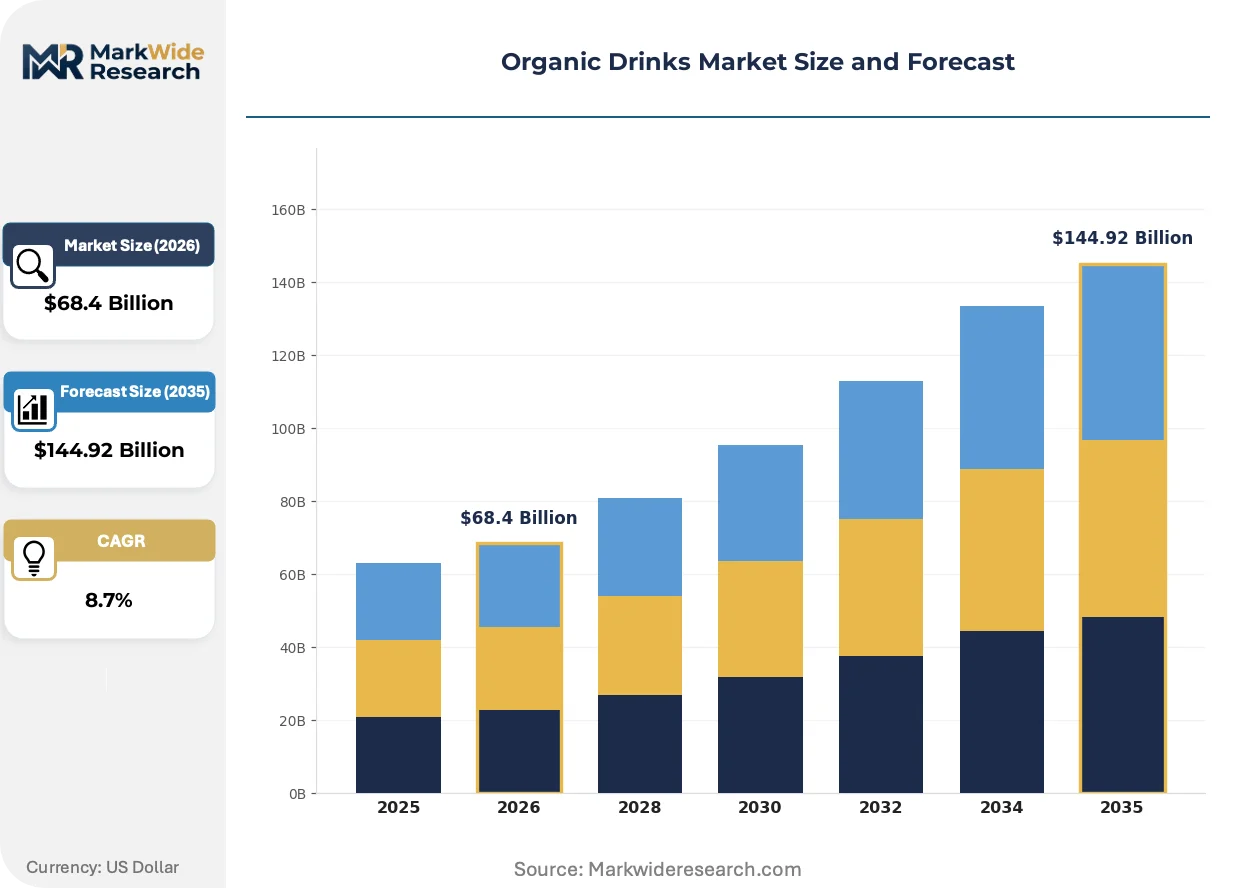
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juices, Teas, Coffee, Smoothies Ingredient Source: Fruit, Vegetables, Herbs, Grains Packaging Type: Bottles, Cans, Tetrapacks, Pouches Distribution Channel: Supermarkets, Online Retail, Health Stores, Cafés |
| Companies Covered | The Hain Celestial Group, Inc., Suja Life LLC, The Coca-Cola Company, Organic Valley, GT’s Living Foods, PepsiCo, Inc., Nestlé S.A., Health-Ade Kombucha, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Drinks Market Strategic Shifts
Reformulation around functional ingredients and packaging circularity is absorbing R&D investment across the value chain, with regulatory pressure on pesticide residues and plastic waste driving simultaneous innovation in sourcing and materials.
High-pressure processing technology is absorbing shelf-life extension demands without thermal degradation of organic nutrient claims. German refrigerated juice brands are adopting HPP at accelerating pace to support clean-label positioning. This adoption is absorbing the technical barrier that previously limited organic juice distribution beyond regional proximity.
REACH chemical restrictions and EU Green Deal packaging mandates are forcing substitution of conventional plastic films with bio-based barrier materials. German and Dutch organic beverage processors face the steepest compliance curves. Premium juice segments are responding with fiber-based bottle trials and deposit-return system participation.
Direct procurement relationships between organic ingredient cooperatives and specialty retail buyers are compressing traditional distributor margins. German REWE and dm-drogerie markt chains are building captive organic supply networks. This disintermediation is most visible in Bavaria and Baden-Württemberg, where regional organic farming density supports shortened supply chains.
Organic Drinks Market Segmentation
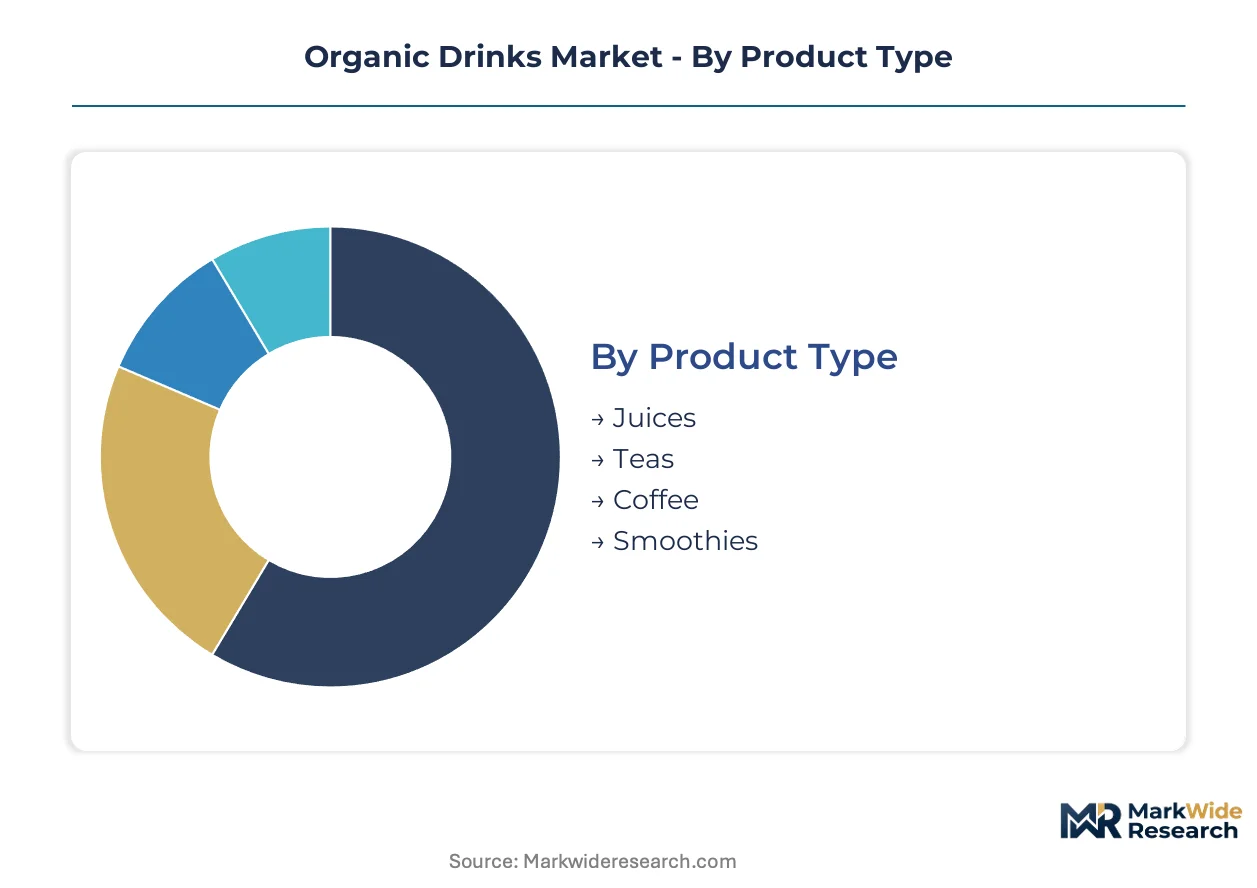
Certification requirements fragment procurement strategies across segment boundaries, with refrigerated formats demanding dual USDA-EU compliance while ambient-stable alternatives navigate simpler single-jurisdiction pathways. Segmentation discipline separates volume-scalable mass-market plays from margin-protected premium positioning.
Product Type:
USDA Organic and EU Organic logo requirements apply uniformly across all product types, though juice processors face heightened EFSA pesticide residue scrutiny due to concentrated fruit sourcing from multiple origins.
- Juices:Cold-pressed and HPP-treated variants dominate refrigerated sets, with German REWE and dm-drogerie markt chains driving volume concentration through direct cooperative procurement. Dual-certification costs filter smaller processors from transatlantic distribution.
- Teas:Adaptogenic formulations combining ashwagandha and reishi command pharmacy-channel premiums. German wellness hospitality chains are expanding certified organic tea menus, creating pull-through demand for ingredient traceability documentation.
- Coffee:Organic arabica sourcing concentrates in Peruvian and Ethiopian highland cooperatives.
- Smoothies:Superfruit and protein-fortified blends represent the steepest expansion trajectory in premium channels.
Juices sit at the top of the volume ranking, with smoothies climbing the fastest.
Ingredient Source:
Cost tier separation distinguishes commodity-scale grain inputs from premium herb and superfruit sourcing, with the latter absorbing disproportionate compliance documentation burdens.
- Fruit:Weather-sensitive harvests in Peru and India create input price instability that compresses margin buffers for refrigerated juice processors. German organic retailers demand blockchain-enabled provenance tracking for berry and citrus supply chains.
- Vegetables:Cold-pressed vegetable blends anchor premium positioning in German pharmacy channels, with kale and beet formulations driving repeat purchase rates.
- Herbs:Adaptogenic ingredient sourcing requires extended supplier qualification timelines under USDA three-year land conversion rules.
- Grains:Oat and rice bases support ambient-stable beverage expansion into mass-market distribution.
Fruit commands the largest procurement spend, with herbs expanding most quickly on functional positioning.
Packaging Type:
Supply concentration in European container manufacturing creates divergent logistics vulnerability profiles, with glass-dependent formats exposed to Italian and German production cluster disruptions.
- Bottles:Glass retains dominance in refrigerated premium positioning, though fiber-based bottle trials are accelerating under EU Green Deal packaging mandates. German and Dutch processors face the steepest compliance curves for bio-based barrier material substitution.
- Cans:Aluminum formats gain ground in mass-market distribution where cost efficiency and logistics optimization override shelf aesthetics. REACH chemical restrictions are forcing liner material reformulation.
- Tetrapacks:Aseptic carton systems support ambient-stable organic juice distribution beyond regional proximity.
- Pouches:Flexible formats absorb single-serve convenience demand in German convenience store channels.
Bottles maintain volume leadership, with cans gaining share fastest on sustainability messaging.
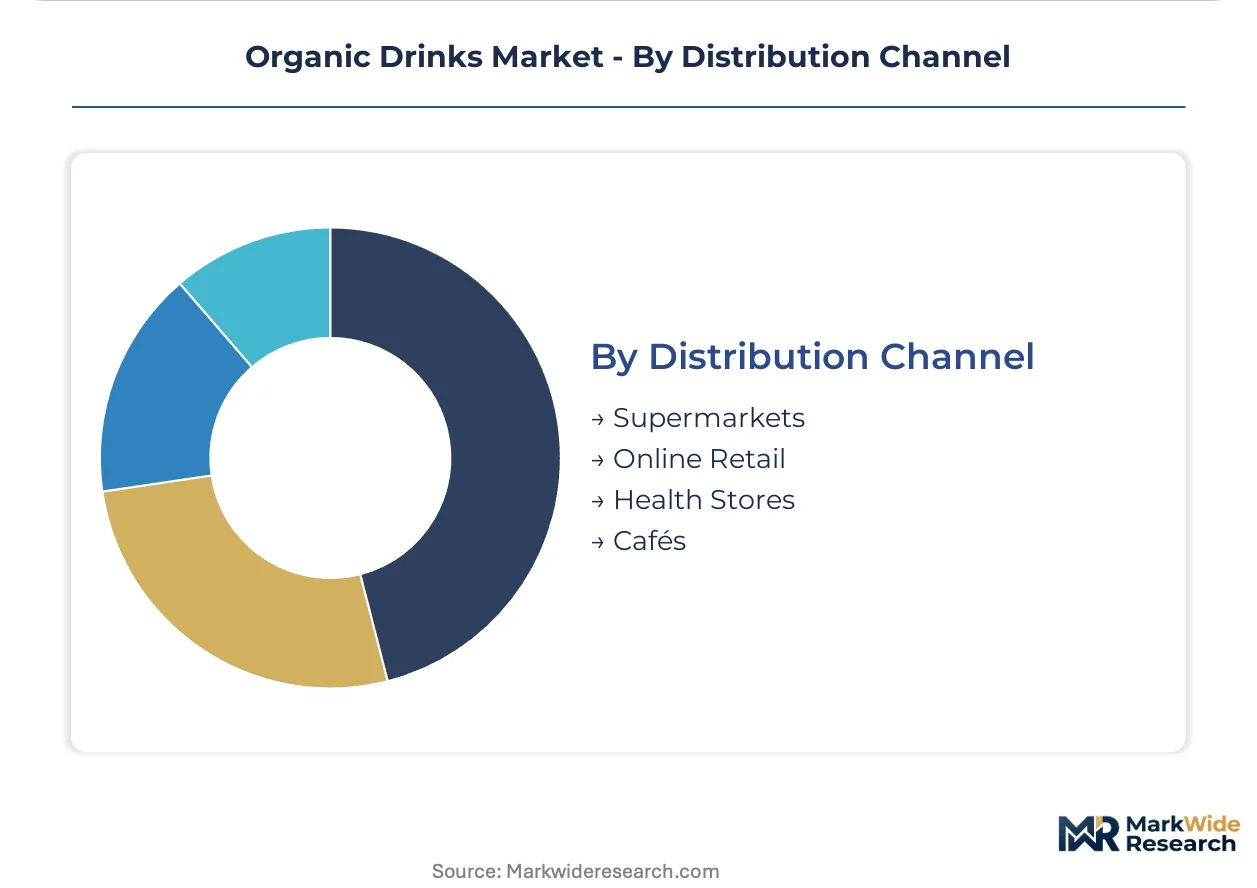
Distribution Channel:
Customer type fragmentation separates consolidated retail buyers with captive supply networks from fragmented hospitality and digital-native channels.
- Supermarkets:German organic retail consolidation concentrates procurement power into fewer accounts with stringent certification requirements. REWE's captive organic supply networks in Bavaria and Baden-Württemberg exemplify disintermediation pressure on traditional distributors.
- Online Retail:Direct-to-consumer subscription models absorb cold-chain complexity for HPP-treated juice brands, bypassing conventional retail slotting fee structures.
- Health Stores:Pharmacy and wellness channel placement demands adaptogenic formulation differentiation.
- Cafés:Specialty coffee chains require consistent supply reliability for menu-standardized organic beverage programs.
Supermarkets dominate volume throughput, with online retail expanding most quickly on subscription retention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing power through dense organic retail infrastructure, while the United States scales volume through mass-market distribution networks that prioritize cost efficiency over certification premiums.
Germany
REWE and dm-drogerie markt chains concentrate procurement through captive organic supply networks in Bavaria and Baden-Württemberg. The EU Green Deal Farm to Fork strategy tightens pesticide residue thresholds, forcing dual-certification investments from exporters. Berlin-Brandenburg hosts cold-pressed juice processors adopting high-pressure processing technology to extend clean-label shelf life.
United States
Specialty café chains and wellness hospitality buyers expand certified organic beverage menus, creating pull-through demand for adaptogenic formulations. The USDA National Organic Program governs ingredient sourcing standards, filtering smaller processors from national retail access. California's Central Valley organic farming clusters supply superfruit inputs to refrigerated juice processors facing cold-chain capex intensity.
France
Organic retail infrastructure outside Paris remains sparse, creating first-mover advantage for brands establishing direct-store-delivery relationships with regional cooperatives. EFSA pesticide residue benchmarks operate in parallel with EU Organic logo requirements. The Auvergne-Rhône-Alpes region shows emerging pharmacy-channel demand for cold-pressed vegetable blends.
United Kingdom
Consolidated supermarket buyers demand blockchain-enabled provenance tracking for berry and citrus supply chains. REACH chemical restrictions force liner material reformulation in aluminum can packaging. London's specialty hospitality sector drives premium positioning for kombucha and fermented tea categories.
Netherlands
Dutch organic beverage processors face steep compliance curves for bio-based barrier material substitution under EU Green Deal packaging mandates. Randstad logistics hubs support refrigerated distribution networks for high-pressure processed juices. Rotterdam's port infrastructure facilitates organic ingredient imports from Peruvian and Indian cooperatives.
Organic Drinks Market Competitive Environment
North American producers anchor mass-market scale through diversified beverage portfolios; European specialists hold premium positioning through certification-intensive supply chains. The vendor base separates into three tiers: multinational conglomerates with organic holdings, mid-cap private-label manufacturers, and cold-pressed specialists serving refrigerated sets. Two strategic archetypes dominate competitive dynamics: backward integration into captive organic ingredient supply, and direct procurement relationships that disintermediate traditional distributors. M&A activity concentrates among wellness hospitality targets, while capacity expansion focuses on high-pressure processing infrastructure.
Within the multinational tier, The Coca-Cola Company and PepsiCo, Inc. exemplify scale-driven portfolio diversification into organic-certified lines. Nestlé S.A. occupies a position bridging mass-market distribution with premium wellness positioning. Among specialists, Suja Life LLC and GT's Living Foods represent the cold-pressed and fermented beverage archetypes where supply reliability demands absorb buyer consolidation pressure. The Hain Celestial Group, Inc. anchors private-label manufacturing scale serving consolidated retail accounts with strict procurement protocols.
| Leading Market Players |
|---|
| The Hain Celestial Group, Inc. |
| Suja Life LLC |
| The Coca-Cola Company |
| Organic Valley |
| GT's Living Foods |
| PepsiCo, Inc. |
| Nestlé S.A. |
| Health-Ade Kombucha |
| Danone S.A. |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal Farm to Fork strategy gates both qualified supply and premium-tier pricing access, as compliance investments filter smaller processors from transatlantic distribution while locking in organic ingredient premiums for certified suppliers serving German REWE and dm-drogerie markt chains.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for HPP-treated refrigerated juices, compressing margin buffers for mid-cap processors unable to absorb cold-chain capex intensity. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified organic lines from single-jurisdiction alternatives and conventional beverages, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from weather-sensitive superfruit harvests in Peru and India, creating input cost volatility that squeezes refrigerated juice margins. Mass-market buyers exhibit highest price sensitivity, while German wellness hospitality chains accept premium positioning for adaptogenic formulations.
Supply Chain Analysis
Freight cost escalation across refrigerated distribution networks is forcing consolidation of organic ingredient procurement into Randstad logistics hubs and Rotterdam port infrastructure. Supply concentration centers on Peru and India for superfruit inputs, Germany and Italy for glass container manufacturing, and the Netherlands for HPP processing capacity. Raw material dependencies include organic berries from Peruvian cooperatives, adaptogenic herbs from Indian certified farms, and bio-based barrier films under EU Green Deal packaging mandates. Single-source vulnerability concentrates in Italian and German glass production clusters. Distribution runs through captive organic supply networks built by German retail consolidators, disintermediating traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with the EU Green Deal Farm to Fork strategy tightening pesticide residue thresholds and accelerating reformulation investments that lock in organic ingredient demand across European supply chains.
For Market Incumbents: Anchor premium positioning through backward integration into Peruvian and Ethiopian organic ingredient cooperatives, securing supply reliability against weather-driven price volatility. Invest in high-pressure processing capacity additions in Berlin-Brandenburg to defend margin buffers against cold-chain capex barriers filtering mid-cap competitors. Certification investment in dual USDA-EU compliance remains essential for transatlantic distribution access. For New Entrants and Emerging Players: Direct-to-consumer subscription models bypass conventional retail slotting fee structures and absorb cold-chain complexity for HPP-treated juice brands. Target underpenetrated French organic retail infrastructure outside Paris through direct-store-delivery relationships with regional cooperatives. Go-to-market leverage centers on adaptogenic formulation differentiation for German pharmacy and wellness channels. For Investors and Strategic Acquirers: Roll-up economics work for cold-pressed juice specialists with established HPP infrastructure because buyer consolidation among German organic retailers demands consistent supply reliability that fragmented processors cannot meet. Long-term viability over a multi-year horizon favors targets with captive organic ingredient relationships and dual-certification compliance. Watch blockchain-enabled provenance tracking adoption as inflection indicator for supply chain transparency premiums.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | Berlin-Brandenburg processors adopting HPP extend clean-label shelf life beyond regional proximity constraints. |
| Dual-Certification Compliance Investment | USDA-EU organic logo alignment filters smaller competitors from transatlantic distribution opportunities. |
| Direct-to-Consumer Subscription Launch | Digital-native brands bypass REWE and dm-drogerie markt slotting fee structures while retaining cold-chain control. |
| Adaptogenic Formulation Extension | Ashwagandha-reishi combinations command pharmacy-channel premiums in German wellness hospitality chains. |
| Circular Packaging Infrastructure | Deposit-return system participation in Denmark and Sweden aligns with EU Green Deal packaging mandates. |
Study Parameters
Coverage spans Germany, United States, France, United Kingdom, and Netherlands, with primary inputs from each market combining interviews with organic beverage brand managers, category buyers at German REWE and dm-drogerie markt chains, cold-chain logistics operators, and regulatory affairs specialists with secondary validation through EU Green Deal policy documents, USDA National Organic Program filings, EFSA pesticide residue databases, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down market sizing.
Granularity-level framing applies at product type, ingredient source, packaging format, and distribution channel dimensions, with additional modeling of certification tier and regional regulatory cluster effects. CAGRs derive from segment-level volume trajectories and pricing evolution assumptions across the projection horizon. Industry-specific forecast inputs include organic farming conversion timelines under USDA three-year land requirements and HPP technology adoption curves in German refrigerated juice processing.
The model assumes a particular technology adoption path for high-pressure processing; alternative pathways for thermal pasteurization would alter the outlook for nutrient claim positioning and clean-label shelf life extension. Forecasts reflect assumptions about EU Green Deal implementation pace and organic ingredient supply elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Juice Market