
 Brazil Organic Food Market | 2026-2036
Brazil Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Organic Food Market Intelligence
Certified agronomist talent is bifurcating the competitive landscape between established operators and emerging cooperatives. Korin leverages its integrated poultry and grain operations to secure consistent organic feed supplies. Mae Terra anchors the packaged organic segment through deep retail penetration across Brazilian supermarket chains. Unilever Group competes via its sustainability-linked procurement standards that favor certified organic sourcing.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, relying instead on composting, crop rotation, and biological pest control to maintain soil fertility and ecological balance. The primary commercial purpose is to supply consumers with residue-minimized nutrition while preserving long-term agricultural land viability. Fruits and vegetables dominate current revenue as the most established organic categories with mature certification infrastructure. Online sales channels represent the fastest-growing distribution pathway, driven by subscription box models and direct-to-consumer logistics investments. Health-conscious consumers concentrate the highest margin pool, particularly in metropolitan corridors where willingness-to-pay premiums for certified organic labels remains strongest.
ANVISA governs organic product registration and labeling standards, while the Ministry of Agriculture enforces farm-level certification audits through accredited third-party bodies. These frameworks shape market access by requiring full traceability documentation and prohibiting conventional-to-organic transition products from carrying certified labels. Stakeholders must monitor pending regulatory revisions around pesticide residue thresholds and carbon accounting requirements that could reshape compliance costs and competitive positioning across Brazilian states.
Market Dynamics
ANVISA's tightened organic certification protocols are compressing the transition timeline for conventional-to-organic conversion, forcing operators to front-load compliance investments before accessing premium pricing tiers. Smallholder cooperatives in Minas Gerais leverage technical assistance programs to accelerate audit readiness, while established vertically integrated players absorb traceability costs through captive supply chains.
Growth Catalysts
- ANVISA Protocol Harmonization:Unified national standards reduce state-level regulatory fragmentation, enabling cross-border organic equivalency agreements with Mercosur trading partners.
- Subscription Logistics Infrastructure:Cold-chain last-mile investments by São Paulo-based direct-to-consumer platforms reduce spoilage rates for organic produce deliveries to metropolitan households.
- Soil Microbiome Analytics:On-farm biological testing kits allow cooperatives to document ecological compliance ahead of third-party audits, shortening certification cycles.
Market Restraints
- Organic Feed Input Volatility:Domestic non-GMO soybean and corn supply fluctuations force poultry and dairy operators to import certified feed at elevated landed costs.
- Accredited Auditor Concentration:Brazil's Ministry of Agriculture recognizes fewer than twelve third-party certification bodies, creating audit scheduling bottlenecks during peak harvest windows.
- Conventional Price Arbitrage:Unlabeled transitional produce from farms in conversion years competes at price points 40% below certified organic equivalents in informal retail channels.
Strategic Opportunities
- Amazon Biome Regenerative Conversion:Degraded pasturelands in Pará and Mato Grosso qualify for carbon-credit-linked organic transition financing under pending federal agroecology incentives.
- Pharmaceutical-Grade Organic Ingredients:ANVISA's expanded residue threshold definitions open export pathways for Brazilian organic botanicals into European nutraceutical supply chains.
- Retail Media Network Integration:Supermarket chains deploy purchase-data targeting to convert conventional fresh-produce shoppers into organic category entrants through personalized promotion algorithms.
Industry Challenges
- Agronomist Certification Scarcity:Brazil's federal agronomy council reports insufficient accredited professionals to supervise the required conversion-acreage expansion under ANVISA's 2024 audit intensity rules.
- Legacy Traceability System Migration:Paper-based farm-record systems in family-operated cooperatives require capital-intensive digitization to meet real-time supply-chain visibility mandates from export buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Organic Food Market |
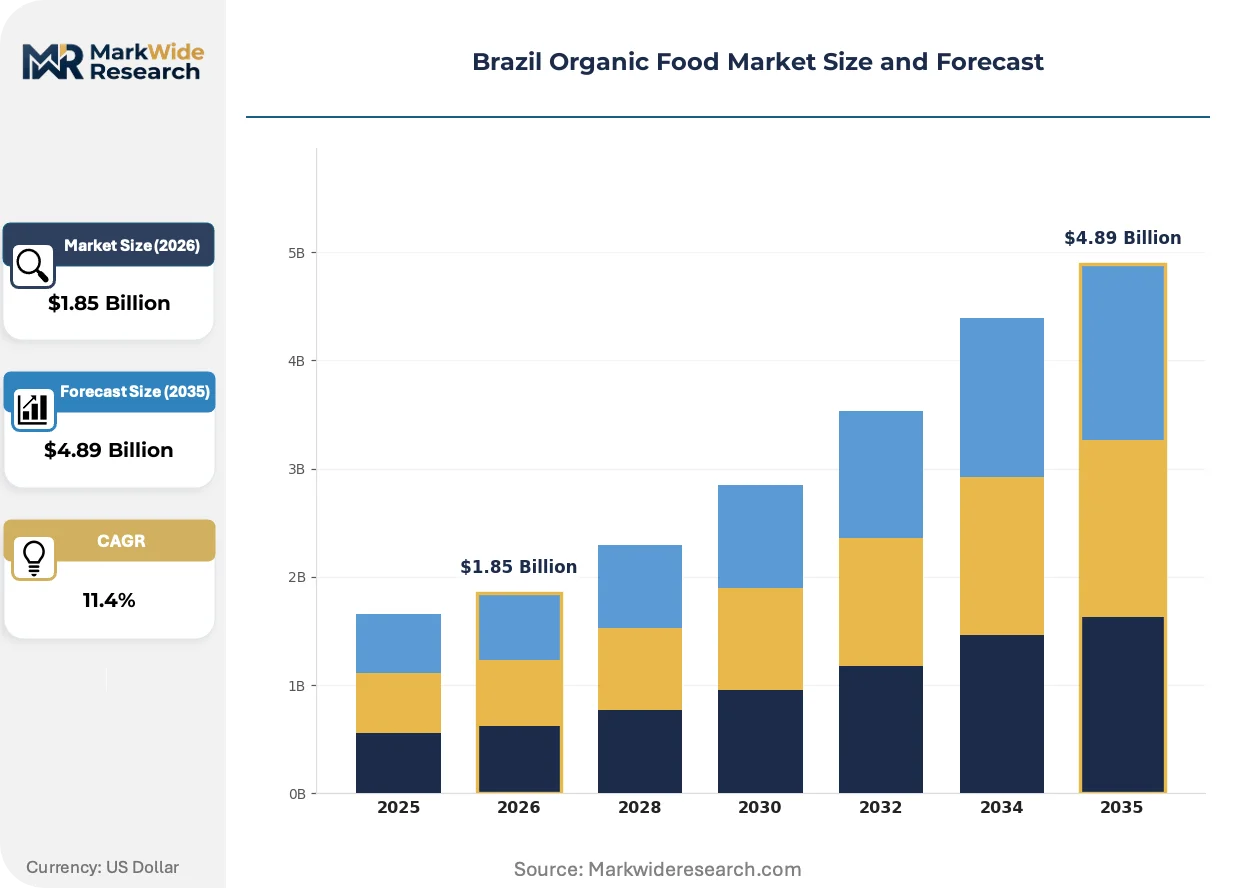
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Retail Stores, Online Sales, Direct Farm Sales, Supermarkets Customer Type: Health-Conscious Consumers, Eco-Conscious Buyers, Families, Vegetarians Packaging Type: Biodegradable, Recyclable, Glass, Paper |
| Companies Covered | Mae Terra, Granja Mantiqueira, M Dias Branco SA Indústria & Comércio de Alimentos, Raizs, Jasmine, Unilever Group, Korin, Nuu, Nestle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Organic Food Market Strategic Shifts & Innovations
Digital verification infrastructure and biological input substitution are compressing the cost gap between organic and conventional production systems. These shifts reshape competitive positioning across Brazil's fragmented supplier base.
Blockchain-enabled batch tracking is displacing paper-based chain-of-custody documentation in export-oriented cooperatives. Minas Gerais grain and coffee operators deploy distributed-ledger systems to satisfy European retailer provenance requirements. This technology is displacing legacy audit sampling methods with continuous automated verification, reducing certification compliance labor hours by enabling remote inspector access to immutable field records.
ANVISA's pending pesticide residue threshold revisions tighten maximum allowable limits for 47 synthetic compounds in processed organic products. The regulation forces reformulation investments among packaged food manufacturers currently relying on transitional ingredient sourcing. São Paulo-based dairy processors face the steepest compliance timelines, with 18-month reformulation windows to secure revised product registrations before enforcement begins.
Health-conscious households in Brazil's southeastern metropolitan corridors now prioritize subscription-based organic produce boxes over supermarket aisle purchasing. Direct-to-consumer platforms capture recurring revenue through curated seasonal offerings that bypass retail margin stacking. Rio de Janeiro and Belo Horizonte demonstrate the highest subscription penetration, where dual-income professional households value time savings alongside residue-minimized nutrition claims.
Brazil Organic Food Market Segmentation
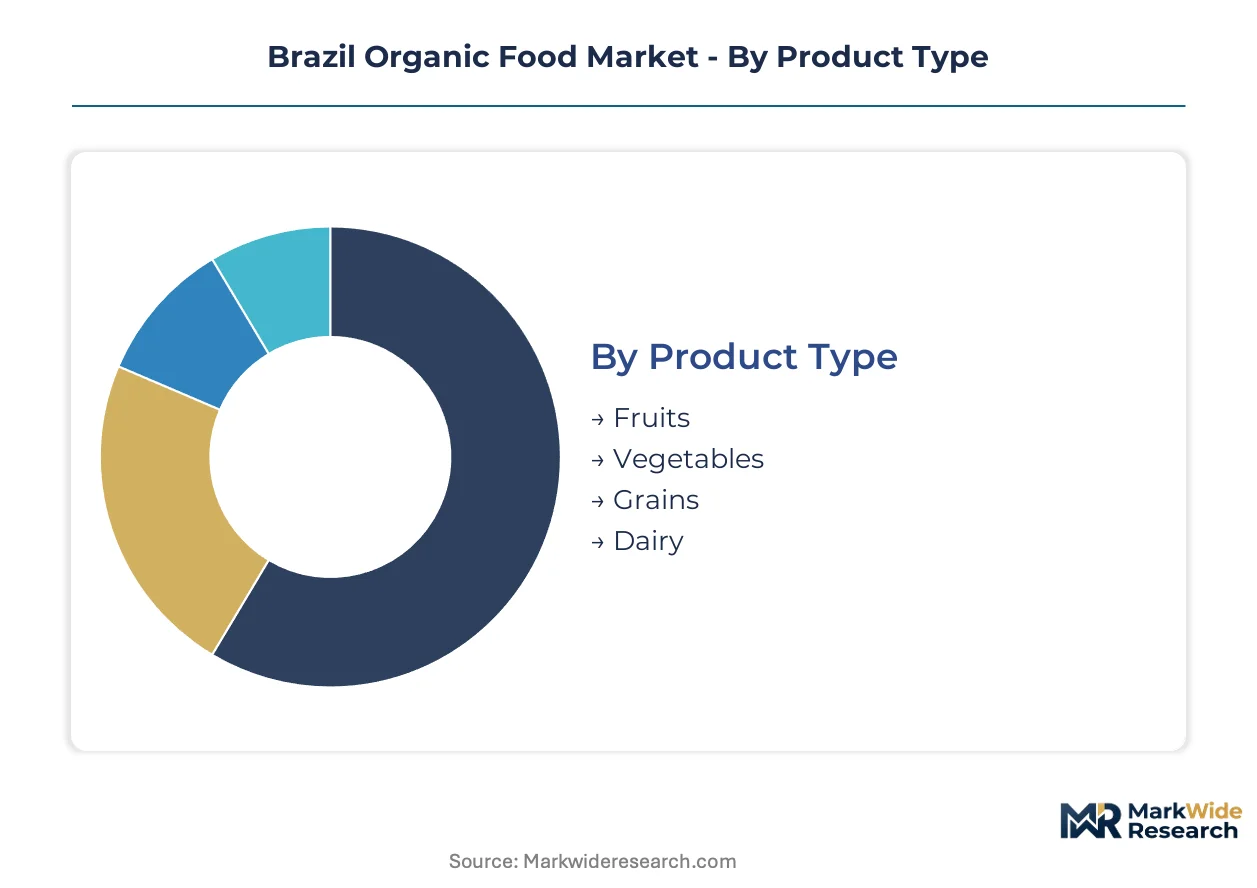
Segmentation in Brazil's organic food market reveals how certification requirements, channel access, and consumer willingness-to-pay premiums fragment commercial opportunity. Understanding these divisions exposes where ANVISA compliance costs concentrate and which buyer clusters justify traceability investments.
Product Type:
Channel mix varies sharply by product perishability and certification maturity, with fresh categories dominating direct-to-consumer platforms while packaged goods anchor supermarket penetration.
- Fruits:Tropical and temperate varieties with established organic certification infrastructure. São Paulo metropolitan households drive premium demand through subscription box services, constrained by cold-chain spoilage rates in last-mile delivery.
- Vegetables:Leafy greens and root vegetables requiring rapid harvest-to-retail turnaround. Minas Gerais cooperatives concentrate supply, leveraging technical assistance programs to accelerate audit readiness under tightened ANVISA protocols.
- Grains:Non-GMO corn and soybeans supplying domestic organic feed markets. Price volatility in domestic supply forces poultry and dairy operators toward import substitution at elevated landed costs.
- Dairy:Milk, cheese, and yogurt with 18-month reformulation timelines under pending residue threshold revisions. São Paulo processors face compressed compliance windows to secure revised ANVISA product registrations.
By volume, Fruits leads. By expansion trajectory, Dairy climbs fastest as residue-minimized nutrition claims penetrate metropolitan professional households.
Distribution Channel:
Margin capture differs dramatically by channel control, with vertically integrated operators extracting premium pricing through direct relationships while retail intermediaries compress producer margins.
- Retail Stores:Neighborhood organic shops and specialty grocers with curated local supplier relationships. Belo Horizonte and Rio de Janeiro clusters demonstrate highest penetration among health-conscious urban corridors.
- Online Sales:Subscription-based direct-to-consumer platforms with recurring revenue models. Cold-chain logistics investments by São Paulo-based operators reduce spoilage rates for produce deliveries to metropolitan households.
- Direct Farm Sales:On-farm pickup and farmers market transactions bypassing retail margin stacking. Minas Gerais cooperatives leverage this channel to build consumer trust ahead of third-party audit cycles.
- Supermarkets:National chains with private-label organic lines and sustainability-linked procurement standards. Purchase-data targeting converts conventional fresh-produce shoppers through personalized promotion algorithms.
Supermarkets command the largest revenue base. Online Sales gains share fastest through subscription retention economics.
Customer Type:
Price elasticity and certification literacy separate buyer clusters, with professional households absorbing premiums while price-sensitive segments gravitate toward transitional or unlabeled produce.
- Health-Conscious Consumers:Dual-income metropolitan households prioritizing residue-minimized nutrition claims. This cluster concentrates in southeastern corridors where willingness-to-pay premiums for certified organic labels remains strongest.
- Eco-Conscious Buyers:Purchase decisions integrating carbon footprint and biodiversity impact alongside personal health. Pending federal agroecology incentives for Amazon Biome regenerative conversion align with this segment's values.
- Families:Multi-person households with volume purchasing patterns and price sensitivity to conventional organic spreads. Supermarket promotional cycles and bulk packaging formats capture this demand.
- Vegetarians:Dietary restriction driving organic protein and dairy alternatives. Specialized retail and online platforms serve this niche with curated seasonal offerings.
Health-Conscious Consumers anchor revenue contribution. Eco-Conscious Buyers expand most quickly as carbon-credit-linked organic transition financing matures.
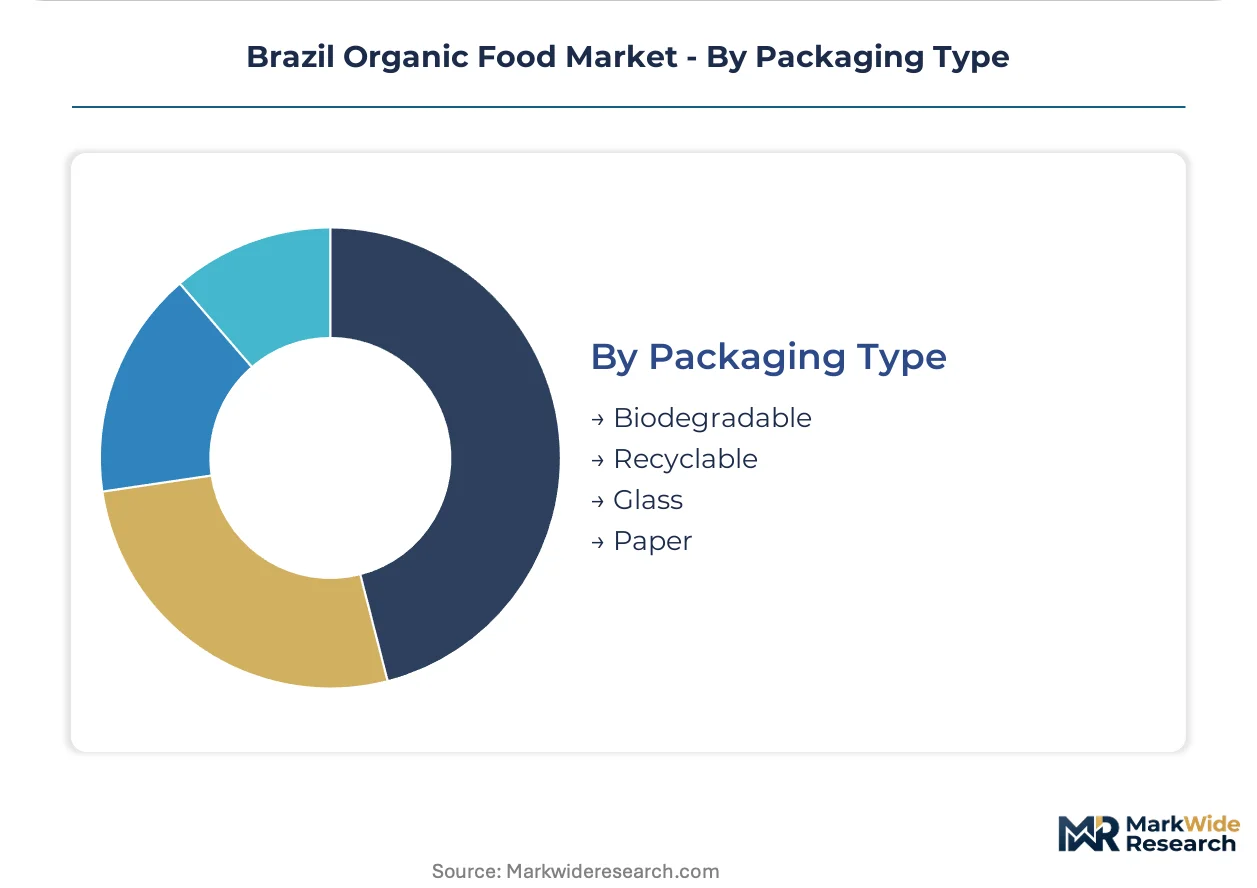
Packaging Type:
Sustainability credentials in packaging materials increasingly influence retailer procurement standards and export market access, particularly for European destination markets.
- Biodegradable:Compostable films and containers derived from plant-based polymers. ANVISA's expanded residue threshold definitions create compliance complexity for biodegradable packaging in contact with processed organic products.
- Recyclable:Multi-material packaging meeting municipal recycling stream requirements. Supermarket chains favor this format for private-label organic lines targeting mainstream consumer transition.
- Glass:Inert containers for dairy and premium preserves with reuse potential. Higher logistics costs limit distribution radius to metropolitan clusters with established return infrastructure.
- Paper:Fiber-based packaging for dry goods and produce with moisture barrier limitations. Minas Gerais grain operators deploy this format for European export shipments satisfying retailer provenance requirements.
Recyclable formats dominate unit volume. Biodegradable alternatives gain adoption fastest under sustainability-linked procurement standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in southeastern metropolitan corridors while conversion-cost pressures dominate northern and central agricultural zones. This asymmetry shapes investment allocation across state-level organic certification pipelines.
São Paulo
Dual-income professional households drive subscription box demand for residue-minimized dairy and fresh produce. ANVISA's tightened protocols compress reformulation timelines for São Paulo-based processors seeking revised product registrations. Cold-chain logistics operators in the metropolitan region reduce spoilage rates through direct-to-consumer platform investments.
Minas Gerais
Smallholder cooperatives leverage technical assistance programs to accelerate audit readiness under intensified federal inspection rules. The Ministry of Agriculture's accredited third-party certification bodies concentrate audit scheduling capacity in this grain and coffee production zone. Belo Horizonte's retail clusters demonstrate highest organic shop penetration among health-conscious urban corridors.
Rio de Janeiro
Metropolitan households exhibit strongest subscription penetration for curated seasonal produce offerings bypassing retail margin stacking. ANVISA's pending residue threshold revisions force reformulation investments among packaged food distributors serving this consumer base. Neighborhood specialty grocers build curated supplier relationships with Minas Gerais cooperatives.
Pará
Degraded pasturelands qualify for carbon-credit-linked organic transition financing under pending federal agroecology incentives. The Amazon Biome's regenerative conversion potential attracts eco-conscious buyer segment alignment. Land tenure regularization programs intersect with organic certification requirements to shape operator entry timelines.
Rio Grande do Sul
Traditional farming cooperatives face capital-intensive digitization demands to meet real-time supply-chain visibility mandates from export buyers. Paper-based farm-record systems require migration to blockchain-enabled batch tracking for European retailer provenance compliance. Southern port infrastructure supports grain export logistics for Mercosur equivalency agreements.
Brazil Organic Food Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Brazil's organic food sector. Vertically integrated poultry and grain operators secure captive feed supplies while packaged food specialists anchor retail penetration through supermarket chain relationships. Three archetypes dominate: integrated agricultural conglomerates with in-house organic feed production, cooperative-based federations leveraging technical assistance scale, and multinational consumer goods groups with sustainability-linked procurement standards. Competitive moves concentrate on traceability system digitization and strategic partnerships with direct-to-consumer logistics platforms.
Among domestic operators, Mae Terra exemplifies the packaged organic segment archetype through deep retail channel presence. Korin occupies a position representing integrated poultry and grain operations with captive organic feed supply control. Unilever Group anchors the multinational tier competing via sustainability-linked sourcing standards that favor certified organic procurement. These three players illustrate how certification compliance investments and channel control separate market positions.
| Leading Market Players |
|---|
| Mae Terra |
| Granja Mantiqueira |
| M Dias Branco SA Indústria & Comércio de Alimentos |
| Raizs |
| Jasmine |
| Unilever Group |
| Korin |
| Nuu |
| Nestle |
| Others |
Cost & Logistics Intelligence
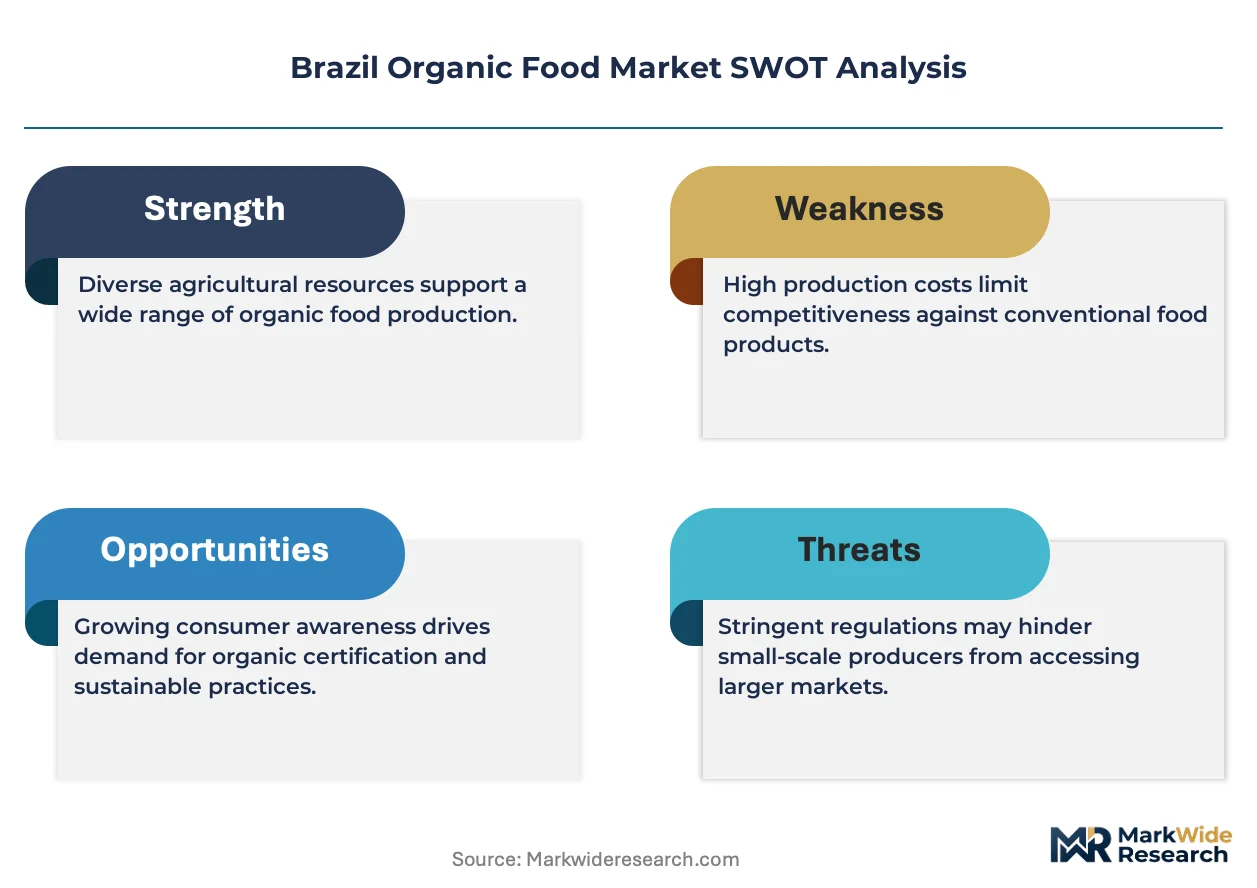
ANVISA's organic certification protocols gate both supply qualification and price differentiation simultaneously, forcing operators to absorb compliance costs before accessing premium pricing tiers while transitional produce without certification competes at steep discounts in informal channels.
Pricing Analysis
São Paulo metropolitan households absorb the steepest organic premiums while Pará and Mato Grosso conversion zones trade at narrower spreads above conventional benchmarks. Three-tier pricing structure across certified organic, transitional, and conventional levels reflects audit intensity and residue documentation completeness. Price differentiation centers on certification grade and cold-chain logistics investment, with subscription-based direct-to-consumer platforms capturing recurring revenue at elevated price points. Cost compression in dairy processing is intensifying because São Paulo-based operators face compressed reformulation timelines under pending residue threshold revisions.
Supply Chain Analysis
Brazil and Argentina anchor South American organic grain and feed production, with Uruguay contributing specialized beef and dairy supply. Domestic non-GMO soybean and corn supply fluctuations force poultry and dairy operators toward import substitution at elevated landed costs. Supply chain risk concentrates in accredited auditor scarcity, with fewer than twelve Ministry of Agriculture-recognized certification bodies creating audit scheduling bottlenecks during peak harvest windows. Distribution runs through supermarket chains with private-label organic lines, direct-to-consumer subscription platforms, and cooperative-based direct farm sales to metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's organic food market is emerging from a regulatory-intensity cycle as ANVISA protocol harmonization stabilizes compliance timelines and subscription logistics infrastructure matures across southeastern metropolitan corridors.
For Market Incumbents: Shield margin position by accelerating blockchain-enabled batch tracking deployment ahead of European retailer provenance mandates, and deepen backward integration into captive organic feed production to offset input volatility threatening poultry and dairy operations. For New Entrants and Emerging Players: Lead with carbon-credit-linked organic transition financing in Pará's degraded pasturelands, where pending federal agroecology incentives create first-mover advantage among eco-conscious buyer segments, and anchor go-to-market through subscription box partnerships with São Paulo logistics platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dairy processing and cold-chain logistics as ANVISA reformulation timelines compress, favoring acquisition targets with established ANVISA product registrations and direct-to-consumer channel control; watch for subscription retention rate inflection as the signal distinguishing sustainable revenue models from promotional-dependent operations.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Minas Gerais cooperatives satisfy European retailer provenance requirements through distributed-ledger documentation systems. |
| Subscription Logistics Infrastructure | São Paulo-based platforms reduce organic produce spoilage rates through metropolitan cold-chain last-mile investments. |
| Carbon-Credit-Linked Transition Financing | Pará pastureland operators access federal agroecology incentives for Amazon Biome regenerative organic conversion. |
| ANVISA Product Registration Acceleration | Dairy processors secure revised residue threshold compliance ahead of enforcement windows in southeastern markets. |
| Cooperative Technical Assistance Scaling | Minas Gerais federations leverage audit readiness programs to compress certification cycles under intensified federal inspection rules. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with cooperative agronomists, supermarket category buyers, cold-chain logistics operators, and ANVISA regulatory affairs specialists; and secondary validation through Ministry of Agriculture certification body records, ANVISA product registration databases, customs trade data for organic feed imports, and cooperative financial disclosures. Bottom-up triangulation across state-level production estimates and top-down reconciliation against national retail audit data anchored volume and value assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, distribution channel, customer archetype, and packaging format, with regional variation in certification pipeline maturity and metropolitan demand concentration. CAGRs were derived from regression-based trend extrapolation calibrated to historical conversion-acreage expansion and subscription penetration trajectories, incorporating ANVISA protocol revision timelines and cold-chain infrastructure investment cycles as industry-specific forecast inputs.
Forecasts assume regulatory continuity in ANVISA organic certification regimes and Ministry of Agriculture audit intensity rules; material policy shifts around pesticide residue thresholds or carbon accounting requirements would require re-modeling. Specific risks include accredited auditor capacity constraints, feed input price volatility, and subscription retention rate deterioration. Recalibration cycles align with material shifts in ANVISA enforcement timelines and federal agroecology incentive program implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Australia Organic Food Market