
 Non-GMO Food Products Market | 2026-2036
Non-GMO Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Food Products Market Analytics
Non-GMO Project Verified certification is collapsing the supplier base into a smaller pool of qualified manufacturers. Amy's Kitchen sustains its market position through deep vertical integration in organic frozen meals. The Hain Celestial Group differentiates via broad portfolio coverage across dairy alternatives and infant nutrition. Cargill leverages its grain origination networks to secure identity-preserved non-GMO supply chains from farm to processor.
Non-GMO food products exclude ingredients derived from genetically modified organisms through controlled sourcing and testing protocols, with thresholds typically set at 0.9% adventitious presence for compliance. These products serve consumers seeking transparency in agricultural biotechnology and supply chain traceability. Beverages and snacks command disproportionate shelf space growth as convenience-oriented health-conscious consumers expand their purchasing. The certification type dimension shows Non-GMO Project Verified and USDA Organic labels increasingly appearing together, concentrating margin pools with dual-certified suppliers who absorb higher audit costs.
The FDA enforces bioengineered food disclosure standards under the National Bioengineered Food Disclosure Standard, while USDA Organic regulations prohibit GMO ingredients entirely, creating overlapping but distinct compliance frameworks. The Non-GMO Project operates as a private verification body with stricter testing protocols than federal minimums, shaping retailer procurement criteria. Stakeholders must monitor evolving state-level labeling initiatives and retailer-specific non-GMO commitments that could fragment compliance requirements beyond federal baselines.
Market Dynamics
Retail procurement criteria are hardening around dual certification requirements, compressing margins for single-certified suppliers while concentrating volume with manufacturers capable of absorbing layered audit costs for Non-GMO Project Verified and USDA Organic standards simultaneously.
Growth Catalysts
- USDA Organic regulations:The prohibition of GMO ingredients under federal organic standards creates a built-in non-GMO consumer base that requires no additional marketing expenditure to activate.
- Beverage and snack manufacturers:These convenience-oriented categories are expanding shelf space allocations for verified non-GMO lines faster than center-store staples, pulling ingredient demand through the supply chain.
- California retail clusters:Concentrated premium purchasing in Pacific Coast metropolitan markets establishes price benchmarks that validate non-GMO premiums for national rollout.
Market Restraints
- Identity-preserved grain premiums:Non-GMO corn and soybean inputs trade at persistent premiums to commodity benchmarks, compressing processor margins when retail price elasticity limits pass-through.
- Testing laboratory concentration:The limited number of ISO-accredited facilities capable of 0.9% adventitious presence testing creates bottlenecks during peak harvest verification windows.
- Cross-contamination protocols:Dedicated handling infrastructure requirements at elevators and processing facilities impose capital burdens that exclude smaller regional operators from certification eligibility.
Strategic Opportunities
- USDA Bioengineered Food Disclosure Standard:Federal mandatory disclosure rules create consumer education moments that drive incremental demand toward explicitly non-GMO labeled alternatives.
- Foodservice direct sourcing:Restaurant chains and institutional buyers are developing captive non-GMO supply agreements that bypass traditional retail distribution markups.
- Blockchain-enabled traceability:Integration of distributed ledger systems with existing certification protocols offers real-time provenance verification that commands additional shelf price premiums.
Industry Challenges
- Auditor capacity constraints:The limited pool of Non-GMO Project-trained inspectors creates certification backlogs that delay product launches and inventory rotations.
- Legacy ERP integration:Existing enterprise systems at mid-sized food manufacturers require expensive customization to track lot-level identity preservation through multi-step processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Food Products Market |
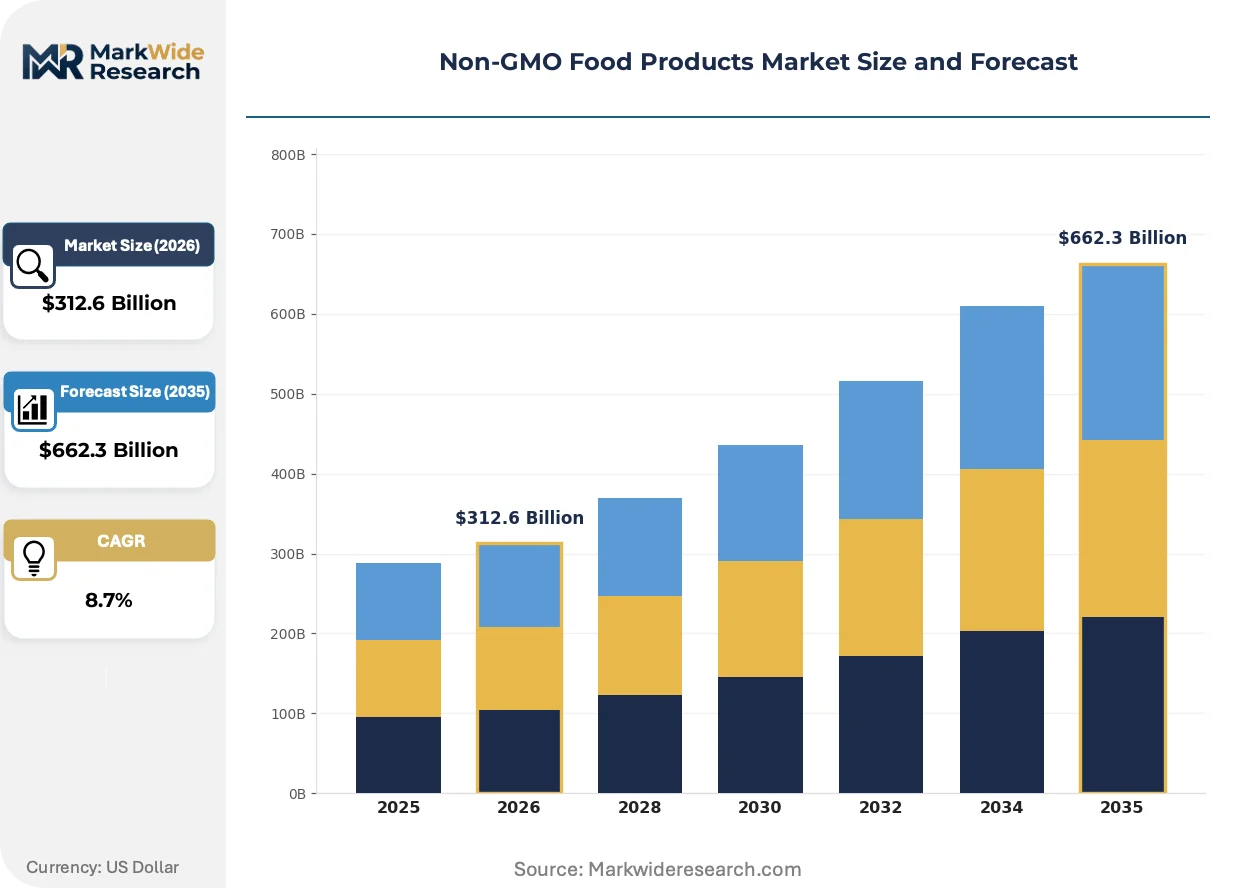
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Dairy, Grains Consumer Segment: Health-Conscious Consumers, Families, Organic Shoppers, Environmentally-Conscious Buyers Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops Certification Type: USDA Organic, Non-GMO Project Verified, Gluten-Free, Vegan |
| Companies Covered | Amy's Kitchen, United Natural Foods, The Hain Celestial Group, Organic Valley, Clif Bar & Company, Cargill, Danone, Nature's Path Foods, Blue Diamond Growers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Food Products Market Evolving Landscape
Verification technologies and procurement protocols are converging to compress the time and cost required to maintain non-GMO chain of custody, while regulatory disclosure mandates reshape how manufacturers communicate biotechnology content to consumers.
Blockchain-based supply chain tracking is miniaturizing the verification burden for identity-preserved grains. Mid-sized regional processors are adopting distributed ledger systems at accelerating pace. This technology is miniaturizing audit costs while enabling real-time contamination alerts that protect certified inventory pools.
The FDA's National Bioengineered Food Disclosure Standard mandates standardized biotechnology content labeling on packaged foods. Manufacturers must reformulate or relabel to maintain competitive positioning against explicit non-GMO claims. The standard most affects processed food categories where ingredient biotechnology status was previously ambiguous to consumers.
Direct-to-retailer certification is displacing distributor-mediated verification for private label non-GMO lines. Grocery chains are establishing their own supplier qualification protocols that exceed baseline federal requirements. This pattern concentrates most visibly in Pacific Northwest metropolitan markets where retailer-specific non-GMO commitments have fragmented procurement standards beyond federal baselines.
Non-GMO Food Products Market Segmentation
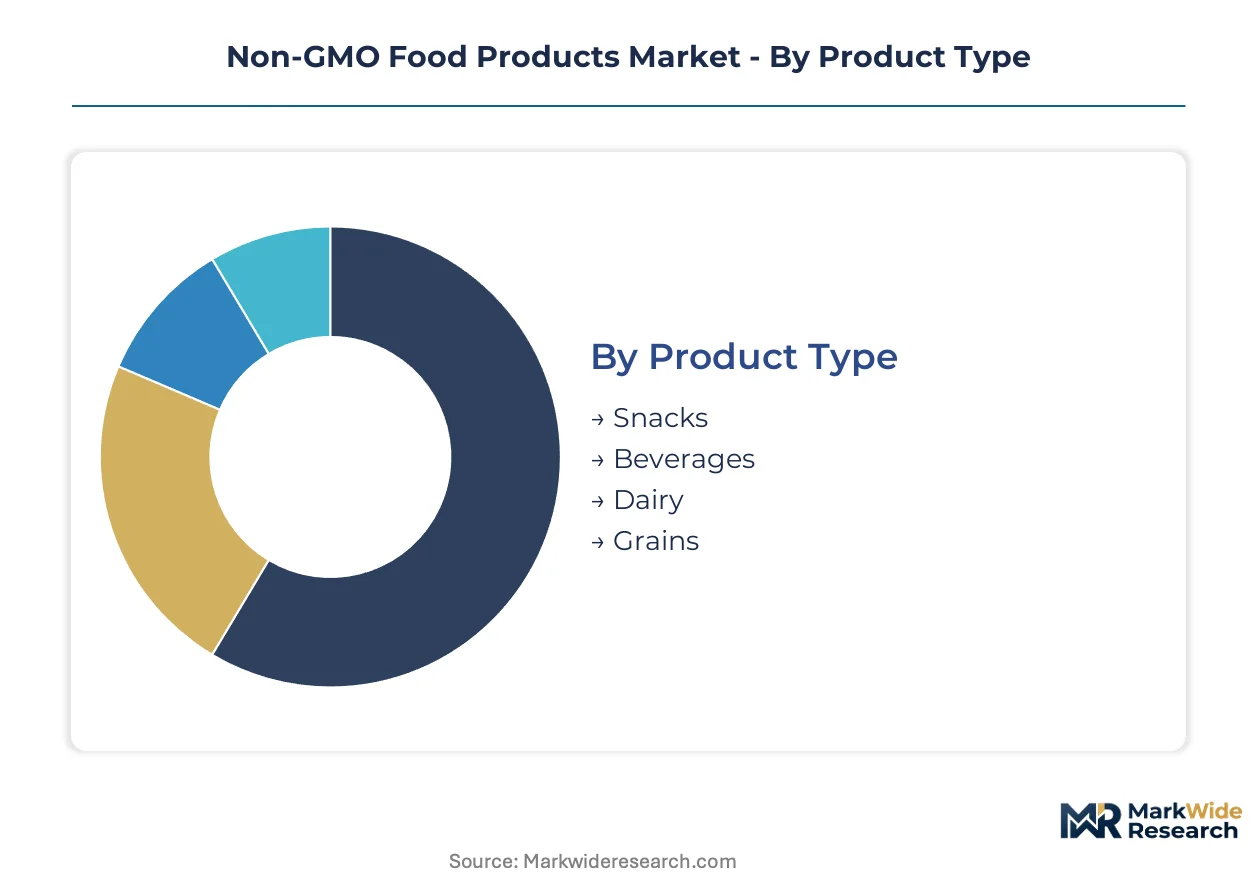
Segmentation in the non-GMO food products market reveals how certification costs and distribution access create divergent margin structures. Manufacturers must navigate distinct compliance burdens and channel economics across product categories and buyer types.
Product Type:
Margin pools concentrate in categories where convenience premiums overlap with health positioning, creating pricing power that offsets identity-preserved input costs.
- Beverages:Functional drinks and plant-based milks command shelf space expansion as retailers chase health-conscious convenience seekers. California metropolitan clusters validate premium pricing that processors struggle to replicate in grains.
- Snacks:Bars, chips, and puffed formulations absorb non-GMO corn and soybean premiums more easily than commodity categories due to impulse purchase dynamics and brand loyalty. Pacific Northwest retail density supports regional-to-national rollout patterns.
- Dairy:Milk, yogurt, and cheese alternatives face compressed margins from conventional dairy price benchmarks despite non-GMO feed requirements for animal-derived products.
- Grains:Rice, quinoa, and ancient wheat varieties serve ingredient buyers and direct consumers with limited pricing power against commodity substitutes.
The dominant share belongs to Beverages, while Snacks is closing the gap fastest.
Consumer Segment:
Volume concentration tracks dual-certification purchasing, where buyers willing to pay layered premiums for USDA Organic plus Non-GMO Project Verified labels drive supplier qualification decisions.
- Organic Shoppers:This cohort already accepts price premiums and requires no additional education on biotechnology transparency, delivering the highest lifetime value per customer. FDA disclosure mandates reinforce their existing purchasing patterns.
- Health-Conscious Consumers:Fitness-oriented buyers prioritize protein content and clean labels over strict non-GMO adherence, creating a bridge segment for single-certified products.
- Families:Households with children show elevated concern for infant nutrition and snack safety, driving trial in dairy and grain categories.
- Environmentally-Conscious Buyers:Sustainability-motivated purchasers respond to non-GMO claims as proxies for broader agricultural practice concerns, though price elasticity limits penetration.
Organic Shoppers hold the largest wallet share, though Health-Conscious Consumers are expanding most quickly as fitness culture mainstreams.
Distribution Channel:
Channel economics separate by certification handling costs, with direct retailer relationships capturing margin that distributor intermediation erodes.
- Supermarkets:Mass retail chains are expanding private label non-GMO lines with proprietary supplier protocols that exceed federal baselines, concentrating volume with manufacturers capable of direct certification relationships.
- Online Retail:E-commerce platforms enable subscription models for non-GMO pantry staples, reducing customer acquisition costs for repeat-purchase categories like grains and snacks.
- Health Food Stores:Specialty retailers maintain strict dual-certification requirements that filter out smaller regional processors lacking audit capacity.
- Specialty Shops:Independent grocers and farmers markets serve as trial channels for emerging brands before supermarket scale-up.
Supermarkets command the volume lead, while Online Retail is gaining share fastest through subscription loyalty mechanics.
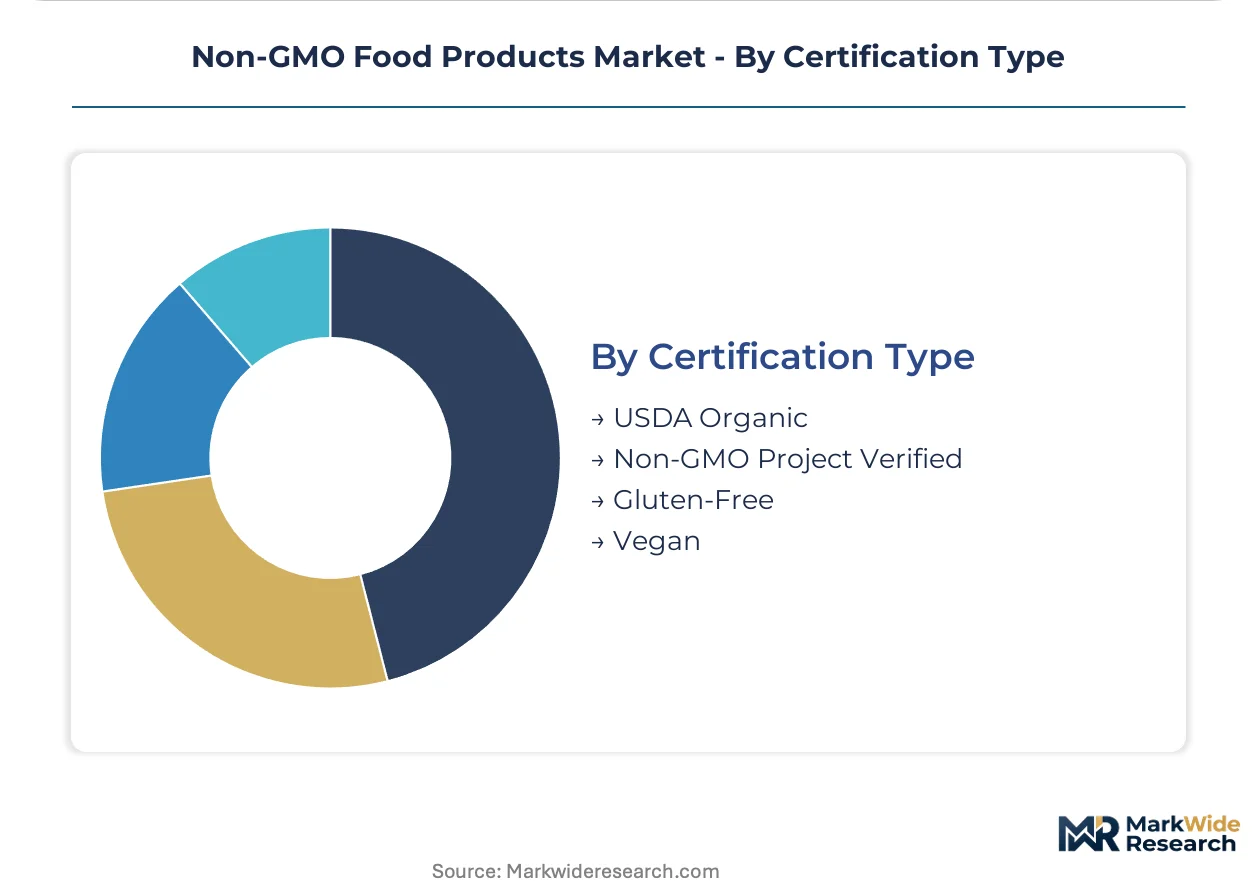
Certification Type:
Compliance layering determines supplier viability, with dual-certified manufacturers capturing margin pools that single-certified competitors cannot access.
- Non-GMO Project Verified:Third-party verification with stricter testing protocols than federal minimums shapes retailer procurement criteria and commands shelf price premiums through consumer trust.
- USDA Organic:Federal prohibition of GMO ingredients creates a built-in non-GMO consumer base requiring no additional marketing expenditure, though audit costs remain substantial.
- Gluten-Free:Celiac and sensitivity-driven demand overlaps partially with non-GMO purchasing, creating niche positioning for grain-based products.
- Vegan:Plant-based positioning attracts environmentally-motivated buyers but does not inherently guarantee non-GMO status without additional certification.
Non-GMO Project Verified maintains the premium position, yet USDA Organic is climbing fastest as federal disclosure rules drive consumers toward established organic labels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium non-GMO purchasing concentrates in coastal metropolitan clusters where health-conscious consumers accept layered certification premiums. United States households drive the highest per-capita expenditure on dual-certified products. European regulatory frameworks accelerate comparable demand patterns across northern member states.
United States
California and Pacific Northwest retail clusters validate premium non-GMO pricing that processors replicate nationally. The FDA enforces bioengineered food disclosure standards under the National Bioengineered Food Disclosure Standard. Seattle and Portland metropolitan areas sustain the densest concentration of dual-certified private label lines.
Canada
Health Canada maintains strict biotechnology approval protocols that reinforce consumer preference for verified non-GMO alternatives. The Canadian Food Inspection Agency coordinates with provincial regulators on organic and non-GMO claim verification. Toronto and Vancouver retail networks expand shelf space for identity-preserved grain products faster than prairie markets.
Germany
Discerning consumers in metropolitan regions reject bioengineered ingredients despite EU-wide authorization frameworks. EFSA guidance on novel food assessments shapes retailer procurement criteria for imported non-GMO lines. Berlin and Hamburg organic retail density supports premium positioning for Project Verified imports.
France
ANSES maintains precautionary biotechnology evaluations that align with consumer skepticism toward GMO cultivation. The country's national agricultural regulator enforces traceability requirements that favor identity-preserved supply chains. Paris and Lyon metropolitan clusters concentrate demand for non-GMO dairy and infant nutrition categories.
United Kingdom
Post-Brexit regulatory autonomy enables stricter biotechnology labeling than EU baseline requirements. The Food Standards Agency consults on precision breeding distinctions that heighten consumer awareness of non-GMO alternatives. London and Southeast England retail channels lead private label non-GMO expansion.
Non-GMO Food Products Market Competitive Landscape
Player mix skews toward diversified food conglomerates with captive organic supply chains and specialized organic manufacturers with deep certification expertise. Mid-sized regional processors struggle to absorb layered audit costs for dual certification, compressing viable participants. Three archetypes dominate: vertically integrated organic specialists, grain-origination multinationals with identity-preserved infrastructure, and portfolio-diversified health food conglomerates. Competitive moves center on direct-to-retailer certification relationships and blockchain-enabled traceability investments that command shelf price premiums.
Among diversified health food conglomerates, The Hain Celestial Group and Danone occupy positions spanning dairy alternatives and infant nutrition. Amy's Kitchen exemplifies the vertically integrated specialist archetype with in-house production of organic frozen meals. Cargill anchors the grain-origination tier, leveraging upstream control over identity-preserved non-GMO supply chains from farm to processor.
| Leading Market Players |
|---|
| Amy's Kitchen |
| United Natural Foods |
| The Hain Celestial Group |
| Organic Valley |
| Clif Bar & Company |
| Cargill |
| Danone |
| Nature's Path Foods |
| Blue Diamond Growers |
| Others |
Value Network & Pricing Analysis
Capacity utilization at ISO-accredited testing laboratories shapes both certification backlogs and the price floors that processors must absorb to maintain Non-GMO Project Verified status. Scale economies in identity-preserved grain handling concentrate margin power with elevator operators in Iowa and Illinois who command premiums for segregated storage infrastructure.
Pricing Analysis
Cost-plus contracts indexed to CBOT corn and soybean futures dominate ingredient procurement for non-GMO processors. Price differentiation rests on dual-certification status and lot-level traceability depth, with single-certified suppliers facing compression. Pricing pressure stems from retail price elasticity that limits pass-through of identity-preserved premiums. Health-conscious consumers show highest price sensitivity, while organic shoppers accept layered premiums with minimal resistance.
Supply Chain Analysis
Strait of Malacca transit vulnerability for imported testing equipment underwrites lead time risk for verification protocols. Supply concentrates in the United States, Canada, and Argentina for identity-preserved corn and soybeans. The chain draws from specialized seed stock, dedicated elevator infrastructure, and ISO-accredited PCR testing services. Single-source vulnerability sits with the limited pool of Non-GMO Project-trained auditors. Distribution runs through direct-to-retailer certification relationships that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
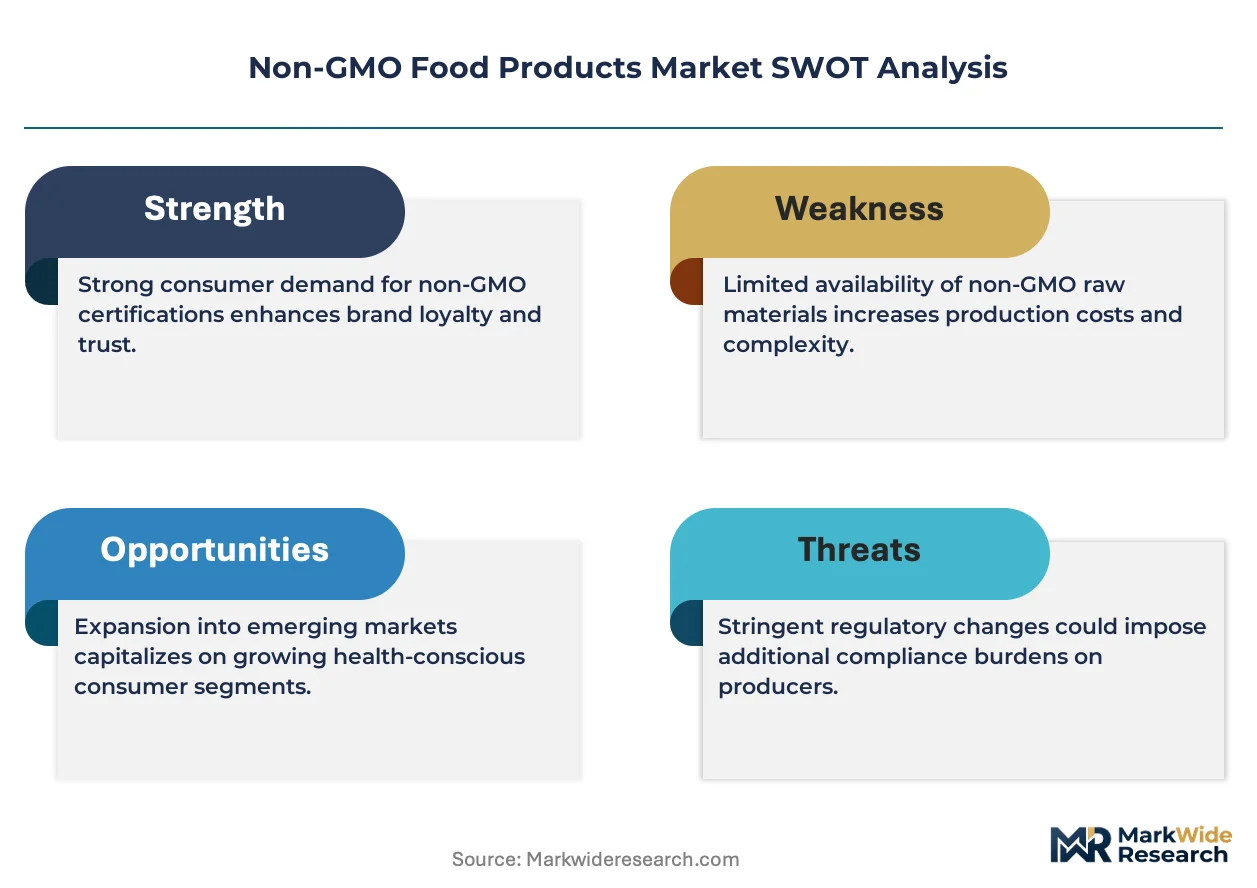
This market functions as a defensive-moat story where regulatory entrenchment through overlapping FDA disclosure rules and USDA Organic standards creates switching costs that lock in qualified suppliers.
For Market Incumbents: Compound certification depth by adding blockchain-enabled traceability layers that command shelf price premiums. Absorb auditor capacity constraints through captive inspector training programs. Defend against emerging regional processors by locking multi-year direct sourcing agreements with Pacific Northwest retail clusters.
For New Entrants and Emerging Players: Anchor in foodservice direct sourcing channels where institutional buyers bypass retail distribution markups. Target white-space in ancient grain ingredient supply for plant-based dairy alternatives. Pursue go-to-market positioning as a dual-certified supplier to health food stores with strict procurement protocols.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors grain-origination multinationals with captive identity-preserved infrastructure. Long-term viability hinges on regulatory compliance automation that reduces per-lot verification costs. Watch auditor training program expansion as the inflection signal for certification bottleneck relief.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Distributed ledger adoption at Cargill and Amy's Kitchen compresses audit costs while enabling real-time contamination alerts. |
| Dual Certification Investment | Layered Non-GMO Project Verified plus USDA Organic status concentrates margin pools with qualified manufacturers. |
| Foodservice Direct Sourcing | Restaurant chain captive supply agreements bypass traditional retail distribution markups for institutional volume. |
| Auditor Training Program Expansion | Non-GMO Project inspector capacity growth alleviates certification backlogs that delay product launches. |
| Identity-Preserved Infrastructure Buildout | Dedicated elevator and processing facility investment excludes smaller regional operators from eligibility. |
Research Methodology
The analysis maps beverages, snacks, dairy alternatives, and grain ingredients, each validated through certification auditors, grain elevator operators, retail category buyers, and foodservice procurement directors. Primary interviews with supply chain stakeholders combined with secondary validation against FDA disclosure rulemakings, USDA Organic program data, Non-GMO Project verification records, and customs trade flows. Bottom-up volume triangulation against top-down expenditure estimates ensures cross-check integrity.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, consumer segment, distribution channel, and certification type dimensions. CAGRs derive from segment-level growth rate aggregation. Forecast inputs include identity-preserved grain premium trajectories and auditor capacity expansion schedules.
Material uncertainties — regulatory fragmentation beyond federal baselines, biotechnology disclosure rule revisions, and auditor training program scale — sit outside the modeled envelope. Forecasts reflect assumptions about certification cost pass-through and retail shelf space allocation. Practitioners should keep alternative scenarios live as state-level labeling initiatives and retailer-specific non-GMO commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Silver Food Market
Specialty Foods
Super Foods Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Global Honey Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Kelp Noodles Market