
 Organic Coconut Sugar Market | 2026-2036
Organic Coconut Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Coconut Sugar Market Outlook
The EU Green Deal's sustainable food system targets is realigning European importer specifications toward fully traceable organic coconut sugar supply chains. Nutiva Inc leverages direct farmer partnerships in Southeast Asia to secure consistent organic volumes. Big Tree Farms anchors its position through vertically integrated processing facilities in Indonesia. Celebes Coconut Corporation dominates export logistics from the southern Philippines into EU and North American distribution networks.
Organic coconut sugar is an unrefined sweetener derived from the evaporated sap of Cocos nucifera flower inflorescences, retaining trace minerals including potassium, magnesium, and zinc with a glycemic index near thirty-five. Its primary commercial purpose centers on replacing refined cane sugar and synthetic sweeteners in clean-label food and beverage formulations. Granulated coconut sugar leads volume sales through baking and household channels, while liquid coconut sugar captures faster growth in beverage manufacturing applications where solubility and caramel flavor profiles command premium positioning. Distribution through health food stores and specialty shops captures higher margins per unit than supermarket or online retail channels, reflecting consumer willingness to pay for certified organic provenance and staff-curated product knowledge.
USDA Organic certification, EU Organic Regulation enforcement, and FDA food labeling standards collectively shape market access requirements and product differentiation thresholds for exporters entering North American and European markets. BIS standards in India and emerging ASEAN organic harmonization frameworks add compliance layers for suppliers targeting Asian market expansion. Stakeholders must monitor evolving traceability mandates and carbon accounting disclosures that will determine which processing cooperatives and export intermediaries retain preferred supplier status with multinational food manufacturers.
Market Dynamics
EU Green Deal traceability mandates are forcing organic coconut sugar exporters to reconstruct supply chain documentation from farmer cooperatives through retail shelves, compressing margins for intermediaries lacking direct farm partnerships.
Growth Catalysts
- EU Organic Regulation enforcement:Certification requirements for full chain-of-custody documentation are locking out non-compliant suppliers and securing premium shelf space for verified exporters in German and French retail channels.
- Clean-label bakery reformulation:Industrial bakers in the United States are substituting refined cane sugar with organic coconut sugar to meet FDA guidance on added-sugar reduction while maintaining caramelization performance.
- Southeast Asian cooperative investment:Farmer-owned processing facilities in Indonesia and the Philippines are capturing value previously lost to third-party processors, improving raw material consistency for export contracts.
Market Restraints
- Raw material concentration risk:Over seventy percent of organic coconut sap harvesting occurs within a 500-kilometer radius in Central Java, exposing supply continuity to localized weather shocks and pest cycles.
- USDA Organic certification timeline:Three-year transition periods for conventional coconut farms seeking organic status create supply inelasticity that cannot respond to sudden demand surges from North American manufacturers.
- Date palm sugar substitution:Middle Eastern and North African suppliers are positioning date-derived sweeteners as lower-cost alternatives with comparable glycemic index claims in European ethnic food channels.
Strategic Opportunities
- ASEAN organic harmonization:Emerging mutual recognition agreements between Indonesia, Thailand, and Vietnam will reduce duplicate certification costs for suppliers targeting intra-Asian distribution.
- Liquid coconut sugar in functional beverages:Solubility advantages over granulated forms are opening formulation contracts with kombucha and adaptogenic drink manufacturers seeking clean-label positioning.
- Direct-to-manufacturer procurement platforms:Digital traceability tools are enabling food brands to bypass traditional import distributors and contract directly with Indonesian farmer cooperatives, capturing 15-20 point margin improvements.
Industry Challenges
- Carbon accounting disclosure requirements:EU CSRD mandates for Scope 3 emissions reporting are forcing exporters to deploy farm-level monitoring systems that most Southeast Asian cooperatives lack technical capacity to implement.
- Skilled fermentation control technicians:Sap-to-sugar processing requires precise temperature and pH management that traditional coconut farmers cannot execute without structured training programs, creating quality variability in smallholder supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Coconut Sugar Market |
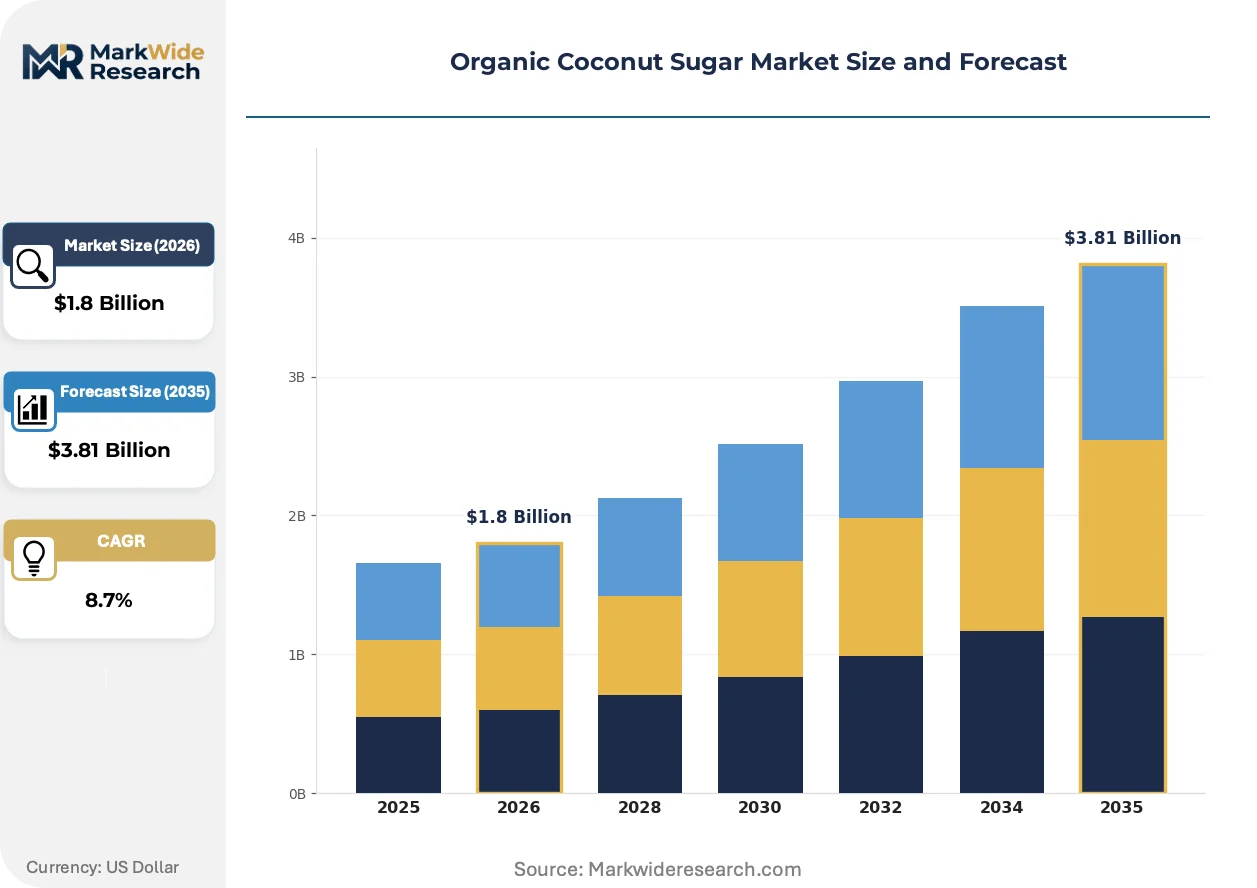
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Coconut Sugar, Liquid Coconut Sugar, Coconut Sugar Syrup, Coconut Blossom Sugar Application: Baking, Beverages, Confectionery, Sauces Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Households, Food Manufacturers, Restaurants, Cafés |
| Companies Covered | Nutiva Inc, Wholesome Sweetener Inc, Big Tree Farms, Celebes Coconut Corporation, PT Holos Integra, The Coconut Company Ltd, Madhava Ltd, SunOpta Inc, Coco Sugar Indonesia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Coconut Sugar Market Strategic Shifts
Processing technology upgrades and regulatory disclosure mandates are converging to reshape competitive positioning, favoring exporters with captive supply relationships and in-house laboratory verification capabilities over trading-house intermediaries.
Solar-powered evaporative drying systems are electrifying energy-intensive sap reduction stages previously dependent on firewood or diesel generators. Indonesian cooperatives with German technical assistance programs are deploying photovoltaic arrays coupled to forced-air dehydration tunnels, cutting fuel costs by half while satisfying EU buyer preferences for low-carbon processing. This electrifying shift is compressing the cost gap between organic and conventional coconut sugar, enabling volume expansion into mid-market retail tiers previously price-excluded.
REACH registration requirements for imported food contact substances are tightening specifications on packaging materials used for bulk organic coconut sugar shipments. EU importers are now rejecting conventional polymer liners in favor of certified compostable films, forcing Southeast Asian processors to reformulate packaging procurement or lose German and Dutch distribution contracts. The regulation is accelerating consolidation among exporters with capital reserves to retool packaging lines.
Certification-driven preference shifts are restructuring procurement patterns in North American natural products retail. Staff-curated health food stores are demanding lot-specific laboratory analysis for glycemic index and mineral content, displacing commodity purchasing based on organic seal alone. This behavior is most visible in California and Pacific Northwest markets, where buyers are paying 30-40 percent premiums for coconut sugar with verified potassium and magnesium assay certificates.
Organic Coconut Sugar Market Segmentation
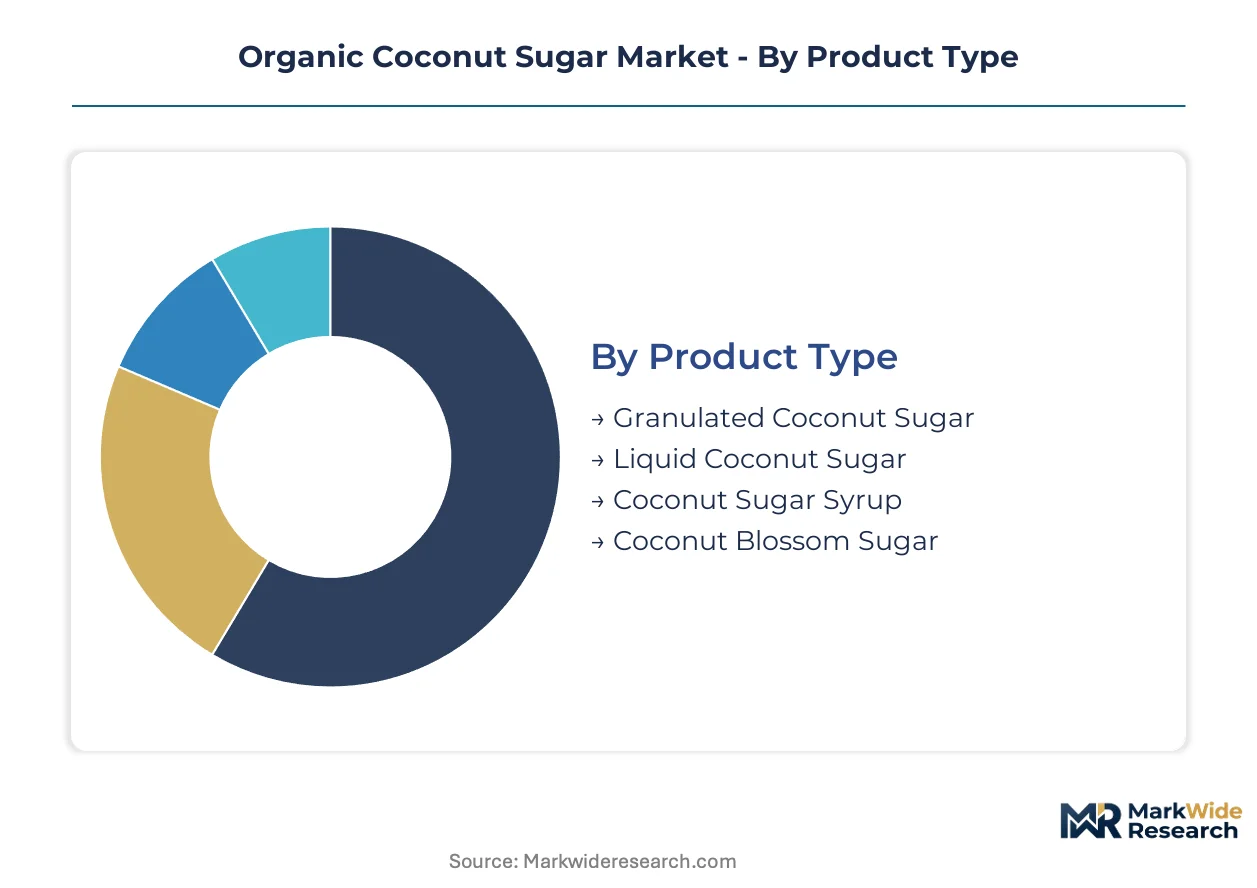
Product form and channel selection dictate margin capture in organic coconut sugar procurement. Manufacturers prioritize solubility and caramelization performance, while retail channel choice reflects consumer willingness to pay for certified provenance and staff expertise.
Product Type:
Processing intensity and moisture content differentiate upgrade cycles across organic coconut sugar formats, with beverage manufacturers driving fastest adoption of liquid variants.
- Granulated Coconut Sugar:Dehydrated crystalline form with 2-4% residual moisture retains potassium and magnesium trace minerals. Industrial bakers in the United States substitute this for refined cane sugar to maintain caramelization while meeting FDA added-sugar reduction guidance. Household penetration through supermarket channels anchors volume.
- Liquid Coconut Sugar:Unfiltered sap concentrate with 75-80% dissolved solids delivers superior solubility in cold-process beverages. Kombucha and adaptogenic drink manufacturers in California and Pacific Northwest markets contract directly for this format, paying premiums for verified glycemic index certification.
- Coconut Sugar Syrup:Intermediate viscosity grade between liquid and granulated forms, used in ethnic sauce formulations and craft confectionery.
- Coconut Blossom Sugar:Marketing designation emphasizing flower-sap origin, commanding retail premiums in European health food channels.
Volume placements concentrate in granulated formats for baking applications; the faster expansion belongs to liquid coconut sugar in functional beverage manufacturing.
Application:
End-use specifications range from caramelization temperature requirements in industrial baking to clean-label positioning in premium beverages.
- Baking:Reformulation of cookies, muffins, and bread mixes requires precise moisture adjustment when substituting coconut sugar for refined alternatives. USDA Organic certification locks in supply contracts with industrial bakers seeking clean-label claims.
- Beverages:Solubility demands and flavor masking requirements favor liquid and syrup formats. German and Dutch importers enforce REACH-compliant packaging for bulk shipments into this segment.
- Confectionery:Artisan chocolate and caramel producers value low-glycemic index positioning for premium product lines.
- Sauces:Ethnic food manufacturers incorporate coconut sugar for balanced sweetness in teriyaki and tamarind-based formulations.
Revenue concentration sits with baking reformulation; beverage applications are climbing the fastest as functional drink categories expand.
Distribution Channel:
Channel selection determines margin structure, with curated retail environments capturing 30-40 point premiums over mass-market routes.
- Online Retail:Direct-to-consumer platforms enable subscription models for certified organic households, though price transparency compresses margins versus specialty retail.
- Supermarkets:Volume placement for granulated formats in conventional grocery requires slotting fee investments and private-label competition.
- Health Food Stores:Staff-curated environments in California and Pacific Northwest markets demand lot-specific mineral assay certificates, justifying premium pricing.
- Specialty Shops:Ethnic food retailers and gourmet outlets stock coconut blossom sugar for consumers seeking alternative sweetener provenance stories.
Transaction volume flows through supermarkets; health food stores deliver the steepest margin expansion trajectory.
End User:
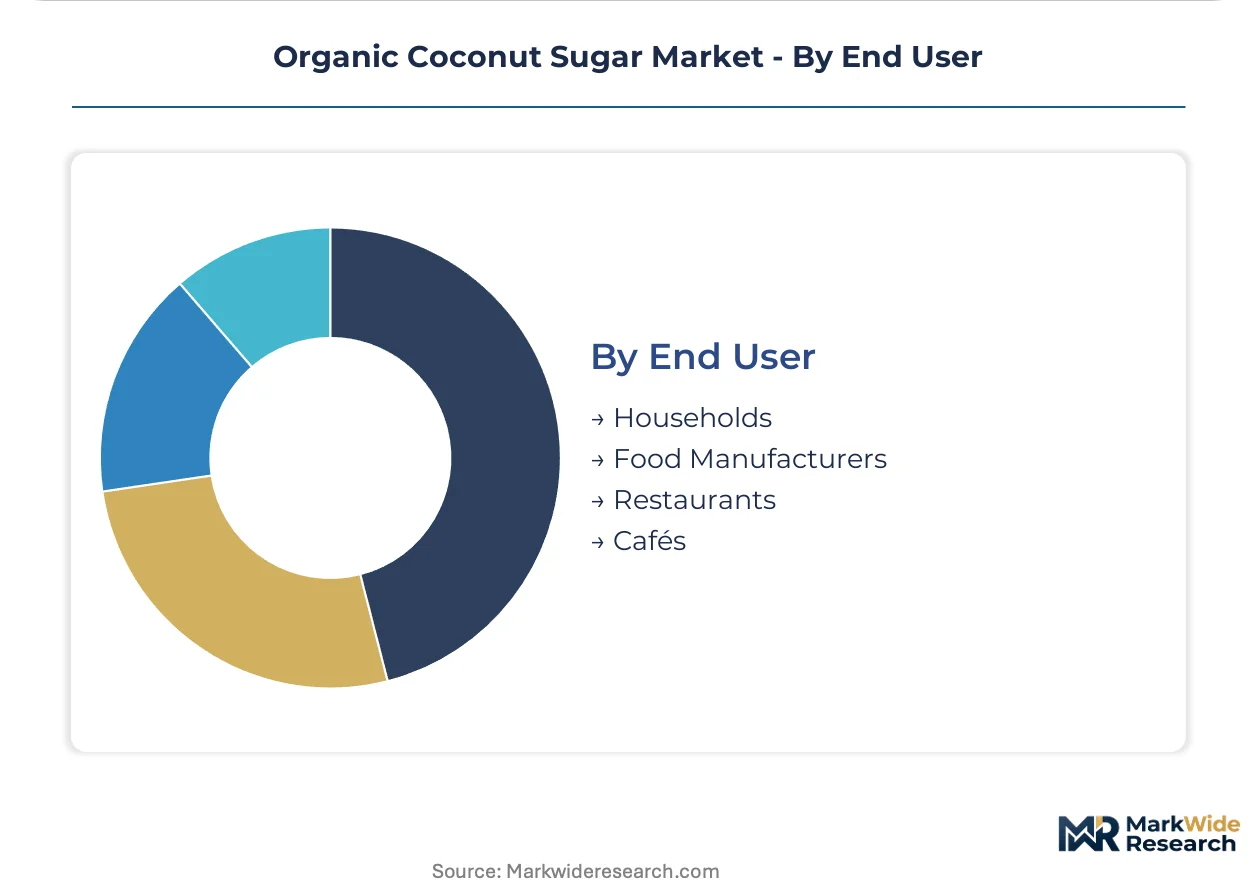
Procurement scale and certification requirements separate household purchasers from institutional buyers with direct cooperative contracting capability.
- Households:Retail package sizes of 250g to 1kg dominate purchasing, with organic seal recognition driving selection over mineral content verification.
- Food Manufacturers:Industrial bakers and beverage companies contract volumes requiring chain-of-custody documentation for EU Organic Regulation compliance.
- Restaurants:Farm-to-table establishments in Portland and San Francisco markets menu coconut sugar for dessert and sauce applications.
- Cafés:Specialty coffee chains substitute coconut sugar for simple syrup in signature beverages, particularly in German urban markets.
Procurement volume concentrates with food manufacturers; cafés are expanding most quickly as beverage menu differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surabaya anchors raw material processing for organic coconut sugar exports, with Indonesian cooperatives supplying granulated and liquid formats to North American and European food manufacturers seeking clean-label sweeteners.
United States
Industrial bakers in Chicago and Minneapolis reformulate cookie and bread mixes using organic coconut sugar to meet FDA guidance on added-sugar reduction. USDA Organic certification requirements lock in supply contracts with verified exporters. California health food stores in Los Angeles and San Francisco demand lot-specific mineral assay certificates, paying premiums for potassium and magnesium verification.
Germany
Natural products retailers in Berlin and Hamburg enforce EU Organic Regulation chain-of-custody documentation for shelf placement. ECHA REACH registration mandates reject conventional polymer packaging liners, forcing compostable film adoption. Bavarian importers contract directly with Indonesian farmer cooperatives using digital traceability platforms, bypassing traditional distributors.
Indonesia
Central Java farmer cooperatives own processing facilities that capture value previously lost to third-party intermediaries. German technical assistance programs deploy photovoltaic arrays and forced-air dehydration tunnels, cutting fuel costs by half. Surabaya export logistics handle bulk shipments to EU and North American distribution networks.
Philippines
Celebes Coconut Corporation dominates export corridors from Mindanao into German and Dutch markets. Three-year USDA Organic transition timelines constrain supply elasticity for North American demand surges. Davao processing clusters face carbon accounting disclosure requirements under EU CSRD mandates that most cooperatives lack technical capacity to implement.
United Kingdom
London specialty coffee chains substitute coconut sugar for simple syrup in signature beverages. Health food retailers in Bristol and Manchester curate staff expertise on glycemic index positioning. UK importers navigate post-Brexit organic equivalence agreements with Indonesian and Philippine suppliers.
Organic Coconut Sugar Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and direct farm partnership intensity. The vendor base separates into three strategic archetypes: vertically integrated Southeast Asian processors with captive supply, North American brand marketers with distributor relationships, and European importers with regulatory compliance specialization. Dominant competitive moves include backward integration into farmer cooperative equity stakes and packaging line retooling for REACH-compliant compostable films.
Within the vertically integrated processor tier, Big Tree Farms and Celebes Coconut Corporation exemplify archetypes with Indonesian and Philippine operational footprints. Nutiva Inc represents the North American brand marketer archetype. These three companies anchor competitive positioning through direct farmer partnerships, laboratory verification capabilities, and preferred supplier status with multinational food manufacturers seeking full chain-of-custody documentation.
| Leading Market Players |
|---|
| Nutiva Inc |
| Wholesome Sweetener Inc |
| Big Tree Farms |
| Celebes Coconut Corporation |
| PT Holos Integra |
| The Coconut Company Ltd |
| Madhava Ltd |
| SunOpta Inc |
| Coco Sugar Indonesia |
| Others |
Value Chain & Pricing Dynamics
Skilled fermentation control technicians in Central Java drive labor-cost differentials that widen spreads between premium certified organic grades and conventional commodity tiers. Their scarcity inflates processing wages for EU Organic Regulation-compliant cooperatives, compressing margins for exporters lacking in-house technical training programs.
Pricing Analysis
Yield-verified pricing anchors organic coconut sugar procurement, with buyers paying premiums for guaranteed glycemic index certification and mineral assay consistency. Three-tier pricing structure across premium certified organic, transitional organic, and conventional economy levels separates verified supply from undocumented alternatives. Price compression runs through the transitional tier as EU Green Deal traceability mandates force documentation investments that smaller cooperatives cannot absorb. Industrial food manufacturers exhibit lowest price sensitivity, absorbing certification premiums to secure chain-of-custody compliance, while ethnic food retailers in European channels remain most price-elastic, substituting toward date palm sugar alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Central Java's 500-kilometer harvesting radius, where over seventy percent of organic coconut sap collection feeds global export volumes. Raw material dependencies center on coconut palm flower inflorescences, firewood or diesel for traditional evaporation, and compostable film packaging for EU REACH compliance. Tariff exposure looms for Philippine exporters navigating post-Brexit UK organic equivalence negotiations and potential ASEAN harmonization disruptions. Distribution runs through Surabaya export logistics clusters into Rotterdam and Hamburg port terminals, with digital traceability platforms enabling direct-to-manufacturer contracting that bypasses traditional import distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photovoltaic-powered evaporative drying systems are displacing fossil-fuel dehydration infrastructure, compressing cost structures and enabling mid-market tier expansion previously price-excluded from organic positioning.
For Market Incumbents: Extend laboratory verification capabilities to capture staff-curated health food store premiums demanding lot-specific mineral assays. Deepen upstream control over Indonesian farmer cooperatives through equity stakes and German technical assistance program partnerships, defending against date palm sugar substitution in European ethnic channels. For New Entrants and Emerging Players: Kombucha and adaptogenic beverage manufacturers represent the most penetrable buyer segment, with solubility requirements favoring liquid coconut sugar formats lacking established supplier relationships. Target Pacific Northwest and California functional drink clusters with direct cooperative contracting enabled by digital traceability platforms, bypassing incumbent distributor networks. For Investors and Strategic Acquirers: The window for entry favors vertically integrated Southeast Asian processors with captive supply and in-house laboratory verification. Long-term viability hinges on EU CSRD carbon accounting disclosure readiness across farmer cooperative networks. Watch for EU-ASEAN organic mutual recognition agreement ratification as inflection signal for intra-Asian distribution cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Cooperatives | Captures value lost to third-party processors while securing USDA Organic and EU Organic Regulation chain-of-custody documentation. |
| Photovoltaic Dehydration Deployment | German technical assistance programs cut fuel costs by half, satisfying EU buyer preferences for low-carbon processing. |
| Liquid Format Capacity Expansion | Opens formulation contracts with kombucha and adaptogenic drink manufacturers seeking cold-process solubility. |
| REACH-Compliant Packaging Retooling | Compostable film adoption prevents rejection by German and Dutch importers enforcing ECHA registration mandates. |
| Direct-to-Manufacturer Digital Platforms | Bypasses traditional import distributors, capturing margin improvements for food brands contracting Indonesian cooperatives. |
Study Parameters
Trade databases, EU Organic Regulation compliance registries, and ECHA REACH filing records formed the secondary backbone of this analysis. Primary fieldwork encompassed interviews with Indonesian farmer cooperative managers, German natural products retail procurement leads, California functional beverage formulators, and Surabaya export logistics operators. Bottom-up volume triangulation across granulated and liquid format production clusters validated against top-down import value flows into Rotterdam, Hamburg, and Los Angeles port terminals.
Bottom-up modeling anchored forecast construction, with segmentation across product form, application, and distribution channel dimensions over the projection horizon. CAGRs derived from slope analysis of certified organic hectare expansion, EU Green Deal traceability mandate implementation timelines, and photovoltaic processing adoption curves. Industry-specific inputs included USDA Organic transition period elasticity constraints and ASEAN organic harmonization negotiation status.
Caveats apply where EU-ASEAN mutual recognition delays, localized Central Java weather shocks, or CSRD carbon accounting technical capacity gaps could materially shift the outlook. Forecasts reflect documented assumptions about cooperative investment trajectories and buyer certification premium sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Organic Cocoa Market