
 South Africa Organic Food Market | 2026-2036
South Africa Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Organic Food Market Insights
South African commercial farming regions is restructuring organic vegetable output to meet rising supermarket procurement quotas. Woolworths leverages its integrated fresh produce supply chain to secure consistent organic stock for premium retail shelves. Pick n Pay competes through dedicated organic private-label ranges across urban store networks. Shoprite anchors volume distribution by extending organic SKUs into its mid-market supermarket base.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, relying instead on crop rotation, biological pest management, and compost-based soil fertility to meet certified purity thresholds. The certification landscape shapes commercial viability, as USDA Organic and EU Organic labels unlock export channels while DALRRD local certification governs domestic shelf placement. Fruits and vegetables dominate current revenue contribution given perishability-driven premium pricing and shorter farm-to-shelf cycles, though grains gain structural momentum through bulk procurement by health-focused retail chains. Supermarkets capture the deepest margin pools through controlled cold-chain logistics and exclusive supplier agreements, while farmers' markets occupy a niche channel for direct producer-consumer relationships.
DALRRD organic standards, EU Organic import equivalency agreements, and the Consumer Protection Act collectively govern product claims, traceability, and retail labeling accuracy across South African organic commerce. Compliance costs favor larger certified operations with dedicated quality personnel, compressing informal producer participation. Stakeholders must monitor certification backlog timelines and retailer audit frequency as gatekeeping mechanisms for market access.
Market Dynamics
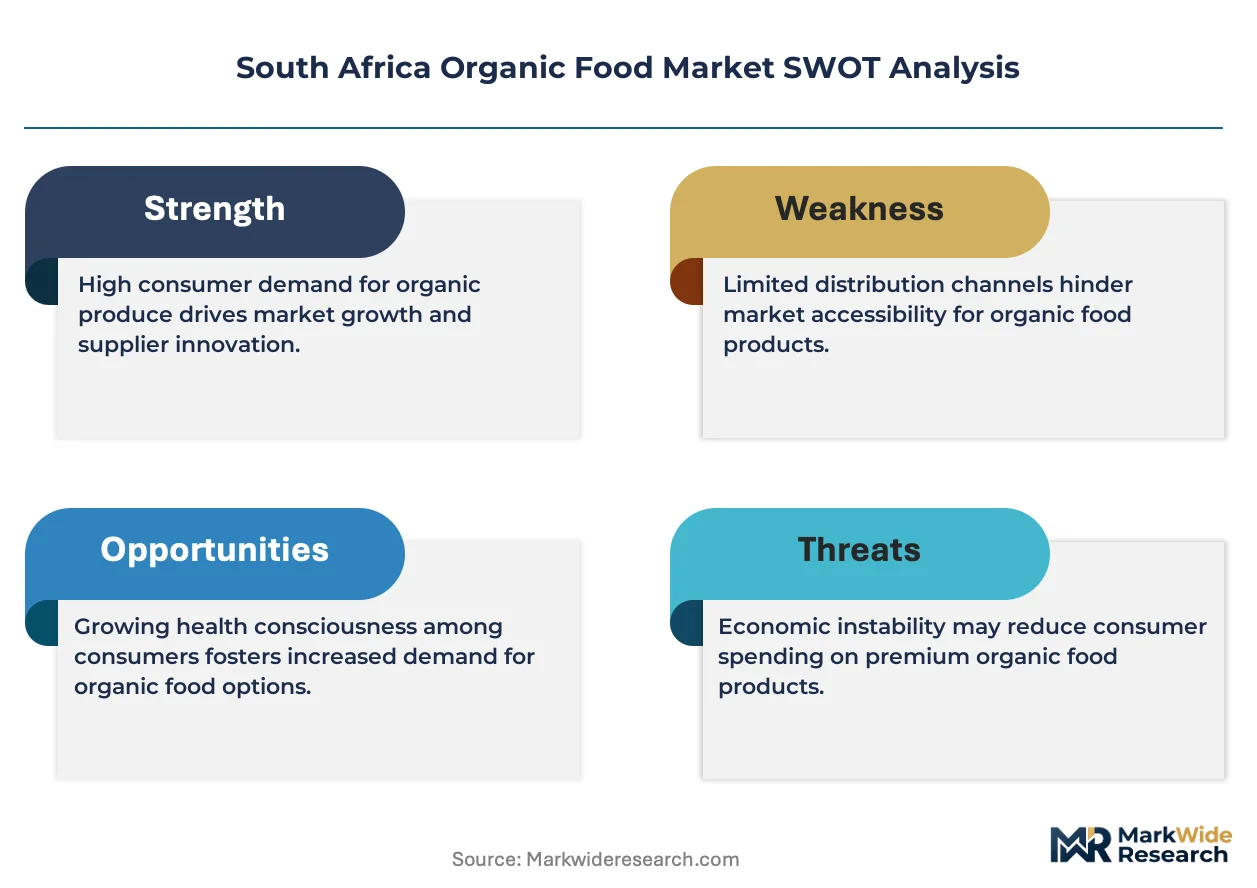
DALRRD's tightened organic certification protocols are forcing supply chain consolidation across South African farming operations, compressing informal producer participation while accelerating investment in dedicated quality infrastructure and cold-chain logistics.
Growth Catalysts
- Western Cape Consumer Concentration:Health-conscious households in Cape Town and surrounding metros are expanding certified organic purchases through premium retail channels, creating pull-through demand for upstream producers.
- EU Organic Equivalency:South Africa's mutual recognition agreement with EU Organic standards unlocks export revenue streams for certified operations, incentivizing compliance investment.
- Biological Pest Management:Advances in pheromone-based integrated pest management reduce synthetic input dependency while meeting DALRRD purity thresholds.
Market Restraints
- Input Cost Volatility:Organic compost and biological pest control inputs face price instability due to limited domestic supplier base concentration in KwaZulu-Natal.
- Certification Backlog Friction:DALRRD audit queue delays extend time-to-market for new organic entrants, favoring incumbent certified operations with established compliance pipelines.
- Conventional Produce Substitution:Lower-priced non-certified "natural" labeling competes for shelf space in mid-market retail, pressuring organic price premiums.
Strategic Opportunities
- Eastern Cape Underpenetration:Port Elizabeth and East London retail corridors show minimal organic SKU density, presenting first-mover expansion potential for compliant suppliers.
- Farmers' Market Channel Innovation:Direct producer-consumer platforms bypass supermarket margin extraction while capturing premium pricing through traceability storytelling.
- Consumer Protection Act Enforcement:Tightening false organic claim penalties create competitive shelter for legitimately certified brands against greenwashing competitors.
Industry Challenges
- Quality Personnel Scarcity:DALRRD-compliant organic certification management requires specialized agronomy and documentation expertise that outstrips current training pipeline output.
- Cold-Chain Capex Intensity:Perishability-driven organic produce requires continuous refrigeration infrastructure that strains smallholder capital access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Organic Food Market |
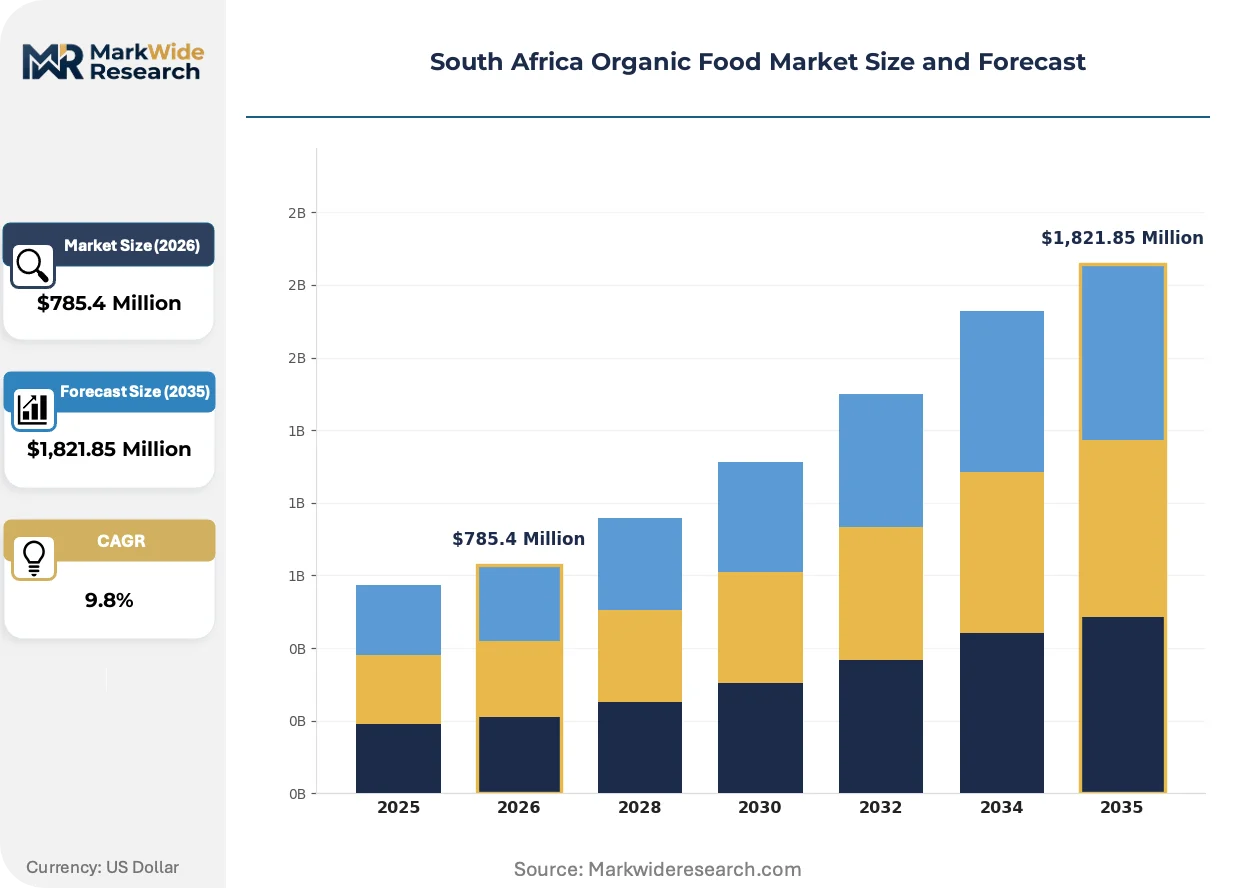
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,821.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Supermarkets, Specialty Stores, Online, Farmers' Markets Customer Type: Health-Conscious Consumers, Families, Chefs, Restaurants Certification: USDA Organic, EU Organic, Local Certification, Others |
| Companies Covered | Woolworths, Pick n Pay, Shoprite, Spar, Hain Celestial, White Wave Foods, Spartan Stores, Standard Bank (Agricultural Finance Division), Local Organic Farmers and Cooperatives, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Organic Food Market Trends and Innovations
Technology convergence and regulatory tightening are compressing traditional farming-to-retail timelines while elevating traceability requirements across South African organic supply chains.
Blockchain-enabled farm-to-fork traceability systems are electrifying transparency expectations in organic produce. Woolworths and Pick n Pay are piloting distributed ledger verification for high-value organic SKUs. This technology compression is collapsing information asymmetry between certified producers and skeptical premium consumers.
DALRRD's 2023 organic standard revisions mandate stricter residue testing protocols and documentation audit trails. Compliance costs are favoring larger certified operations with dedicated quality departments. Gauteng-based supermarket procurement teams are responding by consolidating supplier panels toward vertically integrated organic producers.
Subscription-based organic box delivery is fragmenting traditional supermarket channel dominance in Johannesburg and Cape Town. Direct-to-consumer platforms are displacing weekly grocery trips for affluent health-conscious households. This behavioral shift concentrates most visibly in Sandton and Atlantic Seaboard postal codes where delivery density supports unit economics.
South Africa Organic Food Market Segmentation
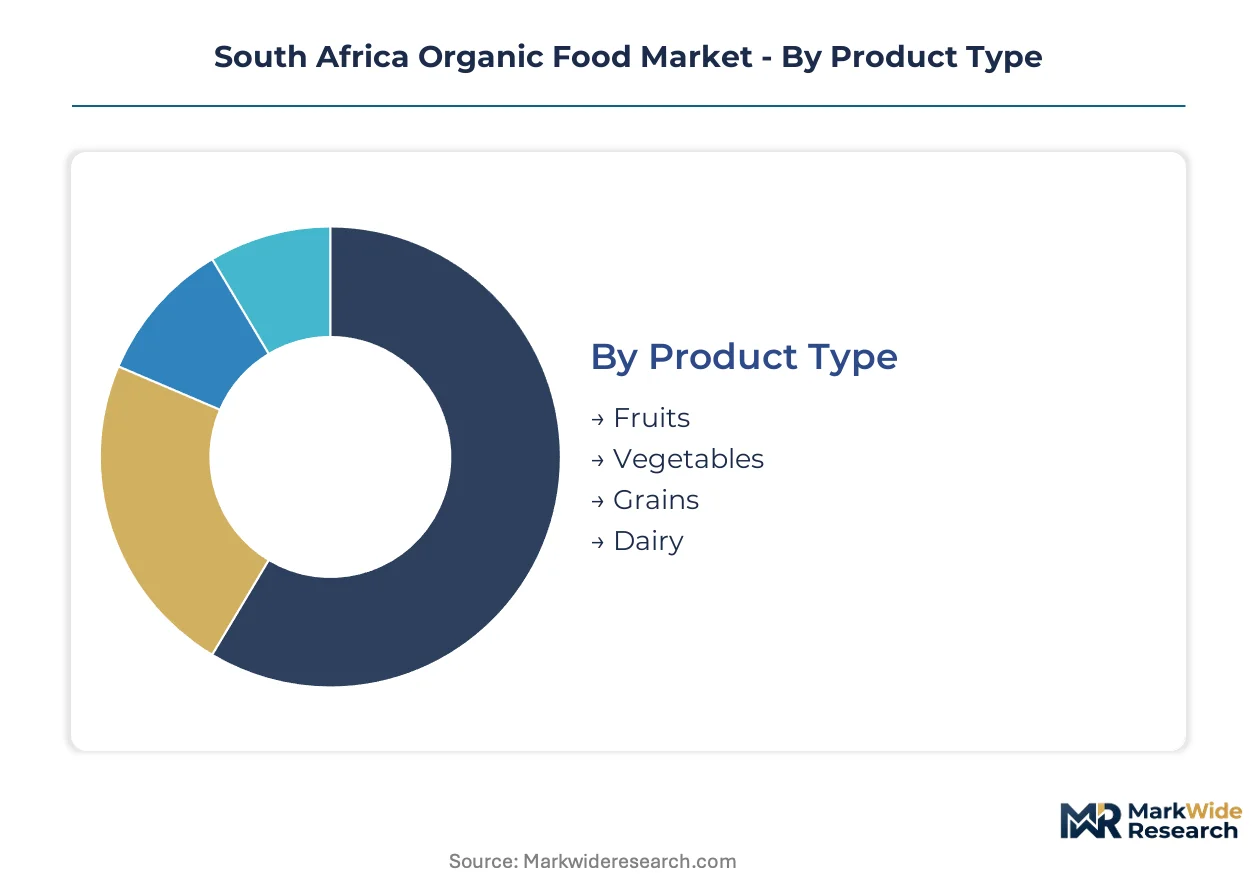
Segmentation in South Africa's organic food market reveals how certification tiers, channel economics, and consumer psychographics fragment commercial opportunity. Each dimension carries distinct margin structures and compliance burdens that shape supplier strategy across Gauteng, Western Cape, and KwaZulu-Natal corridors.
Product Type:
Standalone fresh categories command immediate shelf presence and perishability-driven turnover, while processed grains and dairy embed into longer production cycles with different capital intensity profiles.
- Fruits:Citrus, apples, and stone fruits dominate certified organic acreage in Western Cape orchards, with Woolworths and Pick n Pay procurement teams prioritizing consistent supply for premium produce sections. Cold-chain requirements compress farm-to-retail windows to 48-72 hours, favoring operations within 200 kilometers of Johannesburg and Cape Town distribution centers.
- Vegetables:Leafy greens and brassicas generate the highest revenue velocity per square meter of retail space, driven by health-conscious household meal preparation in Sandton and Atlantic Seaboard postal codes. Biological pest management protocols for vegetables demand more labor inputs than fruit orchards, concentrating production among larger certified operations with dedicated agronomy staff.
- Grains:Organic maize and wheat serve emerging private-label ranges at Shoprite's mid-market price points.
- Dairy:Certified organic milk and cheese remain supply-constrained due to pasture conversion timelines and herd management complexity.
Volume placements concentrate in Vegetables; the faster expansion belongs to Grains.
Distribution Channel:
Channel selection determines margin capture versus reach trade-offs, with controlled cold-chain infrastructure separating high-investment from low-capital participation modes.
- Supermarkets:Woolworths, Pick n Pay, and Shoprite account for the deepest procurement volumes, leveraging exclusive supplier agreements and captive logistics networks to secure consistent organic stock. DALRRD certification compliance serves as a non-negotiable entry ticket for shelf placement.
- Specialty Stores:Independent organic retailers in Cape Town's Kloof Street and Johannesburg's Parkhurst cluster curate premium assortments for affluent health-focused shoppers. These outlets accept smaller batch sizes and tolerate higher supplier margins than mass retail.
- Online:Subscription box platforms fragment weekly grocery trips for Sandton and Atlantic Seaboard households.
- Farmers' Markets:Direct producer-consumer venues in Durban's Morning Trade and Cape Town's Oranjezicht bypass supermarket margin extraction.
Revenue gravity centers on Supermarkets; Specialty Stores climb the fastest as urban premiumization accelerates.
Customer Type:
Customer archetypes stratify by price sensitivity, purchase frequency, and traceability demands that reshape supplier communication and product format decisions.
- Health-Conscious Consumers:Affluent individuals in Johannesburg's northern suburbs and Cape Town's Atlantic Seaboard prioritize certified purity and residue-free guarantees above price considerations. This segment drives subscription box adoption and direct-from-producer purchasing.
- Families:Households with children concentrate organic spending on dairy and vegetables perceived as reducing pesticide exposure for developing bodies.
- Chefs:Restaurant kitchen procurement prioritizes consistent sizing and flavor profiles for menu execution.
- Restaurants:Cape Town's fine-dining establishments and Johannesburg's farm-to-table concepts leverage organic sourcing for menu differentiation.
Transaction density peaks with Health-Conscious Consumers; Restaurants gain share fastest as culinary media amplifies provenance storytelling.
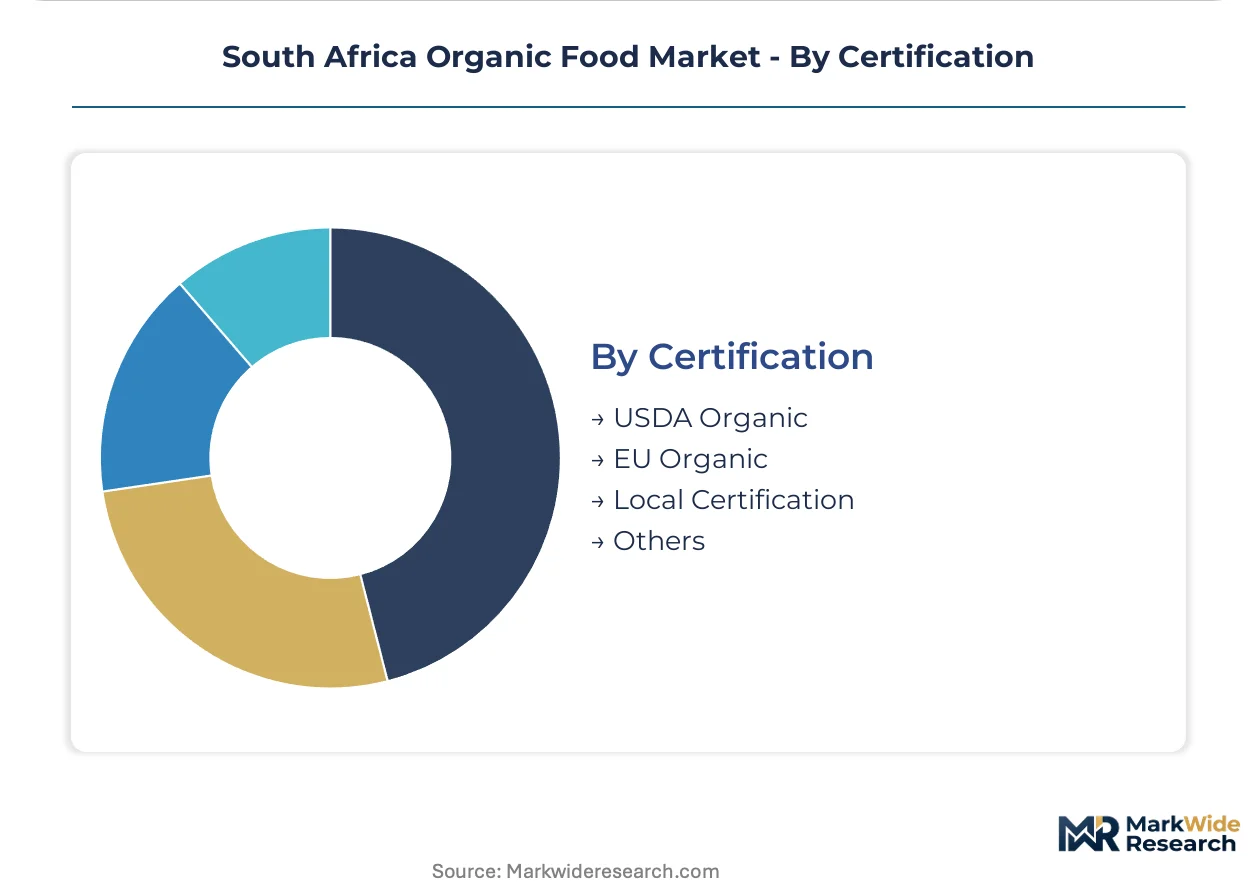
Certification:
Certification tier determines geographic market access and price realization, with international equivalency creating export optionality that domestic-only labels cannot match.
- USDA Organic:United States Department of Agriculture certification unlocks North American export channels for South African producers meeting residue and documentation standards. Compliance costs favor established operations with dedicated quality personnel.
- EU Organic:Mutual recognition agreements between South Africa and European Union standards enable seamless shelf placement in German, Dutch, and British retail without redundant auditing. Western Cape producers leverage this equivalency for citrus and wine grape exports.
- Local Certification:DALRRD organic standards govern domestic supermarket shelf placement and Consumer Protection Act compliance.
- Others:Bio Suisse and Naturland certifications serve niche Swiss and German specialty import channels.
Domestic volume concentrates under Local Certification; EU Organic captures the steepest expansion trajectory as export infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Cape citrus orchards and Gauteng vegetable belts anchor South Africa's organic production geography, with certification-compliant clusters concentrated within cold-chain reach of Johannesburg and Cape Town distribution centers.
Gauteng
Johannesburg's northern suburbs and Sandton postal codes drive premium organic demand through subscription box adoption and specialty retail. DALRRD certification protocols govern supermarket shelf placement across the province. Pretoria-Tshwane farming corridors supply leafy greens to Woolworths and Pick n Pay procurement teams within 48-hour harvest-to-shelf windows.
Western Cape
Cape Town's Atlantic Seaboard households prioritize certified purity in organic fruit and vegetable purchases. EU Organic equivalency agreements enable Western Cape citrus exporters to access German and Dutch retail channels without redundant auditing. Stellenbosch and Paarl wine districts host expanding organic vineyard conversions for both domestic and export markets.
KwaZulu-Natal
Durban metro corridors concentrate mid-market organic demand through Shoprite's expanding SKU ranges. The province's compost and biological pest control supplier base faces price volatility due to limited domestic production concentration. Morning Trade farmers' markets in Durban bypass supermarket margin extraction for direct producer-consumer relationships.
Eastern Cape
Port Elizabeth and East London retail corridors show minimal organic SKU density relative to population scale. DALRRD audit queue delays extend time-to-market for new entrants in this underpenetrated region. First-mover compliant suppliers are testing direct-to-restaurant channels in Gqeberha's emerging farm-to-table dining cluster.
South Africa Organic Food Market Competitive Landscape
Global organic food majors compete with South African retail champions across procurement scale and certification compliance dimensions. The market structure tilts toward consolidated supermarket dominance, with three retail groups capturing the deepest procurement volumes. Strategic archetypes include vertically integrated retail-procurement hybrids, dedicated organic private-label specialists, and direct-to-consumer subscription platforms. Competitive moves center on exclusive supplier agreements and cold-chain infrastructure expansion.
Among South African retail champions, Woolworths exemplifies the integrated supply chain archetype through captive organic produce sourcing. Pick n Pay occupies the private-label innovation tier with dedicated organic ranges across urban store networks. Shoprite anchors volume distribution by extending organic SKUs into mid-market supermarket bases. These three retailers represent the dominant competitive anchors shaping supplier compliance requirements and certification investment patterns across the national market.
| Leading Market Players |
|---|
| Woolworths |
| Pick n Pay |
| Shoprite |
| Spar |
| Hain Celestial |
| White Wave Foods |
| Spartan Stores |
| Standard Bank (Agricultural Finance Division) |
| Local Organic Farmers and Cooperatives |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between DALRRD-compliant domestic labels and EU Organic export-grade products manifests in parallel pricing ladders and supply chain configurations. Premium export channels command residue-testing documentation and cold-chain integrity investments that domestic mid-market tiers bypass, compressing margin structures differently across Gauteng distribution centers and Western Cape export terminals.
Pricing Analysis
Warranty-style freshness guarantees bundled with subscription box deliveries separate premium organic pricing from unbundled farmers' market transactions. Three-tier pricing structure across premium certified export, standard domestic retail, and economy private-label tiers anchors the market. Price differentiation rests on DALRRD certification level and cold-chain completion rather than brand alone. Pricing pressure stems from conventional "natural" label substitution in Shoprite's mid-market base. Health-conscious households in Sandton postal codes exhibit lowest price sensitivity; Eastern Cape families show highest.
Supply Chain Analysis
Refrigerated freight cost concentration within 200-kilometer radii of Johannesburg and Cape Town distribution centers dictates supplier viability. Production clusters in Western Cape citrus belts and Gauteng vegetable corridors feed national retail networks. Raw material dependencies include KwaZulu-Natal compost suppliers, biological pest control formulations, and EU-equivalent certification audit services. Single-source vulnerability concentrates in DALRRD-accredited inspection bodies with extended audit queues. Distribution runs through Woolworths-controlled cold-chain logistics and Pick n Pay procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's organic food sector reads as a certification-driven consolidation play. DALRRD audit backlog friction and compliance cost escalation force informal producers toward exit or acquisition.
For Market Incumbents: Extend exclusive supplier agreements into Eastern Cape corridors before first-mover compliance investments lock in competitor positioning. Deepen backward integration into biological pest control production to offset KwaZulu-Natal input cost volatility. Threat substitution from conventional "natural" labeling demands defensive certification marketing spend. For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer technology-first wedge into farmers' market channel premiumization. White-space targets include Port Elizabeth retail corridor SKU expansion and direct-to-restaurant supply in Gqeberha's farm-to-table cluster. Go-to-market angle should emphasize DALRRD compliance completion ahead of supermarket procurement panel reviews. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated Western Cape producers holding EU Organic equivalency given export infrastructure maturation. Long-term viability favors operations with captive cold-chain assets and dedicated quality personnel. Acquisition target archetype: mid-scale certified vegetable operations within 150 kilometers of Johannesburg distribution hubs. Signal to watch: DALRRD audit queue clearance timelines as inflection indicator for new entrant supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Woolworths-controlled refrigeration networks secure 48-hour harvest-to-shelf windows for leafy greens. |
| EU Organic Certification Investment | Western Cape citrus exporters unlock German and Dutch retail channels without redundant auditing burdens. |
| Biological Pest Control Integration | In-house pheromone-based IPM production reduces KwaZulu-Natal supplier concentration risk. |
| Direct-to-Consumer Platform Launch | Subscription box delivery fragments Sandton and Atlantic Seaboard supermarket channel dominance. |
| Eastern Cape Distribution Partnership | First-mover alliances with Port Elizabeth retailers capture underpenetrated mid-market organic demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Africa organic food market assessment. Primary interviews with DALRRD certification officers, Woolworths procurement managers, Western Cape agronomists, and KwaZulu-Natal compost suppliers combined with secondary validation from DALRRD standard revisions, EU equivalency agreement documentation, and supermarket SKU audit databases. Bottom-up farm-gate production estimates and top-down retail revenue triangulation cross-checked segment outputs.
Reconciliation of production volume streams, import-export customs records, and retail scanner data informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and certification tier. CAGRs derived from trend extrapolation of DALRRD certification issuance rates and supermarket organic SKU expansion trajectories. Industry-specific inputs incorporated biological pest management adoption curves and cold-chain infrastructure investment pipelines.
Several conditions sit outside the modeled scope, including weather-induced crop failure frequency, rand-euro exchange rate volatility effects on export margins, and potential DALRRD regulatory revision timing. Forecasts reflect documented assumptions about certification backlog resolution and supermarket procurement quota growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Australia Organic Beverages Market