
 Global Organic Packaged Food Market | 2026-2036
Global Organic Packaged Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Packaged Food Market Outlook
North American organic dairy processors is recalibrating production schedules to match volatile feed-grade organic corn availability. Stonyfield leverages its Northeast co-op network to secure year-round fluid milk supply. Whole Foods Market controls private-label shelf placement across its 500-plus store footprint. Nature's Path anchors its competitive stance through certified gluten-free and non-GMO breakfast cereal specialization.
Organic packaged food comprises agriculturally sourced ingredients cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, then processed and sealed in retail-ready formats under controlled-atmosphere or aseptic conditions to preserve nutritional integrity and extend shelf life. The category serves consumers seeking verified clean-label nutrition with traceable supply chains. Snacks and beverages command the widest household penetration and fastest velocity through supermarket and online retail channels, while dairy maintains tighter margin pools due to cold-chain infrastructure requirements and shorter expiration windows. Tetra Packs and flexible pouches are displacing rigid glass in beverages and baby food applications where lightweight logistics and reduced breakage drive cost economics.
The USDA Organic seal and EU Green Deal farm-to-fork framework govern ingredient sourcing, processing aids, and label claims across North American and European markets, with third-party certifiers such as CCOF and Ecocert conducting annual audits that determine retail access. India's FSSAI and China's SAMR are drafting parallel national organic standards that will condition import eligibility for exporters targeting Asian middle-class consumers. Stakeholders must monitor divergence between Codex Alimentarius guidelines and emerging national organic regimes to avoid compliance fragmentation that could strand inventory at border checkpoints.
Market Dynamics
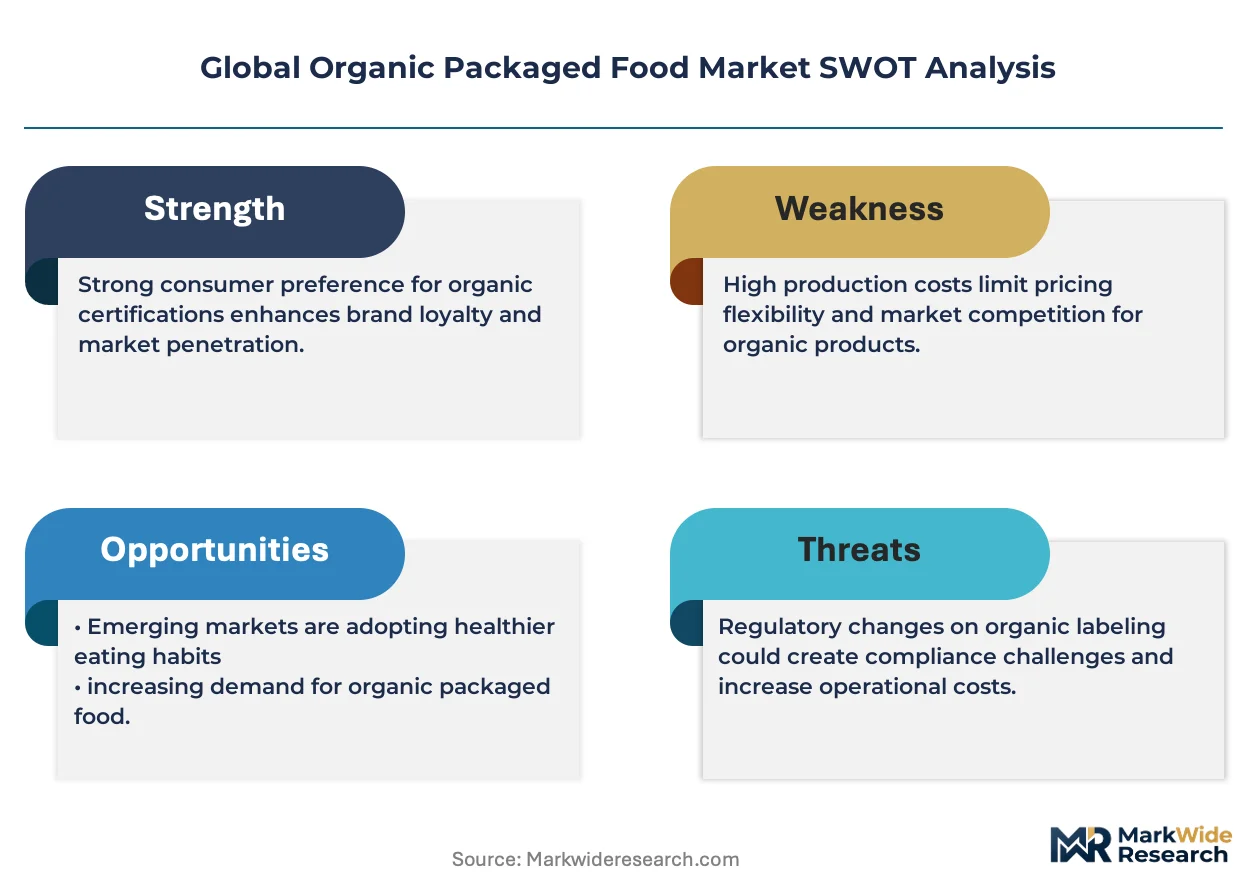
The EU Green Deal's farm-to-fork sustainability targets are tightening pesticide residue thresholds and reshaping supplier compliance requirements across the organic packaged food value chain. This regulatory compression is forcing ingredient processors to revalidate sourcing networks and accelerating consolidation among certified organic handlers.
Growth Catalysts
- EU Green Deal farm-to-fork framework:Mandatory reduction targets for chemical pesticide use are redirecting conventional acreage toward certified organic cultivation, expanding raw material availability for packaged food manufacturers.
- Urban metropolitan clusters:Premium organic retail penetration concentrates in North American and Western European cities where disposable income and health literacy correlate with certified product purchases.
- Cold-chain infrastructure expansion:Refrigerated logistics networks are extending shelf-stable distribution into secondary markets previously excluded from fresh organic dairy and prepared meal access.
Market Restraints
- Feed-grade organic corn volatility:Weather-driven yield fluctuations in the US Midwest and Ukrainian breadbaskets create input cost instability for organic dairy and poultry supply chains.
- Certification timeline friction:Three-year transition periods for conventional-to-organic farmland conversion constrain supply elasticity and lock in price premiums regardless of demand fluctuations.
- Plant-based dairy substitution:Oat and almond milk alternatives are capturing refrigerated case space and consumer trial budgets that previously flowed to certified organic fluid milk.
Strategic Opportunities
- India's FSSAI organic standard development:Formal national certification pathways will unlock import eligibility for exporters targeting the country's expanding middle-class consumer base.
- Flexible pouch packaging convergence:Lightweight barrier films combined with high-pressure processing technology are enabling ambient-stable organic baby food and beverage formats with reduced logistics costs.
- Direct-to-subscription channel innovation:Curated organic snack and meal kit delivery models are bypassing conventional retail slotting fee structures and capturing recurring revenue streams.
Industry Challenges
- Organic inspector talent scarcity:Accredited certifier workforce shortages are extending audit backlogs and delaying new product launches for brands awaiting USDA Organic or Ecocert approval.
- Legacy ERP integration complexity:Lot-level traceability requirements for organic certification are forcing mid-sized processors to replace inventory management systems not designed for ingredient pedigree tracking.
- Aseptic packaging capex intensity:Tetra Pak and Scholle IPN filling line investments require multi-million dollar commitments that strain balance sheets for regional organic beverage entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Packaged Food Market |
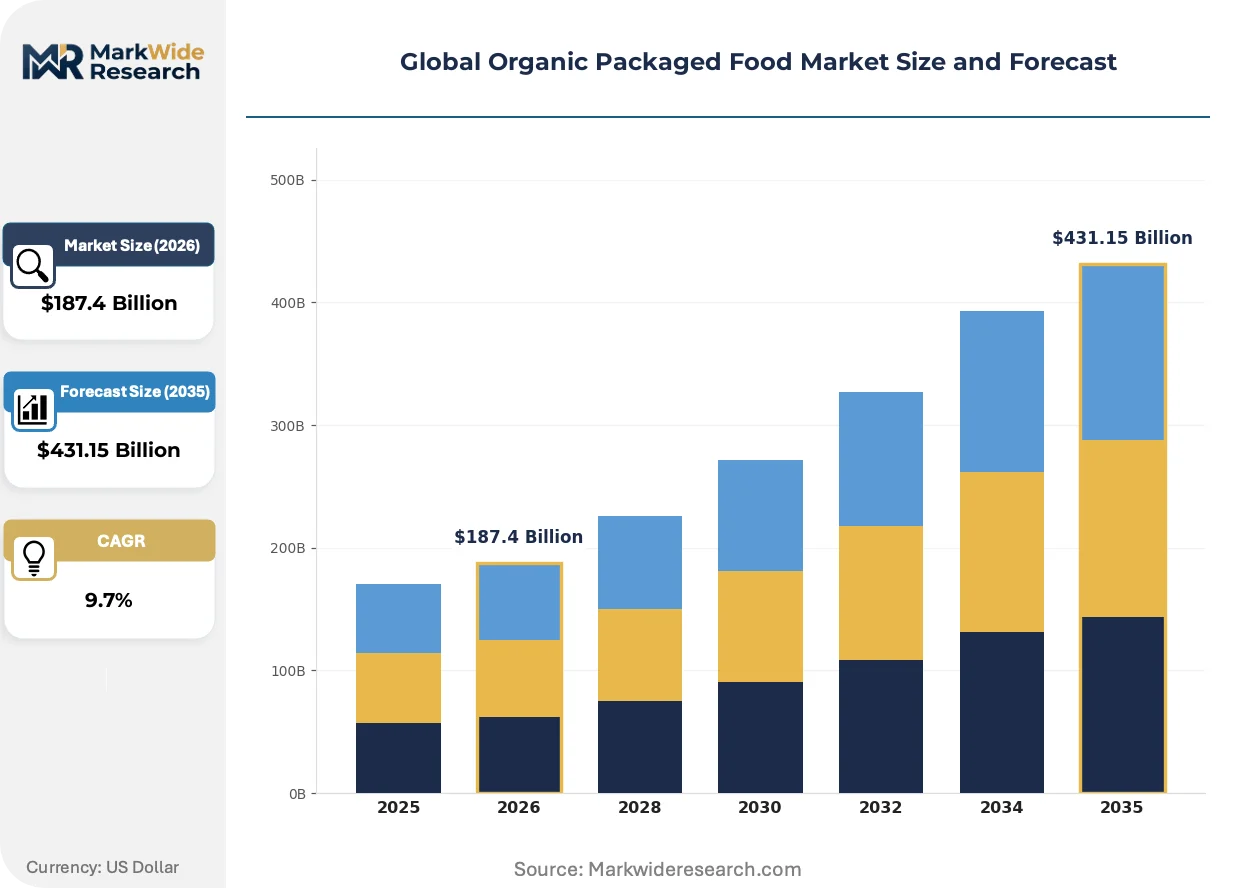
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Dairy, Canned Goods Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops End User: Households, Restaurants, Cafes, Caterers Packaging Type: Bottles, Boxes, Pouches, Tetra Packs |
| Companies Covered | Stonyfield, Grandy Organics, Whole Foods Market, Farmer Focus, Harmless Harvest, Eden Foods, Lakewood Organic, Once Upon a Farm, Nature's Path, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Packaged Food Market Strategic Shifts
Packaging material science and processing technology are converging to extend organic product shelf life without synthetic preservatives. These innovations are compressing the cost gap between conventional and certified organic formats while enabling new distribution reach.
High-pressure processing technology is electrifying the organic beverage and prepared meal segments by delivering pathogen reduction without thermal degradation of heat-sensitive vitamins and enzymes. Premium juice brands and refrigerated soup manufacturers are adopting HPP systems at accelerating rates. This cold-pasteurization method is enabling week-long refrigerated shelf stability that previously required freezing or aseptic hot-fill operations.
REACH chemical registration requirements in Europe are tightening scrutiny of processing aids and packaging migrants that contact organic food surfaces. Manufacturers must now document absence of SVHC substances in printing inks and adhesive layers. Organic baby food and infant formula categories face the steepest compliance burden given vulnerable-consumer regulatory sensitivity.
Certification-driven preference shifts are restructuring procurement patterns among institutional foodservice buyers. K-12 school districts and hospital systems are incorporating USDA Organic and non-GMO verification into bid specifications. This specification creep is most visible in California and New England markets where local procurement policies reinforce federal organic standards.
Global Organic Packaged Food Market Segmentation
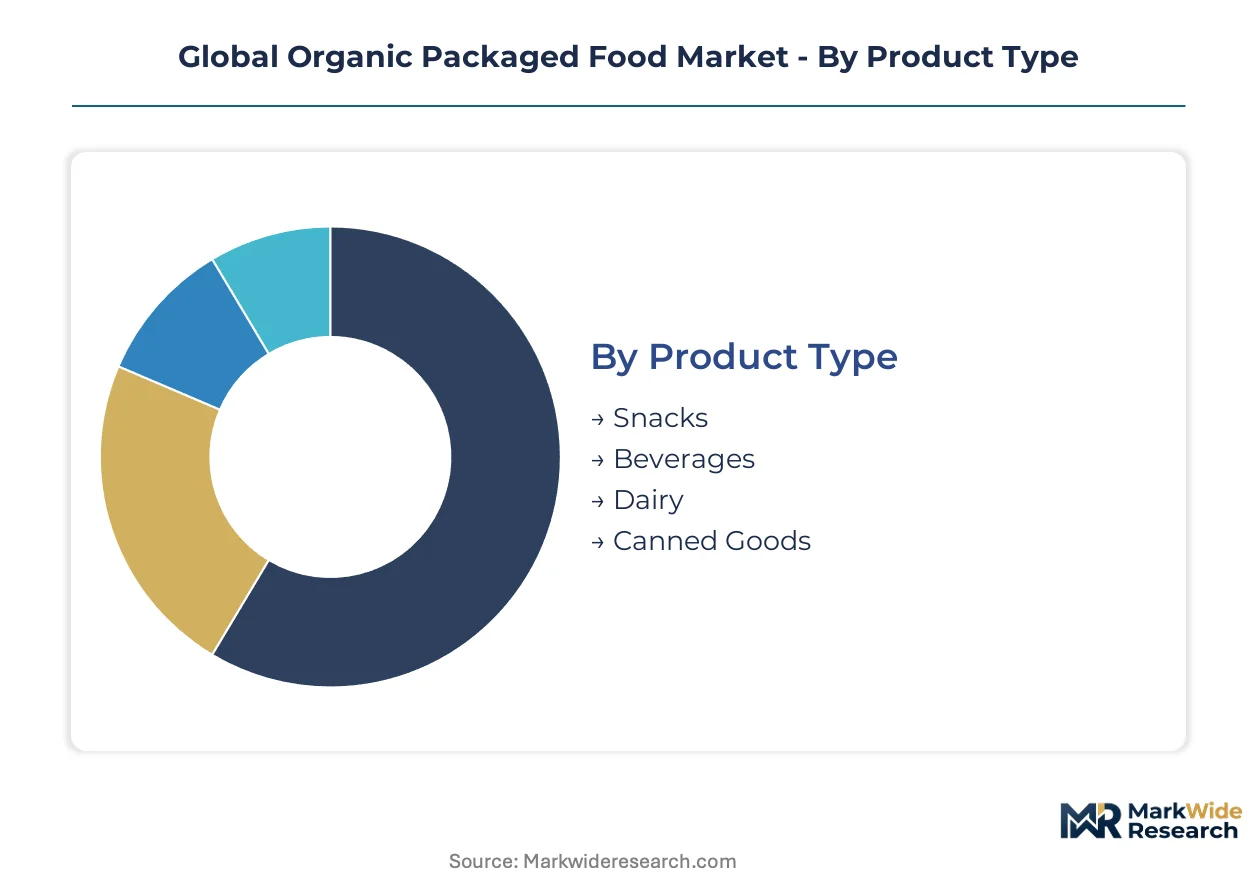
Organic packaged food segmentation reveals how certification requirements, shelf-life demands, and channel economics partition commercial opportunity. Product type and packaging format decisions lock in margin structures and distribution reach.
Product Type:
Standalone snack and beverage segments operate with minimal preparation requirements, while dairy and canned goods embed into broader meal occasions with stricter cold-chain or retort dependencies.
- Snacks:Granola bars, trail mixes, and puffed grain products carry ambient stability and impulse-purchase velocity. German and US households drive volume through certified organic claims that command checkout-aisle placement premiums.
- Beverages:Juices, plant-based milks, and ready-to-drink functional drinks require aseptic or HPP processing to preserve enzyme activity. Refrigerated case competition from conventional alternatives constrains pricing power in North American urban clusters.
- Dairy:Fluid milk, yogurt, and cheese categories face three-year herd conversion timelines and volatile organic feed costs.
- Canned Goods:Vegetables, soups, and prepared beans offer extended shelf stability but carry heavy freight economics.
Volume placements concentrate in Snacks; the faster expansion belongs to Beverages.
Distribution Channel:
Channel cost tiers separate high-volume grocery from premium-capture specialty formats, with digital intermediaries rewriting margin capture rules.
- Supermarkets:Conventional grocery chains dominate unit velocity through private-label expansion and slotting-fee structures that disadvantage emerging brands. Whole Foods Market's 500-plus US store network controls certified organic shelf positioning.
- Online Retail:Direct-to-subscription models bypass retail markup layers and capture recurring revenue through curated snack and meal-kit assortments. Cold-chain shipping constraints limit fresh dairy penetration.
- Health Food Stores:Independent retailers maintain SKU breadth for allergen-free and specialty-diet segments.
- Specialty Shops:Farm-store and farmers-market channels emphasize local provenance over certified organic compliance.
Supermarkets anchor current volume; Online Retail is climbing the fastest as logistics networks mature.
End User:
Customer type segmentation tracks preparation depth, from raw-ingredient households to finished-goods foodservice operators with specification-driven procurement.
- Households:Retail consumers seeking clean-label verification and traceable supply chains. California and New England K-12 districts now embed USDA Organic into bid specifications, extending institutional demand.
- Restaurants:Fast-casual and fine-dining operators menu organic claims for differentiation. Menu price elasticity limits penetration beyond coastal metropolitan clusters.
- Cafes:Coffee-shop chains source certified organic dairy and baked goods for beverage pairing.
- Caterers:Event-service providers face batch-size variability that complicates organic certification documentation.
Households dominate absolute consumption; Restaurants are gaining share fastest through procurement specification creep.
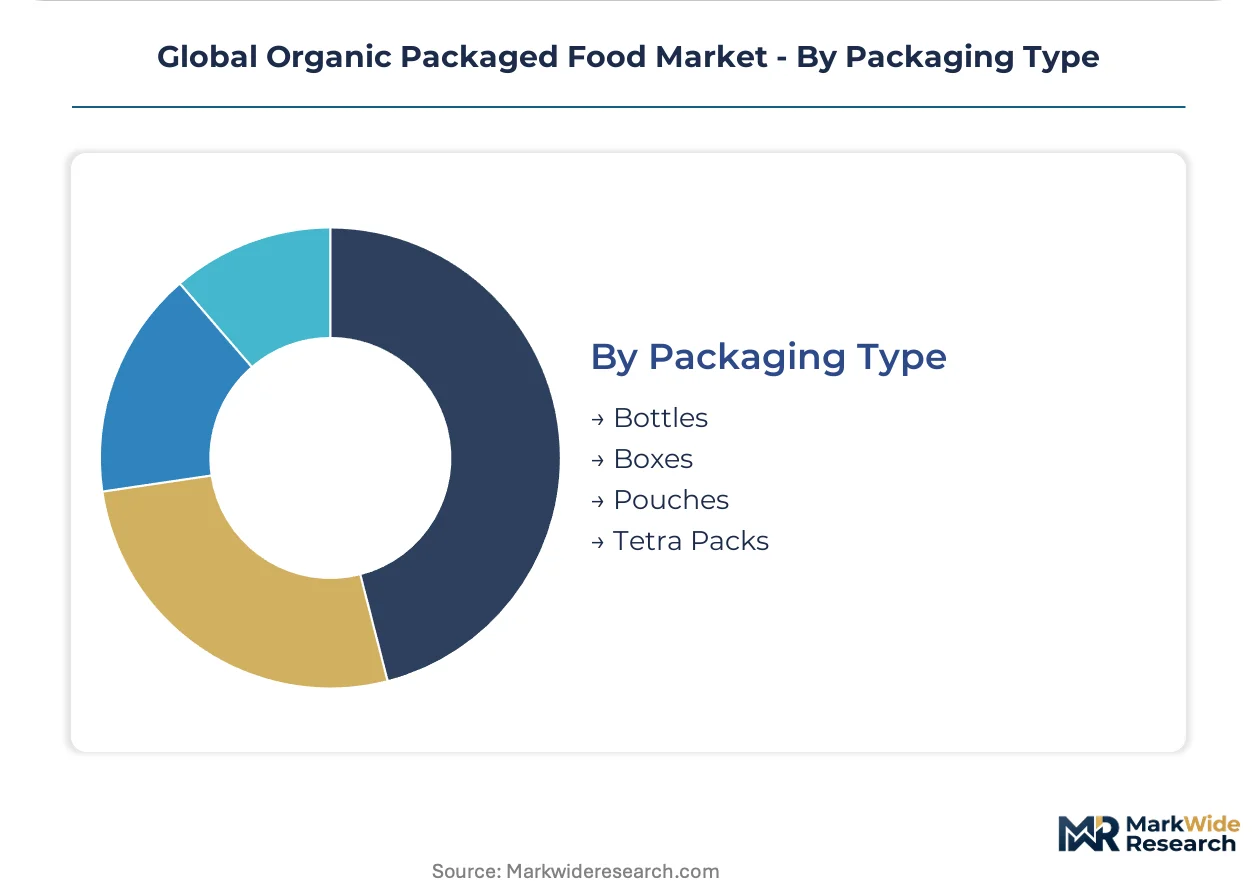
Packaging Type:
Material science investments separate high-barrier premium formats from commodity containers, with sustainability claims now conditioning format selection.
- Bottles:Glass and PET containers for beverages and dressings carry recycling credibility but freight cost penalties. Scholle IPN and Tetra Pak filling lines demand multi-million dollar capex commitments.
- Boxes:Folding carton formats for cereals and dry mixes balance printability with structural protection. REACH chemical registration in Europe now scrutinizes printing ink migrants.
- Pouches:Flexible barrier films enable lightweight logistics and high-pressure processing compatibility for ambient-stable baby food.
- Tetra Packs:Aseptic carton systems displace rigid glass in beverages through reduced breakage and cube efficiency.
Tetra Packs lead current volume placements; Pouches show the steepest expansion trajectory as HPP technology spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Midwest organic corn acreage anchors North American feedstock supply for dairy and poultry value chains. German and French organic wheat cultivation underpins European processed grain manufacturing. Indian organic basmati rice exports supply Middle Eastern and European retail channels.
United States
California's Central Valley and Vermont dairy corridors drive certified organic fluid milk and specialty cheese production. USDA Organic enforcement through accredited bodies like CCOF tightens residue testing protocols annually. Whole Foods Market's 500-plus store network controls premium shelf positioning in metropolitan clusters from Austin to Denver.
Germany
Berlin and Munich metropolitan households command the EU's highest per-capita organic packaged food expenditure. EU Green Deal farm-to-fork pesticide reduction targets redirect Bavarian and Lower Saxony acreage toward certified cultivation. Hamburg and Frankfurt logistics hubs consolidate cold-chain distribution into Scandinavian and Benelux retail markets.
India
Maharashtra and Karnataka organic pulse and spice cultivation supplies domestic and export processing demand. FSSAI national organic standard development is conditioning import eligibility frameworks for international suppliers. Mumbai and Bangalore urban clusters concentrate premium retail penetration among health-literate middle-class consumers.
China
Yangtze River Delta and Pearl River Delta metropolitan areas concentrate organic infant formula and beverage consumption. SAMR organic labeling regulations and GB standards govern domestic certification and cross-border e-commerce eligibility. Shanghai and Shenzhen retail chains are expanding dedicated organic sections in response to food-safety-conscious household demand.
France
Île-de-France and Auvergne-Rhône-Alpes regions anchor organic wine, dairy, and prepared meal manufacturing. EFSA and REACH chemical registration requirements scrutinize processing aids and packaging migrants contacting food surfaces. Lyon and Paris foodservice procurement specifications increasingly embed organic verification for institutional catering contracts.
Global Organic Packaged Food Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-subscription and specialty-diet niches. The vendor base stratifies across multinational dairy processors, regional co-operative networks, and venture-backed clean-label startups. Three archetypes dominate: legacy organic certifiers with multi-decade supply relationships, private-label retailers controlling shelf access, and technology-enabled challengers leveraging high-pressure processing for extended shelf life. Consolidation through co-operative acquisition and strategic sourcing partnerships represents the primary competitive vector.
Within the legacy certifier tier, Stonyfield and Nature's Path exemplify supply-chain-anchored positioning. Stonyfield leverages its Northeast co-operative network to secure year-round fluid milk availability. Nature's Path occupies a specialist position through certified gluten-free and non-GMO breakfast cereal concentration. Among retailer-controlled private-label operators, Whole Foods Market commands certified organic shelf placement across its national footprint. These three entities represent distinct competitive archetypes: co-operative-backed dairy processing, ingredient-specialist manufacturing, and retail-channel vertical integration.
| Leading Market Players |
|---|
| Stonyfield |
| Grandy Organics |
| Whole Foods Market |
| Farmer Focus |
| Harmless Harvest |
| Eden Foods |
| Lakewood Organic |
| Once Upon a Farm |
| Nature's Path |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's farm-to-fork pesticide reduction mandates gate both qualified organic feedstock supply and premium-tier pricing access, compressing certified ingredient availability while elevating compliance costs that manufacturers pass through to metropolitan retail channels.
Pricing Analysis
Warranty and certification-bundling separates USDA Organic and Ecocert-verified SKUs from uncertified alternatives. Three-tier pricing structure across premium certified, transitional organic, and conventional economy levels tracks ingredient pedigree and cold-chain service inclusion. Pricing pressure stems from feed-grade organic corn volatility in the US Midwest and Ukrainian breadbaskets. Households in California and New England metropolitan clusters show lowest price sensitivity, while mass-market supermarket buyers in secondary US cities resist checkout-aisle premiums.
Supply Chain Analysis
Dual-sourcing requirements from Whole Foods Market and institutional K-12 procurement specifications mandate redundant organic dairy and grain supplier qualification. Geographic concentration centers on US Midwest organic corn, German and French organic wheat, and Indian organic basmati rice. Raw material dependencies include certified organic feedstock, aseptic packaging films, and cold-chain refrigerants. Tariff exposure on Ukrainian organic grain imports creates supply risk. Distribution runs through refrigerated logistics networks into North American and Western European metropolitan retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic acreage conversion timelines constrain raw material elasticity, propping pricing premiums regardless of demand fluctuations across the projection horizon.
For Market Incumbents: Hedge feed-grade organic corn exposure through forward contracting with Northeast and Midwest co-operative networks. Accelerate backward integration into certified organic packaging film production to offset REACH chemical registration compliance costs. Defensive consolidation through co-operative acquisition locks in year-round fluid milk availability against plant-based dairy substitution threats. For New Entrants and Emerging Players: India's FSSAI organic standard development opens a window for export qualification and premium retail penetration in Mumbai and Bangalore metropolitan clusters. Target flexible pouch baby food formats where HPP technology reduces aseptic filling line capex barriers. Direct-to-subscription channel innovation bypasses Whole Foods Market slotting fee structures and captures recurring household revenue. For Investors and Strategic Acquirers: Accreditation backlogs at CCOF and Ecocert extending audit timelines is the leading indicator that organic inspector talent scarcity will constrain new product launch velocity and favor incumbent certifier relationships. Long-term viability favors acquisition targets with captive co-operative supply networks and established multi-region certification portfolios. Watch EU Green Deal pesticide threshold enforcement as the signal for accelerated conventional-to-organic acreage conversion and feedstock repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Co-operative Network Acquisition | Stonyfield's Northeast dairy co-op model secures year-round certified fluid milk supply against feed volatility. |
| HPP Technology Adoption | Once Upon a Farm leverages high-pressure processing for ambient-stable organic baby food with extended refrigerated shelf life. |
| Flexible Pouch Format Expansion | Lightweight barrier films reduce logistics costs and enable direct-to-subscription distribution without cold-chain dependency. |
| Private-Label Shelf Positioning | Whole Foods Market controls certified organic placement across 500-plus US stores, capturing metropolitan household velocity. |
| Dual Certification Investment | Simultaneous USDA Organic and Ecocert qualification unlocks transatlantic retail access and institutional procurement eligibility. |
Study Parameters
Document review covered EU Green Deal regulatory filings, USDA Organic enforcement protocols, and FSSAI standard development drafts, complemented by interviews with organic dairy processors, co-operative procurement managers, retail category buyers, and third-party certifier audit directors. Secondary validation drew from customs trade data on organic grain shipments, Nielsen retail audit figures, and SEC filings from packaged food manufacturers. Bottom-up volume modeling triangulated against top-down category spend estimates.
Cross-reference approaches weighted historical organic acreage conversion patterns against panel input from supply chain stakeholders. Segmentation dimensions modeled include product type, packaging format, distribution channel, and metropolitan cluster density. CAGRs were derived from trajectory analysis of certified organic retail penetration rates and cold-chain infrastructure expansion curves. Forecast inputs incorporated EU pesticide threshold enforcement timelines and FSSAI import eligibility framework development.
The model assumes a particular technology adoption path for high-pressure processing and aseptic filling; alternative pathways for ambient-stable organic preservation would alter the outlook for flexible pouch expansion. Forecasts reflect assumptions on feed-grade organic corn yield stability and accredited certifier workforce growth. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or FSSAI final standard publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Natural Food and Drinks Market