
 Organic Soda Market | 2026-2036
Organic Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Soda Market Analytics
Specialty beverage service in fast-casual dining and independent cafés is realigning procurement standards toward certified organic carbonated drinks. Olipop leverages its prebiotic formulation focus to anchor shelf space in premium grocery channels. Poppi sustains momentum through fruit-forward flavor profiles that compete directly with conventional soft drink incumbents. Zevia differentiates via its stevia-sweetened portfolio, positioning the brand for sugar-reduction regulatory environments.
Organic soda denotes carbonated soft drinks manufactured with certified organic ingredients, free from synthetic pesticides and artificial preservatives, typically utilizing organic cane sugar, natural fruit extracts, or plant-based sweeteners in place of high-fructose corn syrup. The production requires adherence to USDA Organic or equivalent certification standards governing ingredient sourcing and processing methods, yielding beverages positioned for health-conscious consumers seeking alternatives to conventional carbonated drinks. Cola and ginger ale variants occupy established volume positions, while lemon-lime formulations capture accelerated interest from younger demographics prioritizing cleaner label profiles. Supermarkets and health food stores dominate distribution infrastructure, though online retail channels are expanding fastest as direct-to-consumer subscription models gain traction among repeat purchasers.
USDA Organic certification governs ingredient integrity and labeling claims across the United States market, while FDA beverage standards regulate additive thresholds and nutritional disclosure requirements. The EU Green Deal and REACH frameworks influence export-oriented producers through chemical restriction protocols and packaging sustainability mandates. Stakeholders must monitor evolving sweetener classifications and extended producer responsibility legislation that will reshape formulation decisions and supply chain accountability.
Market Dynamics
The organic soda market is experiencing structural pressure from tightening certification requirements and ingredient traceability mandates that are reshaping procurement relationships between beverage manufacturers and agricultural suppliers.
Growth Catalysts
- USDA Organic certification expansion:Retailers are mandating certified organic shelf sets in response to documented consumer willingness to pay premium prices for verified clean-label carbonated beverages.
- Fast-casual restaurant procurement:National chains operating in coastal metropolitan clusters are converting fountain and bottled beverage lines to organic-certified SKUs to differentiate against conventional quick-service competitors.
- Prebiotic functional positioning:Formulations incorporating organic inulin and resistant starch are capturing health-conscious consumers seeking digestive wellness benefits beyond sugar reduction.
Market Restraints
- Organic cane sugar price volatility:Weather-induced supply fluctuations in Brazil and India are compressing gross margins for mid-tier producers unable to forward-contract harvest volumes.
- Single-source CO2 dependency:Regional carbon dioxide supply concentrates around petroleum refining byproduct capture, creating vulnerability for organic producers requiring food-grade certification documentation.
- Extended certification timelines:USDA Organic transition periods require three years of documented chemical-free soil management before ingredient harvest, constraining rapid capacity expansion.
Strategic Opportunities
- Direct-to-consumer subscription channels:Repeat purchase automation through curated flavor assortments is bypassing traditional slotting fee barriers in conventional grocery retail.
- EU Green Deal packaging alignment:Biodegradable bottle mandates under REACH-derived national implementations are creating first-mover advantage for organic brands with existing sustainability positioning.
- Stevia-erythritol blend optimization:Advances in organic-compliant natural sweetener masking technologies are enabling cleaner taste profiles that compete with conventional sugar-sweetened benchmarks.
Industry Challenges
- Organic flavor chemist scarcity:Formulation expertise combining FEMA GRAS natural flavor knowledge with organic certification compliance commands premium compensation in tight labor markets.
- Legacy equipment retrofit costs:Conventional bottling lines require dedicated organic product runs with documented cleanout protocols, reducing effective throughput and capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Soda Market |
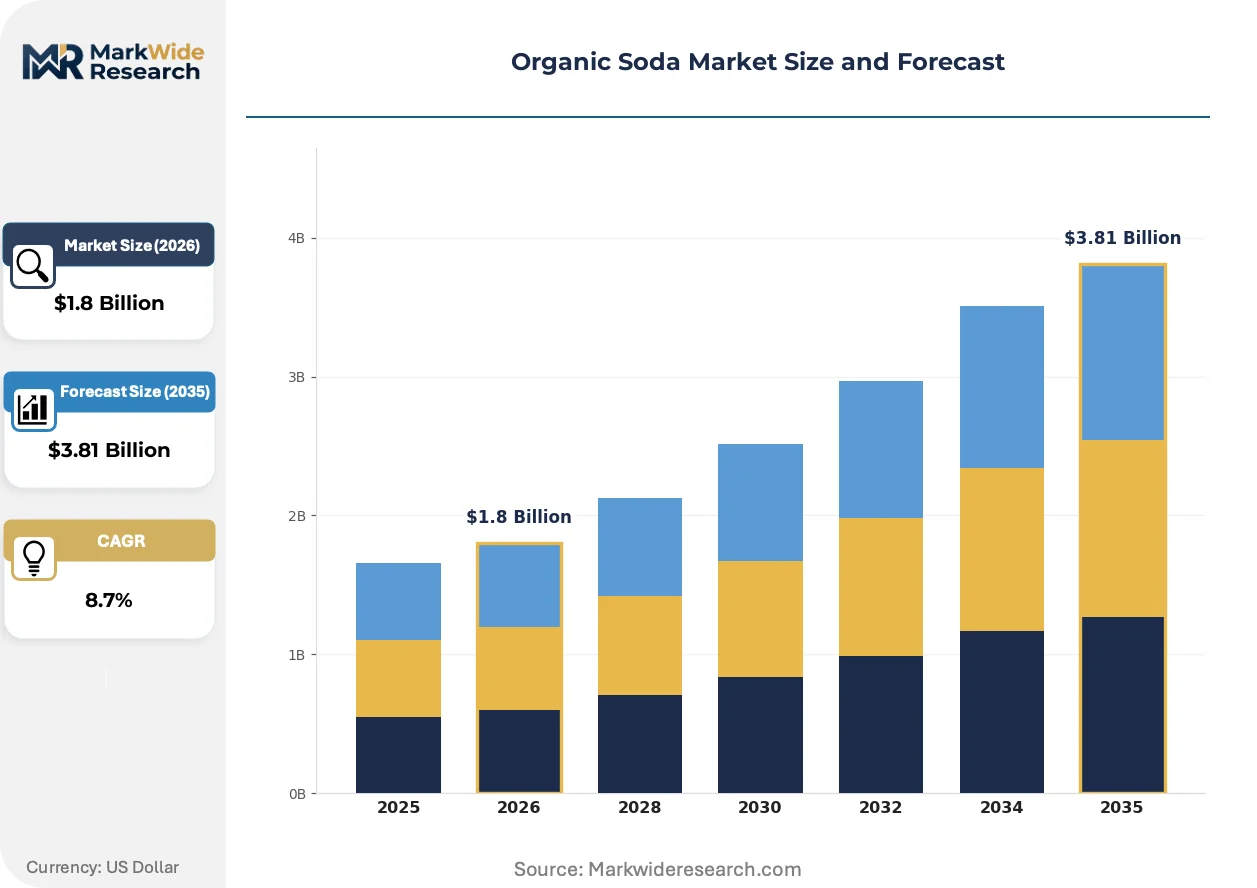
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cola, Lemon-Lime, Root Beer, Ginger Ale Ingredient: Organic Sugar, Natural Sweeteners, Herbal Extracts, Flavoring Agents Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Packaging Type: Cans, Bottles, Tetra Packs, Pouches |
| Companies Covered | Olipop, Poppi, Zevia, Reed's, Virgil's, Maine Root, Boylan Bottling Co, Jones Soda Co, Green Cola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Soda Market Evolving Landscape
Reformulation science and certification technology are converging to expand the addressable market for organic carbonated beverages beyond heritage natural-foods retail into mainstream convenience and foodservice channels.
Micro-encapsulation of organic fruit extracts is expanding into shelf-stable flavor systems that maintain volatile aromatic compounds through pasteurization and extended distribution cycles. Premium private-label programs at specialty grocers are adopting these stabilized concentrates to launch house-brand organic sodas without proprietary extraction infrastructure. The technology is compressing the capital barrier between contract manufacturing and captive production.
REACH chemical restriction protocols are forcing reformulation of conventional preservative systems across European export-oriented production facilities. The industrial consequence is accelerated R&D investment in organic-compliant antimicrobial alternatives such as cultured dextrose and rosemary extract blends. German and French retail buyers are now requiring full substance disclosure beyond ingredient lists to include processing aid documentation.
Younger demographics are prioritizing transparent supply chain storytelling over traditional brand equity in beverage selection decisions. Independent cafés in Pacific Northwest urban centers are replacing conventional fountain equipment with visible-draft organic soda systems that emphasize ingredient provenance. This behavioral pivot is most visible in coastal metropolitan clusters where menu transparency functions as competitive differentiation against national chain locations.
Organic Soda Market Segmentation
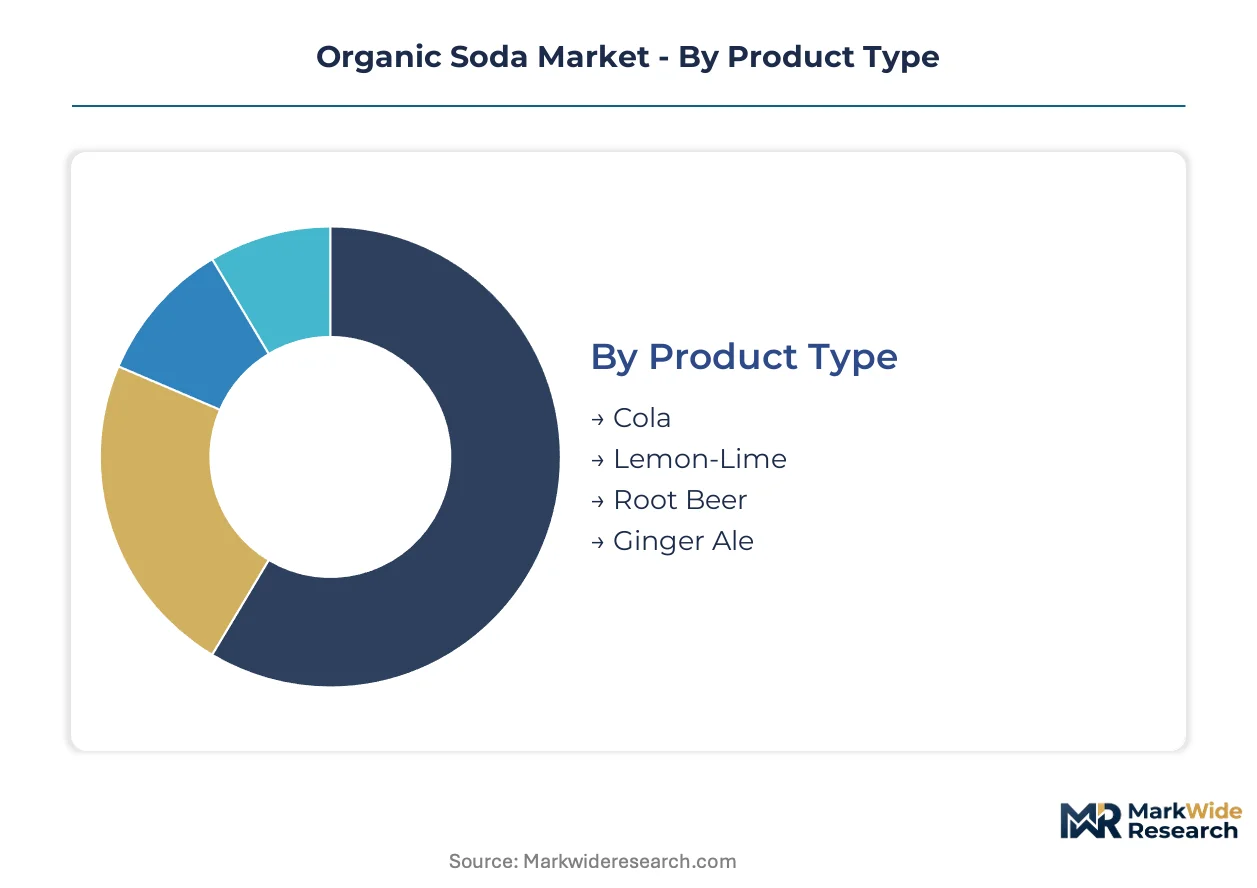
Organic soda segmentation reveals how certification requirements and channel economics concentrate production investment across flavor profiles and packaging formats. Manufacturers must align formulation decisions with distribution infrastructure constraints and end-use pricing power.
Product Type:
Supply concentration in cola and ginger ale production reflects established extraction infrastructure for natural flavor precursors and validated organic certification pathways.
- Cola:Formulations rely on kola nut extract and caramelized organic cane sugar achieving USDA Organic compliance. Demand concentrates in fast-casual restaurant fountain systems across coastal United States metropolitan clusters where menu differentiation commands premium pricing.
- Ginger Ale:Organic ginger root sourcing from Pacific Northwest agricultural cooperatives provides provenance narrative for health-conscious millennials. Independent cafés in Seattle and Portland are converting visible-draft installations to certified organic ginger ale lines.
- Lemon-Lime:Citrus oil micro-encapsulation technology enables shelf-stable organic formulations without synthetic preservatives.
- Root Beer:Sassafras-free recipes using wintergreen and birch bark extracts meet FDA GRAS standards for organic certification compliance.
Cola absorbs the bulk of installed capacity; lemon-lime is expanding most quickly among younger demographics prioritizing cleaner label transparency.
Ingredient:
Cost tier differentiation separates premium-positioned organic sodas from mid-market alternatives based on sweetener sourcing complexity and herbal extract concentration.
- Organic Sugar:Certified organic cane sugar from Brazilian and Indian harvests remains the benchmark for conventional taste replication. Price volatility in forward-contract agricultural markets compresses margins for producers lacking multi-year supplier relationships.
- Natural Sweeteners:Stevia-erythritol blends optimized through organic-compliant masking technologies enable sugar reduction without artificial additive classification. EU Green Deal packaging alignment creates export opportunity for stevia-sweetened portfolios.
- Herbal Extracts:Chamomile, lavender, and adaptogenic botanicals target functional wellness positioning in specialty grocery channels.
- Flavoring Agents:FEMA GRAS-certified natural flavors combined with organic certification compliance command premium formulation expertise in tight labor markets.
Organic sugar commands the largest procurement volume; natural sweeteners are gaining share fastest as sugar-reduction regulations tighten across multiple jurisdictions.
Distribution Channel:
Channel margin structures determine which organic soda formats achieve profitability, with slotting fee barriers and direct-to-consumer automation creating divergent competitive dynamics.
- Supermarkets:Premium shelf sets in coastal United States metropolitan clusters mandate USDA Organic certification for placement. Olipop and Poppi anchor refrigerated sections through prebiotic positioning and fruit-forward flavor profiles.
- Online Retail:Subscription-based repeat purchase automation bypasses traditional slotting fees and enables curated flavor assortment testing. Health-conscious Gen Z consumers in Pacific Northwest urban centers drive highest subscription retention rates.
- Health Food Stores:Heritage natural-foods retail maintains strict ingredient disclosure requirements beyond standard USDA Organic labeling.
- Convenience Stores:Single-serve can formats face pressure from conventional soft drink pricing benchmarks in impulse purchase environments.
Supermarkets absorb the bulk of installed capacity; online retail is climbing the fastest as direct-to-consumer infrastructure matures.
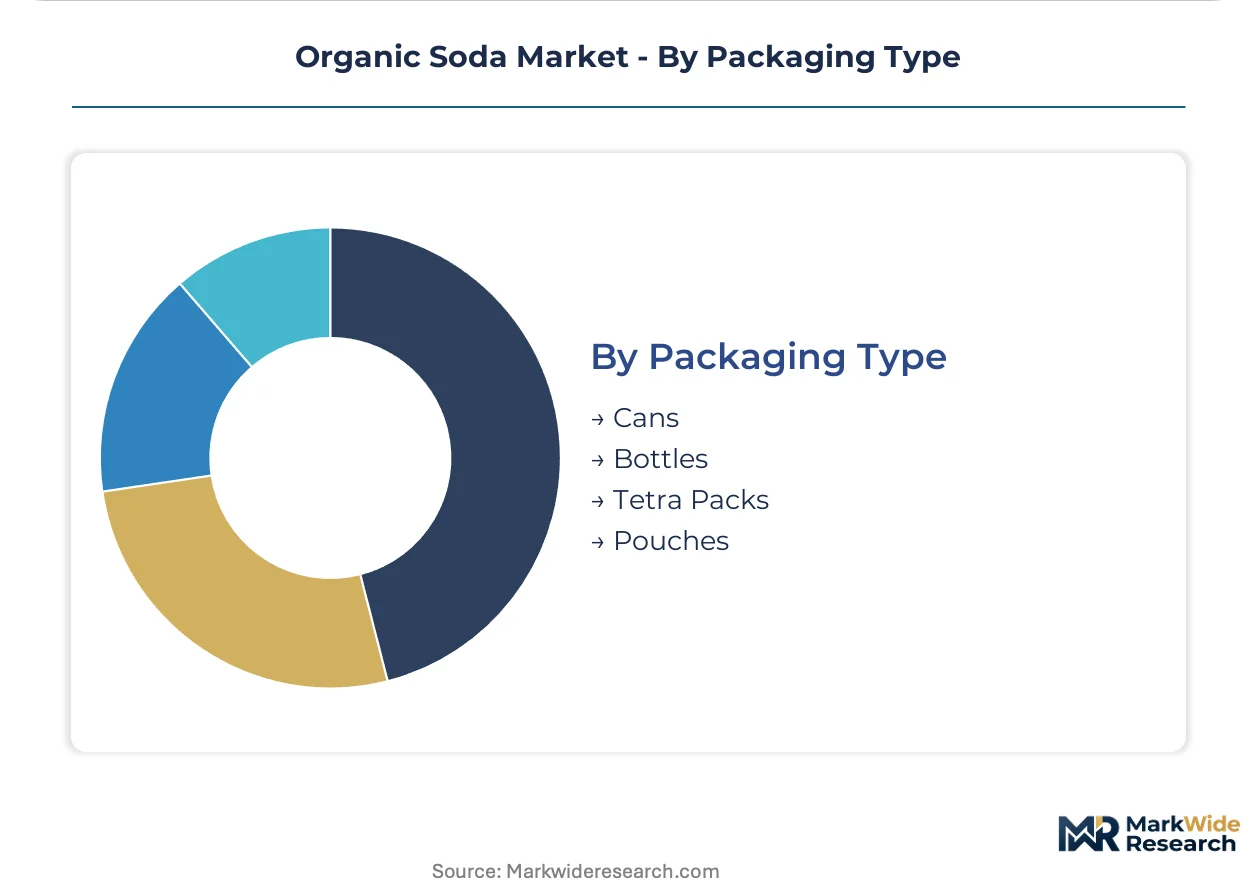
Packaging Type:
REACH-derived national implementations across European export markets are forcing biodegradable material transitions that favor existing sustainability-positioned organic brands.
- Cans:Aluminum recycling infrastructure and lightweight logistics economics dominate volume production. German and French retail buyers now require full substance disclosure for processing aids used in can lining materials.
- Bottles:Biodegradable bottle mandates under EU Green Deal implementations create first-mover advantage for organic brands with established sustainability positioning. rPET and plant-based alternatives command premium pricing in specialty channels.
- Tetra Packs:Aseptic carton formats suit ambient distribution in health food stores lacking refrigerated infrastructure.
- Pouches:Flexible packaging reduces shipping cube for online retail fulfillment, though organic certification compliance for multi-layer films remains complex.
Cans absorb the bulk of installed capacity; bottles are expanding most quickly under European regulatory pressure for packaging sustainability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban tracts across the United States are channeling investment into organic beverage manufacturing facilities near coastal population centers. These tax-advantaged structures concentrate production capacity within distribution range of high-density metropolitan markets.
United States
Health-conscious millennials in Pacific Northwest urban centers and coastal California metropolitan clusters drive specialty café procurement conversions. FDA beverage standards regulate additive thresholds and nutritional disclosure requirements. Seattle and Portland independent cafés are replacing conventional fountain equipment with visible-draft organic soda systems.
Germany
REACH chemical restriction protocols force reformulation of conventional preservative systems across export-oriented production facilities. ECHA substance disclosure mandates require full processing aid documentation beyond standard ingredient lists. Berlin and Hamburg retail buyers now require comprehensive substance disclosure for organic-compliant antimicrobial alternatives.
France
EU Green Deal packaging alignment creates first-mover advantage for brands with established sustainability positioning. EFSA organic labeling rules under evolving EU frameworks tighten ingredient traceability requirements. Paris metropolitan specialty grocers are mandating certified organic shelf sets in refrigerated beverage sections.
United Kingdom
Fast-casual restaurant procurement in London and Southeast England is converting fountain and bottled beverage lines to organic-certified SKUs. Health and Safety Executive guidelines intersect with EU-derived chemical restriction protocols for food-grade processing. Manchester and Birmingham urban centers show accelerating independent café adoption of certified organic carbonated drinks.
Canada
Health Canada and PMRA standards govern organic claim verification and pesticide residue thresholds for imported ingredients. British Columbia and Ontario urban clusters demonstrate concentrated demand from Gen Z consumers prioritizing cleaner label transparency. Vancouver specialty grocers are expanding refrigerated premium shelf sets for certified organic carbonated beverages.
Organic Soda Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-focused innovators commanding premium shelf positioning against legacy bottlers adapting conventional lines. The vendor base organizes around three archetypes: prebiotic functional specialists, stevia-sweetened sugar-reduction platforms, and heritage natural-foods heritage brands. Consolidation pressure is accelerating as slotting fee barriers in conventional grocery retail favor scaled players with direct-to-consumer infrastructure. Dominant competitive moves include strategic partnerships with Pacific Northwest agricultural cooperatives and portfolio diversification into biodegradable packaging formats.
Within the prebiotic functional tier, Olipop and Poppi exemplify formulation-first positioning that anchors refrigerated premium sections. Zevia occupies a distinct position among stevia-sweetened portfolios, representing sugar-reduction regulatory alignment. These three entities collectively demonstrate how certified organic certification combines with functional benefit claims to bypass conventional soft drink pricing benchmarks.
| Leading Market Players |
|---|
| Olipop |
| Poppi |
| Zevia |
| Reed's |
| Virgil's |
| Maine Root |
| Boylan Bottling Co |
| Jones Soda Co |
| Green Cola |
| Others |
Value Network & Pricing Analysis
Organic cane sugar futures on the ICE exchange cascade through contract manufacturing tiers into three distinct pricing bands. Premium shelf-stable formulations command forward-contract premiums from fast-casual restaurant chains, while spot-market dependent mid-tier brands absorb margin compression from Brazilian harvest volatility.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent separate organic-certified rush orders from standard contract windows. Three-tier pricing structure across premium refrigerated, standard ambient, and economy private-label levels stratifies by certification depth and sweetener sourcing complexity. Cost compression in the mid-tier is intensifying because Indian monsoon variability has eroded forward-contract security. Fast-casual restaurant procurement teams show lowest price sensitivity, while convenience store distributors face acute pressure from conventional soft drink benchmarks.
Supply Chain Analysis
Returns of defective aluminum cans flow through regional recycling cooperatives into rPET and biodegradable bottle feedstock streams. Raw ingredient sourcing concentrates in Brazil, India, and Pacific Northwest agricultural cooperatives for organic cane sugar, natural ginger root, and fruit extract precursors. Single-source dependency on petroleum-refinery-derived food-grade carbon dioxide creates vulnerability for organic certification documentation. Distribution runs through refrigerated trucking networks into coastal metropolitan clusters, with direct-to-consumer subscription automation bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA Organic transition timelines create a three-year soil-management bottleneck that props pricing for certified incumbent brands. Supply constraints in organic flavor chemist labor markets further reinforce margin protection for established players.
For Market Incumbents: Lock in multi-year forward contracts with Brazilian and Indian organic cane sugar harvests before monsoon volatility escalates. Secure exclusive refrigerated shelf sets at Pacific Northwest specialty grocers against stevia-sweetened entrants. Invest in captive organic flavor extraction infrastructure to reduce reliance on tight FEMA GRAS specialist labor markets. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription channels in Seattle and Portland urban centers, where Gen Z retention rates exceed conventional grocery conversion. Target lemon-lime flavor profiles with micro-encapsulated citrus oil technology that bypasses synthetic preservative dependencies. Leverage EU Green Deal biodegradable packaging mandates as first-mover differentiation in German and French export markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor prebiotic functional specialists with existing USDA Organic certification in Pacific Northwest manufacturing corridors. Five-to-ten-year viability hinges on backward integration into organic agricultural cooperatives rather than contract manufacturing dependence. Monitor EFSA organic labeling rule evolutions as the critical inflection signal for European export-oriented valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses slotting fee barriers at Kroger and Whole Foods refrigerated sections. |
| Backward Integration into Organic Agriculture | Captures Pacific Northwest ginger root and fruit extract supply before competitor contracting. |
| Biodegradable Packaging Transition | Aligns with EU Green Deal REACH implementations for German and French retail entry. |
| Prebiotic Formulation Patent Filing | Protects inulin and resistant starch positioning against Olipop and Poppi replication. |
| Fast-Casual Fountain System Conversion | Replaces conventional Coca-Cola and Pepsi equipment in coastal metropolitan clusters. |
Research Methodology
Independent corroboration across beverage brand managers, USDA Organic certification auditors, fast-casual restaurant procurement directors, and Pacific Northwest agricultural cooperative leads underwrites the qualitative findings. Secondary validation drew from FDA beverage standard filings, EFSA organic labeling rule dockets, Nielsen retail audit data, and ICE commodity futures records. Bottom-up volume modeling triangulated against top-down category expenditure estimates across the analysis window.
Comparable-period anchoring to historical organic certification expansion rates and fast-casual restaurant procurement conversion timelines shaped the projection horizon. The analytical framework modeled flavor profile segments, sweetener ingredient tiers, distribution channel economics, and packaging format regulatory clusters. CAGRs derived from organic cane sugar price elasticity coefficients and prebiotic functional beverage adoption curves. Forecast inputs incorporated USDA Organic transition period constraints and EU Green Deal packaging mandate implementation schedules.
Weather-induced agricultural supply shocks, EFSA regulatory timeline accelerations, and fast-casual restaurant chain bankruptcy waves are the dominant revision risks. Forecasts reflect documented assumptions on certification auditor capacity and refrigerated trucking network stability. Practitioners should monitor Brazilian harvest yield reports and ECHA substance disclosure mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Food and Beverages Market