
 India Organic Food Market | 2026-2036
India Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
India Organic Food Market Insights
Assorted organic staple bundles is broadening buyer choice beyond single-commodity purchases. 24 Mantra Organic leverages its pan-India procurement network to sustain shelf presence across tier-one and tier-two cities. Organic India anchors its position through Ayurveda-infused product lines that differentiate the brand in functional food aisles. Nourish Organics competes on clean-label snack formats that occupy premium retail space in modern trade channels.
Organic food comprises agricultural produce cultivated without synthetic pesticides, genetically modified organisms, or chemical fertilizers, relying instead on composting, crop rotation, and biological pest management to maintain soil fertility and ecological balance. The primary commercial purpose centers on delivering residue-free nutrition to consumers seeking traceable, environmentally sustainable food systems. Fruits and vegetables command the largest volume share due to daily consumption frequency and perishability-driven repeat purchases, while grains and pulses attract higher margin pools as pantry staples with longer shelf lives and stronger export eligibility. Online retailers represent the fastest-growing distribution channel as urban millennials prioritize doorstep delivery of certified assortments.
FSSAI's organic food regulations and India's NPOP certification framework administered by APEDA shape product standards, mandating traceability documentation and third-party audit compliance for domestic market access. BIS standards for processed organic goods further tighten quality thresholds, creating entry barriers for uncertified operators. Stakeholders must monitor evolving state-level organic farming missions and procurement subsidy structures that will determine regional supply scalability.
Market Dynamics
NPOP certification mandates and FSSAI alignment with organic standards are compressing market access timelines while fragmenting procurement networks across state-level organic missions. Compliance documentation now determines shelf eligibility faster than brand equity.
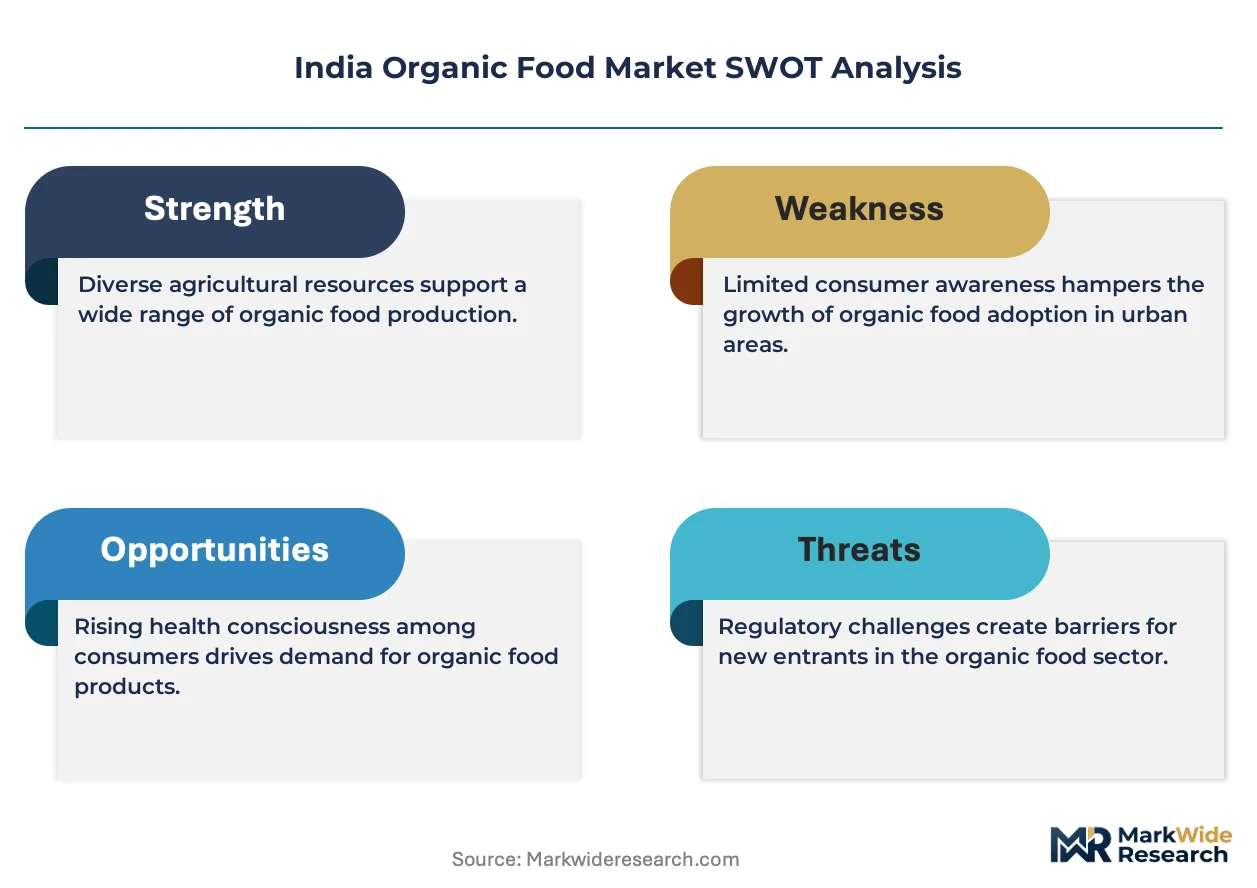
Growth Catalysts
- NPOP Certification Framework:APEDA-administered third-party audits create traceability infrastructure that premium retailers require for assortment inclusion. Tier-one urban households treat certification logos as non-negotiable purchase filters.
- State Organic Farming Missions:Karnataka and Maharashtra procurement subsidies expand certified acreage through direct farmer incentives. Regional supply scalability hinges on these state-level disbursement structures.
- Biological Pest Management:Pheromone trap networks and bio-pesticide spraying protocols reduce synthetic residue risk in export-bound consignments. APEDA-registered export units adopt these protocols to maintain EU and US market access.
Market Restraints
- Input Cost Volatility:Organic manure and bio-fertilizer prices fluctuate with monsoon-dependent biomass availability. Farmers in rainfed districts face working capital strain during drought cycles.
- Supply Concentration Risk:Certified organic seed stocks concentrate with three APEDA-authorized breeders. Germplasm scarcity limits crop diversification for farmers transitioning from conventional cultivation.
- Yield Gap Penalty:Organic conversion protocols mandate 24-36 month transition periods where fields yield conventional output without chemical inputs. Revenue loss during this window deters smallholder participation.
Strategic Opportunities
- Assorted Bundle Formats:Mixed-grain and pulse combinations attract urban millennials seeking variety without multiple SKUs. Modern trade channels allocate expanded shelf space to these curated assortments.
- PLI Scheme Alignment:Food processing incentives under India's Production Linked Incentive scheme subsidize organic cold chain infrastructure. Integrated pack-houses in Madhya Pradesh and Rajasthan capture this support.
- Ayurveda-Infused Positioning:Functional claims rooted in traditional medicine systems differentiate products in pharmacy and wellness retail. FSSAI's health supplement regulations provide compliant labeling pathways.
Industry Challenges
- Certification Timeline Compression:NPOP audit backlogs extend market entry by 8-14 months for new operators. APEDA's accredited agency capacity constraints create queue bottlenecks during harvest windows.
- Traceability System Integration:Blockchain and QR-code documentation platforms require capital outlay that cooperatives struggle to amortize. Digitization gaps persist in Maharashtra's tribal farming belts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Organic Food Market |
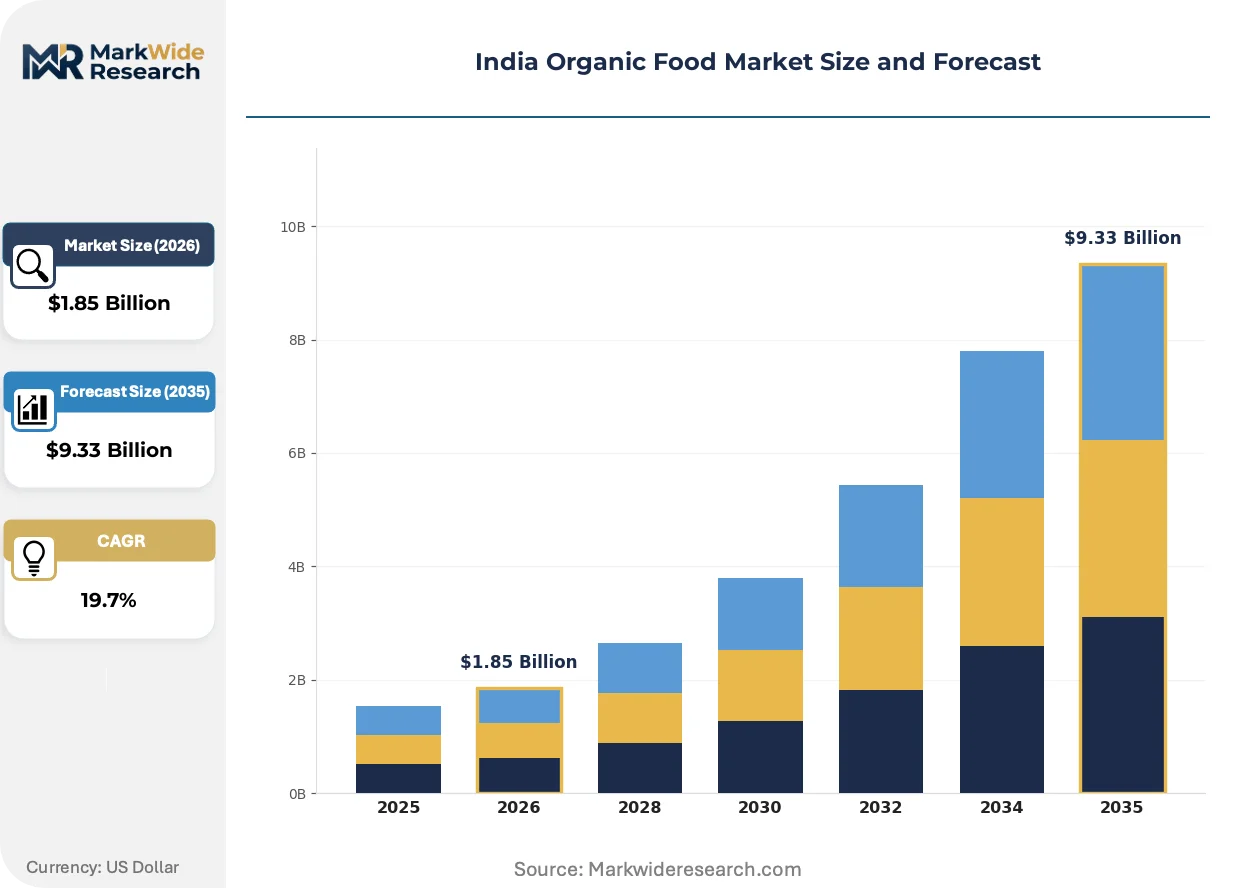
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $9.33 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Pulses Distribution Channel: Supermarkets, Online Retailers, Farmer's Markets, Organic Stores Consumer Type: Health-Conscious, Environmentally Conscious, Millennials, Families Certification: USDA Organic, Indian Organic Certification, EU Organic, Other Standards |
| Companies Covered | Nourish Organics, Pro Nature Organic, Organic India, Anveshan, Farm2Kitchen, 24 Mantra Organic, Organic Tattva, Zama Organics, Conscious Food, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Organic Food Market Trends and Innovations
Technology adoption across certification, cultivation, and distribution layers is compressing information asymmetries between producers and urban buyers. Three developments are restructuring competitive access.
Blockchain-enabled traceability platforms are modularizing supply chain verification into discrete, auditable segments. Export-oriented aggregators in Gujarat and Kerala deploy these systems to satisfy EU organic equivalence requirements. The technology is modularizing compliance costs so that smaller producer groups can access shared infrastructure rather than building captive systems.
FSSAI's 2023 organic food regulations mandate residue testing protocols that align with Codex Alimentarius standards. Processed organic manufacturers must now maintain batch-level documentation that previously applied only to raw commodity exporters. Snack and beverage segments face the steepest compliance ramp as they retrofit legacy quality systems.
Urban millennial households are consolidating weekly purchases through subscription-based organic basket services. Modern trade and quick-commerce platforms capture this demand rotation by locking in recurring delivery slots. Bengaluru and Mumbai exhibit the densest adoption as nuclear families prioritize convenience over price comparison.
India Organic Food Market Segmentation
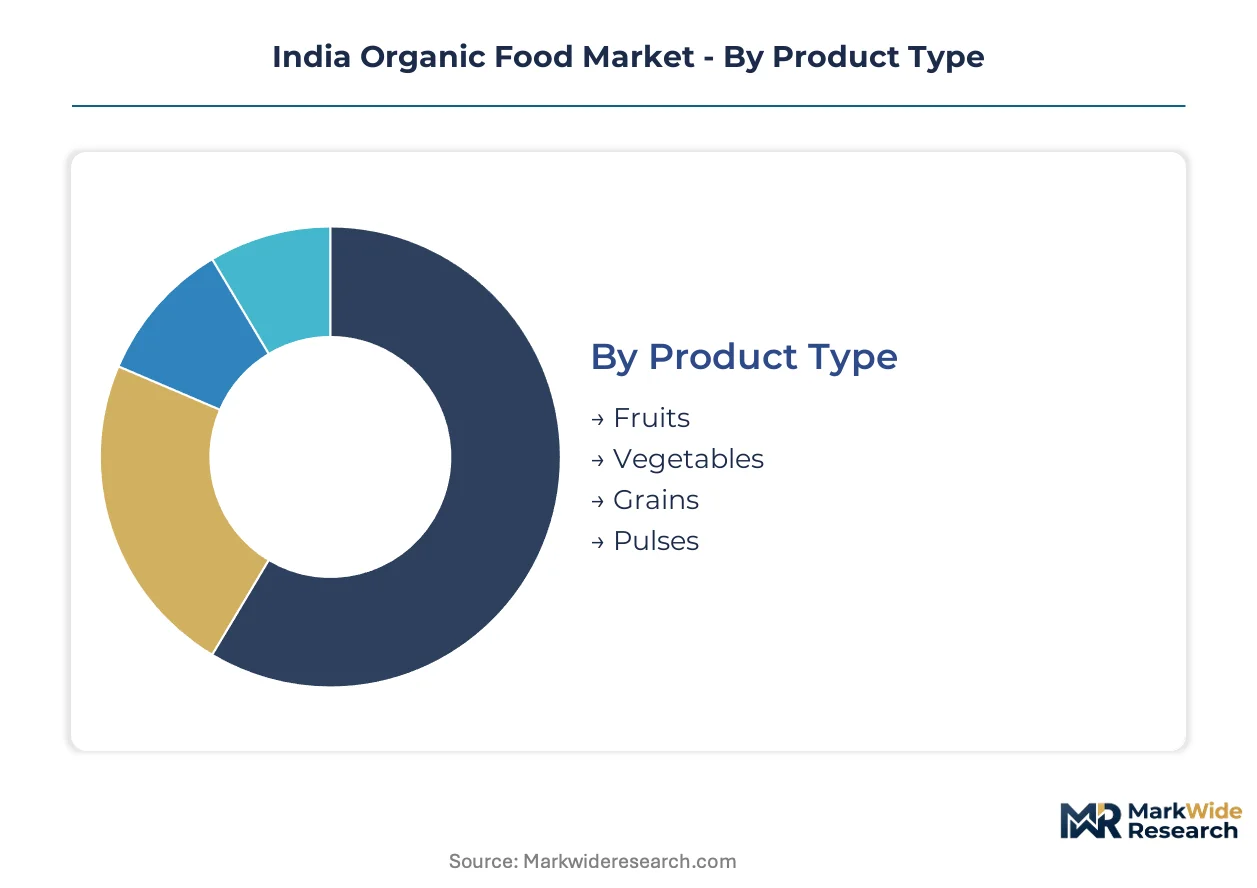
Organic food segmentation in India reflects divergent procurement behaviors across certification tiers and channel formats. Product specifications and traceability standards determine shelf eligibility more than price positioning in tier-one cities. Channel selection and consumer archetype mapping reveal where margin pools concentrate versus where volume scales.
Product Type:
Technical specifications around residue thresholds and shelf stability differentiate procurement economics across fresh and processed categories. NPOP certification mandates apply uniformly but compliance costs vary by perishability and handling requirements.
- Fruits:Daily consumption frequency drives repeat purchase cycles in urban households. Bengaluru and Mumbai modern trade channels allocate premium shelf space to certified tropical varieties including mangoes and pomegranates with export-grade documentation.
- Vegetables:Perishability compresses distribution radius to 150-200 kilometers for leafy greens, concentrating supply around metropolitan consumption belts. Leafy vegetables command the steepest price premiums due to residue sensitivity and cold chain dependency.
- Grains:Longer shelf lives and pantry staple status attract organized retail bundling strategies.
- Pulses:Export eligibility to Middle Eastern markets strengthens procurement contracting for certified varieties.
Grains lead on scale through pantry staple ubiquity; vegetables lead on momentum through quick-commerce adoption.
Distribution Channel:
Channel economics hinge on certification documentation requirements and consumer touchpoint intensity. Urban millennial households exhibit divergent behaviors across physical and digital purchase occasions.
- Supermarkets:Modern trade chains in Mumbai and Delhi enforce NPOP logo visibility as a non-negotiable assortment filter. Shelf slotting fees for certified organic SKUs run higher than conventional alternatives, compressing net margins for emerging brands.
- Online Retailers:Quick-commerce platforms capture recurring delivery slot commitments through subscription basket services. Bengaluru exhibits the densest adoption as nuclear families consolidate weekly purchases through app-based scheduling.
- Farmer's Markets:Direct producer-consumer interfaces bypass certification documentation gaps in tribal farming belts.
- Organic Stores:Specialized retail formats anchor trust through visible audit certificates and staff training on traceability protocols.
Supermarkets dominate current throughput; online retailers are climbing the fastest on urban convenience prioritization.
Consumer Type:
Purchase motivation segmentation maps to distinct price elasticity profiles and information-seeking behaviors across demographic cohorts.
- Health-Conscious:Residue avoidance drives premium willingness-to-pay for batch-tested produce with QR-code traceability. FSSAI-aligned testing documentation satisfies this segment's information requirements more than brand recognition.
- Environmentally Conscious:Soil health and water conservation claims resonate through packaging narratives and carbon footprint labeling. This cohort accepts price premiums for composting and crop rotation verification.
- Millennials:Subscription-based basket services lock in recurring purchase patterns with convenience prioritization.
- Families:Child-focused nutrition safety concerns elevate certification logo visibility in purchase decisions.
Health-conscious consumers anchor current revenue concentration; millennials show the steepest expansion trajectory on digital channel migration.
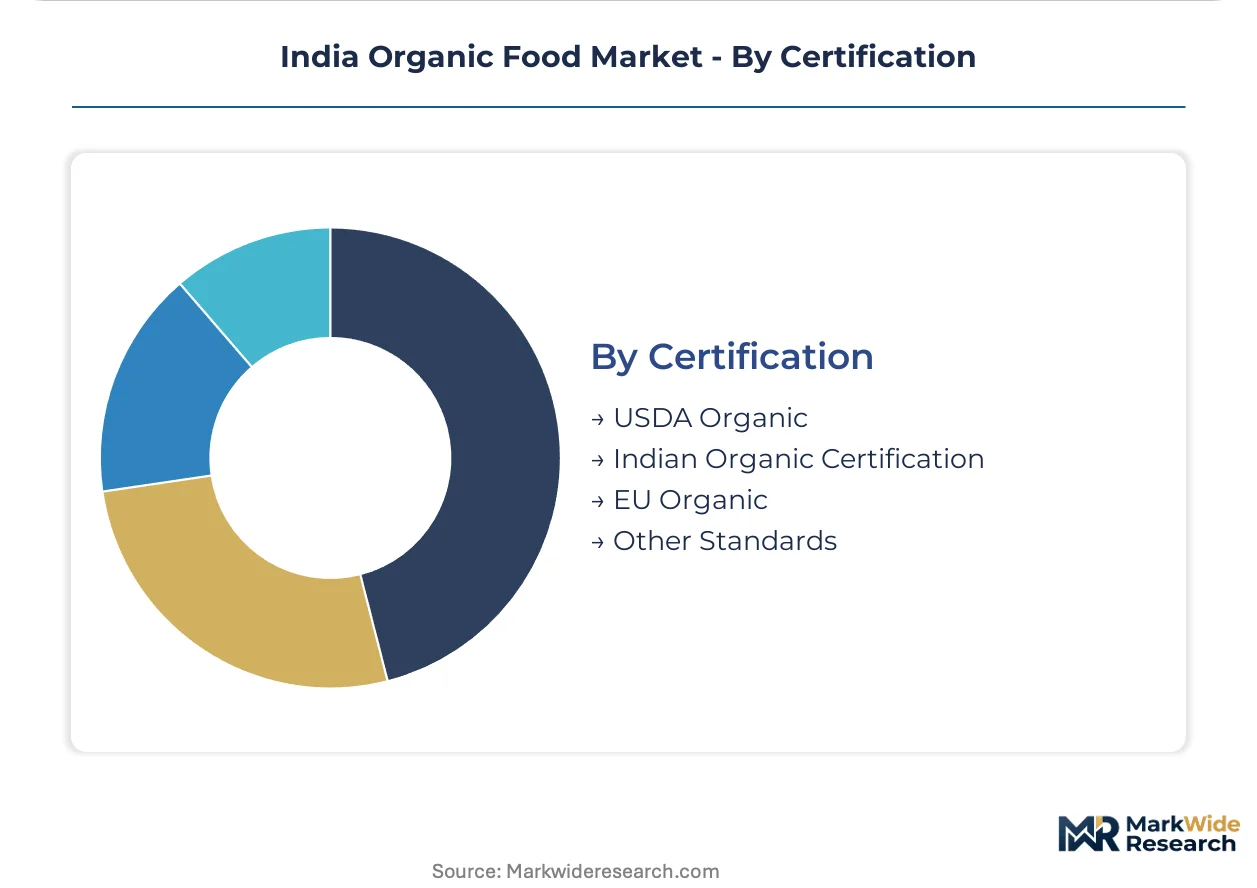
Certification:
Regulatory alignment determines market access scope across domestic and export-oriented production systems. Audit infrastructure availability shapes operator participation economics.
- USDA Organic:Equivalence agreements enable seamless EU market access for export-bound consignments from APEDA-registered units. Gujarat and Kerala aggregators deploy blockchain-enabled documentation to satisfy US-origin verification requirements.
- Indian Organic Certification:NPOP-administered third-party audits create the baseline domestic market entry credential. APEDA-accredited agency capacity constraints generate 8-14 month queue bottlenecks during harvest windows.
- EU Organic:Stricter residue thresholds command premium pricing in European destination markets.
- Other Standards:Japan Agricultural Standard and Swiss Organic certifications access niche high-value segments.
Indian Organic Certification dominates domestic volume; USDA Organic captures the highest export price realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's organic food sector traces its commercial roots to the 1990s export push by APEDA-registered units in Gujarat and Kerala, with domestic certification infrastructure scaling through NPOP formalization in the early 2000s. State-level organic farming missions now determine regional supply trajectories.
Maharashtra
Mumbai's nuclear families drive premium organic basket adoption through quick-commerce subscriptions. FSSAI's 2023 residue testing mandates tighten documentation requirements for processed organic manufacturers based in Pune and Nashik industrial belts. The Western Maharashtra cluster concentrates cold chain infrastructure for perishable organic vegetables supplying metropolitan retail.
Karnataka
Bengaluru's tech workforce exhibits the densest subscription-based organic purchase patterns nationally. Karnataka's state organic farming mission disburses direct procurement subsidies expanding certified acreage in Mandya and Mysuru districts. The Bengaluru-Mysuru corridor anchors integrated pack-houses capturing PLI scheme incentives for food processing infrastructure.
Gujarat
APEDA-registered export units in Gujarat deploy blockchain-enabled traceability platforms satisfying EU organic equivalence requirements. The state's tribal farming belts in eastern districts face digitization gaps in QR-code documentation systems. Gujarat's organic cotton and spice processing clusters supply residue-free consignments to European destination markets.
Kerala
Export-oriented spice aggregators in Kerala maintain EU and US market access through biological pest management protocols. The state's high-value organic cardamom and pepper segments command premium pricing in international markets. Kerala's cooperative structure struggles to amortize capital outlay for blockchain traceability platforms.
Madhya Pradesh
Rainfed districts in Madhya Pradesh experience working capital strain during drought cycles due to organic manure price volatility. The state's organic wheat and pulse cultivation concentrates around Indore and Ujjain procurement hubs. Integrated pack-houses in Madhya Pradesh capture PLI scheme subsidies for organic cold chain development.
India Organic Food Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and channel access dimensions. The vendor base fragments across pan-India procurement networks, Ayurveda-infused functional positioning specialists, and clean-label snack format innovators. Three archetypes dominate: certified staple aggregators with shelf presence across tier-one and tier-two cities; wellness-positioned brands leveraging traditional medicine systems; and convenience-format specialists occupying modern trade premium space. Competitive moves concentrate on geographic expansion through state-level organic mission alignment and portfolio diversification into assorted bundle formats.
Within the certified staple aggregator tier, 24 Mantra Organic leverages its pan-India procurement network to sustain shelf presence across urban retail formats. Organic India anchors its market position through Ayurveda-infused product lines that differentiate the brand in functional food and pharmacy channels. Nourish Organics occupies the clean-label snack specialist position, competing for premium retail space in modern trade and quick-commerce platforms.
| Leading Market Players |
|---|
| Nourish Organics |
| Pro Nature Organic |
| Organic India |
| Anveshan |
| Farm2Kitchen |
| 24 Mantra Organic |
| Organic Tattva |
| Zama Organics |
| Conscious Food |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap aggregators dominate procurement networks across Karnataka and Maharashtra, anchoring pricing discipline through direct farmer contracting that bypasses volatile spot markets for organic manure and bio-fertilizers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by NPOP certification tier and residue testing documentation depth. Premium tiers command substantial markups from health-conscious urban households in Bengaluru and Mumbai who treat FSSAI-aligned batch testing as non-negotiable. Price differentiation stems from certification grade and cold chain handling intensity. Cost compression in economy tiers is intensifying because rainfed districts face working capital strain during drought cycles. Quick-commerce subscribers exhibit lowest price sensitivity; tribal belt direct-procurement buyers show highest elasticity.
Supply Chain Analysis
Return flows of unsold perishables from modern trade channels feed composting networks that regenerate organic manure for Mandya and Mysuru district farms. Geographic supply concentrates in India, with secondary sourcing from Nepal and Sri Lanka for specific spice varieties. Raw material dependencies center on organic seed stocks from APEDA-authorized breeders, monsoon-dependent biomass for manure, and bio-pesticide formulations. Single-source vulnerability haunts germplasm supply as three breeders control certified organic seed stocks. Distribution runs through APEDA-registered export units for international offtake and quick-commerce platforms for urban household penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FSSAI's 2023 residue testing mandates are accelerating compliance investment and consolidating shelf access around documented operators.
For Market Incumbents: Cement procurement lock-in through backward integration into integrated pack-houses capturing PLI scheme subsidies in Madhya Pradesh and Rajasthan. Deepen state organic farming mission alignment to secure preferential farmer incentive disbursement. Threat of NPOP audit backlogs creating 8-14 month entry delays for competitors makes certification infrastructure the priority defensive lever. For New Entrants and Emerging Players: Tribal farming belts in Maharashtra's eastern districts present underserved buyer archetypes where digitization gaps in QR-code documentation exclude cooperative structures from premium retail channels. Penetrable white space sits in direct-to-consumer subscription formats bypassing modern trade slotting fees. Ayurveda-infused positioning offers compliant differentiation through FSSAI health supplement regulations. For Investors and Strategic Acquirers: Valuations sit cheapest among export-oriented aggregators with underutilized blockchain traceability infrastructure. Long-term viability hinges on EU and US market access maintenance through biological pest management protocol adoption. Acquisition target archetype: APEDA-registered units with dormant EU organic equivalence certification. Signal to watch is state-level organic mission budget allocation trajectories as inflection indicator for regional supply scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Chain Infrastructure | PLI scheme subsidies in Madhya Pradesh and Rajasthan reduce capital intensity for organic pack-houses. |
| NPOP Certification Fast-Track Investment | APEDA-accredited agency capacity constraints create queue bottlenecks that preemptive audit scheduling resolves. |
| Ayurveda-Infused Product Line Extension | FSSAI health supplement regulations provide compliant labeling pathways for functional food positioning. |
| Quick-Commerce Subscription Partnership | Bengaluru and Mumbai nuclear families consolidate weekly purchases through app-based delivery slot locking. |
| Blockchain Traceability Platform Deployment | EU organic equivalence requirements for export-bound consignments from Gujarat and Kerala aggregators mandate documentation upgrades. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with APEDA officials, FSSAI regulatory leads, modern trade category buyers, organic farming cooperative managers, and cold chain infrastructure operators with secondary validation from FSSAI organic food regulations, APEDA export registration databases, state organic farming mission budget documents, and NPOP certification audit records. Bottom-up acreage and production estimates triangulated against top-down retail channel throughput data.
Comparable-period anchoring tied projection models to historical certification issuance rates and export consignment volumes across the analysis window. Segmentation dimensions modeled included product type, distribution channel, consumer archetype, and certification tier. CAGRs derived from regression against input cost indices and urban household penetration curves. Forecast inputs incorporated monsoon variability patterns and PLI scheme disbursement trajectories.
Underlying measurement precision varies by segment; online retailer and quick-commerce channel data carry tighter precision than farmer's market and unorganized retail estimates. Forecasts embed assumptions around state subsidy continuity and APEDA audit capacity expansion. Practitioners should monitor FSSAI regulatory amendment cycles and EU organic equivalence agreement renewals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Organic Yogurt Market