
 Europe Organic Food Market | 2026-2036
Europe Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Food Market Analytics
Private-label organic sourcing is rewriting margin distribution across the Europe organic food value chain. Danone S.A. leverages its dairy fermentation expertise to anchor premium organic yogurt lines in French and German retail. Nestlé S.A. extends its plant-based R&D pipeline into certified organic infant nutrition, competing directly with specialized entrants. Alnatura controls Germany's largest dedicated organic store network, sustaining price discipline through backward integration into farming cooperatives.
Europe organic food comprises agricultural products and processed goods cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, meeting EU Regulation 2018/848 standards for soil health, animal welfare, and traceability. The primary commercial purpose is to supply health-conscious buyers with verified clean-label nutrition across retail and food service channels. Dairy and fresh vegetables capture the deepest margin pools as refrigerated supply chains limit competition and justify premium positioning. Online buyers represent the fastest-growing end-user segment as direct-to-consumer platforms bypass traditional wholesale markups. Supermarkets dominate volume flows, though specialty stores retain higher per-basket values through curated assortments and staff expertise.
The EU Green Deal and Farm to Fork Strategy mandate pesticide reduction targets and expand organic acreage to twenty-five percent of EU farmland, reshaping grower incentives and certification demand. EFSA and national bodies such as France's ANSES enforce residue limits and labeling accuracy, creating compliance barriers for uncertified imports. Stakeholders must monitor whether the EU's revised organic regulation tightens third-country equivalence rules and redirects sourcing toward European suppliers.
Market Dynamics
EU Regulation 2018/848 tightens certification standards while the Farm to Fork Strategy mandates twenty-five percent organic farmland conversion, forcing processors to rebuild supplier networks and cold-chain logistics around compliant domestic sourcing.
Growth Catalysts
- Farm to Fork acreage mandates:The EU Green Deal's binding organic land targets create guaranteed offtake for certified growers across France, Germany, and Italy, locking in decade-long procurement contracts with dairy processors.
- Refrigerated e-commerce infrastructure:Direct-to-consumer cold-chain platforms bypass traditional wholesale markups, capturing urban households in Berlin, Paris, and Milan with subscription-based fresh produce deliveries.
- Supermarket private-label expansion:Carrefour, REWE, and E.Leclerc dedicate expanding shelf space to store-brand organic lines, normalizing certified products for price-sensitive weekly shoppers.
Market Restraints
- Input cost volatility:Organic feed grain premiums fluctuate with conventional commodity cycles, compressing margins for livestock operators dependent on Ukrainian and Romanian suppliers.
- Supply concentration risk:Germany's Alnatura and France's Biocoop networks control dedicated retail distribution, limiting shelf access for unaffiliated processors outside cooperative structures.
- Third-country equivalence friction:EFSA scrutiny of non-EU organic certification creates import delays for processed ingredients from Turkey, Ukraine, and Latin American suppliers.
Strategic Opportunities
- Eastern European production expansion:Poland and Romania offer underutilized organic-certified farmland at lower lease rates than Western European counterparts, attracting Dutch and Danish dairy investors.
- Plant-based protein convergence:Fermentation-derived organic proteins hybridize with traditional legume processing, opening formulation partnerships between ingredient suppliers and meat-alternative brands.
- CSRD disclosure requirements:The EU's Corporate Sustainability Reporting Directive mandates supply-chain transparency, creating audit and certification service demand from mid-tier food manufacturers.
Industry Challenges
- Certification timeline compression:EU Regulation 2018/848's three-year conversion period for livestock and annual audits strain smallholder compliance capacity across Mediterranean member states.
- Cold-chain capex intensity:Dedicated organic handling facilities require segregated storage, transport, and processing equipment that multiplies infrastructure investment for multi-product processors.
- Traceability system integration:Blockchain and mass-balance documentation platforms must interface with legacy ERP systems, creating IT implementation bottlenecks for family-owned cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Food Market |
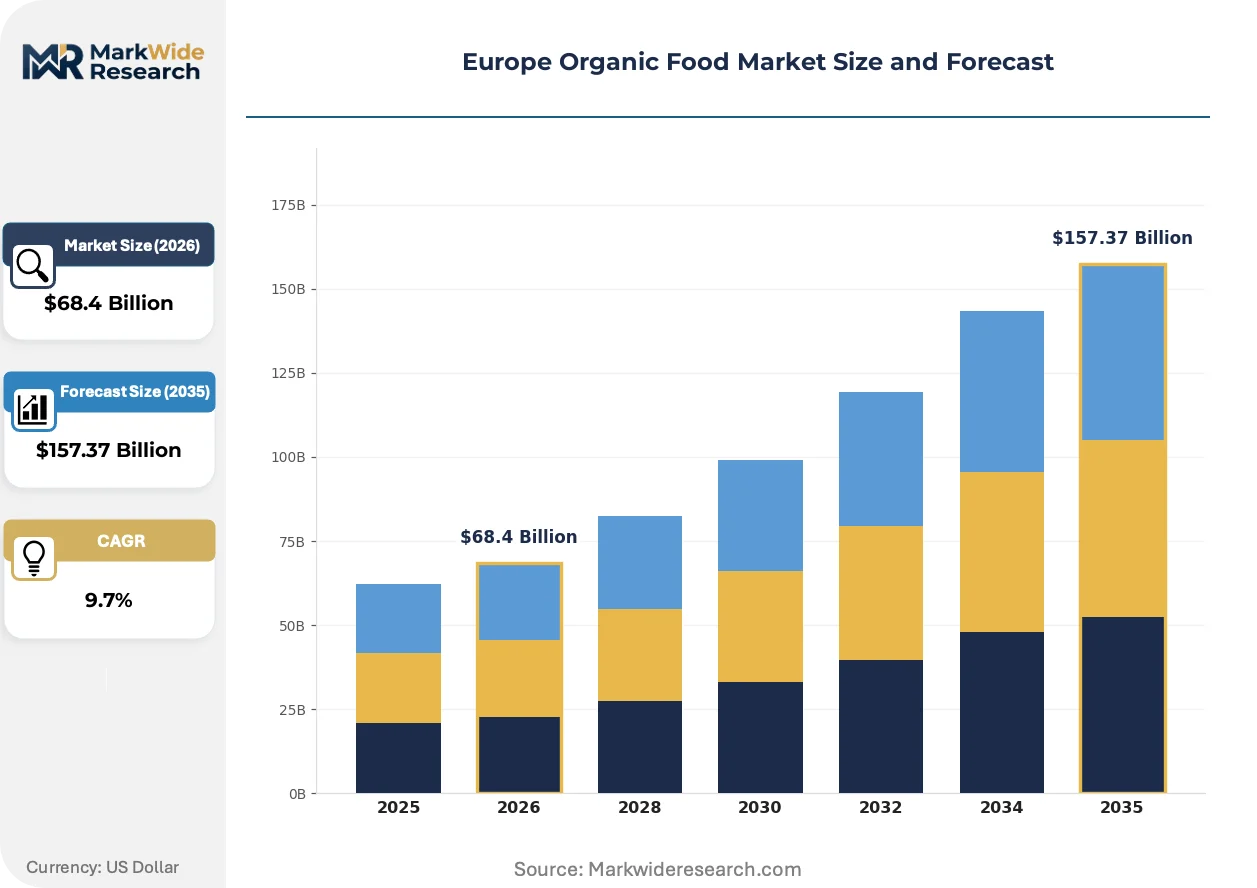
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Grains End User: Retail Consumers, Food Service, Wholesalers, Online Buyers Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Farmers' Markets Pricing Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Danone S.A., General Mills Inc., The Hain Celestial Group Inc., Amy's Kitchen Inc., Nestlé S.A., Alnatura, Biocoop, Sprouts Farmers Market Inc., WhiteWave Foods, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Food Market Evolving Landscape
Biological pest management, precision fermentation, and regenerative agriculture protocols are converging to redefine yield consistency and input substitution across European organic supply chains.
Precision fermentation for dairy proteins is hybridizing with traditional organic milk processing, enabling yogurt and cheese manufacturers to reduce livestock dependency while maintaining EU organic labeling eligibility. Dutch and Danish ingredient suppliers pilot these platforms for infant nutrition and sports nutrition applications. The technology compresses land-use requirements and stabilizes input costs against feed-price volatility.
EFSA's revised maximum residue limits for pesticides tighten enforcement of the EU Organic Regulation's contamination thresholds, triggering processor investment in segregated supply-chain infrastructure. National bodies including France's ANSES conduct unannounced inspections at import checkpoints. Italian and Spanish olive oil and wine exporters face heightened documentation requirements for third-country ingredient sourcing.
Subscription-based fresh produce boxes displace conventional supermarket trips for urban households in Hamburg, Lyon, and Vienna. Direct-to-consumer platforms source from regional grower cooperatives, cutting wholesale and retail margin layers. German consumers show highest adoption rates for weekly vegetable and dairy deliveries, while French buyers prioritize wine and specialty cheese curation.
Europe Organic Food Market Segmentation
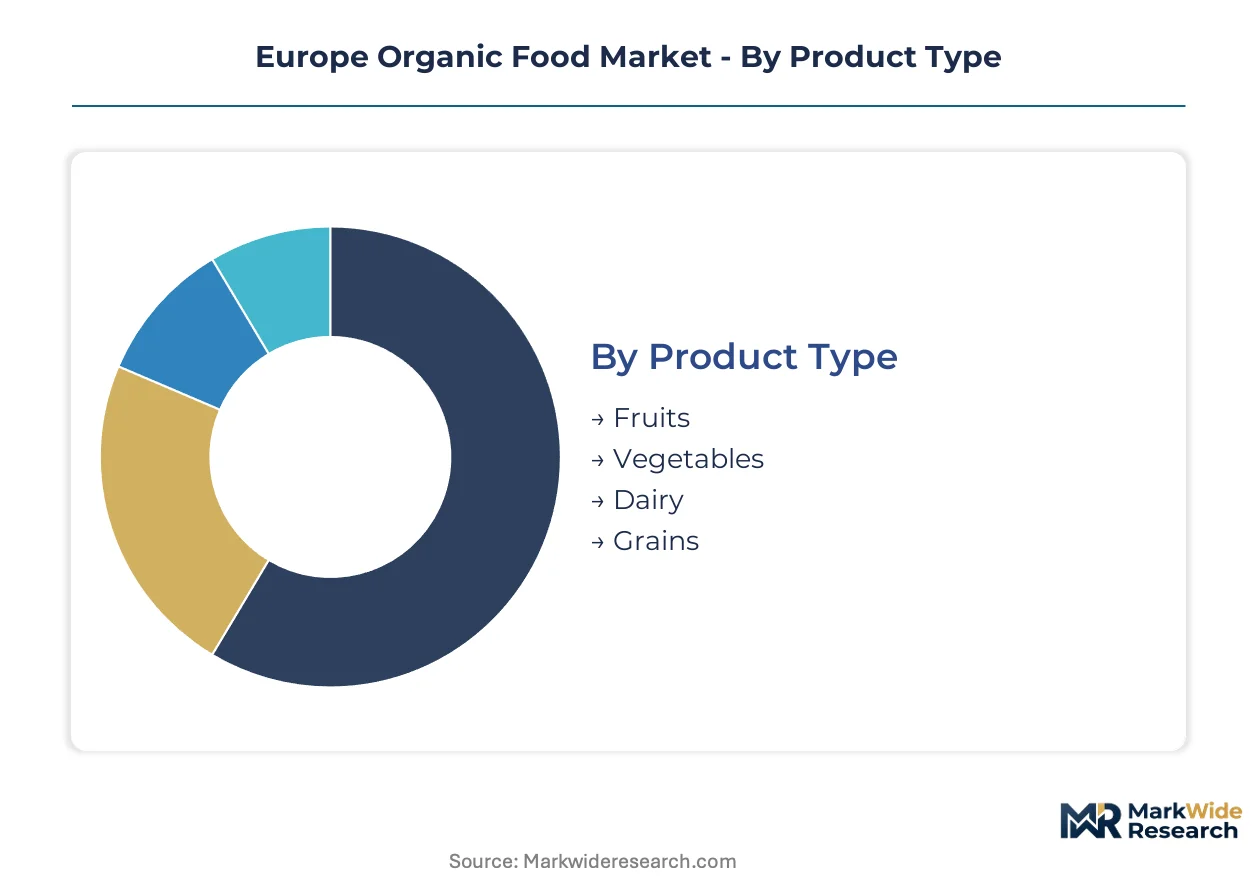
Organic food segmentation in Europe reflects divergent cold-chain requirements, certification complexity, and channel margin structures. Each dimension shapes procurement priorities for processors navigating EU Regulation 2018/848 compliance and Farm to Fork acreage mandates.
Product Type:
After-sales service intensity varies sharply across organic categories, with perishables demanding traceability support and shelf-life guarantees that dry goods rarely require.
- Vegetables:Leafy greens and root vegetables dominate fresh produce procurement contracts from French and German retail buyers. Cold-chain integrity requirements limit supplier pools to operators with dedicated organic handling infrastructure, compressing margins for uncertified competitors.
- Dairy:Yogurt, cheese, and fluid milk command the steepest organic premiums due to livestock conversion timelines and feed certification costs. German and Danish processors anchor supply agreements through backward integration into farming cooperatives.
- Fruits:Citrus and stone fruits from Spain and Italy face EFSA residue scrutiny at import checkpoints.
- Grains:Cereals and pulses from Eastern European suppliers offer volume scale with lower per-unit certification overhead.
By volume, Grains leads. By growth pace, Dairy is ahead.
End User:
Cost tier stratification separates institutional buyers seeking volume discounts from household purchasers prioritizing provenance verification.
- Retail Consumers:Weekly shoppers in France, Germany, and Italy drive demand for private-label organic lines at Carrefour, REWE, and E.Leclerc. Subscription fresh produce boxes are displacing conventional supermarket trips in Berlin, Paris, and Milan.
- Online Buyers:Direct-to-consumer platforms bypass wholesale markups, capturing urban households with curated vegetable and dairy deliveries. German consumers show highest adoption rates for weekly subscriptions.
- Food Service:Restaurants and catering operators source through specialized distributors with mass-balance documentation.
- Wholesalers:Traditional intermediaries face margin compression from platform disintermediation.
Retail Consumers account for the largest revenue pool. Online Buyers are expanding most quickly.
Distribution Channel:
Application-specific handling requirements separate channels by certification audit frequency and traceability system sophistication.
- Supermarkets:Shelf-space allocation for store-brand organic lines normalizes certified products for price-sensitive weekly shoppers. Carrefour and REWE dedicate expanding sections to private-label offerings.
- Specialty Stores:Alnatura's Germany-wide network and France's Biocoop cooperatives sustain higher per-basket values through staff expertise and curated assortments.
- Online Retail:Direct-to-consumer cold-chain platforms require segregated logistics infrastructure.
- Farmers' Markets:Regional grower cooperatives serve proximity-focused buyers in Hamburg, Lyon, and Vienna.
Supermarkets dominate volume flows. Online Retail is gaining share fastest.
Pricing Tier:
Margin concentration aligns with certification grade and supply-chain transparency investment, not merely ingredient quality.
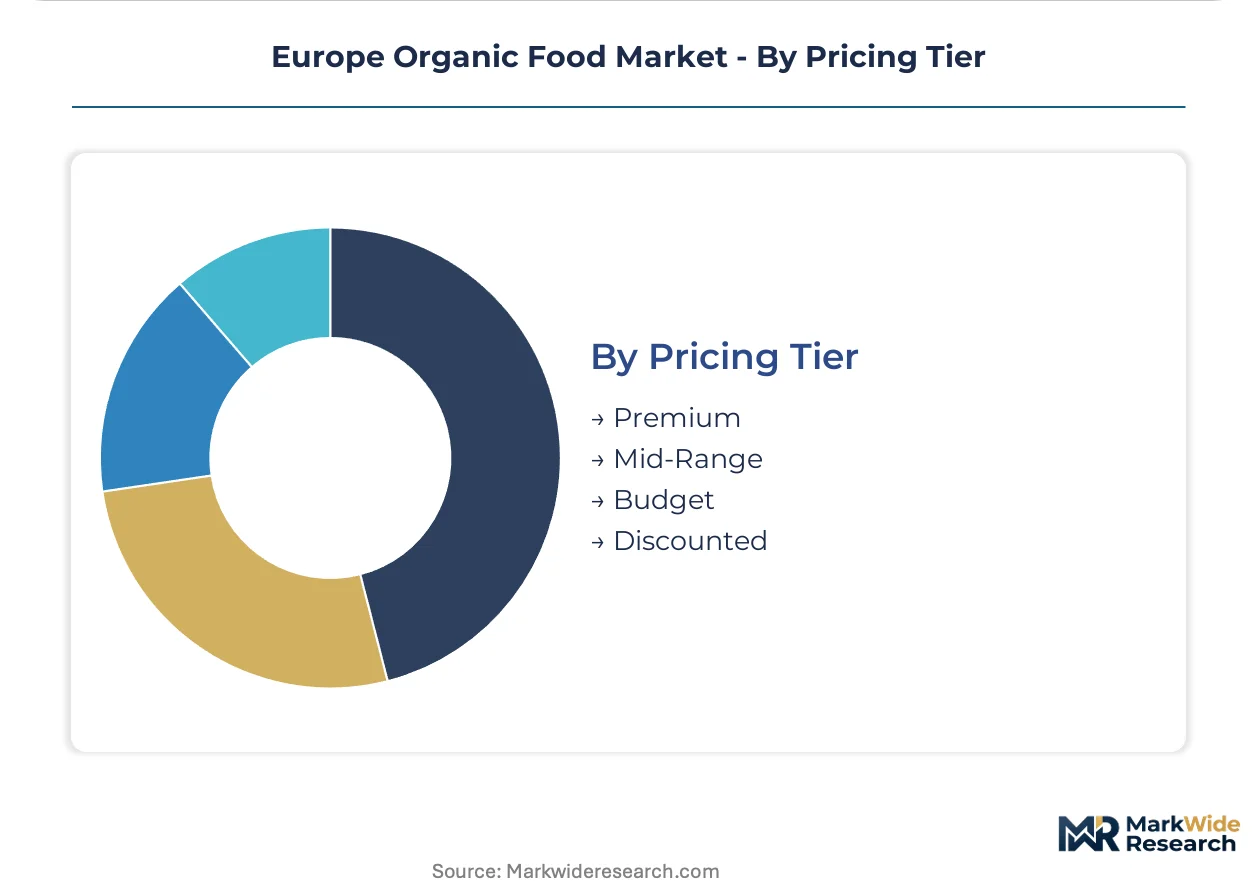
- Premium:Biodynamic and Demeter-certified products command the widest spreads, justified by livestock welfare protocols and soil health documentation. Dutch and Danish infant nutrition suppliers anchor this tier.
- Mid-Range:EU organic standard compliance without additional certification captures mainstream health-conscious buyers in France and Germany.
- Budget:Private-label organic lines at discounters normalize entry-level pricing.
- Discounted:Near-expiry and seasonal surplus channels clear perishable inventory.
Premium captures the deepest margin pool. Mid-Range shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for organic certification varies sharply across European markets, with German discounters driving volume through private-label penetration while French consumers absorb steeper premiums for provenance-verified specialty lines.
Germany
REWE and Edeka's store-brand organic ranges capture weekly household budgets through normalized pricing, while Alnatura's cooperative network sustains disciplined margin structures. The Federal Ministry of Food and Agriculture enforces strict organic conversion timelines under EU Regulation 2018/848. Bavarian dairy cooperatives around Munich anchor backward integration into livestock feed certification.
France
Carrefour and E.Leclerc dedicate expanding hypermarket sections to certified produce, though Biocoop's cooperative federation retains higher per-basket values in urban centers. ANSES conducts unannounced residue inspections at import checkpoints, tightening third-country ingredient documentation. The Provence-Alpes-Côte d'Azur cluster concentrates olive oil and wine exporters facing heightened EFSA scrutiny.
Italy
Conad and Coop Italia normalize organic shelf presence for price-sensitive Mediterranean shoppers, while specialty retailers in Milan and Rome curate regional provenance assortments. The Ministry of Agricultural, Food and Forestry Policies enforces national organic registry compliance alongside EU standards. Emilia-Romagna's processed tomato and dairy cooperatives invest in segregated cold-chain infrastructure.
Spain
Mercadona's private-label organic expansion compresses entry-level pricing for fresh produce, though Catalan specialty stores sustain premium positioning for artisanal lines. The Spanish Agency for Food Safety and Nutrition coordinates residue monitoring with EFSA protocols. Andalusian citrus and olive oil exporters around Seville face intensified documentation requirements for third-country ingredient sourcing.
Netherlands
Albert Heijn's organic range penetration reflects Dutch consumer willingness to absorb modest premiums for certified convenience. The Netherlands Food and Consumer Product Safety Authority enforces strict mass-balance documentation for processed organic goods. Dutch ingredient suppliers around Wageningen pilot precision fermentation platforms for dairy protein alternatives.
Europe Organic Food Market Competitive Landscape
Capability concentration sits with dedicated organic specialists; scale advantage sits with diversified multinationals with refrigerated distribution networks. The market structures around three tiers: cooperative-backed specialty retailers controlling shelf access, multinational processors leveraging fermentation and dairy expertise, and private-label dependent supermarket chains normalizing entry-level pricing. Dominant competitive moves include backward integration into farming cooperatives and cold-chain infrastructure expansion for segregated organic handling.
Among France-based multinational processors, Danone S.A. and Nestlé S.A. occupy positions anchoring premium organic dairy and infant nutrition lines through existing fermentation capabilities and retail distribution scale. Germany's Alnatura exemplifies the cooperative-integrated specialty retailer archetype, sustaining price discipline through captive supply relationships. These three represent the capability-scale spectrum: multinational R&D leverage versus cooperative network control.
| Leading Market Players |
|---|
| Danone S.A. |
| General Mills Inc. |
| The Hain Celestial Group Inc. |
| Amy's Kitchen Inc. |
| Nestlé S.A. |
| Alnatura |
| Biocoop |
| Sprouts Farmers Market Inc. |
| WhiteWave Foods |
| Others |
Value Network & Pricing Analysis
Undercapacity in Eastern European organic dairy processing is tightening procurement competition among German and French retailers, compressing spot-market premiums while locking buyers into longer conversion-timeline contracts. This utilization squeeze simultaneously elevates input cost pass-through leverage for certified cooperatives and forces supermarket chains toward private-label consolidation.
Pricing Analysis
Long-term offtake contracts dominate organic dairy procurement, with three-year livestock conversion timelines locking processors into fixed-price agreements with Bavarian and Danish cooperatives. Price differentiation rests on certification grade—Demeter biodynamic commands spreads above EU baseline—and volume scale, with REWE and Carrefour extracting tiered discounts through category captaincy. Cost compression in private-label tiers is intensifying because Mercadona and discounters are normalizing entry-level organic pricing. Food service distributors show highest price sensitivity due to mass-balance documentation costs, while specialty retailers absorb premiums for provenance-verified assortments.
Supply Chain Analysis
Contract-manufacturing concentration sits with Dutch and Danish dairy processors operating precision fermentation platforms for infant nutrition ingredients. Geographic supply concentrates in Germany, France, and Italy for finished goods, with Poland and Romania feeding raw milk and feed grain inputs. Raw material dependencies center on Ukrainian organic feed grains, French starter cultures, and Italian olive oil for blended products. Single-source vulnerability runs through Black Sea grain corridors disrupted by conflict-related logistics. Distribution runs through supermarket private-label networks and Alnatura's cooperative-controlled retail infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe organic food is cycling through a Farm to Fork-driven acreage expansion phase, with EU-mandated land conversion targets creating decade-long demand visibility for certified growers. This regulatory floor underpins cyclical recovery despite near-term input cost volatility.
For Market Incumbents: Harden cold-chain infrastructure through segregated organic handling facilities in Poland and Romania, insulating margin pools from EFSA residue scrutiny at import checkpoints. Deepen backward integration into farming cooperatives to secure feed grain supply against Ukrainian supply interruptions. Certification investment in Demeter and biodynamic tiers defends premium positioning against supermarket private-label normalization.
For New Entrants and Emerging Players: Pursue white-space in Eastern European production expansion, where underutilized organic-certified farmland offers lower lease rates than Western counterparts. Online subscription fresh produce boxes represent the most penetrable channel, with German urban households showing highest adoption velocity. Direct-to-consumer platform launches bypassing Alnatura and Biocoop cooperative gatekeepers unlock shelf access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure for dairy protein alternatives, shifting competitive economics toward scale players. Long-term viability over the coming decade favors processors with captive supply relationships and segregated logistics networks. Acquisition targets should exhibit cooperative-backed farming integration and CSRD-compliant traceability systems. The signal to watch is EFSA third-country equivalence rulings affecting Turkish and Ukrainian import flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Captive supply of certified organic feed grain secures margin pools against commodity volatility. |
| Precision Fermentation Platform Investment | Dutch and Danish suppliers reduce livestock dependency while maintaining EU organic labeling eligibility. |
| Segregated Cold-Chain Infrastructure Expansion | Dedicated organic handling facilities satisfy EFSA contamination thresholds and residue documentation requirements. |
| Direct-to-Consumer Subscription Launch | Urban households in Berlin and Paris bypass wholesale markups through curated fresh produce deliveries. |
| CSRD Compliance and Traceability Investment | Blockchain documentation platforms meet EU Corporate Sustainability Reporting Directive supply-chain transparency mandates. |
Research Methodology
A spread of perspectives from dairy processing executives, supermarket category buyers, organic certification auditors, and cooperative farming managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Regulation 2018/848 implementation documents, EFSA residue limit databases, and national organic registry filings from France's ANSES and Germany's Federal Ministry of Food and Agriculture. Customs trade data and retail audit metrics from Nielsen completed the evidence base. Bottom-up acreage conversion modeling and top-down retail revenue triangulation anchored volume and value estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeled across product type, end-user archetype, distribution channel, and pricing tier dimensions. CAGRs derived from acreage mandate trajectories under the Farm to Fork Strategy and historical elasticity patterns for organic premium absorption. Forecast inputs incorporated livestock conversion timelines, cold-chain infrastructure buildout rates, and third-country equivalence friction indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Eastern European dairy investors or accelerated precision fermentation adoption by multinational processors would shift outcomes. Regulatory uncertainty around EFSA third-country certification rulings and EU Green Deal pesticide limit revisions represent material revision risks. Quarterly review of organic acreage conversion progress, residue inspection enforcement intensity, and subscription platform customer acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Fast Food Market