
 Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market | 2026-2036
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market Analytics
Serum-based fibrosis staging with enhanced sensitivity thresholds is rotating toward center stage as the preferred non-invasive alternative to liver biopsy. Genfit leverages its proprietary algorithm development to anchor European clinical validation networks. Gilead Sciences sustains one of the industry's deepest NASH therapeutic pipelines, creating captive demand for companion biomarker solutions. Siemens Healthineers dominates imaging-integrated fibrosis assessment through its elastography platform ecosystem.
Non-alcoholic steatohepatitis biomarkers comprise quantifiable biological indicators—encompassing serum proteins, lipid metabolites, and cell-death fragments—detected through immunoassay, mass spectrometry, or imaging modalities to stage hepatic inflammation and fibrosis without tissue extraction. These markers serve primarily to stratify patients for clinical trials, monitor disease progression, and predict treatment response in a condition affecting approximately one-quarter of the global adult population. Fibrosis markers command the deepest margin pools owing to their direct linkage with liver-related mortality endpoints and regulatory acceptance as trial surrogates. Diagnostic tests represent the fastest-growing application dimension as payers and health systems seek alternatives to costly, invasive biopsy procedures with known sampling variability.
The FDA maintains stringent validation requirements for NASH biomarkers intended as surrogate endpoints, while the EMA's parallel scientific advice pathways enable synchronized transatlantic development strategies. Clinical Laboratory Improvement Amendments govern laboratory-developed test deployment in the United States, creating accreditation barriers that concentrate market access among established diagnostic platforms. Stakeholders must monitor evolving payer coverage determinations for non-invasive fibrosis tests, as reimbursement decisions will separate scalable commercial adoption from confined research-tool status.
Market Dynamics
Serum-based non-invasive staging is decomposing the liver biopsy monopoly, forcing diagnostic developers to recalibrate validation protocols around sensitivity thresholds rather than histological concordance alone.
Growth Catalysts
- EMA parallel scientific advice pathways:Synchronized transatlantic development reduces redundant clinical trials, compressing time-to-market for biomarker panels seeking dual regulatory acceptance.
- Clinical trial density in the United States:Pharmaceutical sponsors require companion diagnostics for pipeline stratification, creating captive demand for fibrosis staging algorithms.
- Mass spectrometry lipidomics platforms:Enhanced metabolite resolution enables multi-analyte signatures that outperform single-protein markers in predicting disease progression.
Market Restraints
- CLIA accreditation concentration:Laboratory-developed test deployment barriers limit market access to established diagnostic platforms with existing quality infrastructure.
- Histological reference standard variability:Sampling error and inter-observer disagreement in biopsy interpretation undermine biomarker validation studies.
- Reimbursement determination lag:Payer coverage decisions for non-invasive fibrosis tests remain inconsistent across commercial and public insurance frameworks.
Strategic Opportunities
- Pediatric NASH stratification:Underserved adolescent patient populations lack validated non-invasive alternatives to invasive assessment protocols.
- Artificial intelligence-enhanced elastography:Machine learning integration with imaging modalities is compressing operator dependency and expanding point-of-care deployment.
- Japan's PMDA early consultation framework:Expedited regulatory dialogue for novel biomarkers enables accelerated market entry in Asia-Pacific's second-largest pharmaceutical market.
Industry Challenges
- Cross-platform harmonization:Immunoassay standardization across Siemens, Roche, and Abbott instrument ecosystems requires extensive bridging studies.
- Surrogate endpoint negotiation:FDA acceptance of biomarker-based trial endpoints demands prolonged scientific advice cycles with uncertain outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market |
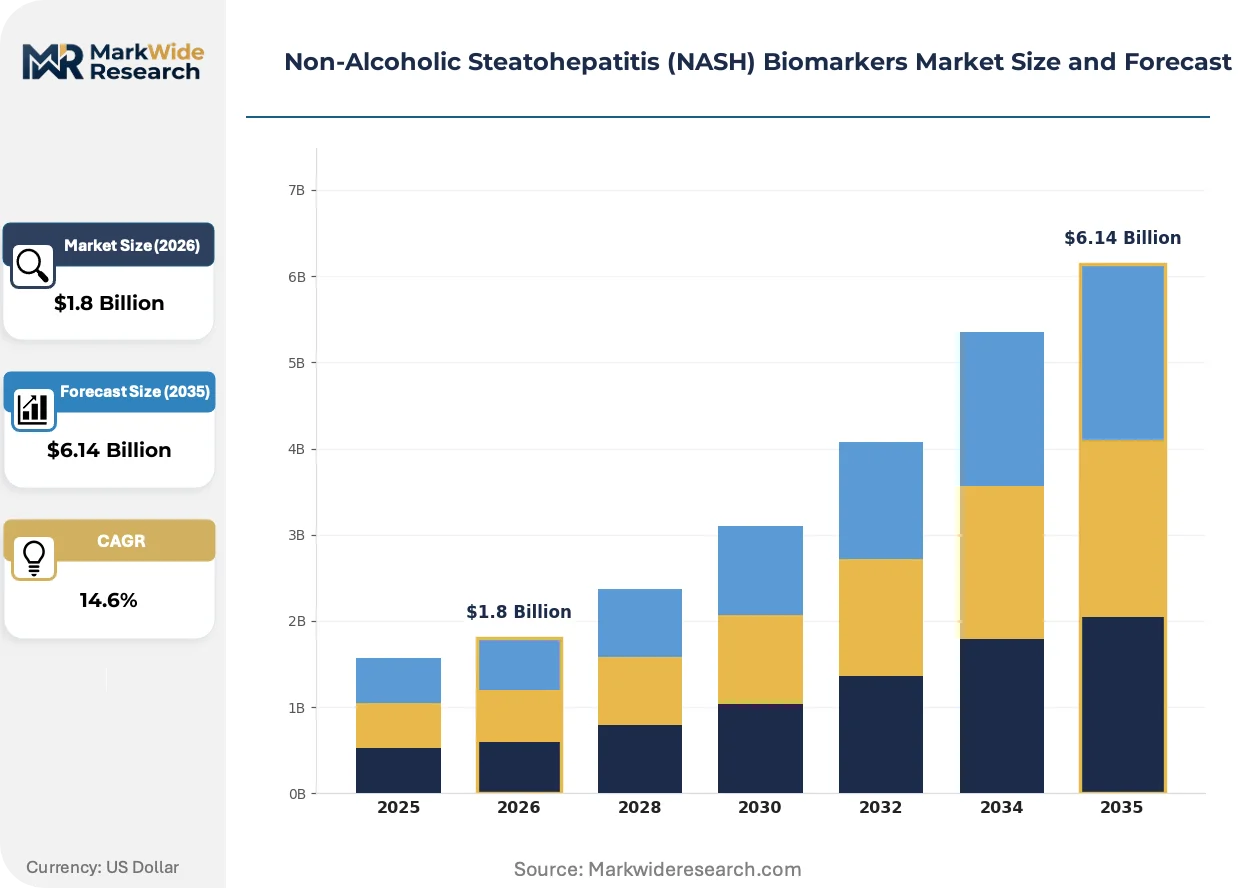
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biomarker Type: Inflammatory Markers, Lipid Profile, Fibrosis Markers, Apoptosis Markers Application: Clinical Trials, Diagnostic Tests, Research Studies, Drug Development End User: Hospitals, Diagnostic Labs, Research Institutes, Pharmaceutical Companies Delivery Mode: In Vitro, Point-of-Care, Laboratory-Based, Home Testing |
| Companies Covered | Genfit, Gilead Sciences, Novartis, Pfizer, Bristol-Myers Squibb, Roche Diagnostics, Siemens Healthineers, Quest Diagnostics, Labcorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market Evolving Landscape
Multi-omics integration is displacing single-analyte dominance, compelling developers to architect composite algorithms that fuse proteomic, metabolomic, and imaging signals into unified staging scores.
Magnetic resonance elastography is decomposing the invasive biopsy workflow for pharmaceutical sponsors. Phase III trial designers at Gilead Sciences and Intercept Pharmaceuticals now specify MR elastography as the primary stratification tool. This compression of tissue-based verification is reshaping site selection criteria and patient recruitment economics across the clinical research organization landscape.
REACH registration requirements for in vitro diagnostic substances are tightening supply chain documentation for European biomarker reagent manufacturers. The EMA's evolving quality expectations for companion diagnostic co-development are forcing parallel technical file preparation. Diagnostic developers with pre-existing ISO 13485 infrastructure are capturing first-mover advantage in synchronized FDA-EMA submissions.
Hospital procurement committees are consolidating vendor relationships around integrated platform ecosystems rather than discrete test menus. Health system executives at Kaiser Permanente and the Mayo Clinic now demand elastography-ultrasound convergence with automated reporting. This preference compression favors Siemens Healthineers and Philips over standalone serum assay specialists in United States capital equipment cycles.
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market Segmentation
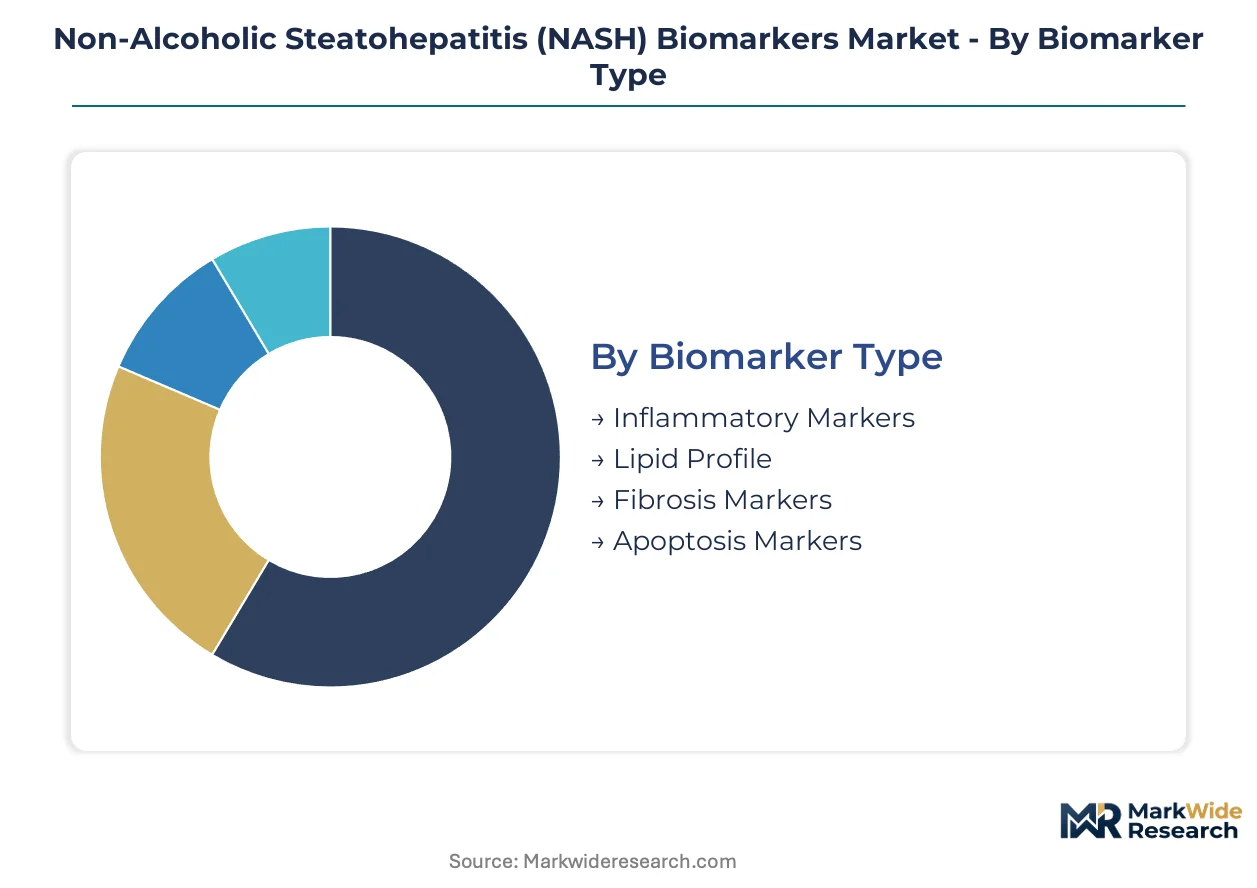
Biomarker developers must align product architecture with distinct procurement workflows across pharmaceutical sponsors, clinical laboratories, and hospital systems. Channel fragmentation demands differentiated validation strategies and pricing models for each downstream customer type.
Biomarker Type:
Serum assay manufacturers route inflammatory and lipid markers through high-throughput laboratory channels, while fibrosis staging tools integrate into imaging platforms and point-of-care devices.
- Fibrosis Markers:Quantifiable indicators of extracellular matrix deposition include ELF panel components, PRO-C3, and enhanced liver fibrosis scores. Pharmaceutical sponsors in the United States specify these markers as primary stratification tools for Phase III NASH trials, compressing demand toward CLIA-accredited reference laboratories with validated mass spectrometry infrastructure.
- Inflammatory Markers:Cytokine signatures and chemokine panels detect hepatic necroinflammation through multiplex immunoassay platforms. European clinical networks concentrate procurement through centralized hospital laboratories seeking EMA-aligned validation packages for companion diagnostic co-development.
- Lipid Profile:Lipidomics platforms quantify steatosis progression through circulating phospholipid and triglyceride metabolite signatures.
- Apoptosis Markers:Cell-death fragments including cytokeratin-18 and caspase-cleaved products indicate hepatocyte injury severity.
By volume, inflammatory markers lead due to broad screening applications. By growth pace, fibrosis markers are expanding most quickly on regulatory acceptance momentum.
Application:
Cost tier separation distinguishes premium-priced companion diagnostics for drug development from standardized clinical laboratory assays.
- Diagnostic Tests:Non-invasive staging panels for patient stratification in hepatology clinics deploy through hospital outreach laboratories and regional reference networks. Payer coverage determinations in the United States and Germany dictate commercial scalability beyond research-tool status.
- Clinical Trials:Biomarker-qualified central laboratories serve pharmaceutical sponsors with protocol-specific validation and longitudinal sample banking. FDA scientific advice pathways and EMA parallel consultation frameworks compress development timelines for surrogate endpoint qualification.
- Drug Development:Target engagement markers and pharmacodynamic indicators support pipeline decision-making from preclinical through Phase II stages.
- Research Studies:Academic consortia and government-funded epidemiological programs drive exploratory biomarker discovery with less stringent analytical validation requirements.
Diagnostic tests dominate current procurement volume. Clinical trials command the steepest expansion trajectory as pipeline density accelerates.
End User:
Customer type dictates contract structure, with pharmaceutical sponsors demanding multi-year companion diagnostic partnerships and hospitals preferring capitated platform agreements.
- Pharmaceutical Companies:Integrated drug-diagnostic co-development programs require biomarker developers to align technical file preparation with therapeutic IND timelines. Gilead Sciences, Intercept Pharmaceuticals, and Genfit sustain captive demand for proprietary algorithm validation.
- Diagnostic Labs:Quest Diagnostics and LabCorp in the United States, plus Synlab and Unilabs in Europe, consolidate purchasing power around automated immunoassay and mass spectrometry menu expansion.
- Hospitals:Integrated delivery networks including Kaiser Permanente and the Mayo Clinic specify elastography-ultrasound convergence with automated reporting.
- Research Institutes:Academic medical centers and government laboratories drive early-stage biomarker discovery with flexible procurement mechanisms.
Diagnostic labs lead by test volume. Pharmaceutical companies are gaining share fastest on pipeline investment cycles.
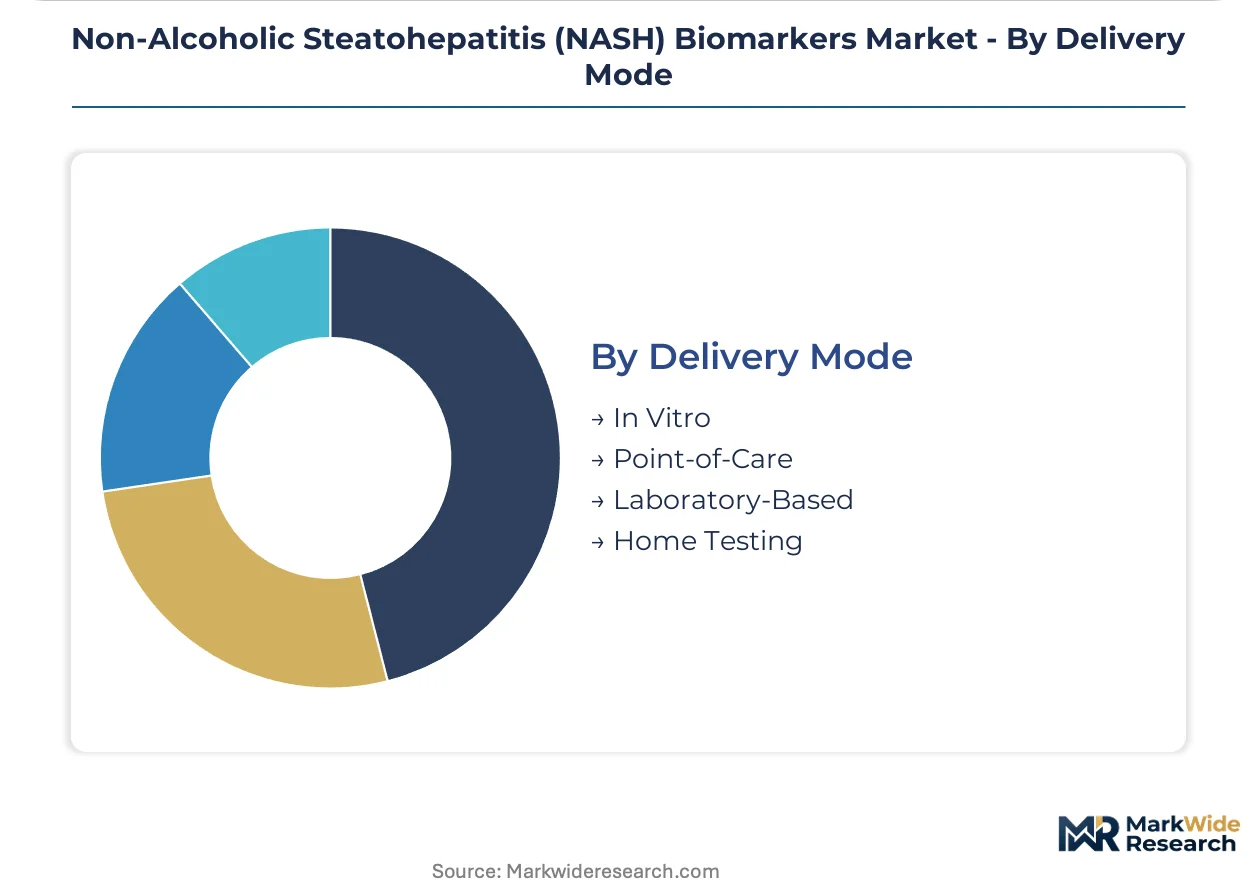
Delivery Mode:
Maturity gradients separate established laboratory-based workflows from emerging point-of-care and home testing modalities still seeking regulatory clearance.
- Laboratory-Based:Centralized high-complexity testing with mass spectrometry and automated immunoassay platforms delivers quantitative multi-analyte panels. CLIA accreditation and ISO 15189 certification requirements concentrate market access among established diagnostic infrastructure operators.
- Point-of-Care:Near-patient devices with simplified sample processing target hepatology clinics and primary care expansion. Siemens Healthineers and Philips integrate elastography with portable ultrasound to reduce operator dependency.
- In Vitro:Reagent and kit formats for laboratory-developed test deployment support customized assay configurations.
- Home Testing:Direct-to-consumer sample collection with mail-back analysis remains nascent pending FDA clearance for NASH-specific claims.
Laboratory-based systems dominate current deployment. Point-of-care modalities show the steepest growth curve on health system decentralization priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic infrastructure concentrates in the United States, Germany, Japan, and Switzerland where pharmaceutical trial density and reference laboratory networks create premium pricing power for validated biomarker platforms.
United States
Clinical trial sponsors at Gilead Sciences and Intercept Pharmaceuticals drive captive demand for companion diagnostic validation. FDA scientific advice pathways compress development timelines for surrogate endpoint qualification. Boston and San Francisco biotech clusters anchor centralized laboratory partnerships with Quest Diagnostics and LabCorp.
Germany
Siemens Healthineers leverages its Erlangen headquarters to integrate elastography platforms with hospital procurement networks. REACH registration requirements tighten supply chain documentation for European reagent manufacturers. Munich and Heidelberg medical centers concentrate mass spectrometry lipidomics validation studies.
Japan
PMDA early consultation frameworks accelerate regulatory dialogue for novel fibrosis staging algorithms. METI funding programs support point-of-care device commercialization in hepatology clinics. Tokyo and Osaka hospital systems specify automated reporting integration with existing ultrasound infrastructure.
Switzerland
Roche Diagnostics anchors European immunoassay standardization through its Basel operations. Swissmedic alignment with EMA parallel scientific advice enables synchronized transatlantic submissions. Zurich and Geneva reference laboratories consolidate purchasing power around multi-analyte panel expansion.
United Kingdom
EMA scientific advice utilization rates exceed European averages among British diagnostic developers. NHS England coverage determinations for non-invasive fibrosis tests dictate commercial scalability beyond research applications. London and Cambridge clinical research organizations reshape site selection criteria around MR elastography stratification.
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with imaging-integrated platforms commanding premium pricing against high-throughput laboratory assays. The market structure consolidates around three tiers: multinational diagnostic conglomerates with existing regulatory infrastructure, mid-cap biomarker specialists with proprietary algorithm portfolios, and regional reference laboratories with CLIA-accredited mass spectrometry capacity. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic expansion through ISO 13485-certified manufacturing footprints.
Within the pharmaceutical-integrated tier, Gilead Sciences and Genfit exemplify captive demand generation through proprietary pipeline investment. Among diagnostic infrastructure providers, Siemens Healthineers and Roche Diagnostics occupy positions as platform ecosystem anchors, with the former concentrating imaging-elastography convergence and the latter dominating automated immunoassay menu breadth. These three companies represent the archetype spectrum from therapeutic sponsor to equipment manufacturer to reagent supplier that structures competitive positioning in biomarker commercialization.
| Leading Market Players |
|---|
| Genfit |
| Gilead Sciences |
| Novartis |
| Pfizer |
| Bristol-Myers Squibb |
| Roche Diagnostics |
| Siemens Healthineers |
| Quest Diagnostics |
| Labcorp |
| Others |
Value Network & Pricing Analysis
CLIA accreditation requirements in the United States simultaneously gate laboratory-developed test deployment and stratify pricing power between established diagnostic platforms and emerging entrants, compressing margin capture toward ISO 13485-certified manufacturers with pre-existing quality infrastructure.
Pricing Analysis
FDA scientific advice pathways dictate the pricing tier structure for NASH biomarker validation services, separating premium companion diagnostic co-development contracts from standardized clinical laboratory assays. Price differentiation rests on EMA parallel consultation status and mass spectrometry infrastructure depth. Pricing pressure stems from hospital procurement consolidation around integrated elastography-ultrasound platforms. Pharmaceutical sponsors show lowest price sensitivity; regional reference laboratories face acute margin compression.
Supply Chain Analysis
Germany and Switzerland anchor European reagent manufacturing and immunoassay platform assembly for NASH biomarker deployment. Raw material dependencies include high-purity antibodies, stable-isotope metabolite standards, and magnetic resonance elastography hardware components. Supply chain risk centers on REACH registration documentation gaps for novel in vitro diagnostic substances. Distribution runs through CLIA-accredited central laboratories and hospital procurement networks rather than direct-to-clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment, where FDA surrogate endpoint qualification and EMA parallel scientific advice create multi-year validation barriers that protect incumbent diagnostic platforms from rapid displacement.
For Market Incumbents: Consolidate algorithm portfolios through proprietary lipidomics platform acquisition to counter mass spectrometry commoditization. Deepen CLIA-accredited laboratory partnerships in Boston and San Francisco biotech clusters to lock in pharmaceutical sponsor volume. Siemens Healthineers and Roche Diagnostics should compress point-of-care elastography development timelines before emerging Asian manufacturers achieve PMDA clearance.
For New Entrants and Emerging Players: Lead with pediatric NASH stratification as the most penetrable white-space segment, where validated non-invasive alternatives remain absent. Target Japan's METI-funded hepatology clinic networks through simplified sample processing devices. Pursue automated reporting integration with existing ultrasound infrastructure as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA acceptance of MR elastography as primary Phase III stratification tool reshapes the acquisition landscape toward imaging-integrated diagnostic developers. Five-to-ten year viability favors mid-cap biomarker specialists with ISO 13485 manufacturing footprints and synchronized FDA-EMA submission experience. Monitor EMA companion diagnostic co-development quality expectation evolution as the critical inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Aligns biomarker validation timelines with Gilead Sciences and Intercept Pharmaceuticals pipeline milestones. |
| CE Marking Pathway Expansion | Unlocks European hospital procurement through EMA-parallel technical file synchronization. |
| Mass Spectrometry Infrastructure Acquisition | Consolidates multi-analyte panel capacity for pharmaceutical central laboratory contracts. |
| AI-Enhanced Elastography Software Launch | Reduces operator dependency and expands point-of-care deployment in Kaiser Permanente networks. |
| Reimbursement Strategy Formulation | Secures CMS and commercial payer coverage determinations for non-invasive fibrosis staging. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads at diagnostic manufacturers and secondary analysis of FDA 510(k) filings anchors the qualitative findings. Conversations with hospital procurement managers at integrated delivery networks, biomarker development executives at pharmaceutical sponsors, and CLIA laboratory directors inform channel dynamics. Secondary sources include ClinicalTrials.gov protocol specifications, EMA scientific advice outcome summaries, CMS Medicare coverage determinations, and SEC 10-K disclosures from listed diagnostic conglomerates. Bottom-up test volume modeling and top-down pharmaceutical R&D expenditure triangulation yield convergent market sizing.
Sensitivity analysis across biomarker type, application, end user, and delivery mode segmentation dimensions structures the analytical framework. CAGRs derive from longitudinal pharmaceutical pipeline density tracking and payer coverage expansion modeling. Forecast inputs incorporate mass spectrometry platform installation rates and MR elastography site qualification timelines throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside FDA surrogate endpoint acceptance or EMA parallel consultation success would require recalibration. Forecasts reflect assumptions regarding reimbursement determination velocity and clinical trial sponsor consolidation patterns. Recalibration cycles align with material shifts in regulatory guidance and pharmaceutical pipeline investment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Antibody Testing Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Veterinary Molecular Diagnostics Market