
 Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market | 2026-2036
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market Insights
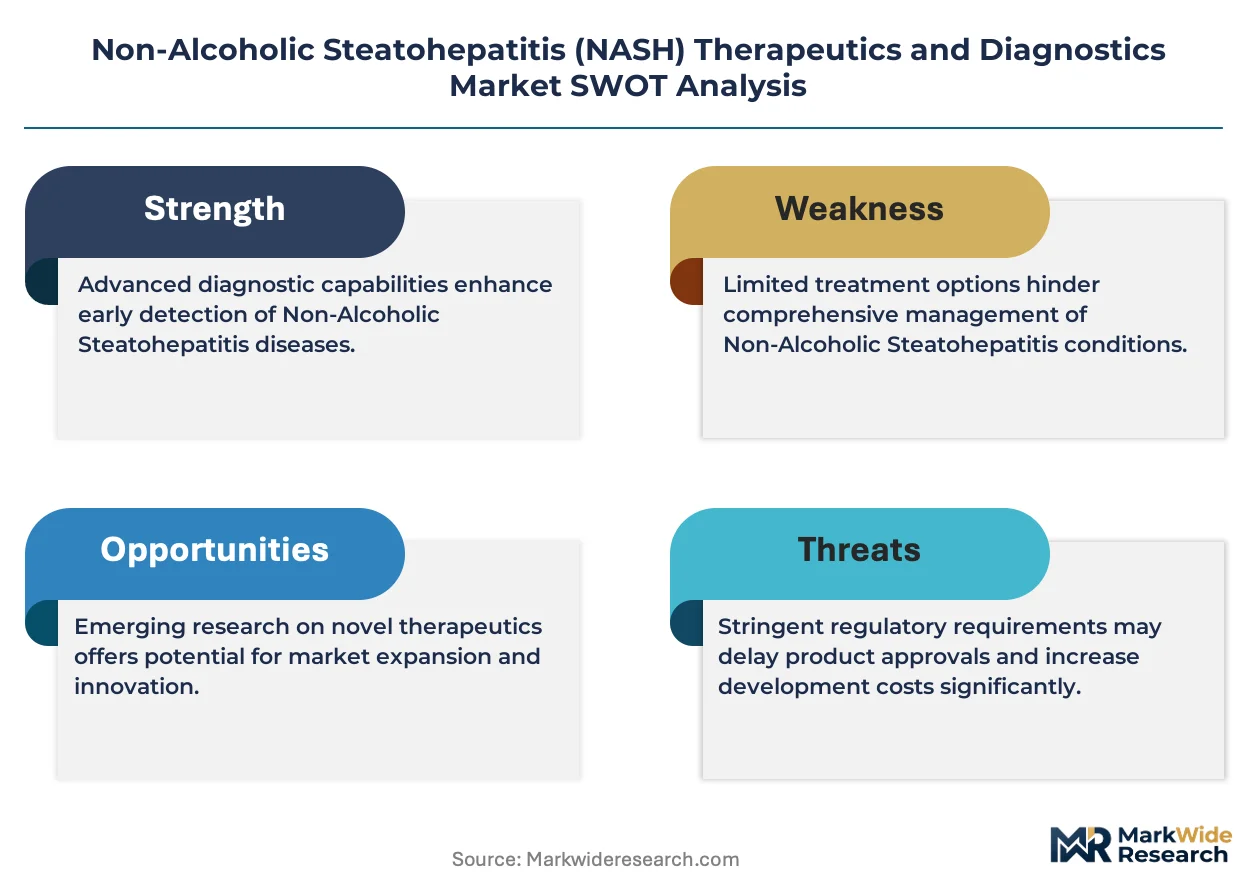
The NASH therapeutics and diagnostics market is shifting between premium-priced biologic therapies and commodity-tier small-molecule and dietary supplement alternatives. Madrigal Pharmaceuticals anchors its position through deep specialization in thyroid hormone receptor-beta agonism for liver-selective metabolic targeting. Novo Nordisk leverages its metabolic disease platform to extend competitive reach from diabetes into adjacent NASH populations. Gilead Sciences sustains R&D intensity across multiple mechanistic approaches despite prior late-stage setbacks.
Non-alcoholic steatohepatitis therapeutics and diagnostics encompass pharmacological interventions and clinical assessment tools designed to halt fibrosis progression, reduce hepatic inflammation, and enable non-invasive disease staging through biomarker panels and advanced imaging. The primary purpose centers on intercepting cirrhosis development before irreversible liver damage demands transplantation. Biologics command the deepest margin pools due to manufacturing complexity and targeted mechanisms, while diagnostic kits and biomarker analysis represent the fastest-expanding technology layer as clinicians abandon invasive biopsy protocols. Liver biopsy persists as a mature reference standard despite well-documented sampling variability and patient aversion.
FDA breakthrough therapy designation and EMA priority medicines pathways are compressing review timelines for NASH drug candidates, directly shaping sponsor investment priorities and clinical trial design. The EU Green Deal's pharmaceutical sustainability frameworks and REACH chemical safety standards are beginning to influence manufacturing site selection and supply chain disclosure requirements for active pharmaceutical ingredients. Stakeholders must monitor how evolving non-invasive diagnostic reimbursement codes in major markets reshape the economic viability of screening-at-scale models versus specialist-referral pathways.
Market Dynamics
FDA accelerated approval pathways are compressing clinical trial timelines while forcing sponsors to invest earlier in companion diagnostic development. This structural pressure is reshaping how therapeutic developers sequence their regulatory and commercial strategies.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA pathway compresses review timelines for NASH candidates with preliminary clinical evidence of substantial improvement over existing options. Sponsors now front-load biomarker validation to secure this status.
- Non-invasive Diagnostic Reimbursement:Medicare coverage decisions in the United States for elastography and multi-biomarker panels are replacing liver biopsy as the gatekeeper to specialty referral. Diagnostic kit manufacturers are scaling production capacity to meet this demand inflection.
- Metabolic Disease Platform Extension:Diabetes therapeutic developers are repurposing GLP-1 receptor agonist infrastructure for NASH indication expansion. This convergence leverages existing manufacturing networks and prescriber relationships.
Market Restraints
- Biopsy-dependent Endpoint Validation:Regulatory authorities continue requiring histological confirmation for accelerated approval, creating friction with patient recruitment. Sampling variability in NASH staging persists as a technical limitation no imaging modality has fully resolved.
- Active Pharmaceutical Ingredient Concentration:Complex peptide and biologic manufacturing concentrates among contract manufacturers in Switzerland and Ireland. Any disruption to these sites propagates through multiple sponsor pipelines simultaneously.
- Orphan Indication Competition:Sponsors of rare liver diseases command priority review vouchers that compress NASH candidates in FDA scheduling queues. This regulatory crowding extends time-to-market for fibrosis-targeted therapies.
Strategic Opportunities
- Pediatric NASH Protocol Development:The absence of approved therapies for adolescent populations creates a whitespace indication with distinct trial design requirements. Regulatory science investment here precedes competitor entry.
- EU Green Deal Manufacturing Incentives:REACH-compliant solvent recycling and renewable energy sourcing at API facilities qualify for ECHA certification advantages. Early adopters secure preferred supplier status with sustainability-mandated hospital systems.
- Pharmacy-based Screening Integration:Point-of-care fibrosis assessment devices are penetrating retail health clinics as a new patient identification channel. This bypasses traditional hepatology referral bottlenecks in underserved regions.
Industry Challenges
- Quantitative Imaging Biomarker Standardization:VCTE device manufacturers and MRI-PDFF platforms operate on non-harmonized calibration protocols. Cross-site trial data pooling requires expensive central reading infrastructure.
- Gene Therapy Manufacturing Scale-up:Viral vector capacity constraints limit AAV-based NASH candidates to small early-phase studies. Capital deployment for GMP suites outpaces current clinical demand visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market |
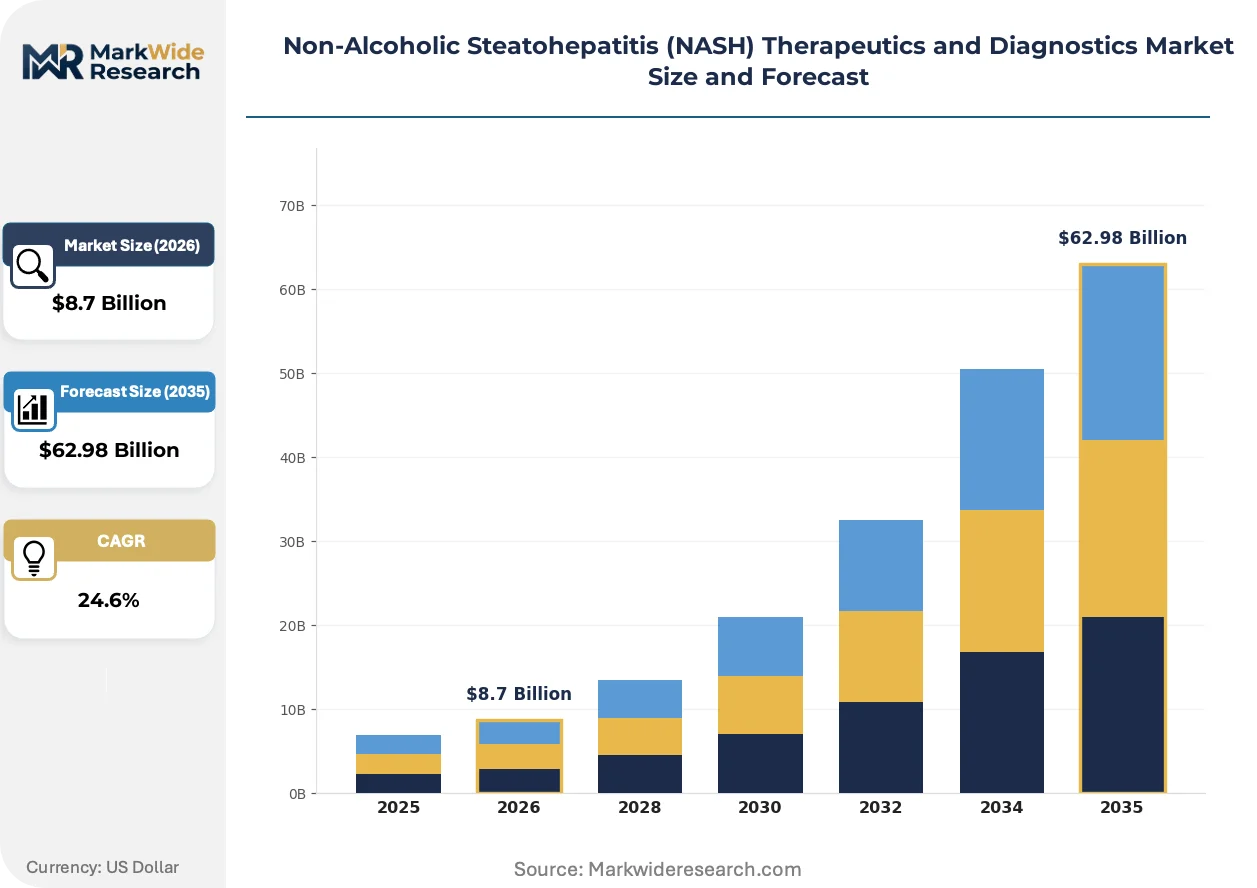
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Dietary Supplements, Diagnostic Kits Technology: Biomarker Analysis, Imaging Techniques, Genomic Testing, Liver Biopsy End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Delivery Mode: Oral, Injectable, Transdermal, Intravenous |
| Companies Covered | Madrigal Pharmaceuticals, Intercept Pharmaceuticals, Novo Nordisk, Gilead Sciences, Genfit, Akero Therapeutics, Siemens Healthineers, Novartis, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market Trends and Innovations
Artificial intelligence pattern recognition is displacing manual histopathology review while machine learning biomarker algorithms compress diagnostic staging into single blood draws. These parallel advances are collapsing the traditional separation between therapeutic development and diagnostic deployment.
Multi-omics biomarker panels are converging with electronic health record integration to enable population-scale risk stratification. Large integrated delivery networks in the United States are piloting automated screening triggers for at-risk diabetes patients. This convergence is compressing the interval between disease onset and specialist intervention from years to months.
EMA's priority medicines scheme is accelerating conditional marketing authorization for therapies demonstrating fibrosis regression without cirrhosis resolution. European sponsors are restructuring phase IIb trials to capture histological endpoints earlier. Small-cap biotechs without EU regulatory expertise are partnering with established CROs to navigate decentralized assessment procedures.
Hospital procurement committees are unbundling diagnostic service contracts from therapeutic purchasing agreements. Previously bundled liver biopsy and pathology services are being sourced separately from imaging and biomarker vendors. This pattern is most visible in United States academic medical centers where value analysis committees now dominate vendor selection.
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market Segmentation
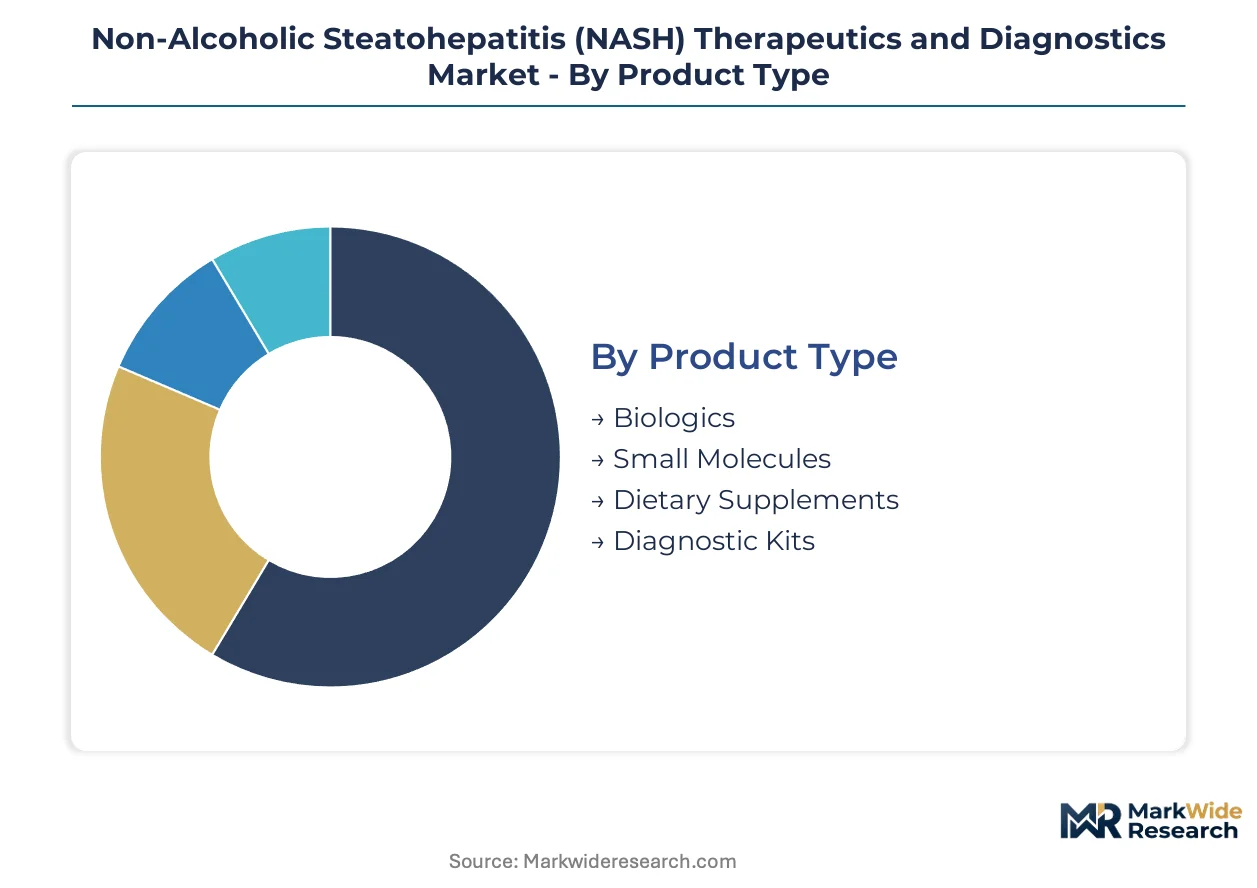
Segmentation in NASH therapeutics and diagnostics reveals how therapeutic mechanisms and diagnostic modalities compete for capital allocation. Technology maturity and reimbursement status create divergent margin profiles across product categories.
Product Type:
Product differentiation in NASH follows manufacturing complexity and regulatory pathway intensity.
- Biologics:Peptide and antibody-based therapies targeting fibrogenesis and metabolic pathways command premium pricing due to cold-chain requirements and GMP complexity. Demand concentrates in United States academic medical centers where prior authorization infrastructure supports high-cost injectables.
- Small Molecules:Oral agents targeting nuclear receptors and metabolic enzymes offer scalable manufacturing and broader prescriber access. United States specialty pharmacies are building distribution networks for these candidates as they near regulatory milestones.
- Dietary Supplements:Vitamin E and omega-3 formulations occupy an over-the-counter channel with limited clinical validation. Retail health positioning competes on price rather than outcomes.
- Diagnostic Kits:Multi-biomarker panels and point-of-care devices enable non-invasive staging. Medicare coverage decisions are accelerating laboratory adoption of these alternatives to biopsy.
Mature deployment sits with small molecules. Newer deployment is concentrated in diagnostic kits.
Technology:
Technology selection in NASH reflects the tension between invasive reference standards and scalable screening platforms.
- Biomarker Analysis:Serum-based panels measuring cytokeratin-18, ELF score, and proprietary algorithms enable population screening without imaging infrastructure. United States integrated delivery networks are piloting automated ordering for at-risk diabetes patients.
- Imaging Techniques:Vibration-controlled transient elastography and MRI-PDFF quantify liver stiffness and fat fraction without ionizing radiation. European hospital procurement committees are unbundling these services from traditional radiology contracts.
- Genomic Testing:Polygenic risk scores and pharmacogenomic profiling guide therapy selection in research settings. Clinical utility remains limited by payer coverage gaps.
- Liver Biopsy:Percutaneous sampling with histopathological scoring persists as the regulatory gold standard for trial endpoints. Patient recruitment friction and sampling variability drive demand toward alternatives.
Established practice centers on liver biopsy. Steepest expansion trajectory belongs to imaging techniques.
End User:
End-user segmentation tracks the migration of NASH care from tertiary centers toward community access points.
- Hospitals:Tertiary hepatology units manage decompensated cirrhosis and transplant evaluation. United States academic medical centers anchor clinical trial recruitment for advanced fibrosis therapies.
- Diagnostic Laboratories:Centralized reference labs process biomarker panels and genomic assays at scale. Labcorp and Quest infrastructure supports nationwide access to non-invasive staging.
- Research Institutes:Academic centers conduct mechanistic studies and early-phase trials. NIH-funded consortia standardize histopathological assessment across sites.
- Outpatient Clinics:Community gastroenterology and endocrinology practices screen at-risk populations. Point-of-care devices are penetrating this channel to bypass specialist referral bottlenecks.
High-complexity care remains hospital-based. Volume growth is concentrating in outpatient clinics.
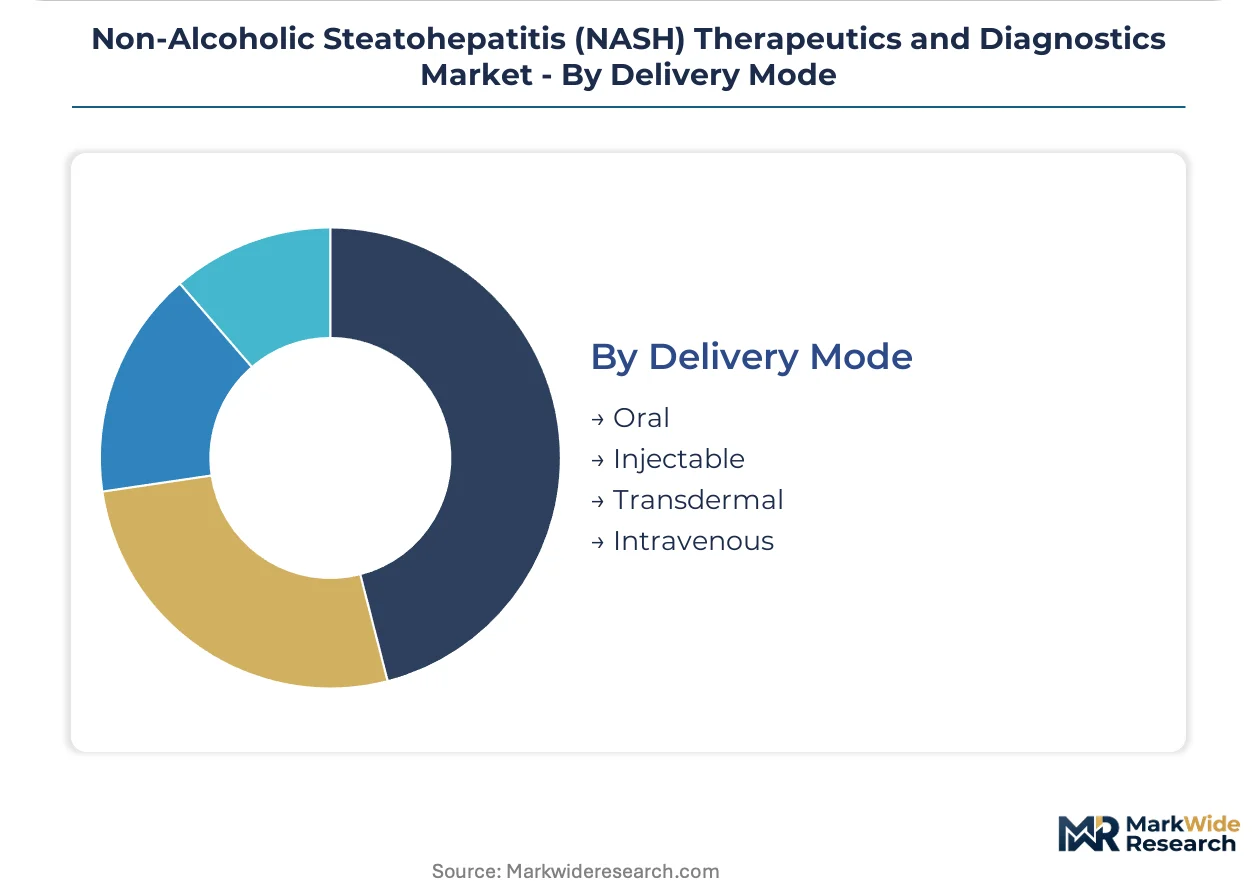
Delivery Mode:
Delivery mode selection balances patient adherence, pharmacokinetic requirements, and manufacturing investment.
- Oral:Once-daily tablets dominate metabolic disease drug development due to patient preference and pharmacy distribution efficiency. Thyroid hormone receptor-beta agonists and FXR agonists follow this pathway.
- Injectable:Subcutaneous GLP-1 receptor agonists leverage existing diabetes infrastructure for NASH indication expansion. Novo Nordisk manufacturing networks support this modality.
- Transdermal:Patch-based delivery remains experimental for NASH-specific agents. Dermatological tolerability limits commercial viability.
- Intravenous:Hospital-administered biologics target acute decompensation or peri-transplant settings. Infusion center capacity constrains scalability.
Injectable platforms anchor near-term launches. Oral formulations represent the dominant long-term trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American clinical trial density for NASH therapeutics, with Massachusetts General Hospital and Brigham and Women's Hospital enrolling patients across multiple Phase III programs. This concentration shapes regulatory strategy and biomarker validation timelines.
United States
Medicare coverage expansion for non-invasive diagnostics drives laboratory adoption of elastography and multi-biomarker panels. FDA breakthrough therapy designations compress review timelines, accelerating sponsor investment in companion diagnostic development. The Research Triangle Park corridor in North Carolina hosts contract research organizations managing decentralized trials.
Germany
EMA priority medicines pathways accelerate conditional marketing authorization for fibrosis-targeted therapies. REACH chemical safety standards influence active pharmaceutical ingredient manufacturing site selection. The Rhine-Main biotech cluster around Frankfurt sustains early-phase clinical infrastructure.
Switzerland
Contract manufacturers in Basel and Zurich concentrate complex peptide and biologic production capacity. Swissmedic maintains alignment with EMA centralized procedures while offering national scientific advice. The Greater Geneva Bern area anchors specialized hepatology research institutes.
Japan
PMDA Sakigake designation creates fast-track pathways analogous to FDA breakthrough status. METI pharmaceutical competitiveness initiatives support domestic manufacturing resilience. The Kanto region around Tokyo concentrates diagnostic imaging device development.
United Kingdom
MHRA post-Brexit regulatory autonomy enables tailored approval pathways for novel diagnostics. NHS England value-based procurement frameworks reshape hospital vendor selection. The Cambridge-London corridor sustains genomic biomarker research consortia.
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market Competitive Landscape
Capital-heavy biologic manufacturers compete with asset-light specialty pharmaceutical developers for hepatology prescriber access. The market structures around three tiers: integrated metabolic disease platforms with diabetes infrastructure, pure-play NASH specialists with single-mechanism depth, and diagnostic platform vendors with imaging and biomarker portfolios. Dominant competitive moves include strategic partnerships between therapeutic developers and diagnostic manufacturers for co-development, plus geographic expansion into European and Asia-Pacific markets ahead of regulatory milestones.
Within the pure-play specialist tier, Madrigal Pharmaceuticals and Intercept Pharmaceuticals exemplify focused mechanistic approaches. Among integrated metabolic platforms, Novo Nordisk occupies a position leveraging existing GLP-1 infrastructure. Gilead Sciences represents diversified R&D intensity across multiple therapeutic modalities. These three anchors illustrate how competitive positioning splits between narrow indication depth and broad platform extension.
| Leading Market Players |
|---|
| Madrigal Pharmaceuticals |
| Intercept Pharmaceuticals |
| Novo Nordisk |
| Gilead Sciences |
| Genfit |
| Akero Therapeutics |
| Siemens Healthineers |
| Novartis |
| Eli Lilly |
| Others |
Pricing and Supply Chain Analysis
Peptide manufacturing costs in Switzerland and Ireland cascade through biologic pricing tiers, with cold-chain logistics and GMP complexity anchoring premium positioning for advanced fibrosis therapies while small-molecule alternatives compete on pharmacy distribution efficiency.
Pricing Analysis
Value-based pricing anchored to fibrosis regression outcomes dominates biologic reimbursement negotiations with United States payers. Three-tier pricing structure across premium biologics, standard small-molecules, and economy dietary supplements reflects manufacturing complexity and regulatory pathway intensity. Cost compression in the small-molecule tier intensifies as diabetes drug developers repurpose existing infrastructure for NASH indication expansion. Community gastroenterology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Basel and Zurich concentrate complex peptide manufacturing capacity for multiple sponsor pipelines. Active pharmaceutical ingredient production draws from Switzerland, Ireland, and selected United States facilities with advanced biologic capabilities. Viral vector supply and specialized cold-chain logistics represent critical dependencies. Single-source vulnerability at contract manufacturing organizations propagates disruption risk across competing development programs. Distribution runs through specialty pharmacy networks for injectables and wholesale channels for oral agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over companion diagnostic development and non-invasive biomarker platforms determines competitive access to accelerated approval pathways.
For Market Incumbents: Anticipate regulatory pressure to unbundle diagnostic services from therapeutic purchasing agreements by deepening point-of-care device partnerships. Secure preferred supplier status with sustainability-mandated hospital systems through REACH-compliant manufacturing investments. Counter emerging biologic competitors by accelerating pediatric NASH protocol development ahead of competitor entry. For New Entrants and Emerging Players: AI-enabled histopathology pattern recognition offers a technology-first wedge into diagnostic infrastructure gaps left by manual review bottlenecks. Penetrate pharmacy-based screening channels in underserved United States regions where hepatology referral capacity constrains patient identification. Pursue co-development partnerships with established therapeutic sponsors lacking companion diagnostic capabilities. For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards to first-in-class mechanisms is the leading indicator that valuation premiums will concentrate in single-mechanism specialists with validated biomarker strategies. Target acquisition profiles emphasizing EU regulatory expertise and decentralized trial infrastructure. Monitor Medicare coverage decisions for multi-biomarker panels as the inflection signal for diagnostic platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA accelerated approval pathways now mandate parallel biomarker validation with therapeutic candidates. |
| Pediatric NASH Protocol Investment | Regulatory science leadership in adolescent populations precedes competitor whitespace entry. |
| EU Green Deal Manufacturing Certification | ECHA-compliant solvent recycling qualifies suppliers for sustainability-mandated procurement frameworks. |
| Pharmacy-Based Screening Integration | Point-of-care fibrosis devices bypass specialist referral bottlenecks in underserved United States regions. |
| Multi-Omics Biomarker Platform Expansion | Electronic health record integration enables population-scale risk stratification for integrated delivery networks. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare coverage determinations, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from SEC 10-K disclosures, NIH-funded consortium publications, and GPO contract databases. Bottom-up patient-flow modeling and top-down epidemiological estimates underwent iterative triangulation.
Cross-referencing historical approval timelines against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include therapeutic mechanism, disease stage, administration route, and regional regulatory cluster. CAGRs derived from epidemiological incidence projections, treatment penetration curves, and pricing evolution assumptions. Forecast inputs incorporated biomarker adoption rates and reimbursement code expansion timelines.
Several conditions sit outside the modeled scope, including pipeline attrition from late-stage clinical failures, regulatory reversals on accelerated approval requirements, and manufacturing disruptions at concentrated API facilities. Forecasts reflect documented assumptions about payer behavior and diagnostic substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
China Plasma Protein Therapeutics Market