
 North America Syndromic Multiplex Diagnostic Market | 2026-2036
North America Syndromic Multiplex Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
North America Syndromic Multiplex Diagnostic Market Analytics
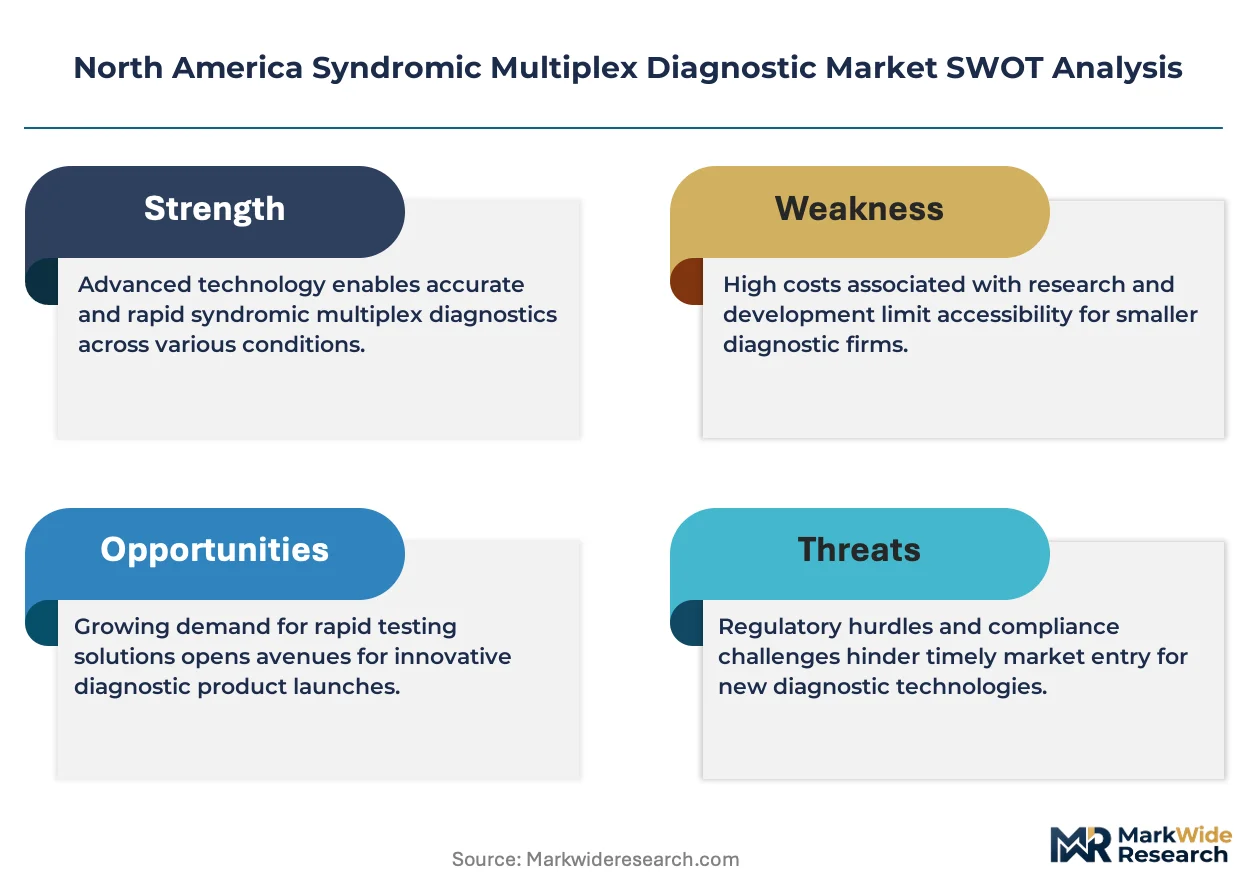
FDA's evolving 510(k) premarket notification framework for multiplex infectious disease assays is realigning the cost-of-entry calculus for new platform developers. BioFire Diagnostics leverages its integrated filmarray system to sustain installed-base loyalty across acute-care hospitals. bioMérieux anchors its competitive position through deep menu expansion in bloodstream and respiratory panels. QIAGEN differentiates via modular assay architectures that accommodate emerging pathogen targets without full platform redesign.
Syndromic multiplex diagnostics combine multiple nucleic acid amplification targets into single-run panels capable of detecting viral, bacterial, and fungal pathogens from one patient specimen within one to two hours. These systems employ polymerase chain reaction, microarray hybridization, or mass spectrometry detection methods to replace sequential single-target testing with simultaneous pathogen identification and antimicrobial resistance marker detection. Respiratory infection panels currently lead product type volume, while gastrointestinal applications represent the fastest-expanding segment as outpatient settings adopt streamlined stool pathogen workflows. Assay reagents capture recurring revenue streams that instruments alone cannot match, creating durable margin pools for platform holders.
FDA, CMS, and CLIA collectively shape market access through premarket review, reimbursement coding, and laboratory quality certification requirements that determine which test systems reach commercial scale. The agency's breakthrough device designation for novel multiplex panels accelerates regulatory timelines, while CMS parallel coding reviews determine whether hospitals recover assay costs through diagnostic-related group payments. Stakeholders must monitor emerging FDA guidance on artificial intelligence-assisted result interpretation, as algorithm-enabled syndromic panels approach submission thresholds that could redefine competitive differentiation.
Market Dynamics
CMS reimbursement compression for laboratory-developed tests is forcing hospital systems to consolidate purchasing power around FDA-cleared multiplex platforms with predictable diagnostic-related group alignment. This structural pressure favors integrated instrument-reagent ecosystems over modular open systems.
Growth Catalysts
- CLIA Complexity Waivers:The 1988 Clinical Laboratory Improvement Amendments framework permits moderate-complexity laboratories to operate syndromic panels without full high-complexity certification, expanding deployment sites into community hospitals and urgent care networks.
- Antimicrobial Stewardship Mandates:Joint Commission accreditation standards now require documented pathogen identification within 48 hours for hospitalized patients receiving antibiotics, creating institutional pressure for rapid multiplex turnaround.
- FilmArray Chemistry:Nested PCR with melt-curve analysis enables single-run detection of 20-plus targets without separate nucleic acid extraction, compressing hands-on technician time to under two minutes per specimen.
Market Restraints
- Reagent Rental Lock-In:Capital equipment placement contracts tie hospitals to proprietary consumable streams, preventing cost arbitrage across competing assay menus for multi-year contract terms.
- Plastics Supply Concentration:Injection-molded cartridge manufacturing concentrates in Puerto Rico and Mexican border zones, exposing production continuity to hurricane disruption and cross-border logistics friction.
- CMS Gapfill Pricing:New molecular codes enter market at placeholder reimbursement rates that frequently understate actual assay costs, creating margin pressure during the 12-to-24-month pricing establishment window.
Strategic Opportunities
- Central American Reference Laboratories:Underpenetrated hospital networks in Guatemala and Costa Rica present first-mover positioning for US-cleared platforms seeking volume outside saturated domestic markets.
- At-Home Collection Integration:Self-collected nasal and stool specimens paired with courier logistics enable outpatient syndromic testing without physical clinic infrastructure.
- AI-Assisted Interpretation:FDA breakthrough device designation pathways for algorithm-enabled result reporting offer differentiation beyond raw pathogen detection toward clinical decision support.
Industry Challenges
- Molecular Diagnostics Specialist Shortage:ASCP-certified technologists with PCR troubleshooting competency command premium wages in tight labor markets, constraining 24/7 STAT panel availability.
- LIS Integration Complexity:Bidirectional HL7 interfacing between syndromic instruments and legacy laboratory information systems requires 80-to-120-hour validation cycles per hospital IT environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Syndromic Multiplex Diagnostic Market |
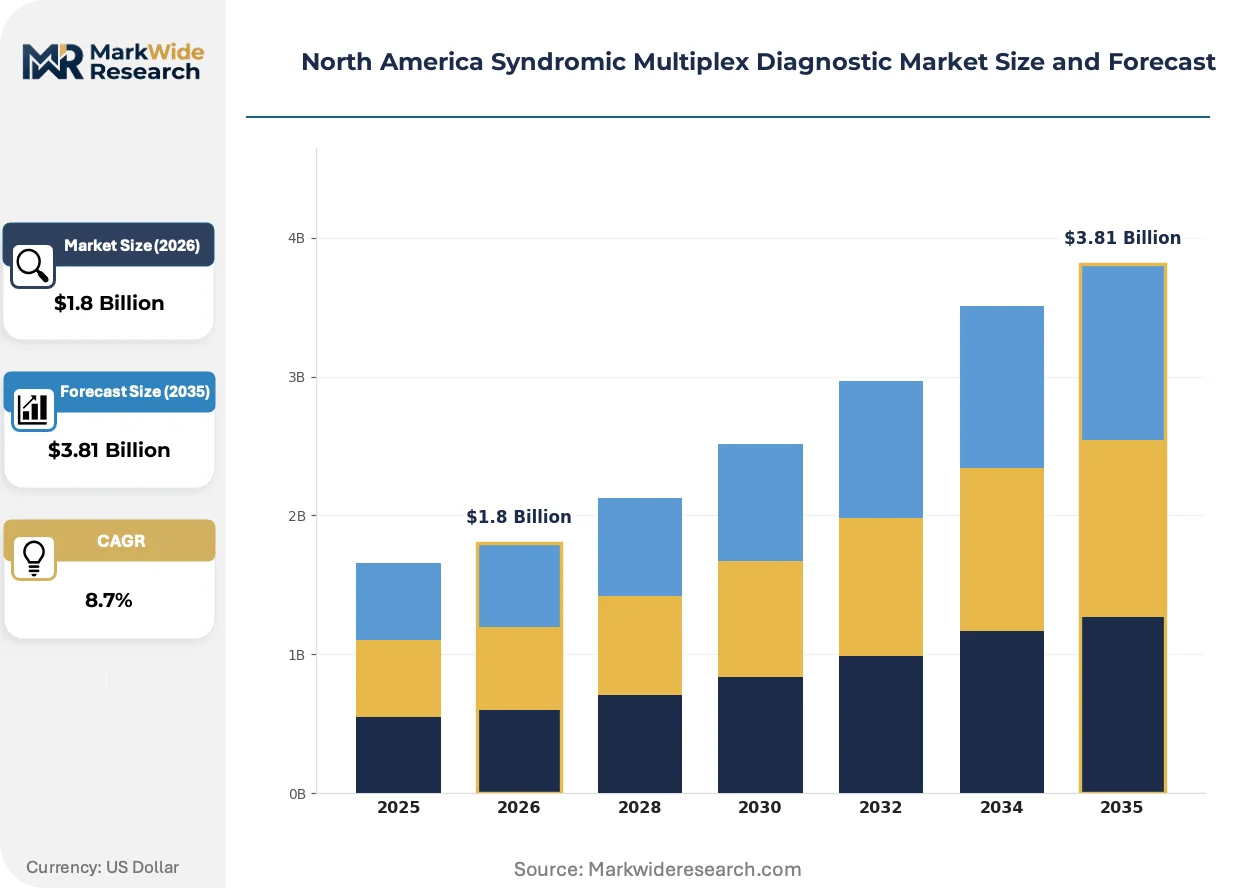
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Instruments, Software, Reagents Application: Respiratory Infections, Gastrointestinal Infections, Central Nervous System Infections, Healthcare-Associated Infections End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Technology: Polymerase Chain Reaction, Microarray, Mass Spectrometry, Nucleic Acid Testing |
| Companies Covered | BioFire Diagnostics, bioMérieux, Luminex Corporation, QIAGEN, BD, Abbott, Cepheid, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Syndromic Multiplex Diagnostic Market Evolving Landscape
Multiplex detection architectures are converging with point-of-care form factors, collapsing the historical separation between reference laboratory accuracy and bedside speed. This convergence is redrawing competitive boundaries between acute-care and ambulatory settings.
Digital PCR is consolidating quantitative pathogen load monitoring into syndromic workflows previously limited to qualitative presence-absence reporting. Transplant centers and oncology units are adopting absolute copy-number detection for immunocompromised patient management. This capability is compressing the need for separate viral load assays alongside screening panels.
FDA's 2023 guidance on infectious disease diagnostics with antimicrobial resistance markers is accelerating simultaneous phenotype-genotype reporting requirements. Bloodstream infection panels must now detect mecA, vanA, and KPC genes alongside organism identification. This regulatory expansion is forcing assay developers to expand target menus without instrument hardware replacement.
Hospital procurement committees are consolidating molecular testing contracts under single-source agreements that bundle respiratory, gastrointestinal, and bloodstream panels. Integrated delivery networks in Texas and Florida are leading this vendor consolidation, trading menu breadth for standardized training and service response times. This behavior is compressing the addressable market for standalone specialty platform vendors.
North America Syndromic Multiplex Diagnostic Market Segmentation
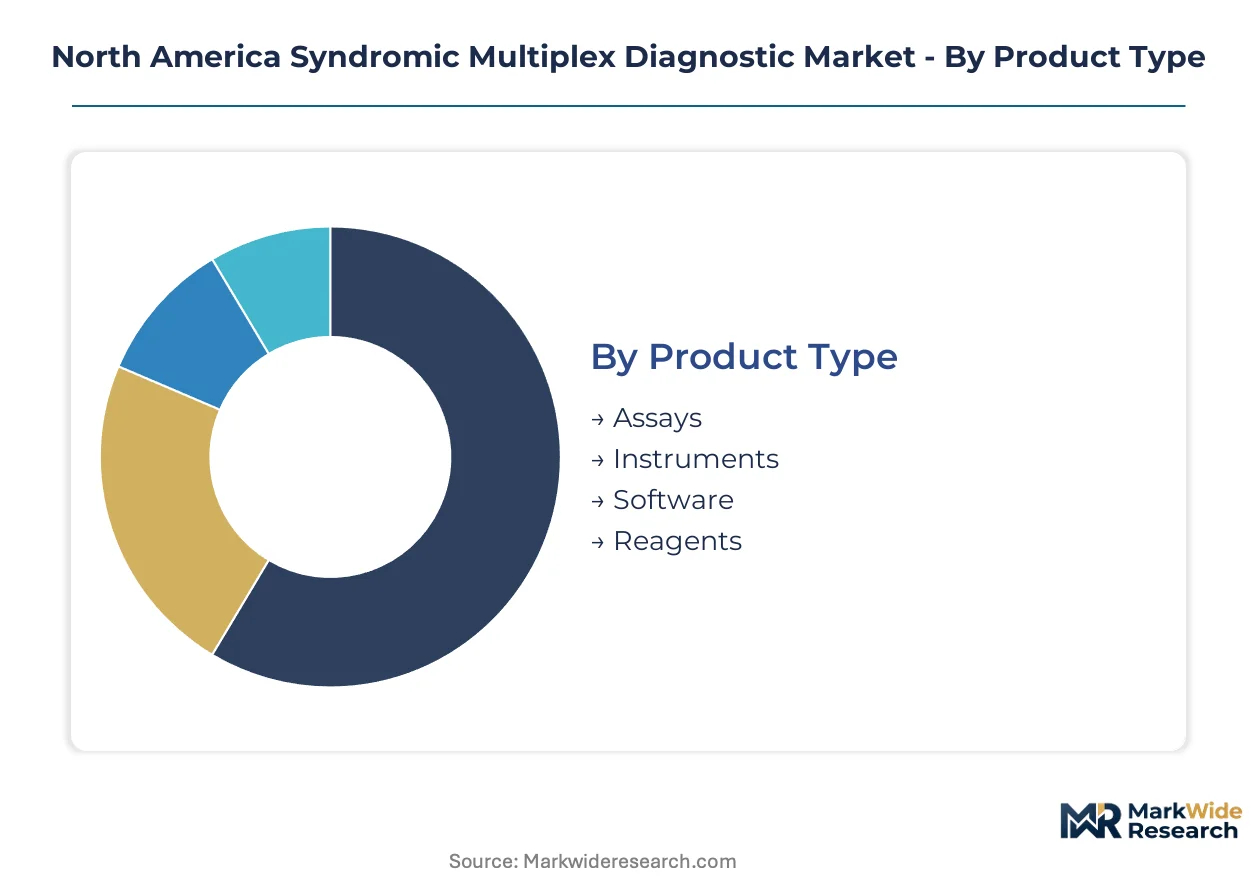
Syndromic multiplex diagnostics fragment across four interlocking dimensions that determine procurement patterns and margin capture. Product type dictates recurring revenue intensity, while application focus shapes regulatory pathway complexity and reimbursement coding. End-user concentration and technology choice further constrain vendor positioning strategies.
Product Type:
Supply concentration for consumable manufacturing sits with polymerase chain reaction cartridge producers in Puerto Rico and Mexican border zones, exposing continuity risk to hurricane disruption and cross-border logistics friction.
- Assays:Preconfigured panel cartridges integrate nucleic acid extraction with multiplex amplification chemistry. Hospital laboratories in the Northeastern United States anchor demand as academic medical centers expand reference testing volume for respiratory and bloodstream panels.
- Reagents:Lyophilized master mixes and proprietary buffers constitute the highest-margin recurring revenue stream. FDA 510(k) clearance pathways for new target expansions compress time-to-market for assay menu extensions without platform replacement.
- Instruments:Integrated filmarray and modular platform hardware requires CLIA moderate-complexity certification alignment. Capital equipment placement contracts tie hospitals to proprietary consumable streams for multi-year terms.
- Software:Laboratory information system interfacing and algorithm-enabled result interpretation modules demand 80-to-120-hour HL7 validation cycles per hospital IT environment.
Assays and reagents absorb the bulk of installed capacity; software is expanding most quickly as FDA breakthrough device designation pathways accelerate algorithm-enabled clinical decision support submissions.
Application:
Cost tier stratification separates high-complexity reference laboratory panels from moderate-complexity point-of-care deployments, with reimbursement coding determining viable test sites.
- Respiratory Infections:Viral and bacterial pathogen detection from nasopharyngeal specimens dominates current panel volume. Joint Commission antimicrobial stewardship mandates requiring 48-hour pathogen identification institutionalize demand across acute-care hospitals.
- Gastrointestinal Infections:Streamlined stool pathogen workflows target outpatient settings with simultaneous bacterial, viral, and parasitic detection. Central American reference laboratories in Guatemala and Costa Rica present first-mover positioning for US-cleared platforms seeking volume outside saturated domestic markets.
- Healthcare-Associated Infections:Bloodstream infection panels incorporating mecA, vanA, and KPC resistance gene detection serve immunocompromised patient management in transplant and oncology units.
- Central Nervous System Infections:Cerebrospinal fluid multiplex panels for meningitis and encephalitis pathogen identification require specialized collection logistics and STAT turnaround capabilities.
Respiratory panels command the deepest installed base; gastrointestinal applications are climbing the fastest as outpatient adoption accelerates.
End User:
Customer type concentration favors integrated delivery networks consolidating molecular testing contracts under single-source agreements bundling multiple panel categories.
- Hospitals:Acute-care facilities with 24/7 STAT laboratory capabilities anchor platform placement. Texas and Florida integrated delivery networks lead vendor consolidation behavior, trading menu breadth for standardized training and service response times.
- Laboratories:Reference laboratories and hospital-affiliated core labs process high-throughput specimen volumes with batch processing efficiency. CLIA complexity waivers expand deployment sites into community hospitals and urgent care networks without full high-complexity certification.
- Diagnostic Centers:Outpatient-focused facilities adopt at-home collection integration with courier logistics for syndromic testing without physical clinic infrastructure.
- Research Institutions:Academic medical centers anchor translational research applications and novel target validation for future panel expansion.
Hospitals retain the largest installed instrument base; diagnostic centers are gaining share fastest as ambulatory testing workflows mature.
Technology:
Technology maturity curves separate established polymerase chain reaction dominance from emerging digital PCR quantitative capabilities and mass spectrometry alternative architectures.
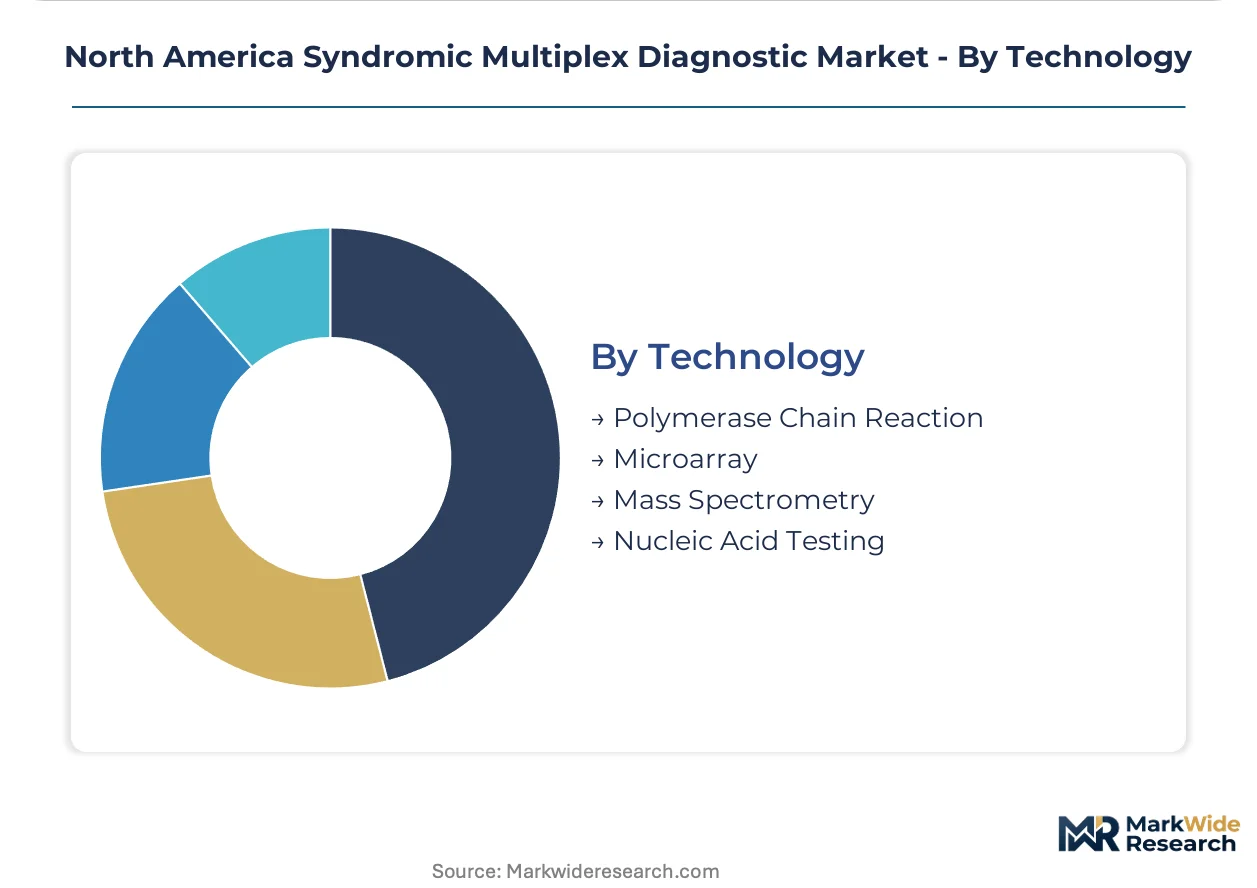
- Polymerase Chain Reaction:Nested PCR with melt-curve analysis enables single-run detection of 20-plus targets without separate nucleic acid extraction. FilmArray chemistry compresses hands-on technician time to under two minutes per specimen.
- Nucleic Acid Testing:Isothermal amplification and CRISPR-based detection methods challenge thermal cycler dependency for point-of-care form factors. Modular assay architectures accommodate emerging pathogen targets without full platform redesign.
- Microarray:Solid-phase hybridization enables expanded target menus beyond PCR primer multiplexing limits for research and reference laboratory applications.
- Mass Spectrometry:Matrix-assisted laser desorption ionization time-of-flight methods provide orthogonal protein-based pathogen identification complementary to nucleic acid detection.
Polymerase chain reaction holds the dominant installed base; nucleic acid testing is expanding most quickly as point-of-care convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Boston-Cambridge corridor anchor North American syndromic multiplex diagnostic concentration, with FDA premarket review proximity and academic medical center density driving platform development clusters.
United States
Hospital laboratories across the Northeastern United States expand adoption of syndromic panels for rapid pathogen identification. FDA 510(k) premarket notification pathways for multiplex infectious disease assays compress time-to-market for new platform developers. The Boston-Cambridge corridor anchors reference testing volume as academic medical centers drive translational research applications.
Canada
Canadian hospital networks consolidate molecular testing procurement under provincial health authority frameworks. Health Canada regulatory alignment with FDA premarket review standards accelerates cross-border platform clearance timelines. Ontario and Quebec provinces concentrate reference laboratory capacity with CLIA-equivalent certification requirements.
Mexico
Mexican border zone manufacturing clusters produce injection-molded cartridge components for US platform vendors. Cross-border logistics friction and hurricane exposure in Puerto Rico concentrate supply continuity risk for consumable production. Northern border states anchor maquiladora operations serving North American instrument assembly demand.
North America Syndromic Multiplex Diagnostic Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North America syndromic multiplex diagnostic market. The vendor base organizes around integrated instrument-reagent ecosystems versus modular open-system architectures. Three archetypes dominate: filmarray-integrated platform holders, menu-expanding reference laboratory specialists, and modular assay architects. Strategic moves concentrate on FDA breakthrough device designation pursuit and antimicrobial resistance marker menu expansion.
Among US-based platform developers, BioFire Diagnostics and Luminex Corporation exemplify integrated ecosystem strategies that tie hospital procurement to proprietary consumable streams. bioMérieux anchors the European multinational tier with North American reference laboratory penetration. These three entities represent distinct competitive positioning vectors: nested PCR chemistry integration, xMAP bead-based multiplexing, and deep bloodstream and gastrointestinal panel specialization.
| Leading Market Players |
|---|
| BioFire Diagnostics |
| bioMérieux |
| Luminex Corporation |
| QIAGEN |
| BD |
| Abbott |
| Cepheid |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Lyophilized reagent master mixes constitute the dominant upstream cost input, flowing from Puerto Rico and Mexican border zone manufacturing clusters through FDA-cleared platform vendors to hospital procurement committees that negotiate multi-year reagent rental contracts locking in consumable streams.
Pricing Analysis
Lead-time compression commands measurable price premiums, with STAT turnaround specifications under two hours attracting higher per-test rates than batch-processed reference laboratory workflows. The dominant pricing structure rests on instrument placement with reagent rental commitments, where FDA breakthrough device designation and antimicrobial resistance marker menu breadth drive differentiation. Price differentiation hinges on CLIA complexity waiver alignment and integrated delivery network contract scale. Pricing pressure stems from CMS gapfill pricing windows that understate actual assay costs during 12-to-24-month establishment periods. Community hospitals with moderate-complexity certification exhibit highest price sensitivity; academic medical centers with bundled panel procurement demonstrate lowest.
Supply Chain Analysis
FDA 510(k) clearance and CLIA moderate-complexity certification gate entry for cartridge manufacturers, concentrating qualified supply among Puerto Rico, Mexico, and select US mainland facilities. Injection-molded PCR cartridges draw from specialized polymer resins, lyophilized enzyme formulations, and optical-grade plastics. Single-source vulnerability concentrates in hurricane-exposed Puerto Rico operations and cross-border logistics corridors. Distribution runs through integrated delivery network procurement committees that consolidate respiratory, gastrointestinal, and bloodstream panel contracts under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America syndromic multiplex diagnostic market is consolidating into a vertical-integration race where control over lyophilized reagent formulation and cartridge manufacturing determines margin capture against CMS reimbursement compression.
For Market Incumbents: Extend antimicrobial resistance marker menus through FDA breakthrough device designation pathways before mecA, vanA, and KPC detection becomes table stakes. Lock in hospital procurement committees with reagent rental contracts spanning 5-7 years to preempt modular open-system competitors. Backward integration into Puerto Rico cartridge manufacturing insulates against hurricane disruption and cross-border logistics friction threatening supply continuity. For New Entrants and Emerging Players: Launch via at-home collection integration paired with courier logistics targeting outpatient diagnostic centers outside hospital infrastructure. Central American reference laboratories in Guatemala and Costa Rica present the most penetrable geography for US-cleared platforms seeking volume beyond saturated domestic markets. AI-assisted result interpretation modules offer differentiation toward clinical decision support beyond raw pathogen detection. For Investors and Strategic Acquirers: FDA breakthrough device designation announcements for algorithm-enabled panels are the leading indicator that clinical decision support capabilities are approaching submission thresholds capable of redefining competitive positioning. Over a 5-10 year horizon, platform holders with integrated filmarray chemistry and deep menu expansion in bloodstream and gastrointestinal applications represent viable acquisition targets. Watch for Health Canada regulatory alignment accelerating cross-border clearance timelines as a signal of Canadian hospital network consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates regulatory timelines for novel multiplex panels with antimicrobial resistance markers. |
| Reagent Rental Contract Expansion | Locks hospital procurement committees into proprietary consumable streams for multi-year terms. |
| AI-Assisted Interpretation Module Development | Positions platforms for clinical decision support beyond qualitative pathogen detection. |
| Central American Reference Laboratory Partnership | Captures first-mover volume in underpenetrated Guatemala and Costa Rica hospital networks. |
| Puerto Rico Manufacturing Footprint Diversification | Mitigates hurricane exposure and cross-border logistics friction for cartridge production. |
Research Methodology
Document review covered FDA 510(k) premarket notification filings, CMS Medicare reimbursement coding decisions, and hospital procurement database records, complemented by interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and CLIA compliance officers. Secondary validation drew from CMS gapfill pricing determinations, Joint Commission antimicrobial stewardship accreditation standards, and Puerto Rico manufacturing facility disclosures. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down market sizing derived from integrated delivery network contract consolidation patterns.
Segment-level value outputs across the projection horizon reflect modeled assumptions for respiratory, gastrointestinal, bloodstream, and central nervous system panel categories, further disaggregated by product type, end-user concentration, and technology platform. CAGRs were derived from hospital adoption curve analysis, CLIA complexity waiver expansion trajectories, and CMS reimbursement coding evolution. Forecast inputs incorporated antimicrobial stewardship mandate compliance timelines and AI-assisted interpretation module development pipelines.
FDA guidance revisions on infectious disease diagnostics, CMS gapfill pricing determinations, and hurricane disruption frequency in Puerto Rico are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in Joint Commission accreditation standards or Health Canada regulatory alignment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Blood Ketone Test Meter Market