
 In-Vitro Diagnostics (IVD) Instruments Market | 2026-2036
In-Vitro Diagnostics (IVD) Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Diagnostics (IVD) Instruments Market Insights
Reagent rental and subscription-based consumable contracts is pivoting the commercial model from capital equipment sales to recurring revenue streams. Roche Diagnostics leverages its installed base of cobas analyzers to lock in long-term reagent commitments. Abbott Laboratories anchors its competitive position through integrated immunoassay and molecular testing platforms. Danaher sustains pricing power via Leica Biosystems and Beckman Coulter service contracts that span instrument lifecycle management.
In-vitro diagnostics instruments comprise electromechanical systems engineered to perform quantitative or qualitative analysis of biological specimens, with throughput specifications ranging from tens to thousands of tests per hour depending on analyzer class. These systems serve the primary commercial purpose of enabling clinical decision-making through standardized, reproducible biomarker detection in blood, tissue, urine, or other matrices. Immunoassay analyzers command the deepest margin pools due to high reagent pull-through and established reimbursement codes. PCR and next-generation sequencing segments attract capital allocation fastest as oncology and infectious disease panels expand menu breadth. Hospitals remain the dominant installed base, though diagnostic laboratories are capturing disproportionate growth through centralized high-volume automation.
The FDA's 510(k) clearance framework and Clinical Laboratory Improvement Amendments govern instrument complexity classification and laboratory accreditation in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter performance evaluation and post-market surveillance obligations across European member states. China's NMPA accelerates review timelines for domestically manufactured IVD instruments through innovation pathway designations, reshaping competitive access. Stakeholders must monitor evolving harmonization gaps between FDA and EMA predicate device requirements as dual-market registration strategies face mounting compliance cost divergence.
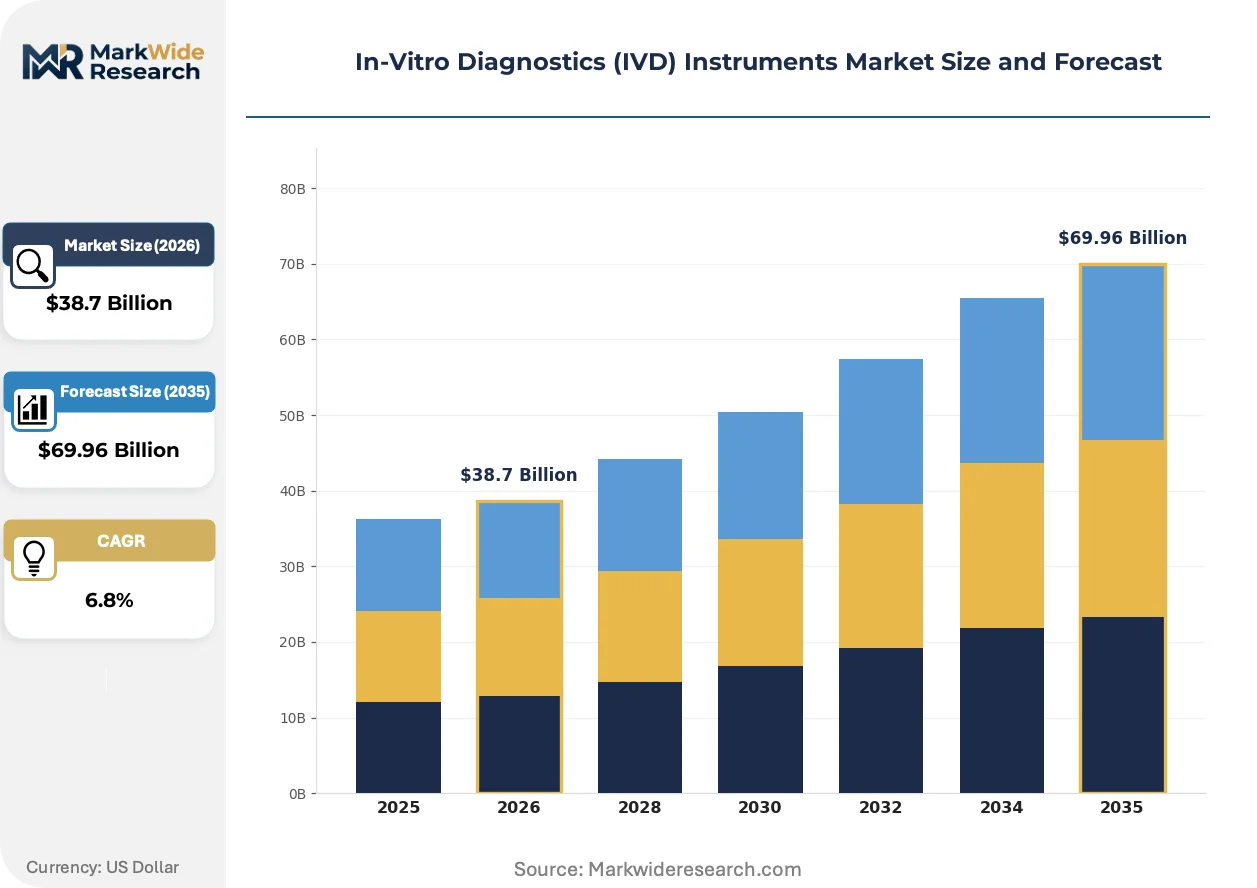
Market Dynamics
Reagent rental contracts now dominate commercial relationships, converting capital equipment transactions into recurring revenue streams and compressing customer switching flexibility across installed bases.
Growth Catalysts
- CLIA Complexity Waivers:The FDA's moderate-complexity device pathway accelerates laboratory accreditation timelines in the United States, expanding test menu accessibility for smaller diagnostic facilities.
- Decentralized Testing Infrastructure:Health systems in Germany, China, and the United States prioritize point-of-care deployment, driving analyzer placement into ambulatory settings and retail clinics.
- Automated Workflow Integration:Pre-analytical and post-analytical robotics reduce manual handling errors while increasing throughput specifications for high-volume immunoassay platforms.
Market Restraints
- Optical Component Concentration:Precision photomultiplier tubes and laser diodes concentrate sourcing from Japanese and German specialty suppliers, creating input vulnerability.
- IVDR Performance Evaluation Burden:The EU In Vitro Diagnostic Regulation imposes extended clinical evidence requirements for novel biomarker assays, lengthening commercialization timelines.
- Manual Microscopy Substitution:Digital pathology and whole-slide imaging displace traditional light microscopy in histopathology workflows, constraining analog instrument replacement cycles.
Strategic Opportunities
- India Diagnostic Laboratory Expansion:Private hospital chains and standalone reference laboratories in Mumbai, Delhi, and Bangalore underinvest in automated platforms relative to test volume growth.
- AI-Assisted Result Interpretation:Machine learning algorithms for pattern recognition in immunofluorescence and hematology smears converge with analyzer hardware to reduce pathologist review burden.
- NMPA Innovation Pathways:China's domestic manufacturing incentives accelerate review timelines for locally produced molecular diagnostic instruments, reshaping competitive access.
Industry Challenges
- Field Service Engineer Scarcity:Electromechanical troubleshooting and laser alignment expertise concentrates among aging technician cohorts, constraining uptime guarantee fulfillment.
- LIS/EMR Integration Complexity:Middleware connectivity between proprietary analyzer data formats and hospital information systems requires customized HL7 mapping, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Diagnostics (IVD) Instruments Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Reagents, Assays, Consumables Technology: PCR, Microarrays, Immunoassays, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutes Application: Infectious Diseases, Cancer, Genetic Testing, Metabolic Disorders |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Danaher, Thermo Fisher Scientific, Bio-Rad Laboratories, BD, bioMérieux, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Diagnostics (IVD) Instruments Market Trends and Innovations
Digital integration and consumable-anchored business models are compressing traditional equipment sales cycles while expanding remote service capabilities across distributed instrument fleets.
Next-generation sequencing platforms for oncology and infectious disease panels are absorbing capital allocation from conventional PCR systems as menu breadth expands and per-run economics improve. Academic medical centers and large reference laboratories in the United States and Germany lead adoption, displacing single-analyte molecular workflows. The technology is absorbing mid-throughput instrument demand previously served by dedicated real-time PCR analyzers.
REACH substance restrictions and RoHS compliance obligations in the European Union constrain mercury-containing reagents and certain rare earth magnet formulations in electromechanical components. Manufacturers reformulate chemiluminescent substrates and redesign magnetic separation modules to maintain CE marking eligibility. Immunoassay reagent suppliers face the steepest substitution timelines given their reliance on legacy detection chemistry.
Consolidated procurement through group purchasing organizations now dictates analyzer selection for multi-site health systems, compressing vendor diversity and standardizing service contract terms. Independent diagnostic laboratories lose negotiating leverage as purchasing concentrates through national contracts. The United States exhibits the most pronounced buyer consolidation, with three GPOs controlling the majority of hospital capital equipment acquisition.
In-Vitro Diagnostics (IVD) Instruments Market Segmentation
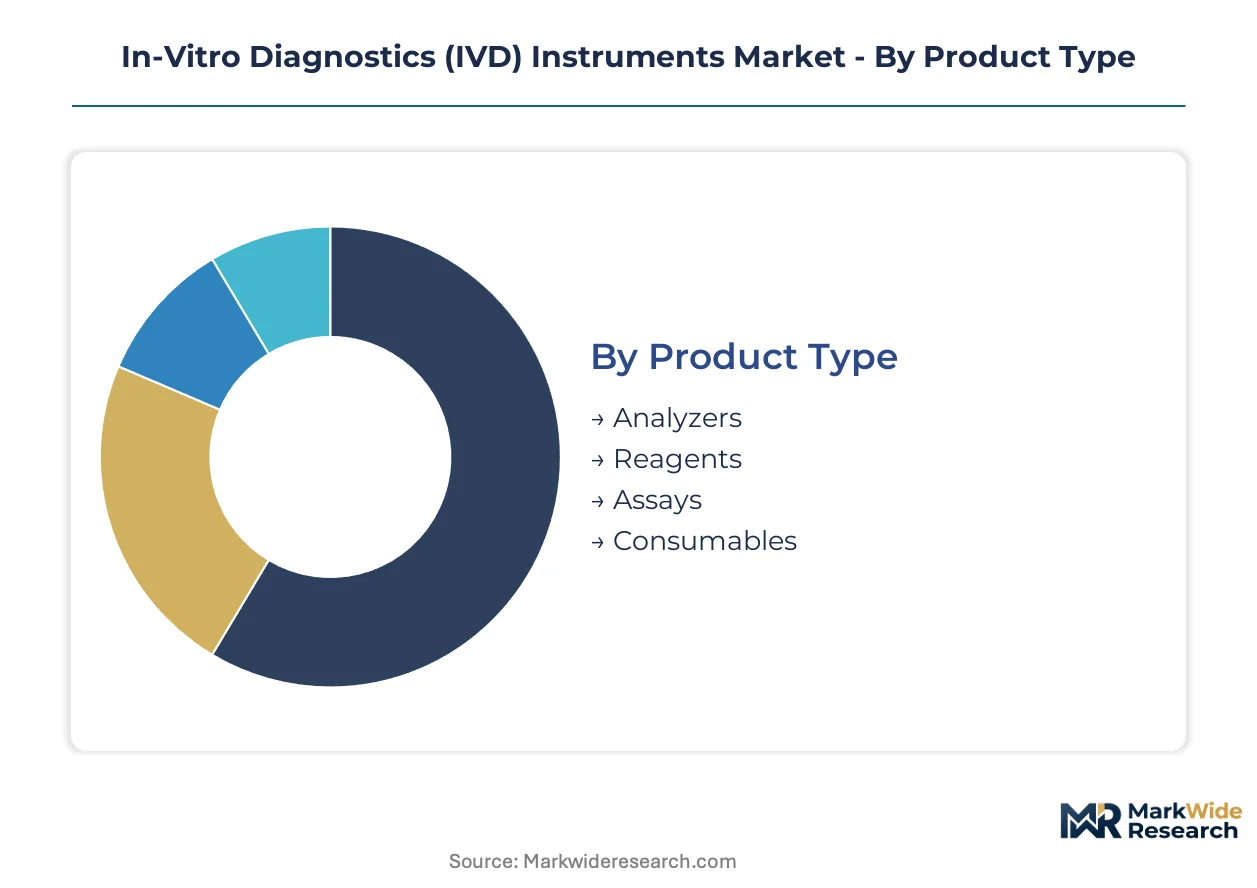
IVD instrument segmentation reveals divergent margin structures and capital intensity across hardware, consumables, and service revenue pools. Technology and end-user dimensions determine pricing power, installed base stickiness, and regulatory pathway complexity.
Product Type:
Capital equipment buyers prioritize throughput specifications and reagent lock-in economics; consumables purchasers optimize per-test cost and supply security.
- Analyzers:Electromechanical platforms with throughput ranging from hundreds to thousands of tests per hour. Demand concentrates in diagnostic laboratories across Germany, China, and the United States as facilities consolidate testing onto centralized high-volume automation. Reagent rental contracts convert capital sales into recurring revenue streams, compressing customer switching flexibility.
- Reagents:Chemiluminescent substrates, enzyme conjugates, and magnetic bead formulations enabling biomarker detection. Hospital systems in the United States anchor the deepest volume pools through long-term supply agreements tied to analyzer placements. Margin profiles exceed hardware due to proprietary formulation requirements and regulatory filing barriers.
- Assays:Pre-validated test kits with defined analytical performance characteristics. Clinical laboratories in Germany and China drive menu expansion for oncology and infectious disease panels. CE marking under IVDR and FDA 510(k) pathways govern commercial access timelines.
- Consumables:Pipette tips, reaction vessels, and sample handling disposables. High-throughput reference laboratories in Mumbai and Bangalore absorb volume growth as test automation expands. Sourcing concentrates through group purchasing organizations, standardizing vendor selection.
Analyzers lead volumes today; reagents are gaining share fastest.
Technology:
Detection chemistry and amplification methodology determine sensitivity specifications, turnaround times, and capital deployment requirements.
- PCR:Thermal cycling platforms for nucleic acid amplification with established infectious disease menus. Diagnostic laboratories in the United States retain substantial installed bases for respiratory and sexually transmitted infection panels. Per-run economics face pressure from next-generation sequencing displacement in oncology applications.
- Microarrays:Solid-phase hybridization systems for multiplexed genetic analysis. Research institutes in Germany and academic medical centers in China absorb capacity for pharmacogenomic and cytogenetic testing. Menu breadth constraints limit clinical adoption relative to sequencing alternatives.
- Immunoassays:Antibody-antigen binding detection with chemiluminescent or electrochemical readout. Hospital laboratories across the United States, Germany, and China anchor the largest revenue pools due to high test volumes in endocrinology and cardiac biomarkers. Reagent pull-through sustains margin premiums across analyzer lifecycle.
- Next-Generation Sequencing:Massively parallel sequencing platforms for oncology and hereditary disease panels. Large reference laboratories in the United States and Germany lead adoption as per-run costs decline and bioinformatics pipelines mature. The technology is absorbing mid-throughput demand previously served by dedicated PCR analyzers.
Immunoassays dominate revenue today; next-generation sequencing is climbing the fastest.
End User:
Facility scale and accreditation status determine instrument complexity tier and service contract structure.
- Hospitals:Integrated health systems with CLIA-certified laboratories and captive patient volumes. The United States exhibits the most concentrated procurement through group purchasing organizations, compressing vendor diversity. Uptime guarantees and field service response times dominate selection criteria.
- Diagnostic Laboratories:Standalone reference facilities and hospital-affiliated outreach operations. Private chains in India and China are underinvested in automation relative to test volume growth. Centralized high-throughput platforms reduce manual handling errors and labor cost per reportable result.
- Clinics:Point-of-care settings requiring waived or moderate-complexity devices under CLIA. Retail clinic expansion in the United States and Germany drives analyzer placement into ambulatory settings. FDA premarket notification pathways accelerate commercialization for moderate-complexity instruments.
- Research Institutes:Academic and government laboratories with flexible funding and protocol customization requirements. Sequencing and microarray platforms concentrate in Germany and the United States due to grant funding density. Instrument specifications prioritize flexibility over throughput standardization.
Hospitals anchor installed base today; diagnostic laboratories are expanding most quickly.
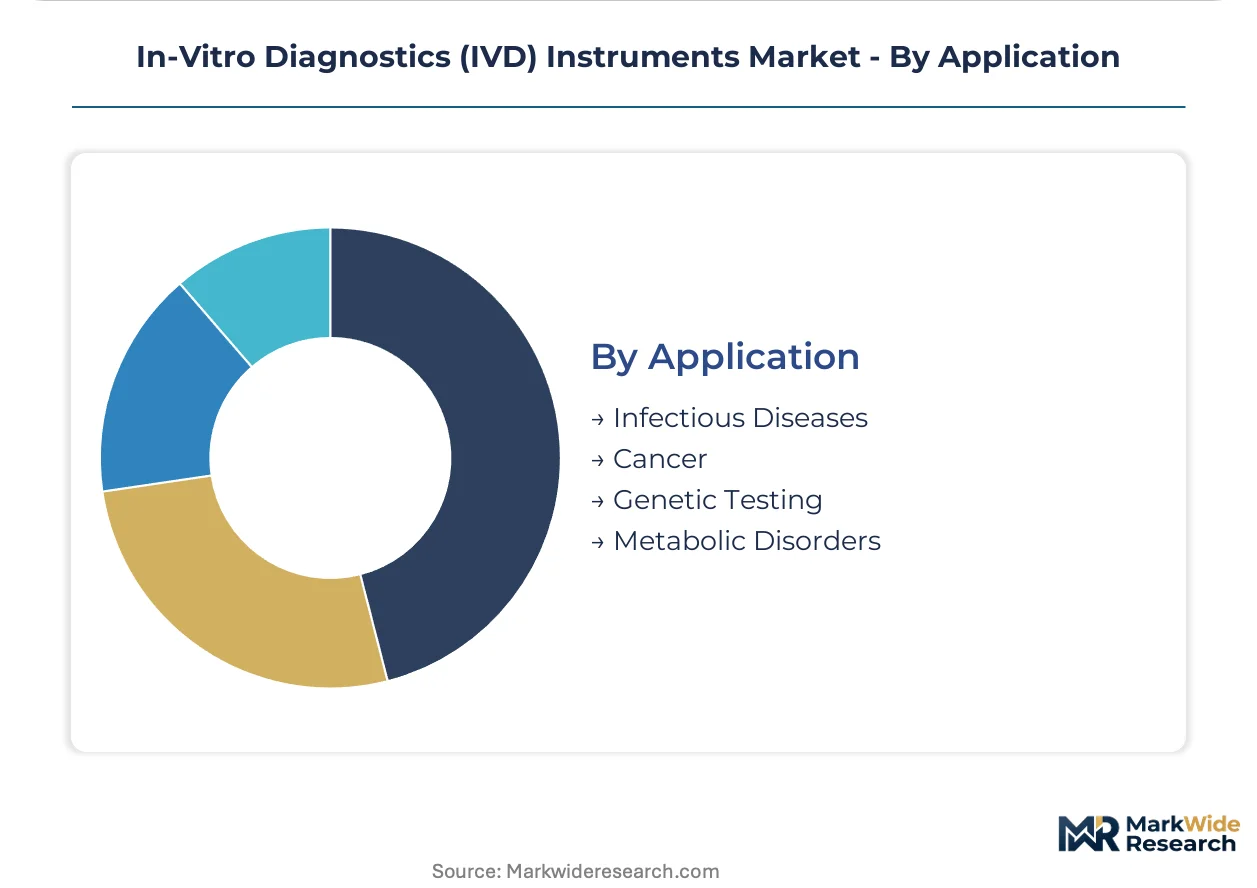
Application:
Disease prevalence and reimbursement density determine test menu prioritization and analyzer configuration.
- Infectious Diseases:Respiratory, sexually transmitted, and hospital-acquired infection panels with high test frequency. Diagnostic laboratories in the United States and China absorb volume for COVID-19, influenza, and antimicrobial resistance surveillance. PCR and immunoassay platforms compete on turnaround time and sensitivity specifications.
- Cancer:Oncology biomarker testing for therapy selection and minimal residual disease monitoring. Academic medical centers in Germany and the United States lead next-generation sequencing adoption for solid tumor and hematologic malignancy panels. Companion diagnostic requirements tie assay approval to pharmaceutical therapy labels.
- Genetic Testing:Carrier screening, prenatal diagnostics, and hereditary disease risk assessment. Research institutes and specialized reference laboratories in the United States concentrate activity. Regulatory frameworks vary substantially across FDA, EMA, and NMPA jurisdictions.
- Metabolic Disorders:Diabetes, thyroid dysfunction, and cardiovascular risk marker quantification. Hospital laboratories across Germany, China, and the United States sustain high immunoassay throughput for HbA1c, TSH, and lipid panels. Established reimbursement codes support margin stability.
Infectious diseases leads volumes today; cancer is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's diagnostic laboratory automation intensity exceeds China's by a substantial margin, yet Beijing's NMPA innovation pathways are compressing review timelines faster than EMA processes allow.
United States
Hospital systems concentrate analyzer procurement through three dominant group purchasing organizations, standardizing vendor selection across multi-site networks. FDA's 510(k) premarket notification framework accelerates moderate-complexity device commercialization for point-of-care expansion. The Boston-Cambridge corridor anchors molecular diagnostics R&D density, with academic medical centers piloting next-generation sequencing integration into routine oncology workflows.
Germany
Reference laboratories in Munich and Hamburg drive centralized high-throughput automation adoption as labor costs pressure manual workflow economics. EU In Vitro Diagnostic Regulation imposes extended clinical evidence requirements for novel biomarker assays, lengthening commercialization timelines relative to FDA pathways. The Rhine-Ruhr industrial belt concentrates immunoassay reagent manufacturing, with Baden-Württemberg housing precision optical component suppliers serving analyzer assembly.
China
Domestic manufacturers capture share in molecular diagnostic instruments as NMPA innovation designations accelerate review timelines for locally produced platforms. Health systems in Shanghai and Beijing prioritize decentralized testing infrastructure deployment into retail clinic networks. The Yangtze River Delta clusters IVD instrument production, with Suzhou and Hangzhou emerging as contract manufacturing hubs for multinational reagent suppliers.
India
Private hospital chains and standalone reference laboratories in Mumbai, Delhi, and Bangalore underinvest in automated platforms relative to test volume growth trajectory. CDSCO regulatory pathways for IVD devices remain less harmonized with FDA predicate requirements, complicating dual-market registration strategies. Diagnostic laboratory consolidation accelerates in metropolitan clusters as venture capital flows into standardized pathology networks.
Japan
Aging demographics sustain demand for metabolic disorder and cancer screening panels through hospital-affiliated laboratories. PMDA review processes for novel IVD instruments maintain alignment with FDA evidentiary standards, preserving market access predictability. The Kansai region around Osaka concentrates reagent manufacturing, while Tokyo anchors clinical trial activity for companion diagnostic development.
In-Vitro Diagnostics (IVD) Instruments Market Competitive Landscape
Top-tier vendors anchor the premium analyzer segment, while mid-scale specialists occupy regional reagent niches and service-dependent installed bases. The vendor structure concentrates around integrated platform providers with captive consumable streams, compressing standalone equipment manufacturers into price-competitive positioning. Strategic archetypes include reagent-locked ecosystem builders, modular platform diversifiers, and precision component verticalists. Competitive moves center on reagent rental contract expansion and field service network densification.
Among Swiss and German-origin conglomerates, Roche Diagnostics and Siemens Healthineers exemplify the integrated platform archetype through analyzer-installed base anchoring. Danaher occupies a position within the precision life sciences instrumentation tier, with Beckman Coulter and Leica Biosystems representing modular diversification strategies. These three entities illustrate how reagent pull-through economics and lifecycle service contracts sustain margin structures against capital equipment commoditization pressure.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| BD |
| bioMérieux |
| QIAGEN |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up diagnostic laboratory chains in the United States and Germany anchor reagent rental contracts that compress capital equipment pricing while locking in long-term consumable commitments, creating asymmetric bargaining power against standalone instrument manufacturers. This ownership concentration reshapes supply behavior toward volume-tiered procurement and forces pricing discipline through consolidated group purchasing organization leverage.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-throughput analyzers as domestic manufacturers exploit NMPA innovation pathways to undercut established import premiums. Three-tier pricing structure across premium, standard, and economy levels separates high-throughput immunoassay platforms from modular PCR systems and entry-level point-of-care devices. Cost compression in the economy tier is intensifying because of standardized reagent formulations and reduced field service bundling. Independent diagnostic laboratories exhibit the highest price sensitivity due to thin per-test margins, while academic medical centers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates in China's NMPA innovation pathway are reshaping sourcing patterns for electromechanical components and optical subsystems. Precision photomultiplier tubes and laser diodes draw from Japanese and German specialty suppliers, while magnetic bead formulations and chemiluminescent substrates rest on Chinese and US chemical manufacturing. Single-source vulnerability concentrates in photonics components where Hamamatsu and Osram anchor global capacity. Distribution runs through regional service hubs in Suzhou, Indianapolis, and Mannheim that coordinate field engineer deployment and spare parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's compressed NMPA review timelines and the EU's extended IVDR clinical evidence requirements creates regulatory cost differentials that favor dual-track registration strategies prioritizing Asian market entry.
For Market Incumbents: To counter next-generation sequencing displacement in oncology panels, immunoassay incumbents should deepen reagent lock-in through expanded menu breadth for cardiac and endocrine biomarkers while anchoring field service density in India's underautomated metropolitan clusters. Backward integration into precision optical component supply buffers tariff exposure on Japanese photomultiplier sourcing. For New Entrants and Emerging Players: Enter via India's diagnostic laboratory consolidation wave, where venture-backed pathology networks in Mumbai and Bangalore underinvest in automation relative to test volume growth. White-space targets include mid-throughput immunoassay platforms with localized reagent manufacturing and AI-assisted hematology smear interpretation modules. A direct sales model bypassing GPO concentration in the United States preserves margin capture. For Investors and Strategic Acquirers: Precision life sciences conglomerates are the most active acquirer in this space, seeking modular platform diversification to offset capital equipment commoditization. Over a multi-year horizon, target archetypes include regional reagent specialists with captive installed bases and field service networks in underserved geographies. The signal to watch is NMPA domestic-manufacturing quota expansion compressing import market access.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contract Expansion | Roche Diagnostics locks long-term consumable commitments through cobas analyzer placements. |
| AI-Assisted Result Interpretation | Machine learning algorithms reduce pathologist review burden in immunofluorescence workflows. |
| NMPA Innovation Pathway Registration | Domestic manufacturers accelerate molecular diagnostic instrument review timelines in China. |
| Field Service Network Densification | Beckman Coulter uptime guarantees anchor hospital system loyalty across CLIA-certified laboratories. |
| Next-Generation Sequencing Platform Launch | Oncology and infectious disease panels absorb capital allocation from conventional PCR systems. |
Research Methodology
Bottom-up hospital and diagnostic laboratory modeling reconciled against top-down instrument shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, GPO contracts managers, regulatory affairs specialists, and reference laboratory directors combined with secondary validation from FDA 510(k) filings, NMPA registration databases, hospital procurement records, and EU IVDR technical documentation. Triangulation across these sources ensures segment-level granularity.
Historical trendline analysis of analyzer placements and reagent consumption patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include technology type, end-user facility scale, application area, and regional regulatory cluster. CAGRs derived from unit economics modeling incorporate test volume trajectories, reimbursement code stability, and automation adoption curves specific to immunoassay and molecular diagnostic workflows.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time reagent pricing transparency and private diagnostic laboratory financials introduce uncertainty bands. Forecasts reflect assumptions on CLIA complexity waiver expansion, IVDR implementation pacing, and NMPA domestic-content incentive durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market