
 Next-Generation Sequencing for Non-Invasive Prenatal Testing Market | 2026-2036
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market Foresight
Direct-to-physician laboratory partnerships is rewriting how NIPT services reach expectant mothers across developed healthcare systems. Illumina, Inc. leverages its dominance in sequencing-by-synthesis instrument placement to anchor clinical laboratory workflows. BGI Genomics competes through integrated sequencing and bioinformatics operations spanning multiple continents. Thermo Fisher Scientific Inc. extends its position via reagent and platform standardization that reduces laboratory switching costs.
Next-generation sequencing for non-invasive prenatal testing deploys massively parallel sequencing of cell-free fetal DNA fragments circulating in maternal blood, typically requiring minimum 4% fetal fraction for reliable aneuploidy detection. The technology enables chromosomal abnormality screening without invasive sampling procedures that carry miscarriage risk. Targeted sequencing approaches command substantial volume in routine trisomy screening due to lower per-test cost and faster turnaround. Nanopore sequencing technologies represent the fastest-expanding technology segment as Oxford Nanopore's platforms enable point-of-care deployment with reduced capital footprint. Diagnostic laboratories capture the dominant end-user share, though fertility clinics are expanding NIPT adoption within pre-implantation genetic testing workflows.
FDA oversight of laboratory-developed tests and the EU's In Vitro Diagnostic Regulation impose divergent validation requirements that fragment product registration strategies across jurisdictions. China's NMPA maintains separate clinical trial mandates for imported versus domestically manufactured NIPT assays, creating asymmetric market access conditions. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies and prepare for potential classification shifts that could reclassify NIPT from screening to diagnostic indication in major markets.
Market Dynamics
Cell-free DNA screening protocols are consolidating around massively parallel sequencing platforms as clinical laboratories face mounting pressure to reduce per-test turnaround times while maintaining detection sensitivity thresholds. This technological standardization is compressing vendor differentiation and reshaping procurement criteria across hospital maternity units and diagnostic chains.
Growth Catalysts
- EU In Vitro Diagnostic Regulation (IVDR):The 2022 implementation timeline is accelerating CE-marking investments among assay developers, creating compliant product pipelines that unlock European market access for validated NIPT kits.
- Fertility clinic integration:Pre-implantation genetic testing workflows are absorbing cell-free fetal DNA screening into embryo selection protocols, expanding addressable volume beyond traditional obstetric indications.
- Nanopore sequencing:Oxford Nanopore's reduced-capital platforms are enabling point-of-care deployment in resource-constrained settings, decentralizing testing infrastructure from centralized reference laboratories.
Market Restraints
- Reagent supply concentration:Sequencing-by-synthesis chemistry production clusters in California and Massachusetts, exposing laboratories to single-source dependency risks during logistics disruptions.
- Fetal fraction variability:Maternal obesity and early gestational age samples frequently fall below the 4% detection threshold, generating no-call results that require invasive follow-up procedures.
- China NMPA asymmetry:Domestic versus imported assay trial requirements create divergent approval timelines that disadvantage foreign manufacturers seeking parity with BGI Genomics and local competitors.
Strategic Opportunities
- Microdeletion syndrome expansion:Targeted panel extensions beyond trisomy detection into 22q11.2 deletion and other submicroscopic abnormalities command premium pricing in tertiary care centers.
- Germany's statutory reimbursement:The G-BA's 2022 NIPT inclusion in prenatal care guidelines establishes a reimbursement template that neighboring EU member states are evaluating for adoption.
- AI-assisted variant interpretation:Machine learning integration with bioinformatics pipelines is compressing reporting timelines and reducing specialist cytogeneticist staffing requirements.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories struggle to recruit computational biologists capable of validating variant calling algorithms under FDA quality system regulations.
- Instrument obsolescence cycles:Three-year platform refresh timelines strain capital budgets as sequencing throughput per run doubles with each generation, forcing premature depreciation of installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Sequencing for Non-Invasive Prenatal Testing Market |
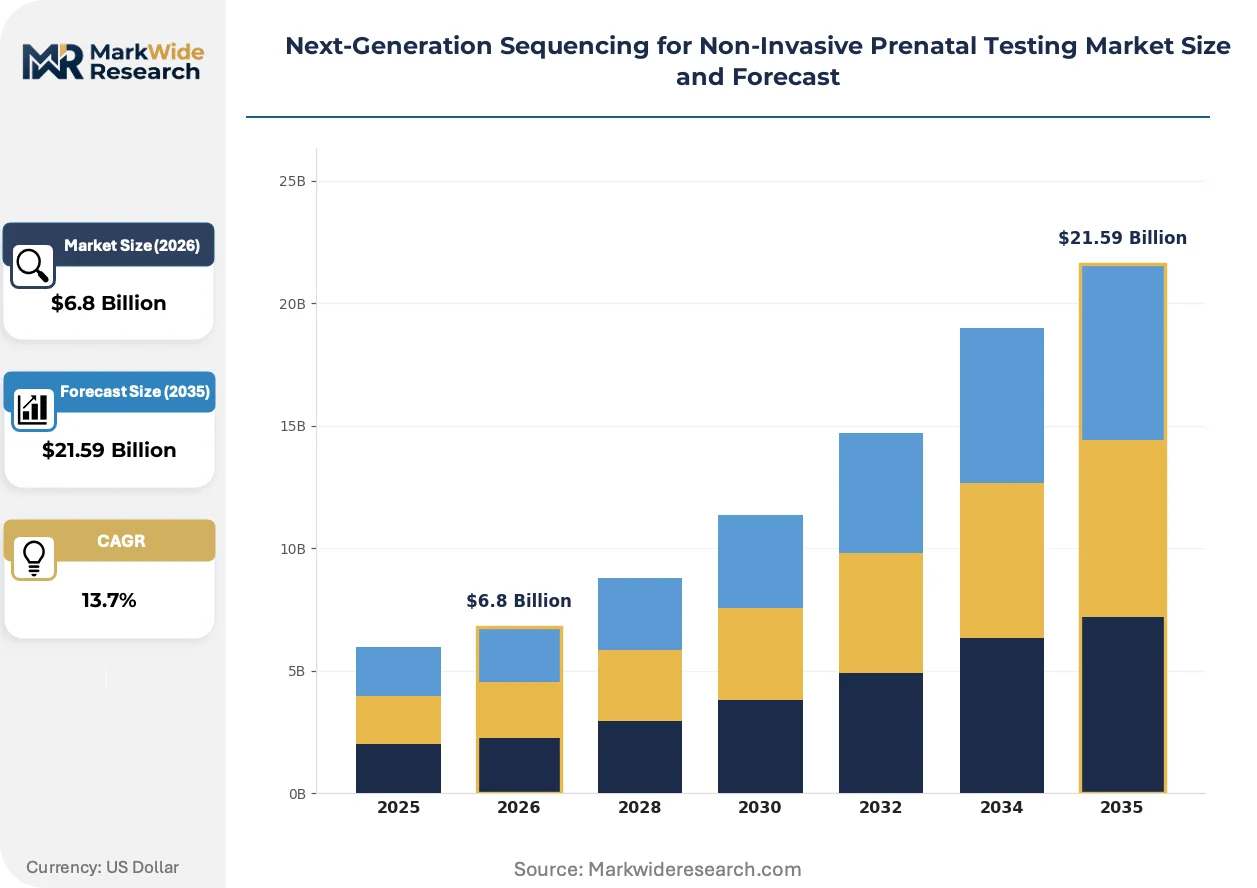
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, RNA Sequencing, Whole Genome Sequencing, Targeted Sequencing Technology: Sequencing by Synthesis, Ion Torrent, Single-Molecule Real-Time, Nanopore Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Fertility Clinics Application: Chromosomal Abnormality Detection, Genetic Disease Screening, Anomaly Diagnosis, Gender Determination |
| Companies Covered | Illumina, Inc., Natera, Inc., F. Hoffmann-La Roche Ltd., BGI Genomics, Laboratory Corporation of America Holdings, Berry Genomics, Thermo Fisher Scientific Inc., Eurofins LifeCodexx GmbH, Oxford Nanopore Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market Shifts & Advancements
Sequencing technology trajectories are fragmenting competitive positioning as point-of-care platforms challenge the centralized laboratory model that has dominated prenatal screening deployment. This divergence is creating parallel value chains with distinct equipment, consumable, and service requirements.
Targeted sequencing panels are migrating from whole-genome approaches in routine trisomy screening workflows. Hospital laboratories with moderate sample volumes are adopting these lower-cost alternatives to reduce reagent expenditure per test. The technology is migrating from high-complexity reference centers toward mid-tier community hospitals that previously outsourced testing.
The FDA's 2023 guidance on laboratory-developed tests is tightening analytical validation requirements for cell-free DNA assays processed in-house. Manufacturers of sequencing platforms must now supply more extensive performance data to support clinical laboratory claims. High-throughput diagnostic chains in the United States are responding by consolidating LDT portfolios around vendor-supported kit configurations that transfer regulatory liability.
Direct-to-physician laboratory partnerships are displacing traditional hospital outreach models as the primary distribution channel for NIPT services. Fertility specialists and maternal-fetal medicine practices now contract directly with reference laboratories, bypassing health system intermediaries. This channel compression is most visible in the United States and Germany where independent practice structures predominate.
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market Segmentation
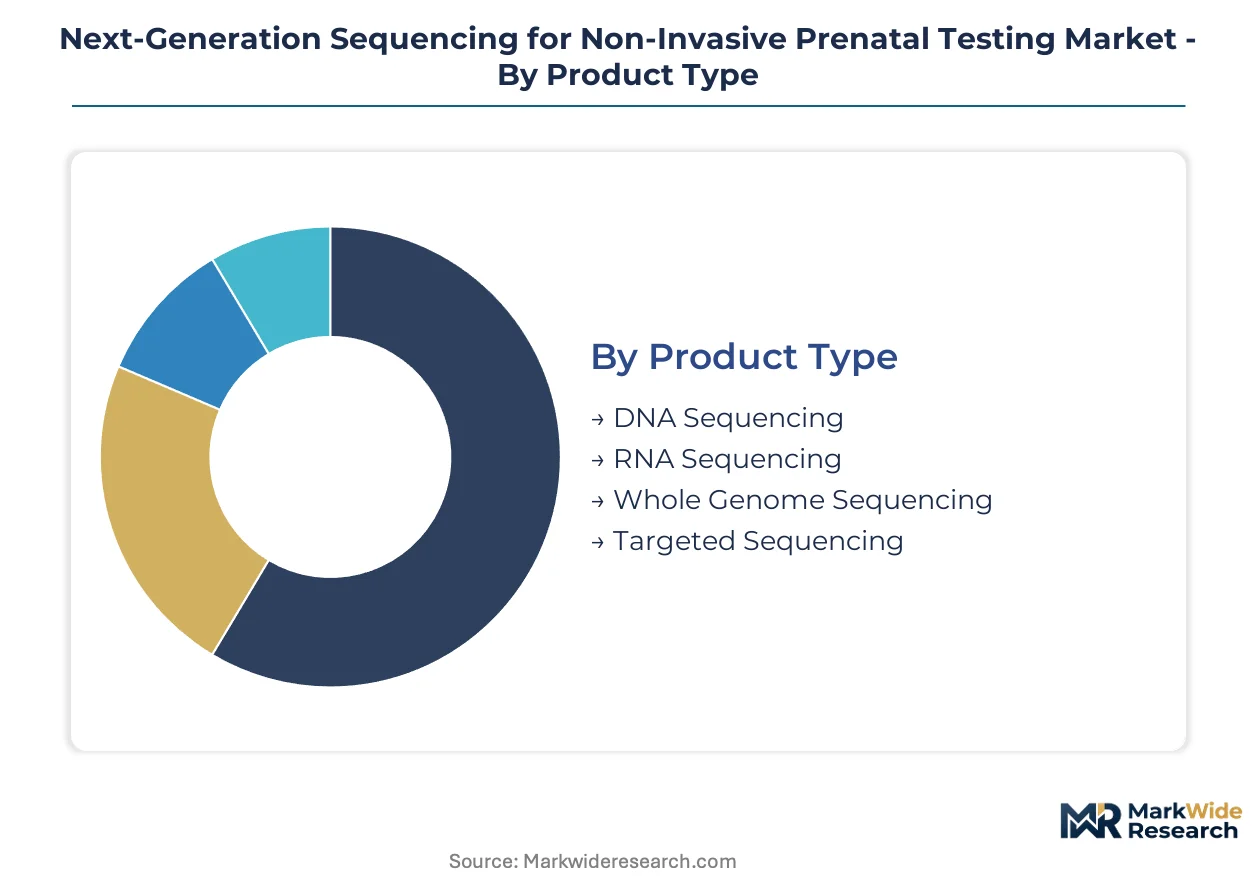
Segmentation of the NGS-based NIPT market reveals how sequencing chemistry, platform architecture, and care setting interact to determine test economics and clinical utility. Each dimension carries distinct implications for capital deployment, reimbursement positioning, and competitive differentiation.
Product Type:
Cost tier differentiation across sequencing methodologies shapes laboratory procurement decisions and per-test economics in high-throughput screening environments.
- Targeted Sequencing:Focused panels interrogate specific chromosomal regions associated with common aneuploidies, reducing reagent consumption and computational burden. Hospital maternity units in the United States and Germany favor this approach for routine trisomy screening due to faster turnaround and lower per-sample cost.
- Whole Genome Sequencing:Comprehensive fetal genome analysis enables detection of rare microdeletions and submicroscopic abnormalities beyond standard panel coverage. Tertiary care centers in China absorb premium pricing for expanded indications where clinical utility data supports reimbursement claims.
- DNA Sequencing:Cell-free fetal DNA fragment analysis constitutes the dominant methodological foundation for current NIPT workflows.
- RNA Sequencing:Transcriptomic approaches remain exploratory for prenatal applications, with limited commercial deployment.
Targeted Sequencing commands the established base. The steepest expansion runs through Whole Genome Sequencing.
Technology:
Platform maturity versus disruptive potential creates divergent investment profiles for laboratories evaluating instrument refresh cycles.
- Sequencing by Synthesis:Illumina's reversible terminator chemistry dominates installed base metrics across clinical reference laboratories. The technology delivers high accuracy and established regulatory validation packages that accelerate laboratory-developed test deployment in FDA-inspected facilities.
- Nanopore Sequencing:Oxford Nanopore's single-molecule detection enables real-time analysis with minimal capital footprint and portable form factors. Community hospitals in resource-constrained settings adopt these platforms to decentralize testing from centralized reference laboratories.
- Ion Torrent:Semiconductor-based detection offers intermediate throughput positioning between capillary electrophoresis and high-output sequencing-by-synthesis systems.
- Single-Molecule Real-Time:Pacific Biosciences' long-read technology addresses structural variant detection with limited current penetration in routine prenatal screening workflows.
Sequencing by Synthesis anchors current volume. Nanopore Sequencing is gaining share fastest among new platform acquisitions.
End User:
Customer type concentration determines go-to-market architecture, with direct laboratory partnerships displacing traditional distribution channels.
- Diagnostic Laboratories:High-complexity reference centers process the majority of cell-free DNA screening volume through centralized workflows. Quest Diagnostics and LabCorp in the United States, along with Eurofins and Synlab in Germany, leverage scale economies to compress per-test pricing.
- Fertility Clinics:Pre-implantation genetic testing integration is expanding addressable volume beyond traditional obstetric indications. Specialized reproductive medicine practices in the United States and Spain now contract directly with sequencing service providers for embryo selection protocols.
- Hospitals:In-house maternity unit laboratories with moderate sample volumes increasingly adopt targeted sequencing platforms to retain revenue previously outsourced.
- Research Institutions:Academic medical centers drive assay development and clinical validation studies that support subsequent commercial kit registration.
Diagnostic Laboratories maintain volume leadership. Fertility Clinics show the steepest expansion trajectory as pre-implantation applications mature.
Application:
Clinical indication breadth determines reimbursement eligibility and pricing power across screening versus diagnostic categories.
- Chromosomal Abnormality Detection:Trisomy 21, 18, and 13 screening represents the validated indication base with established positive predictive value metrics. Germany's G-BA reimbursement inclusion and similar health technology assessments in France and the Netherlands sustain volume concentration in European markets.
- Genetic Disease Screening:Expanded panels targeting single-gene disorders and carrier status are migrating from research use to clinical validation. China's NMPA has approved domestic assays for thalassemia and deafness gene screening, creating parallel regulatory pathways.
- Anomaly Diagnosis:Confirmatory testing following ultrasound abnormalities commands premium pricing in maternal-fetal medicine subspecialty practices.
- Gender Determination:Non-medical sex selection applications face regulatory restrictions in multiple jurisdictions including India and China.
Chromosomal Abnormality Detection holds the reimbursement foundation. Genetic Disease Screening is climbing the fastest as panel expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area's sequencing instrument manufacturing corridor underwrites United States dominance in NIPT platform supply, while Shanghai's Yangshan deep-water port enables China's reagent import velocity.
United States
FDA oversight of laboratory-developed tests and commercial insurance reimbursement parity drive clinical laboratory consolidation. The agency's 2023 analytical validation guidance tightens performance data requirements for cell-free DNA assays. High-throughput diagnostic chains in California and Massachusetts absorb regulatory liability through vendor-supported kit configurations.
China
NMPA maintains divergent clinical trial mandates for imported versus domestically manufactured assays, accelerating local kit registration timelines. The regulator's thalassemia and deafness gene screening approvals create parallel commercial pathways. BGI Genomics anchors integrated sequencing operations across Shenzhen and Beijing manufacturing clusters.
Germany
The G-BA's 2022 NIPT inclusion in statutory prenatal care guidelines establishes reimbursement precedent across EU member states. Eurofins and Synlab diagnostic chains leverage scale economies to compress per-test pricing in Berlin and Hamburg laboratory networks. The country's maternity units adopt targeted sequencing for routine trisomy screening workflows.
United Kingdom
NHS England's fetal anomaly screening program drives centralized procurement of cell-free DNA testing services. The National Institute for Health and Care Excellence evaluates expanded panel coverage for microdeletion syndromes. London reference laboratories process volume for fertility clinic partnerships across Southeast England.
Japan
PMDA's structured clinical trial requirements for prenatal diagnostics extend approval timelines for foreign assay developers. METI's genomic medicine promotion framework subsidizes sequencing infrastructure deployment in Osaka and Nagoya metropolitan hospitals. Domestic laboratories prioritize targeted panels for aneuploidy detection in advanced maternal age populations.
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The vendor base concentrates around sequencing-by-synthesis instrument manufacturers with established regulatory validation packages. Three archetypes dominate: integrated sequencing-and-bioinformatics operators, reference laboratory service providers, and point-of-care platform disruptors. Competitive moves center on direct-to-physician channel compression and fertility clinic partnership expansion.
Among platform integrators, Illumina, Inc. and Thermo Fisher Scientific Inc. occupy positions anchoring clinical laboratory workflows through instrument placement and reagent standardization. BGI Genomics exemplifies the vertically integrated archetype spanning manufacturing and service delivery across multiple continents. Oxford Nanopore Technologies represents the point-of-care disruption vector with reduced-capital platforms enabling decentralized deployment.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Natera, Inc. |
| F. Hoffmann-La Roche Ltd. |
| BGI Genomics |
| Laboratory Corporation of America Holdings |
| Berry Genomics |
| Thermo Fisher Scientific Inc. |
| Eurofins LifeCodexx GmbH |
| Oxford Nanopore Technologies |
| Others |
Supply & Pricing Matrix
Overcapacity in California and Massachusetts sequencing reagent manufacturing clusters is compressing supplier pricing power while forcing diagnostic laboratories to lock in multi-year consumable contracts. This utilization dynamic tightens margins for sequencing-by-synthesis chemistry producers even as hospital maternity units demand per-test cost reductions.
Pricing Analysis
Volume-discount tiering structures separate high-throughput diagnostic chains from mid-tier hospital laboratories and fertility clinics. Pricing stratifies across premium whole-genome expanded panels, standard targeted trisomy screening, and economy reflex testing protocols. Cost compression in the standard tier is intensifying because BGI Genomics and domestic Chinese manufacturers are exporting aggressively into European and Southeast Asian markets. Fertility clinics demonstrate highest price sensitivity due to fragmented practice structures and direct-to-physician contracting, while tertiary care centers in China absorb premium pricing for microdeletion syndrome expansion panels.
Supply Chain Analysis
Contract manufacturing concentration rests with Illumina's San Diego production facilities, Thermo Fisher's Massachusetts operations, and BGI Genomics' Shenzhen manufacturing clusters. Raw material dependencies include fluorescent nucleotides, semiconductor flow cells, and synthetic oligonucleotide libraries. Single-source vulnerability runs through California-based sequencing reagent production, where logistics disruptions during wildfire seasons have previously constrained clinical laboratory operations. Distribution runs through direct vendor-to-laboratory partnerships that displace traditional medical device distributors, with point-of-care nanopore platforms increasingly shipping through specialized life science supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's expansion is constrained by acute shortages of computational biologists capable of validating variant calling algorithms under FDA quality system regulations. This capability gap creates asymmetric returns for stakeholders who secure bioinformatics talent pipelines or automated interpretation platforms.
For Market Incumbents: Harden regulatory validation packages against tightening FDA laboratory-developed test guidance by pre-submission engagement with the agency's Center for Devices and Radiological Health. Anchor hospital maternity unit relationships through captive reagent supply contracts that increase switching costs when Oxford Nanopore's point-of-care platforms threaten decentralization. Prioritize backward integration into synthetic oligonucleotide production to reduce exposure to single-source nucleotide suppliers in California. For New Entrants and Emerging Players: Pursue fertility clinic direct contracting channels in Spain and the United States, where pre-implantation genetic testing workflows remain underpenetrated by established reference laboratory networks. Target Germany's statutory reimbursement environment, where G-BA inclusion creates immediate addressable volume without private payer negotiation delays. Lead with AI-assisted variant interpretation as a service layer that reduces specialist cytogeneticist staffing requirements for mid-tier hospital laboratories. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated sequencing-and-bioinformatics operators with locked-in reagent consumable streams. Long-term viability over the projection horizon favors targets with NMPA domestic assay approvals in China, where asymmetric trial requirements protect local manufacturers from imported competition. Watch for FDA reclassification signals that could shift NIPT from screening to diagnostic indication, fundamentally altering reimbursement and competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR compliance unlocks European market access for validated NIPT kits against fragmented national requirements. |
| Hospital System Partnership | Direct laboratory contracts with maternal-fetal medicine practices bypass health system intermediaries in Germany and the United States. |
| Software Companion Development | AI-assisted variant interpretation reduces specialist cytogeneticist staffing requirements and compresses reporting timelines. |
| Reimbursement Strategy | G-BA inclusion in Germany establishes template for neighboring EU member state health technology assessments. |
| Regulatory Approval Pathway | NMPA domestic trial mandates accelerate local kit registration timelines versus imported assay requirements in China. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with clinical laboratory directors, maternal-fetal medicine specialists, regulatory affairs leads at sequencing platform manufacturers, and procurement managers at diagnostic chains. Secondary validation drew from FDA 510(k) filings, NMPA registration databases, EMA IVDR technical documentation, G-BA reimbursement decisions, and hospital procurement contract disclosures. Bottom-up test volume modeling across diagnostic laboratories, fertility clinics, and hospital maternity units was triangulated against top-down market sizing from instrument placement data and reagent consumption estimates.
Calibration against historical instrument shipment records and consumable revenue disclosures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include sequencing methodology, platform technology, end-user facility type, clinical application, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to reimbursement expansion timelines and technology substitution patterns. Industry-specific forecast inputs incorporated fetal fraction detection threshold improvements and nanopore sequencing accuracy trajectories.
Sensitivities concentrate around FDA reclassification decisions, NMPA trial requirement modifications, and G-BA reimbursement scope expansions. Forecasts reflect documented assumptions regarding regulatory pathway timelines and technology adoption rates. Quarterly review of instrument placement announcements, reimbursement coding updates, and regulatory guidance publications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Digital Genome Market
Genomics
Restriction Endonucleases Market
Genomics
Global Pharmacogenomics Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Global Digital PCR Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Glycan Sequencing Market
Genomics
Plant Genomics Market
Genomics
DNA Sequencing Services Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Pharmacogenomic (Pgx) Testing Market