
 Restriction Endonucleases Market | 2026-2036
Restriction Endonucleases Market Size, Share, and Industry Trends Forecast 2026-2036
Restriction Endonucleases Market Outlook
CRISPR-Cas9 integration with traditional restriction endonucleases is narrowing the functional gap between research-grade and therapeutic-grade enzyme requirements. Thermo Fisher Scientific leverages its reagent-to-instrument ecosystem to control workflow pricing across academic and commercial accounts. New England Biolabs anchors its position through concentrated manufacturing in Ipswich, Massachusetts, with deep vertical integration into recombinant protein production. Takara Bio Inc. competes through specialized cold-chain distribution networks spanning Asia-Pacific and North American research markets.
Restriction endonucleases are bacterial enzymes that recognize specific double-stranded DNA sequences—typically palindromic motifs of 4 to 8 base pairs—and cleave phosphodiester bonds at or near these sites, with Type II enzymes constituting the dominant commercial class due to their predictable cleavage patterns. These enzymes serve as foundational tools for DNA fragmentation, molecular cloning, and gene editing across life science research and biopharmaceutical manufacturing. Type II Enzymes capture the largest revenue share given their established protocols and broad protocol compatibility, while Modified Enzymes represent the fastest-expanding category as engineered variants with altered specificity or enhanced thermostability command premium pricing in gene editing workflows. Academic Research Institutes remain the volume anchor, though Pharmaceutical Companies now drive margin expansion through GMP-grade enzyme procurement for cell and gene therapy manufacturing.
FDA oversight of gene therapy manufacturing and EPA guidelines for recombinant microorganism containment shape enzyme quality standards and facility compliance costs in the United States, while ISO 13485 certification requirements influence supplier qualification for diagnostic applications in Europe and Asia. The EU AI Act and GDPR frameworks indirectly constrain automated sequence analysis platforms that integrate restriction mapping algorithms, affecting downstream software-enzyme bundled sales. Stakeholders must monitor evolving GMP-grade specifications from FDA and EMA as cell therapy commercialization scales, since enzyme purity tiers will increasingly determine supplier switching costs and contract manufacturing organization partnerships.
Market Dynamics
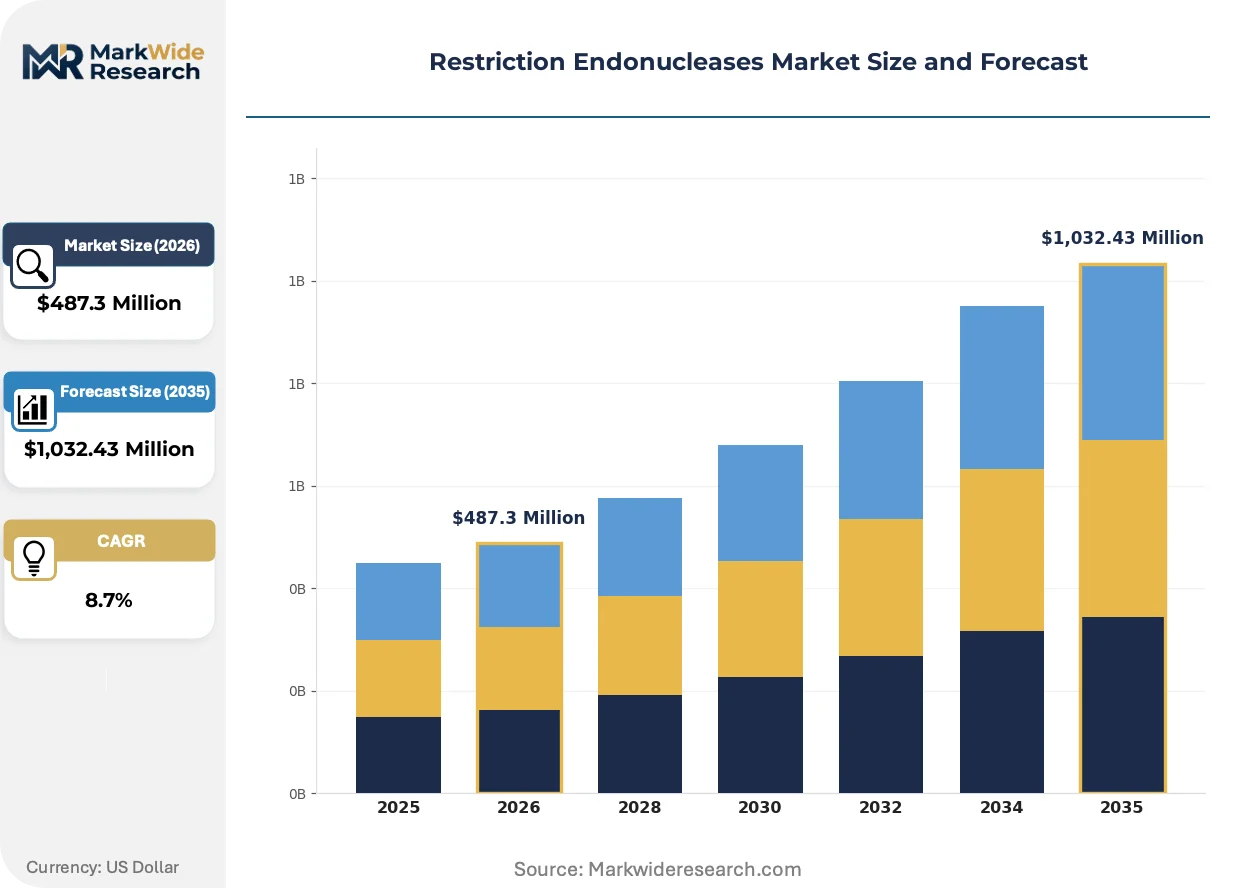
CRISPR-Cas9 workflows are compressing demand for traditional restriction endonucleases in research settings while simultaneously expanding GMP-grade enzyme requirements for therapeutic manufacturing. This bifurcation is reshaping supplier portfolios and pricing architectures across the value chain.
Growth Catalysts
- Cell therapy manufacturing scale-up:FDA-approved gene therapies are requiring bulk enzyme procurement with validated purity tiers, pulling contract manufacturers into long-term supply agreements.
- ISO 13485 certification expansion:Diagnostic device manufacturers in Europe and Asia are mandating certified enzyme inputs, creating qualification barriers that favor established suppliers.
- Gene editing pipeline maturation:Pharmaceutical companies in Boston and San Francisco biotech corridors are widening R&D enzyme volumes for IND-enabling studies.
Market Restraints
- Recombinant protein input volatility:Fermentation-grade yeast extract and specialized media costs fluctuate with agricultural commodity markets, squeezing margins on high-volume standard-grade enzymes.
- Supplier concentration in coastal Massachusetts:A dominant share of Type II enzyme manufacturing capacity clusters within a 50-mile radius of Ipswich, creating weather and logistics vulnerability.
- CRISPR-Cas9 substitution in research:Programmable nucleases are displacing restriction enzymes in cloning workflows, compressing addressable demand in academic segments.
Strategic Opportunities
- GMP-grade enzyme white space in Asia-Pacific:Japan, South Korea, and Singapore are building cell therapy manufacturing hubs with limited local validated enzyme supply, opening qualification windows for entrants.
- Engineered thermostable variants:Enzymes with extended half-life at elevated temperatures are enabling single-tube reaction protocols that reduce handling steps in automated workflows.
- EU Green Deal biomanufacturing incentives:Sustainability-linked procurement criteria are favoring suppliers with renewable energy-powered fermentation facilities and reduced solvent purification processes.
Industry Challenges
- GMP-grade validation timelines:FDA and EMA documentation requirements for enzyme master files are extending qualification cycles to 18-24 months, delaying revenue recognition for new entrants.
- Specialized fermentation workforce scarcity:Recombinant protein production requires PhD-level strain engineering talent that concentrates around legacy biotechnology clusters, constraining geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restriction Endonucleases Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type II Enzymes, Type I Enzymes, Type III Enzymes, Modified Enzymes Application: Molecular Cloning, Gene Editing, DNA Fragmentation, Genetic Engineering End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Diagnostics Labs Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Thermo Fisher Scientific, New England Biolabs, Takara Bio Inc., Agilent Technologies, Merck KGaA, Promega Corporation, QIAGEN, Illumina Inc., GenScript, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restriction Endonucleases Market Strategic Shifts
Enzyme engineering and regulatory automation are converging to redefine product specifications and customer engagement models. Suppliers are racing to align technical roadmaps with evolving therapeutic manufacturing standards.
Engineered restriction endonucleases with altered recognition specificity are hybridizing with CRISPR-Cas9 systems in complex gene editing workflows. Pharmaceutical process development teams are adopting these hybrid toolkits for precise genomic scar generation. The technology is hybridizing research and therapeutic-grade enzyme categories, forcing suppliers to unify quality systems across previously separate product lines.
EMA's evolving GMP guidelines for starting materials in gene therapy manufacturing are tightening enzyme impurity specifications. Manufacturers must now demonstrate absence of host-cell DNA below 10 nanograms per dose, requiring additional validation steps. European contract development organizations are responding by consolidating supplier panels to reduce audit burden.
Academic core facilities are consolidating purchasing through group procurement organizations to capture volume discounts previously reserved for pharmaceutical accounts. Thermo Fisher Scientific and MilliporeSigma are deploying dedicated field specialists to these aggregators, displacing traditional distributor relationships. This concentration is most visible in United States Research I institutions where shared instrumentation centers centralize enzyme specification decisions.
Restriction Endonucleases Market Segmentation
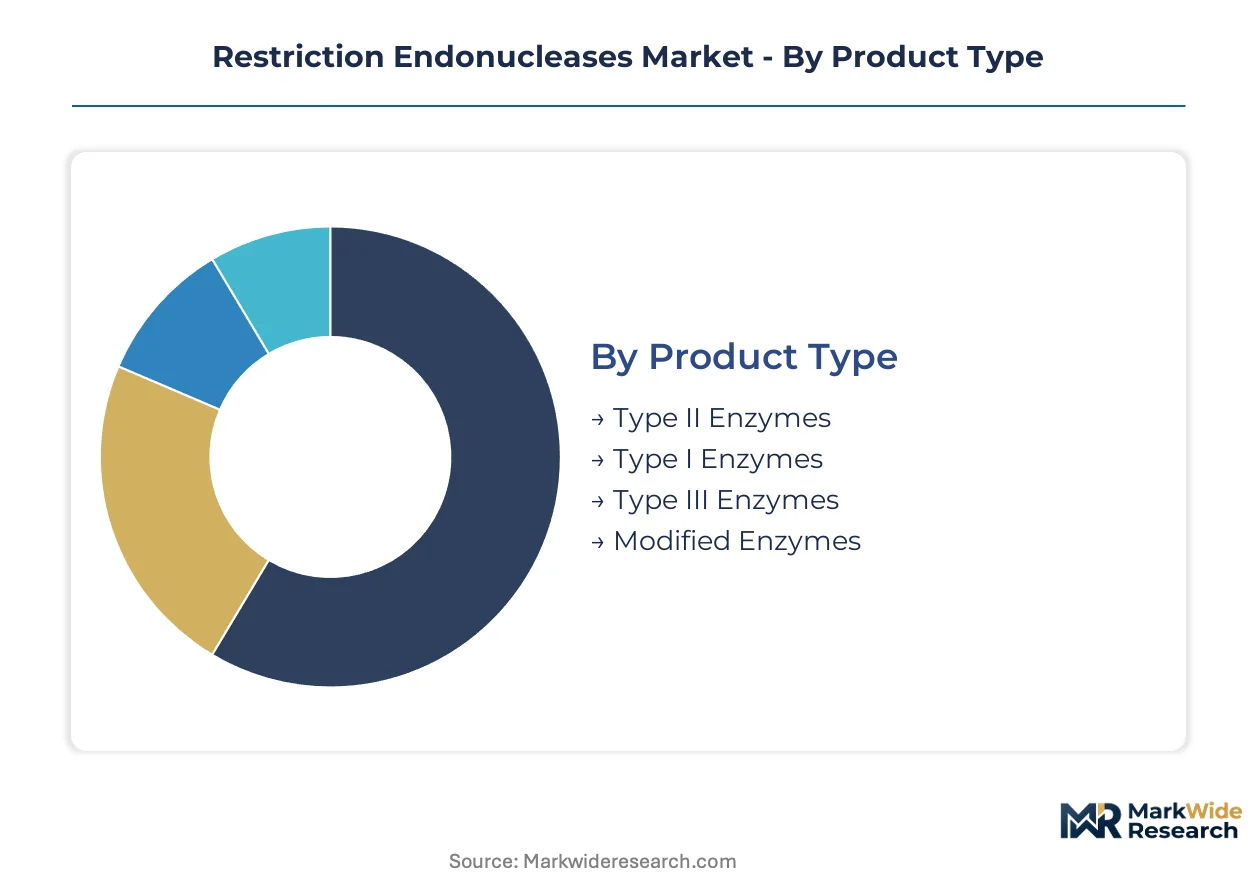
Restriction endonuclease procurement cycles vary dramatically across segments, with research-grade enzymes turning over in weeks while GMP-grade validations stretch across quarters. Understanding these velocity differences helps suppliers align inventory models with cash flow requirements.
Product Type:
Cycle times compress from years to months as one moves from validated therapeutic grades to standard research formulations.
- Type II Enzymes:These bacterial enzymes recognize palindromic DNA sequences of 4 to 8 base pairs and cleave at predictable positions within or adjacent to recognition sites. Pharmaceutical manufacturing in Boston and San Francisco corridors consumes bulk volumes for IND-enabling studies, though academic labs remain the volume anchor through routine cloning workflows.
- Modified Enzymes:Engineered variants with altered specificity, enhanced thermostability, or reduced star activity command premium pricing in automated gene editing workflows. Gene therapy process development teams in Singapore and South Korea are widening procurement of these variants for complex genomic scar generation protocols.
- Type I Enzymes:ATP-dependent restriction systems with variable cleavage positions see limited commercial deployment outside specialized bacterial strain engineering applications.
- Type III Enzymes:These bifunctional enzymes with combined restriction and modification activities occupy niche roles in plasmid copy number control research.
Type II Enzymes dominate installed base. Modified Enzymes is where expansion concentrates.
Application:
Cost tiers stratify sharply, with therapeutic manufacturing applications commanding 10-15x pricing multiples over research-grade consumables.
- Gene Editing:CRISPR-Cas9 integration with engineered nucleases is compressing development timelines for cell therapies. FDA oversight of gene therapy manufacturing is tightening enzyme impurity specifications, requiring demonstration of host-cell DNA below 10 nanograms per dose.
- Molecular Cloning:Traditional DNA insertion into plasmid vectors remains the foundational workflow across academic core facilities. Group procurement organizations at United States Research I institutions are consolidating purchasing to capture volume discounts previously reserved for pharmaceutical accounts.
- DNA Fragmentation:Controlled cleavage for next-generation sequencing library preparation drives standardized high-volume consumption.
- Genetic Engineering:Metabolic pathway construction and strain optimization in industrial biotechnology applications require flexible multi-enzyme cocktails.
Molecular Cloning dominates installed base. Gene Editing is climbing the fastest.
End User:
Customer type determines margin structure more than volume, with pharmaceutical procurement teams negotiating multi-year supply agreements against spot-market academic purchasing.
- Pharmaceutical Companies:GMP-grade enzyme procurement for cell and gene therapy manufacturing is pulling contract manufacturers into long-term supply agreements with validated purity tiers. EMA's evolving guidelines for starting materials are extending qualification cycles to 18-24 months.
- Academic Research Institutes:Shared instrumentation centers at Research I institutions centralize enzyme specification decisions. Thermo Fisher Scientific and MilliporeSigma deploy dedicated field specialists to these aggregators, displacing traditional distributor relationships.
- Biotechnology Firms:Mid-stage cell therapy developers in Japan and South Korea face limited local validated enzyme supply, opening qualification windows for entrants.
- Diagnostics Labs:ISO 13485 certification requirements in Europe and Asia are mandating certified enzyme inputs, creating qualification barriers that favor established suppliers.
Academic Research Institutes dominate installed base. Pharmaceutical Companies is where margin expansion concentrates.
Distribution Channel:
Supply concentration in coastal Massachusetts creates logistics vulnerability that channel strategy must address through redundant sourcing.
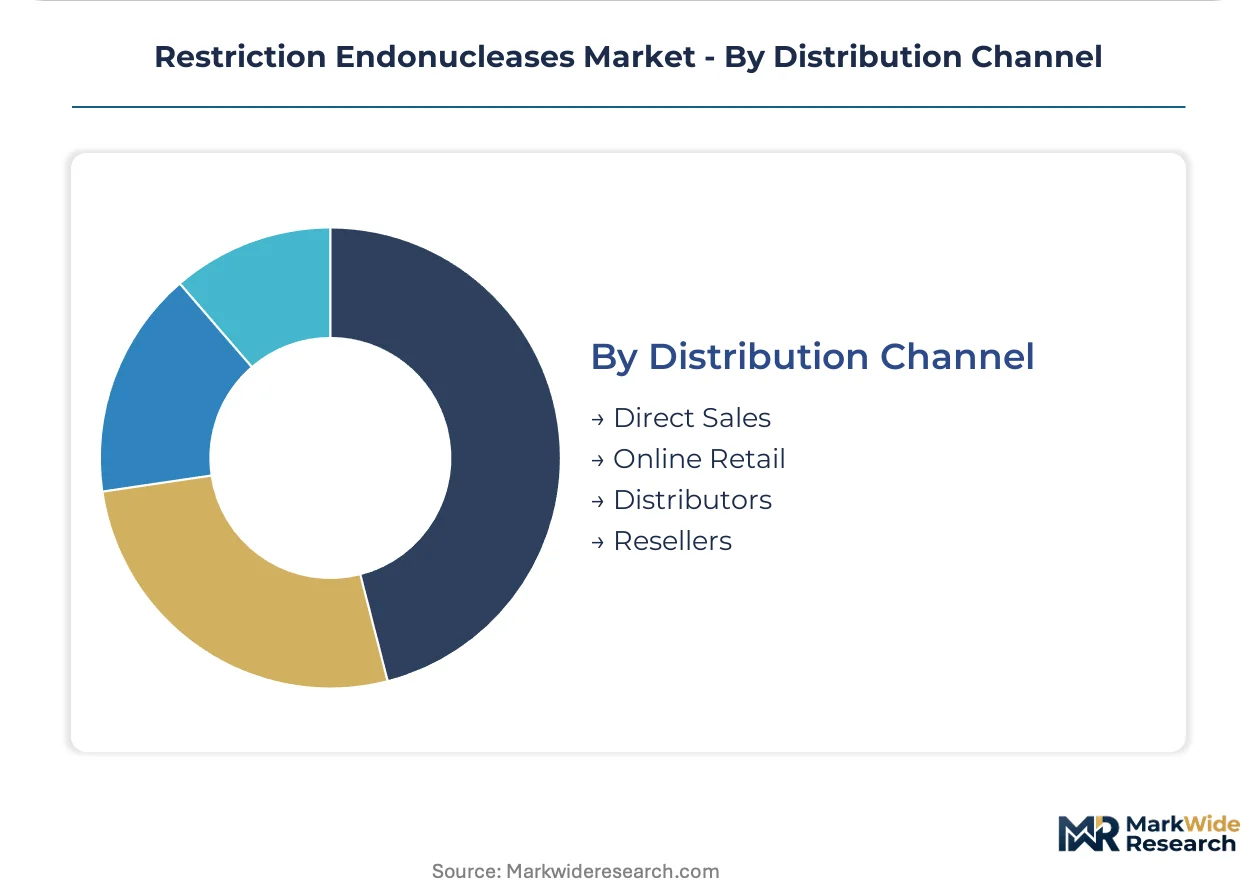
- Direct Sales:Multi-year supply agreements with pharmaceutical manufacturers bypass distributor markups while locking in volume commitments. Field application scientists provide technical support for complex GMP-grade validations.
- Distributors:Regional life science specialists maintain cold-chain integrity for temperature-sensitive enzyme shipments across Asia-Pacific research markets. Takara Bio Inc. competes through specialized distribution networks spanning these territories.
- Online Retail:E-commerce platforms capture standard-grade research enzyme replenishment with next-day delivery guarantees for routine cloning workflows.
- Resellers:Secondary channel partners serve fragmented academic accounts below direct sales minimums.
Distributors dominate installed base. Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export GMP-grade enzymes to Singapore and South Korea cell therapy hubs, while Japanese suppliers serve Asia-Pacific research markets through specialized cold-chain networks.
United States
FDA-approved gene therapies are requiring bulk enzyme procurement with validated purity tiers, pulling contract manufacturers into long-term supply agreements. EPA guidelines for recombinant microorganism containment shape facility compliance costs. Boston and San Francisco biotech corridors widen R&D enzyme volumes for IND-enabling studies.
Germany
EMA's evolving GMP guidelines for starting materials in gene therapy manufacturing tighten enzyme impurity specifications. REACH frameworks influence chemical reagent handling protocols. Heidelberg and Munich pharmaceutical clusters drive demand for diagnostic-grade enzyme inputs.
Japan
METI biomanufacturing incentives support local cell therapy manufacturing hub development with limited validated enzyme supply. PMDA oversight aligns with international GMP standards. Tokyo and Osaka research markets anchor regional consumption through academic core facilities.
Singapore
Biomedical Sciences Initiative funding accelerates cell therapy manufacturing infrastructure buildout. The national pharmaceutical regulator mandates alignment with FDA and EMA quality standards. Biopolis research corridor concentrates demand for engineered thermostable enzyme variants.
South Korea
MFDS gene therapy approval pathways are maturing, requiring GMP-grade enzyme documentation for commercial manufacturing. Government biotech investment programs support local CDMO capacity expansion. Songdo and Seoul metropolitan bioclusters drive procurement of modified enzyme formulations.
Restriction Endonucleases Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered pricing architectures. The vendor base separates into consolidated reagent-to-instrument ecosystems and concentrated manufacturing specialists. Three archetypes dominate: diversified life science conglomerates, recombinant protein production specialists, and regional distribution-anchored competitors. M&A activity targets GMP-grade validation capabilities, while capacity expansion focuses on renewable energy-powered fermentation facilities.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages its reagent-to-instrument ecosystem to control workflow pricing. New England Biolabs anchors the recombinant protein specialist position through concentrated manufacturing in coastal Massachusetts. Takara Bio Inc. exemplifies the regional distribution-anchored archetype, competing through specialized cold-chain networks spanning Asia-Pacific research markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| New England Biolabs |
| Takara Bio Inc. |
| Agilent Technologies |
| Merck KGaA |
| Promega Corporation |
| QIAGEN |
| Illumina Inc. |
| GenScript |
| Others |
Value Chain & Pricing Dynamics
Fermentation-grade yeast extract and specialized media suppliers in agricultural commodity markets anchor upstream cost structures, concentrating margin capture in GMP-grade enzyme tiers where purity validation creates switching costs. Standard research-grade enzymes face commodity-like pricing pressure, while therapeutic-grade variants command sustained premiums through FDA and EMA documentation requirements.
Pricing Analysis
Current-generation Type II enzymes trade at established price points, prior-generation formulations face compression from CRISPR-Cas9 substitution, and next-generation engineered thermostable variants capture premium positioning. Three-tier pricing structure across GMP-certified, research-grade, and bulk standard levels differentiates by ISO 13485 certification status and validated purity tiers. Cost compression in standard research grades is intensifying because academic core facilities consolidate purchasing through group procurement organizations. Biotechnology firms in Asia-Pacific cell therapy hubs show least price sensitivity due to limited local validated supply alternatives.
Supply Chain Analysis
Tariff exposure between United States and Asia-Pacific research markets dominates supply chain risk calculations for temperature-sensitive enzyme shipments. Manufacturing concentrates in coastal Massachusetts, Germany's Heidelberg pharmaceutical corridor, and Japan's Tokyo-Osaka research belt. Raw material dependencies include recombinant protein production strains, fermentation-grade yeast extract, and chromatography resins for purification. Single-source vulnerability clusters around PhD-level strain engineering talent concentrated in legacy biotechnology hubs. Distribution runs through specialized cold-chain networks for temperature-sensitive formulations, direct sales for pharmaceutical accounts, and regional life science distributors for academic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PhD-level recombinant protein production expertise concentrates in established biotechnology clusters, constraining geographic expansion and creating acquisition premiums for validated manufacturing capabilities. This scarcity dynamic favors incumbents with captive talent pipelines and challenges new entrants seeking GMP-grade qualification.
For Market Incumbents: Entrench position through backward integration into recombinant protein production strains and fermentation media supply, locking in cost visibility against agricultural commodity volatility. Add redundant manufacturing capacity outside coastal Massachusetts to mitigate weather and logistics concentration risk. Prioritize unified quality systems across research-grade and therapeutic-grade enzyme lines as hybrid CRISPR-nuclease workflows blur category boundaries. For New Entrants and Emerging Players: Asia-Pacific cell therapy manufacturing hubs in Singapore, South Korea, and Japan present the most penetrable white space due to limited local validated enzyme supply and 18-24 month qualification windows. Target biotechnology firms and contract development organizations building GMP-grade manufacturing capacity with engineered thermostable enzyme variants that enable single-tube reaction protocols. Establish partnerships with regional cold-chain distributors to bypass direct sales infrastructure gaps. For Investors and Strategic Acquirers: Capital is best deployed toward recombinant protein production specialists with existing ISO 13485 certification and FDA master file documentation, positioned for GMP-grade volume expansion as cell therapy commercialization scales. Long-term viability hinges on supplier consolidation into therapeutic manufacturing workflows rather than research-grade commoditization. Watch for EMA and FDA guidance revisions on starting material impurity specifications as the inflection signal for accelerated qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Grade Validation Investment | FDA and EMA master file documentation creates 18-24 month competitive moats for contract manufacturers. |
| Renewable Energy Fermentation Transition | EU Green Deal procurement criteria favor suppliers with carbon-neutral production facilities in Germany and Netherlands. |
| Engineered Thermostable Variant Development | Singapore Biopolis research corridor drives demand for single-tube reaction protocols in automated gene editing workflows. |
| Asia-Pacific Distribution Partnership | Takara Bio's cold-chain networks demonstrate channel control value in Japan, South Korea, and emerging Singapore hubs. |
| Academic Group Procurement Engagement | Thermo Fisher field specialists at United States Research I institutions displace traditional distributor relationships. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA gene therapy guidance documents, EMA GMP starting materials guidelines, ISO 13485 certification databases, and trade flow data for fermentation-grade inputs. Primary interviews engaged enzyme procurement managers at pharmaceutical companies, regulatory affairs leads at contract manufacturers, academic core facility directors, and recombinant protein production specialists. Bottom-up enzyme volume estimates by application tier triangulate against top-down market sizing through supplier revenue analysis.
Forecast inputs include gene editing pipeline maturation rates, cell therapy manufacturing capacity buildouts across Singapore, South Korea, and Japan, and CRISPR-Cas9 substitution patterns in academic research settings. Segmentation models incorporate product type tiers, application-grade specifications, end-user procurement structures, and regional regulatory clusters. CAGRs derive from volume trajectory analysis against pricing architecture shifts across the projection horizon, with specific weighting for GMP-grade qualification timeline delays and engineered variant adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by diversified life science conglomerates or accelerated regulatory harmonization between FDA and EMA would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
NGS Automation Market
Genomics
DNA Methylation Market
Genomics
Gene Sequencing Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Next Generation Genomics Market
Genomics
Genomics Personalized Health Market
Genomics
United States DNA Sequencing Products Market
Genomics
Agrigenomics Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Microbiome Sequencing Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Middle East and Africa Whole Exome Sequencing Market