
 Glycan Sequencing Market | 2026-2036
Glycan Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Glycan Sequencing Market Foresight
Biopharmaceutical quality control is shifting toward glycan profiling as biosimilar developers seek analytical parity with originator molecules. Waters Corporation leverages its UPLC-MS platform dominance to anchor high-throughput glycan screening workflows in North American contract research organizations. Shimadzu Corporation competes through integrated HPLC-FLR systems that reduce sample preparation burden for Asian biomanufacturers. Thermo Fisher Scientific extends its installed base via Orbitrap mass spectrometry configurations optimized for glycopeptide mapping.
Glycan sequencing encompasses the structural determination of carbohydrate chains attached to proteins and lipids, typically employing enzymatic release, fluorescent labeling, and separation by hydrophilic interaction chromatography with detection limits reaching femtomolar sensitivity. Its primary commercial purpose lies in ensuring batch-to-batch consistency of glycoprotein therapeutics where glycosylation patterns directly modulate efficacy and immunogenicity. Mass spectrometry instruments capture the dominant share of capital expenditure as resolution requirements tighten for complex glycan mixtures, while software segments exhibit the fastest expansion driven by automated structure prediction algorithms that reduce manual interpretation time. Reagents and consumables form a recurring revenue pool with margin profiles exceeding instruments due to per-run consumption patterns.
FDA biosimilar guidance, EMA immunogenicity assessment requirements, and ICH Q5E comparability protocols collectively elevate analytical rigor for glycan characterization across regulated markets. The FDA's evolving stance on glycosylation as a critical quality attribute directly shapes instrument qualification standards and software validation requirements for IND submissions. Stakeholders must monitor how WHO prequalification standards for biosimilars propagate glycan sequencing specifications into emerging manufacturing jurisdictions.
Market Dynamics
FDA biosimilar guidance and EMA immunogenicity protocols are forcing biopharmaceutical manufacturers to upgrade glycan characterization capabilities ahead of regulatory submission deadlines, compressing replacement cycles for legacy analytical platforms.
Growth Catalysts
- EMA immunogenicity assessment requirements:European biopharmaceutical developers must demonstrate glycosylation consistency across biosimilar batches, mandating high-resolution mass spectrometry deployment.
- Monoclonal antibody pipeline expansion:Therapeutic protein developers in the United States, Germany, and Japan require glycan profiling for every manufacturing run to secure batch release approvals.
- Automated structure prediction algorithms:Software vendors are embedding machine learning into glycan interpretation workflows, reducing manual analysis time and enabling higher-throughput screening.
Market Restraints
- Capital intensity of mass spectrometry platforms:Orbitrap and Q-TOF instruments require seven-figure investments that strain mid-tier contract research organization budgets.
- Fluorescent labeling reagent supply concentration:Two Japanese chemical suppliers control over half of high-purity 2-AB and APTS dye production, creating input vulnerability.
- Glycopeptide mapping complexity:Current fragmentation methods struggle to resolve isobaric glycan structures on multiply glycosylated proteins, limiting analytical confidence.
Strategic Opportunities
- Indian biosimilar manufacturing expansion:CDSCO alignment with WHO prequalification standards creates instrument demand among emerging biomanufacturers in Hyderabad and Bangalore clusters.
- Cell and gene therapy glycan analysis:Viral vector producers require glycoprotein characterization for AAV and lentiviral envelope proteins, opening adjacent application space.
- Cloud-based data interpretation platforms:Remote structure elucidation services allow smaller laboratories to access enterprise-grade bioinformatics without capital expenditure.
Industry Challenges
- Cross-trained analytical chemist scarcity:Glycobiology expertise combining mass spectrometry operation with carbohydrate biochemistry commands premium compensation and extends hiring timelines.
- 21 CFR Part 11 software validation burden:Electronic record systems for glycan analysis require documented installation qualification, operational qualification, and performance qualification protocols that delay deployment.
- Reference standard availability gaps:Certified glycan libraries for quantitative comparison remain limited for complex biantennary and triantennary structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycan Sequencing Market |
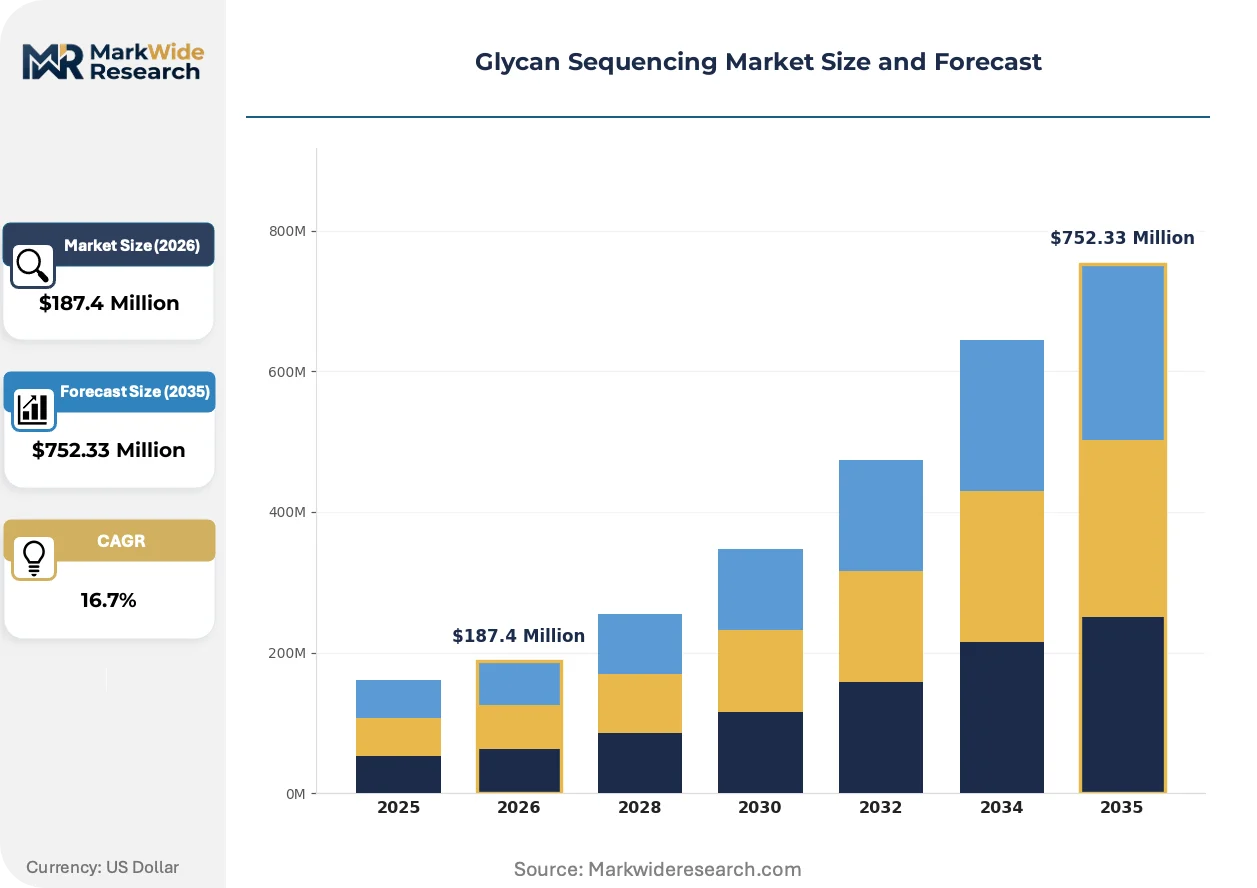
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $752.33 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Organizations Technology: Mass Spectrometry, High-Performance Liquid Chromatography, Capillary Electrophoresis, Microarray Application: Drug Development, Diagnostics, Biomarker Discovery, Quality Control |
| Companies Covered | Waters Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Asparia Glycomics, Bio-Techne Corporation, Agilent Technologies, New England Biolabs, Ludger Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycan Sequencing Market Shifts & Advancements
Technological convergence between artificial intelligence and high-resolution mass spectrometry is compressing glycan identification timelines from days to hours. Regulatory agencies are codifying glycosylation as a critical quality attribute across therapeutic classes. Procurement patterns are fragmenting as smaller biopharmaceutical developers bypass centralized core facilities.
Capillary electrophoresis coupled with laser-induced fluorescence detection is decentralizing glycan analysis from centralized mass spectrometry core facilities into individual quality control laboratories. Mid-sized biopharmaceutical developers in the United States and Germany are adopting CE-LIF systems for routine batch release testing. This instrumentation shift is compressing turnaround times and reducing per-sample costs by eliminating external service provider markups.
ICH Q5E comparability protocols now mandate glycan characterization for post-approval manufacturing changes across all EMA-regulated submissions. Biopharmaceutical manufacturers must demonstrate glycosylation pattern equivalence when modifying cell culture conditions or purification steps. European contract manufacturing organizations are responding by embedding dedicated glycan analysis suites within existing quality control infrastructure.
Biopharmaceutical procurement teams are unbundling after-sales service contracts from instrument purchases and negotiating region-specific maintenance agreements. Large molecule developers in Japan and South Korea now source spare parts and field service through independent third-party providers rather than original equipment manufacturer packages. This purchasing behavior shift is most visible among multi-site biomanufacturers with internal metrology capabilities seeking to reduce total cost of ownership.
Glycan Sequencing Market Segmentation
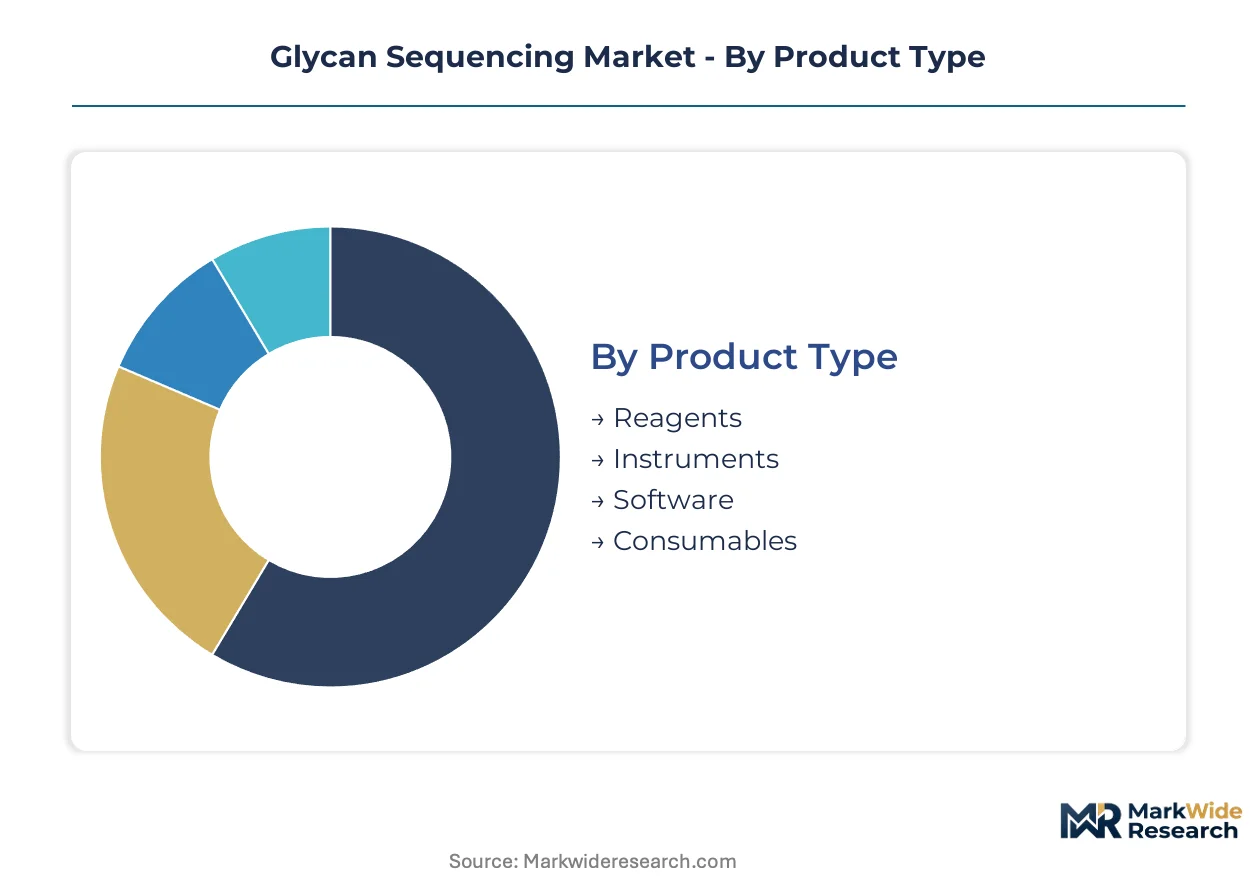
Glycan sequencing procurement splits sharply between capital-intensive instrumentation and recurring consumable spend, with technology choices locking buyers into multi-year reagent supply relationships. End-user sophistication ranges from FDA-regulated biopharmaceutical manufacturers requiring validated workflows to academic laboratories prioritizing analytical flexibility over throughput.
Product Type:
Buyer differentiation hinges on capital deployment capacity versus operational expenditure preferences, separating large biomanufacturers from resource-constrained research operations.
- Reagents:Enzymatic release kits, fluorescent labeling dyes, and derivatization chemicals constitute the highest-margin recurring revenue stream. Biopharmaceutical quality control laboratories in the United States and Germany consume these materials in fixed ratios per analytical run, creating predictable replenishment cycles tied to manufacturing batch volumes.
- Instruments:Mass spectrometry platforms, liquid chromatography systems, and capillary electrophoresis units represent seven-figure capital commitments with decade-long depreciation schedules. Waters Corporation, Thermo Fisher Scientific, and Shimadzu Corporation dominate installed base expansion through integrated hardware-software bundles.
- Software:Automated glycan structure prediction and spectral interpretation tools reduce manual analysis time from days to hours. Machine learning algorithm deployment is accelerating among contract research organizations seeking to compress turnaround times for biosimilar comparability studies.
- Consumables:Separation columns, capillaries, and sample preparation cartridges require per-run replacement. Margin profiles exceed instruments due to proprietary format lock-in and limited third-party compatibility.
Volume sits with Reagents; growth tilts toward Software.
End User:
Regulatory burden intensity separates commercial manufacturers from exploratory research operations, with FDA and EMA submission requirements dictating analytical rigor tiers.
- Pharmaceutical Companies:Therapeutic protein developers deploy glycan sequencing for batch release testing and biosimilar comparability protocols. Monoclonal antibody manufacturers in the United States, Germany, and Japan mandate glycosylation analysis for every production lot to secure regulatory approval.
- Research Institutions:National laboratories and dedicated glycobiology centers pursue fundamental carbohydrate structural biology. Funding cycles from NIH, DFG, and AMED determine instrument refresh rates rather than manufacturing throughput requirements.
- Biotechnology Firms:Emerging biologics developers balance analytical depth against capital constraints, often outsourcing glycan characterization to specialized contract research organizations during preclinical phases.
- Academic Organizations:University core facilities serve multiple principal investigators with shared instrumentation, prioritizing methodological flexibility over regulatory compliance documentation.
Revenue concentrates with Pharmaceutical Companies; expansion is steepest among Biotechnology Firms.
Technology:
Resolution requirements and sample throughput needs drive platform selection, with mass spectrometry capturing complex mixture analysis and chromatography dominating routine quality control.
- Mass Spectrometry:Orbitrap and Q-TOF configurations deliver sub-parts-per-million mass accuracy for isobaric glycan differentiation. FDA biosimilar guidance mandating high-resolution characterization is compressing replacement cycles for legacy time-of-flight instruments in United States contract manufacturing organizations.
- High-Performance Liquid Chromatography:Hydrophilic interaction chromatography with fluorescence detection remains the workhorse for released glycan profiling. European biopharmaceutical manufacturers favor HPLC-FLR for validated batch release workflows due to established pharmacopeial methods.
- Capillary Electrophoresis:Laser-induced fluorescence detection enables rapid separation with minimal sample consumption. Mid-sized developers in Germany and Japan are adopting CE-LIF to decentralize analysis from centralized core facilities.
- Microarray:Printed glycan arrays facilitate high-throughput lectin binding studies and antibody specificity screening. Academic glycobiology programs leverage this technology for exploratory biomarker discovery rather than regulated manufacturing support.
Deployment volume favors High-Performance Liquid Chromatography; capability investment is climbing fastest in Mass Spectrometry.
Application:
Regulatory submission stage determines analytical stringency, with quality control workflows requiring validated methods and discovery applications tolerating exploratory approaches.
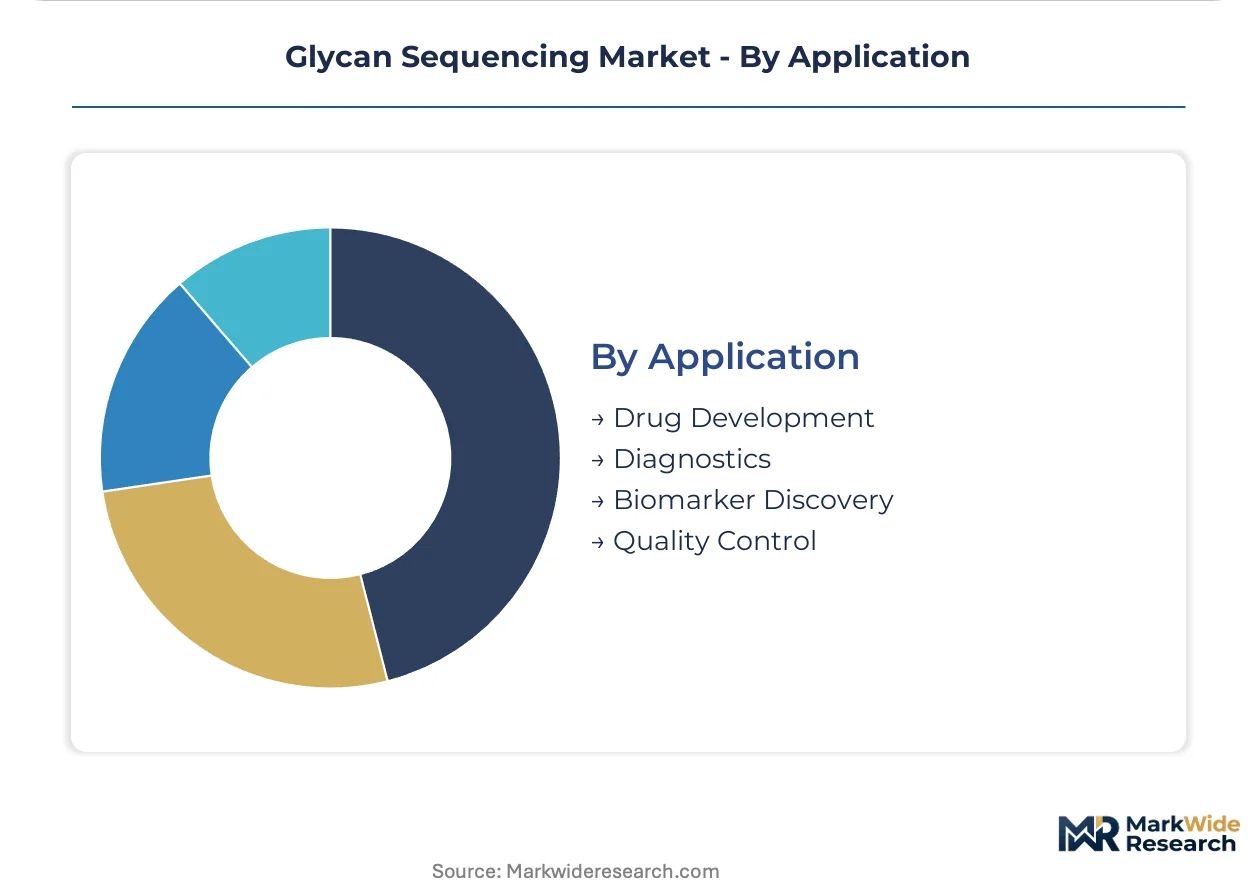
- Drug Development:Glycoprotein therapeutic candidates undergo extensive glycosylation characterization during cell line selection and clone screening. ICH Q5E comparability protocols mandate glycan analysis for manufacturing process changes across EMA-regulated submissions.
- Diagnostics:Disease-associated glycan biomarker panels require quantitative reproducibility for clinical assay deployment. Cancer screening applications in Japanese healthcare systems are driving standardized workflow adoption.
- Biomarker Discovery:Exploratory profiling of serum glycoproteins seeks disease-specific carbohydrate signatures. NIH-funded consortia in the United States are expanding glycan database construction to support translational research.
- Quality Control:Batch-to-batch consistency verification represents the largest addressable spend category. Biosimilar developers must demonstrate glycosylation pattern equivalence to originator molecules for FDA and EMA approval.
Spend concentrates in Quality Control; methodological innovation is expanding most quickly in Biomarker Discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument production concentrates in Massachusetts, Kyoto, and San Jose, while biopharmaceutical consumption clusters in Cambridge, Basel, and Osaka. Regulatory divergence between FDA, EMA, and PMDA submission requirements shapes localized procurement specifications.
United States
Monoclonal antibody manufacturers in Greater Boston and San Francisco Bay Area drive instrument replacement cycles. FDA biosimilar guidance mandates glycosylation characterization as a critical quality attribute for IND submissions. Waters Corporation anchors its UPLC-MS installed base through service contracts with Cambridge contract research organizations.
Germany
Boehringer Ingelheim and Merck KGaA biomanufacturing sites require validated HPLC-FLR workflows for batch release testing. EMA immunogenicity assessment protocols compress analytical turnaround times for Mannheim and Darmstadt quality control laboratories. Baden-Württemberg precision engineering suppliers dominate capillary electrophoresis component fabrication.
Japan
PMDA post-approval change management rules force Osaka and Tokyo biopharmaceutical developers to maintain glycan analysis redundancy. Shimadzu Corporation leverages domestic manufacturing to reduce lead times for Kyoto and Kobe instrument installations. Tsukuba academic consortia expand glycan database construction through AMED translational research funding.
India
CDSCO alignment with WHO prequalification standards accelerates instrument procurement among Hyderabad and Bangalore biosimilar clusters. Dr. Reddy's and Biocon manufacturing expansions require glycan sequencing capability for export market access. Karnataka biotech parks embed shared analytical facilities to amortize capital expenditure across emerging developers.
Switzerland
Roche and Novartis therapeutic protein production in Basel mandates high-resolution mass spectrometry for glycopeptide mapping. Swissmedic pharmacovigilance requirements extend glycan characterization into post-market surveillance protocols. Zurich precision instrument suppliers capture service revenue from German and French biomanufacturers seeking cross-border calibration standards.
Glycan Sequencing Market Competitive Landscape
Top-tier vendors anchor the high-resolution mass spectrometry segment, while mid-tier specialists compete on integrated consumable-instrument bundles. The market exhibits tiered consolidation with three to four firms controlling premium platform installations. Strategic archetypes include diversified analytical conglomerates, precision chromatography specialists, and enzymatic reagent pure-plays. Competitive moves center on software-embedded service contracts and geographic expansion through distributor networks in emerging biomanufacturing jurisdictions.
Among diversified analytical conglomerates, Waters Corporation and Thermo Fisher Scientific exemplify platform breadth spanning hardware, software, and consumable integration. Shimadzu Corporation represents the precision chromatography specialist archetype with concentrated expertise in Asian biomanufacturing workflows. These three firms occupy positions that shape procurement specifications for FDA and EMA-regulated submissions, with their installed bases creating switching costs for quality control laboratories seeking validated method transfer.
| Leading Market Players |
|---|
| Waters Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Asparia Glycomics |
| Bio-Techne Corporation |
| Agilent Technologies |
| New England Biolabs |
| Ludger Ltd. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up reagent specialists have consolidated enzymatic release kit and fluorescent dye production, tightening supply discipline and anchoring premium pricing tiers for biopharmaceutical quality control laboratories in the United States and Germany. Their concentrated ownership structures enable coordinated capacity management that resists spot-price volatility while extracting margin from instrument OEM bundling requirements.
Pricing Analysis
Margin tightening in mass spectrometry platforms reflects seven-figure capital deployment thresholds that strain mid-tier contract research organization budgets. Three-tier pricing structure across premium Orbitrap configurations, standard Q-TOF systems, and economy HPLC-FLR bundles segments buyers by validation requirements and throughput needs. Cost compression in consumables accelerates because biopharmaceutical procurement teams unbundle service contracts and negotiate region-specific maintenance agreements. Biotechnology firms exhibit highest price sensitivity due to preclinical outsourcing patterns, while FDA-regulated monoclonal antibody manufacturers accept premium tiers for 21 CFR Part 11 compliance documentation.
Supply Chain Analysis
Freight cost escalation from Japanese chemical suppliers to European and North American biomanufacturers amplifies input vulnerability for 2-AB and APTS fluorescent labeling dyes. Geographic supply concentration centers on Japan, Germany, and the United States for precision optical components, ion source assemblies, and separation column substrates. Raw material dependencies include high-purity acetonitrile, fused silica capillaries, and rare-earth magnet assemblies for mass analyzer stability. Single-source vulnerability in high-purity dye production from two Japanese chemical suppliers creates structural risk for global batch release testing schedules. Distribution runs through original equipment manufacturer direct sales forces and specialized life science distributors with field application scientist support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FDA biosimilar guidance and EMA immunogenicity protocols erect barrier-to-entry moats favoring players with validated 21 CFR Part 11 software installations and established pharmacopeial method libraries.
For Market Incumbents: Extend software-embedded service contracts into multi-year enterprise agreements with Cambridge and Basel contract manufacturing organizations to lock out competing instrument platforms. Anchor installed base expansion through exclusive fluorescent labeling reagent supply relationships that elevate switching costs for quality control laboratories facing ICH Q5E comparability protocol deadlines. Threatened by cloud-based data interpretation platforms enabling smaller laboratories to bypass capital expenditure, incumbents must deepen bioinformatics integration into hardware bundles. For New Entrants and Emerging Players: Launch via cloud-based structure elucidation services targeting Indian biosimilar developers in Hyderabad and Bangalore clusters seeking WHO prequalification without seven-figure instrument investments. White-space penetration concentrates in cell and gene therapy glycan analysis for AAV and lentiviral envelope protein characterization, where regulatory standards remain emergent and analytical flexibility commands premium positioning. Go-to-market acceleration rests on AMED and NIH translational research funding channel partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor enzymatic reagent pure-plays with captive supply relationships to Japanese dye manufacturers and established pharmacopeial reference standard libraries. Long-term viability over a multi-year window hinges on regulatory capture through FDA and EMA submission template integration. Signal to monitor: CDSCO alignment velocity with WHO prequalification standards as inflection indicator for emerging market instrument demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA biosimilar guidance compliance secures IND submission acceptance for glycoprotein therapeutics. |
| Backward Integration | In-house fluorescent dye production insulates margins from Japanese supplier concentration risk. |
| Platform Integration | Machine learning algorithm deployment compresses glycan interpretation timelines from days to hours. |
| Geographic Expansion | Hyderabad and Bangalore service facilities capture Indian biosimilar manufacturing instrumentation demand. |
| Long-term Supply Agreement | Multi-year reagent contracts with Cambridge contract research organizations stabilize recurring revenue. |
Research Methodology
Document review covered FDA biosimilar guidance documents, EMA immunogenicity assessment protocols, ICH Q5E comparability guidelines, and PMDA post-approval change management rules, complemented by interviews with biopharmaceutical quality control directors, mass spectrometry platform engineers, regulatory affairs specialists, and contract research organization procurement managers. Secondary validation drew from SEC instrument manufacturer filings, AMED translational research grant disclosures, CDSCO regulatory alignment notifications, and NIH glycobiology consortium publications. Bottom-up segmentation modeling triangulated against top-down therapeutic protein production forecasts.
Segmented outputs across product type, end user, technology platform, application, and regional regulatory cluster dimensions were generated across the analysis window. CAGRs were derived from instrument replacement cycle compression rates, biosimilar pipeline expansion trajectories, and software adoption curve penetration assumptions. Industry-specific forecast inputs incorporated monoclonal antibody manufacturing batch volume projections and WHO prequalification standard propagation timelines.
Regulatory guidance revision, supply chain disruption in Japanese dye production, and cloud-based platform substitution acceleration are the dominant revision risks to modeled assumptions. Forecasts reflect documented stakeholder input and secondary source triangulation without claiming predictive certainty. Stakeholders should weight assumptions against their own operating context and regulatory submission timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Microbiome Sequencing Market
Genomics
North America Microarray Market
Genomics
Genetic Analysis Services Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Global Long Read Sequencing Market
Genomics
Omics Lab Services Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Human Genetics Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Cancer Biomarkers Market
Genomics
Oligonucleotide Pool Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Animal Genetics Market
Genomics
DNA Diagnostics Market