
 Global Pharmacogenomics Market | 2026-2036
Global Pharmacogenomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacogenomics Market Foresight
Direct-to-consumer and hospital-based testing channels is reconfiguring how pharmacogenomic services reach patients and providers. Illumina, Inc. leverages its sequencing platform installed base to dominate clinical laboratory workflows. Thermo Fisher Scientific Inc. sustains competitive positioning through integrated reagent-instrument systems that lock in recurring consumable demand. QIAGEN anchors molecular diagnostics channels with sample-to-insight automation that reduces hands-on time for pharmacogenomic assays.
Pharmacogenomics applies genomic analysis to predict individual drug response, utilizing single-nucleotide polymorphism detection, gene expression profiling, and pharmacokinetic pathway mapping to optimize therapeutic selection and dosing. Sequencing technologies command the highest value per test while PCR kits retain volume leadership in routine cytochrome P450 screening. Cancer therapeutics represents the fastest-expanding application segment as oncologists integrate EGFR, KRAS, and BRCA pharmacogenomic data into first-line treatment protocols.
FDA companion diagnostic guidance, EMA pharmacogenomic biomarker qualification pathways, and Japan PMDA genomic medicine reimbursement policies collectively shape market access requirements for test developers. CLIA laboratory certification in the United States and ISO 15189 accreditation in Europe establish minimum analytical validity thresholds that filter out undercapitalized entrants. Stakeholders must monitor evolving payer coverage decisions for preemptive pharmacogenomic panels versus reactive single-gene testing to align portfolio investments with reimbursement trajectories.
Market Dynamics
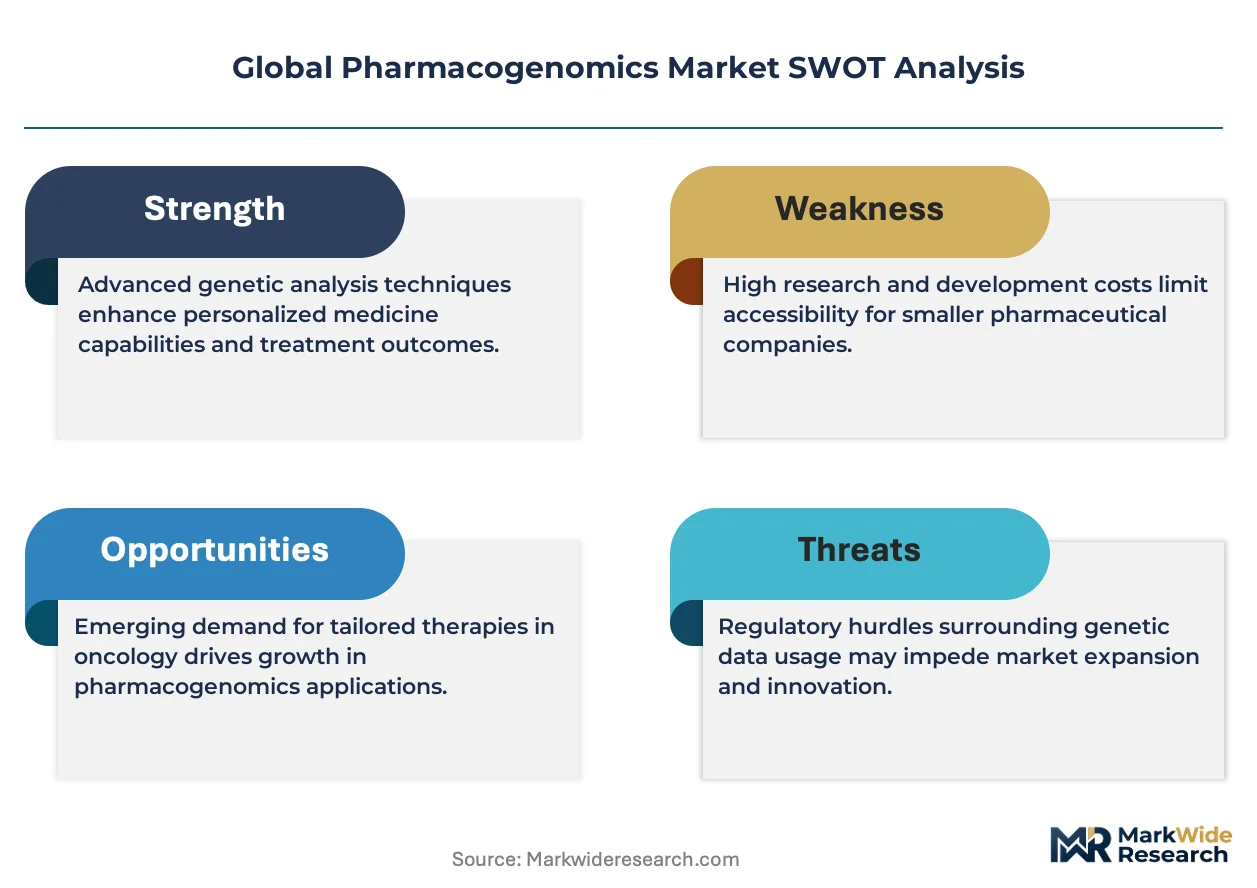
Companion diagnostic mandates from the FDA and EMA are compressing development timelines for pharmacogenomic assays, forcing test developers to integrate biomarker validation with drug approval pathways rather than pursuing sequential regulatory filings.
Growth Catalysts
- Oncology protocol expansion:Major hospital networks in the United States, Germany, and Japan are embedding EGFR, KRAS, and BRCA testing into first-line cancer treatment workflows, creating institutional demand pull.
- Reimbursement framework maturation:Japan's PMDA genomic medicine reimbursement policies and Germany's G-BA precision medicine assessments are establishing predictable payment pathways for preemptive pharmacogenomic panels.
- Sequencing platform installed base:Clinical laboratories with existing next-generation sequencing infrastructure are adding pharmacogenomic modules at marginal capital cost, accelerating test menu expansion.
Market Restraints
- Consumable cost concentration:Reagent-instrument lock-in strategies by dominant platform vendors create switching costs that limit price competition in routine cytochrome P450 screening.
- Analytical validity thresholds:CLIA laboratory certification requirements and ISO 15189 accreditation standards filter out undercapitalized entrants, consolidating market access among established diagnostic laboratories.
- Physician education gaps:Limited pharmacogenomic training in medical curricula slows clinical adoption even where reimbursement exists, particularly in primary care prescribing of psychiatric and cardiovascular medications.
Strategic Opportunities
- Pediatric pharmacogenomics:Underpenetrated testing in pediatric oncology and psychiatry in the United States represents white space as dosing algorithms for warfarin, codeine, and thiopurines gain clinical validation.
- Sample-to-insight automation:Integration of nucleic acid extraction, library preparation, and variant interpretation into single-workflow platforms reduces hands-on time and enables point-of-care deployment in community hospital settings.
- Direct-to-consumer channel maturation:Regulatory clarity from the FDA on pharmacogenomic health risk reporting is opening subscription-based models for medication management and polypharmacy optimization in aging populations.
Industry Challenges
- Bioinformatics talent scarcity:Variant classification and clinical interpretation pipelines require specialized computational biology expertise that outpaces current training program output, creating hiring bottlenecks for test developers.
- EHR integration complexity:Pharmacogenomic results require structured data formats and clinical decision support alerts that conflict with legacy electronic health record architectures in most hospital systems.
- Payer evidence requirements:Health technology assessment bodies demand prospective clinical utility data that exceeds retrospective pharmacokinetic studies, extending commercialization timelines for novel biomarker panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacogenomics Market |
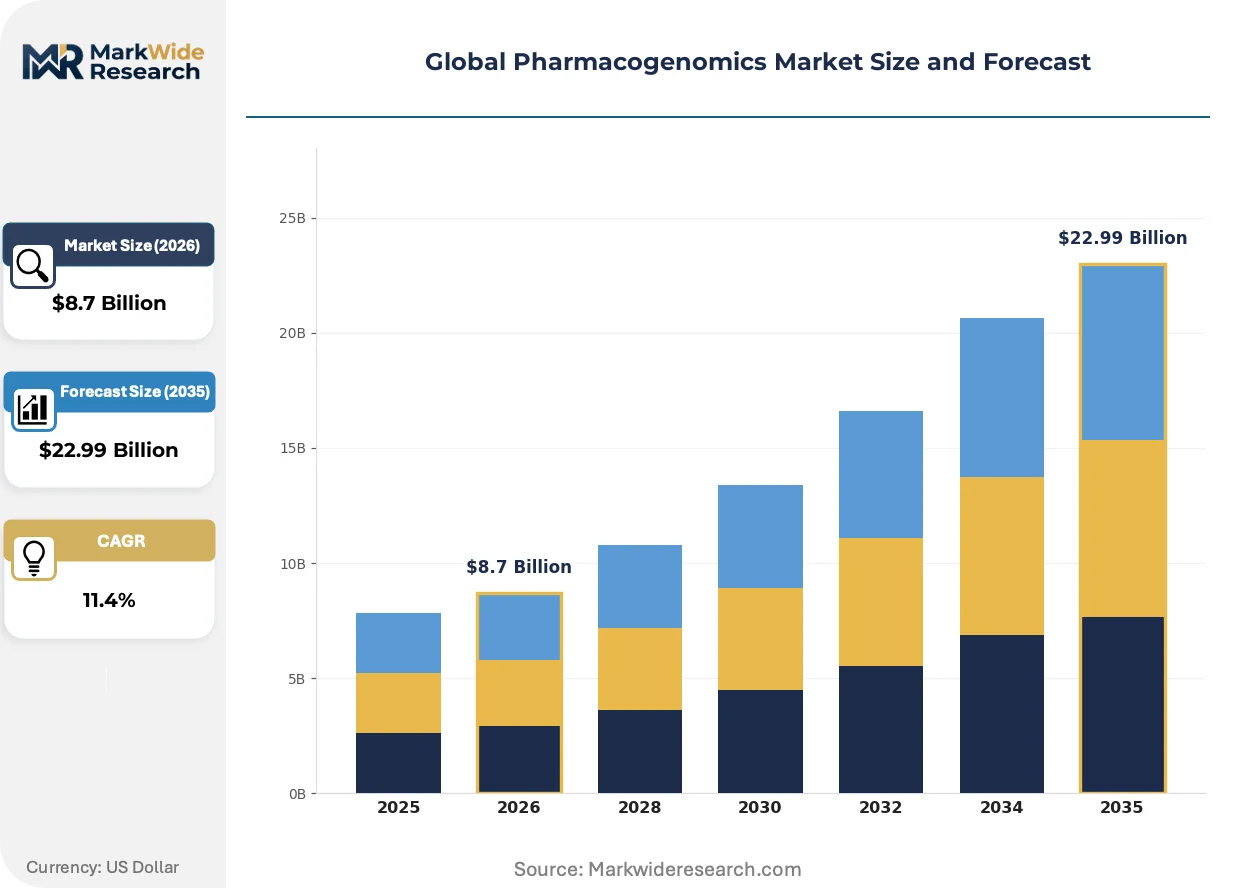
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genotyping Assays, DNA Microarrays, Sequencing Technologies, PCR Kits, Bioinformatics Software Application: Personalized Medicine, Cancer Therapeutics, Cardiovascular Risk Assessment, Drug Safety, Rare Disease Diagnosis End User: Pharmaceutical Companies, Research Institutes, Diagnostic Laboratories, Genetic Testing Centers Delivery Mode: Laboratory Services, Point-of-Care Testing, Direct-to-Consumer Testing, Hospital-Based Testing |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., QIAGEN, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Myriad Genetics, Inc., Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacogenomics Market Shifts & Advancements
Pharmacogenomic testing is migrating from centralized reference laboratories toward distributed clinical workflows, compressing turnaround times and embedding genomic data directly into prescribing decisions at the point of care.
Long-read sequencing technology is hybridizing with short-read platforms to resolve complex pharmacogene regions including CYP2D6 structural variation and HLA-B*57:01 typing for abacavir hypersensitivity. Academic medical centers in the United States and Japan are piloting hybrid workflows that combine long-read resolution with short-read throughput for preemptive panel testing. This technology convergence is compressing the cost-per-informative-variant for pharmacogenomic assays while expanding the actionable gene set beyond cytochrome P450 enzymes.
EMA pharmacogenomic biomarker qualification pathways are creating accelerated routes for test developers to establish analytical validity claims concurrent with drug marketing authorization. The industrial consequence is tighter coupling between companion diagnostic development and therapeutic clinical trials, particularly in oncology. European contract research organizations and diagnostic developers are reconfiguring service offerings to support parallel regulatory submissions, with Germany and the Netherlands emerging as qualification application hubs.
Hospital pharmacy departments are assuming procurement authority for pharmacogenomic testing services previously managed by pathology or genetics divisions, consolidating vendor relationships and demanding integrated medication management platforms. This organizational shift is displacing standalone test requisition models in favor of subscription-based clinical decision support systems that embed pharmacogenomic guidance into computerized physician order entry. The United States exhibits the most visible procurement transformation, with integrated delivery networks negotiating enterprise contracts spanning inpatient, outpatient, and retail pharmacy settings.
Global Pharmacogenomics Market Segmentation
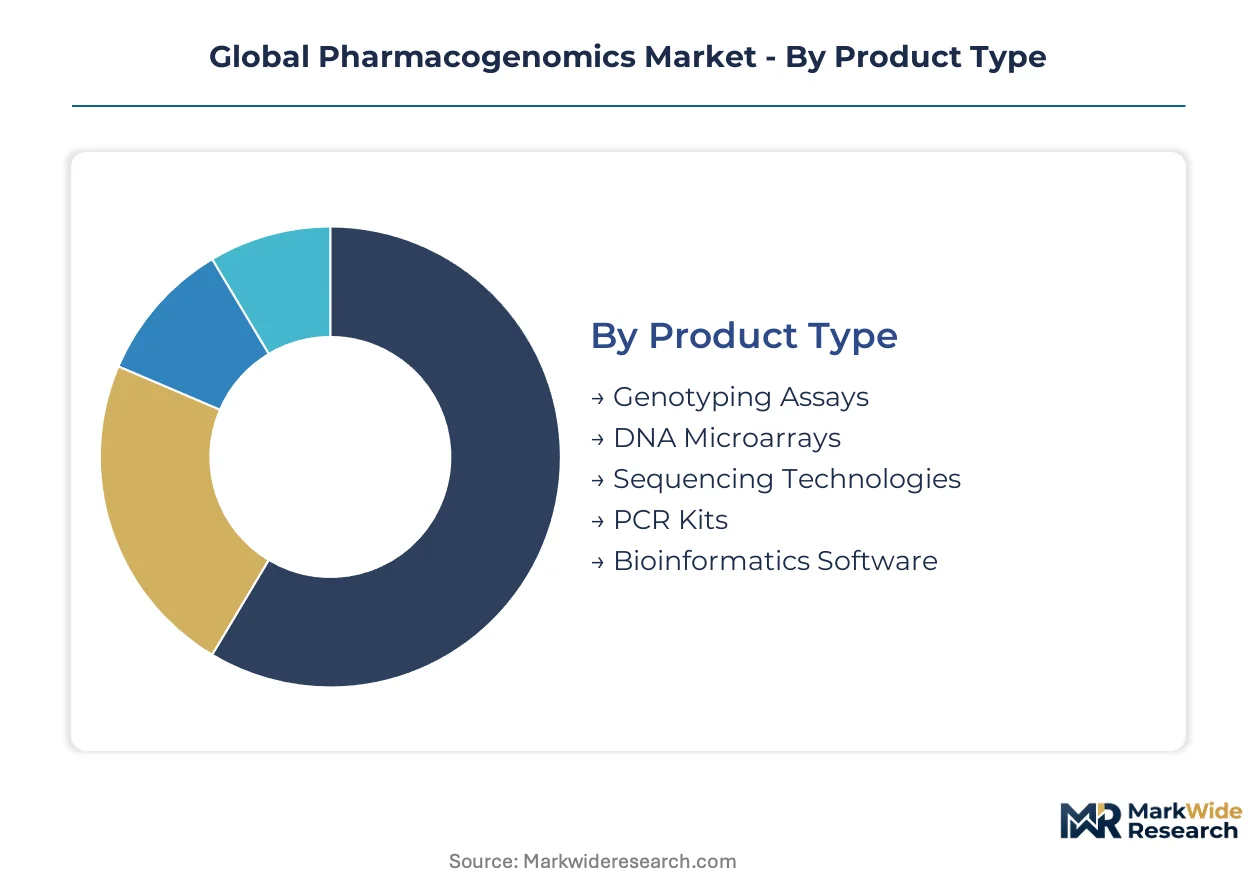
Segmentation in pharmacogenomics reveals how technological maturity, clinical application depth, and service delivery models create distinct competitive arenas. Each category exposes where capital concentrates, where regulatory friction operates, and where new entrants can establish footholds.
Product Type:
Mature platforms dominate routine clinical workflows while emerging technologies capture research and complex variant detection demand.
- Genotyping Assays:Single-nucleotide polymorphism detection platforms process CYP2C19, CYP2D6, and VKORC1 variants for antiplatelet, psychiatric, and anticoagulant dosing protocols. Demand concentrates in United States hospital laboratories where preemptive panel reimbursement has stabilized, though reagent costs limit expansion into resource-constrained settings.
- Sequencing Technologies:Next-generation sequencing platforms deliver comprehensive pharmacogene coverage with analytical validity exceeding CLIA thresholds for clinical diagnostic use. Germany's university medical centers and Japan's cancer genomic medicine hubs are expanding installed capacity for oncology companion diagnostic workflows, compressing turnaround times for EGFR and KRAS variant reporting.
- DNA Microarrays:Fixed-content panels offer cost-efficient screening for established pharmacogenomic variants in large population cohorts.
- PCR Kits:Real-time amplification systems retain dominance in cytochrome P450 screening for cardiovascular and psychiatric medication management.
- Bioinformatics Software:Variant interpretation pipelines integrate clinical decision support with electronic health record systems for point-of-care deployment.
PCR kits retain volume leadership; sequencing technologies hold the steepest expansion curve.
Application:
Clinical utility validation separates commercially viable segments from research-stage propositions across therapeutic areas.
- Cancer Therapeutics:Companion diagnostic mandates from FDA and EMA require EGFR, KRAS, BRCA, and MSI biomarker testing prior to targeted therapy initiation. Major hospital networks in the United States and Japan have embedded these assays into first-line treatment protocols, creating institutional demand pull that sustains premium pricing for validated tests.
- Personalized Medicine:Preemptive pharmacogenomic panel testing guides medication selection and dosing across multiple therapeutic categories before adverse events occur. Germany's G-BA precision medicine assessments and Japan's PMDA genomic medicine reimbursement policies are establishing predictable payment pathways that accelerate clinical adoption beyond oncology.
- Cardiovascular Risk Assessment:CYP2C19 and SLCO1B1 testing informs statin and antiplatelet prescribing decisions in coronary artery disease management.
- Drug Safety:HLA-B*57:01 screening for abacavir hypersensitivity and TPMT testing for thiopurine toxicity prevention reduce hospitalization costs.
- Rare Disease Diagnosis:Pharmacogenomic data complements exome sequencing to explain variable drug responses in Mendelian disorders.
Personalized medicine commands the highest reimbursement rates; cancer therapeutics is gaining share fastest.
End User:
Procurement authority shifts are reconfiguring vendor relationships across institutional customer types.
- Diagnostic Laboratories:CLIA-certified reference laboratories and hospital-based molecular diagnostics units process the majority of pharmacogenomic test volume in the United States. ISO 15189-accredited facilities in Germany and Netherlands serve as European qualification application hubs for EMA biomarker pathways.
- Pharmaceutical Companies:Drug developers integrate pharmacogenomic biomarker strategies into clinical trial designs to satisfy FDA and EMA companion diagnostic requirements. Parallel regulatory submissions for therapeutic and diagnostic approvals compress development timelines and demand integrated service partnerships.
- Research Institutes:Academic medical centers pilot hybrid long-read and short-read sequencing workflows for complex pharmacogene resolution.
- Genetic Testing Centers:Specialized facilities focus on direct-to-consumer and physician-ordered pharmacogenomic screening services.
Diagnostic laboratories retain volume leadership; pharmaceutical companies hold the steepest expansion curve.
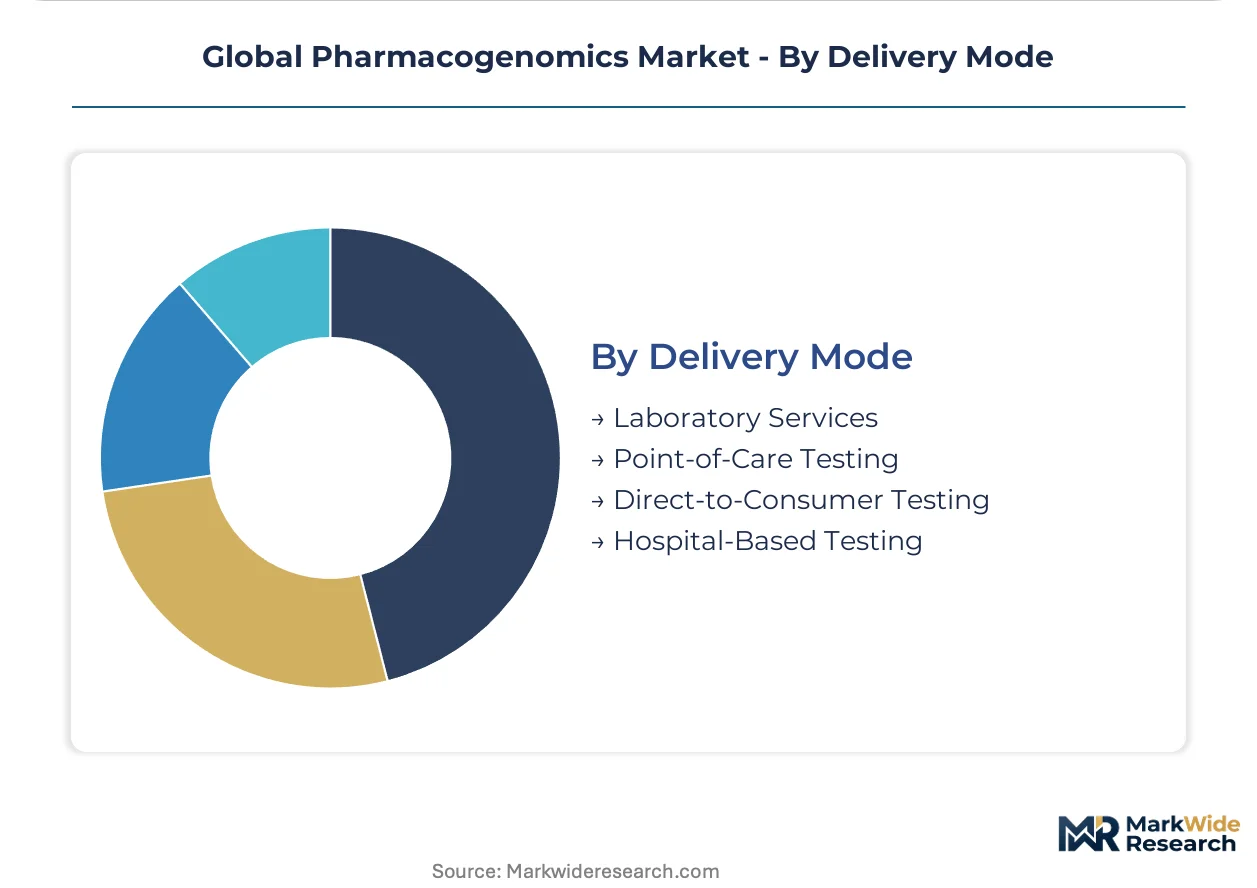
Delivery Mode:
Channel structure determines pricing power, regulatory exposure, and patient access economics.
- Laboratory Services:Centralized reference laboratories achieve economies of scale in high-complexity pharmacogenomic testing with comprehensive bioinformatics interpretation. United States integrated delivery networks negotiate enterprise contracts spanning inpatient, outpatient, and retail pharmacy settings, consolidating vendor relationships.
- Hospital-Based Testing:Point-of-care deployment in community hospital settings compresses turnaround times for urgent therapeutic decisions. Hospital pharmacy departments in the United States are assuming procurement authority previously held by pathology divisions, demanding subscription-based clinical decision support systems.
- Point-of-Care Testing:Sample-to-insight automation platforms reduce hands-on time for nucleic acid extraction and variant interpretation.
- Direct-to-Consumer Testing:Regulatory clarity from FDA on pharmacogenomic health risk reporting enables subscription-based medication management models.
Laboratory services retain volume leadership; hospital-based testing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacogenomics test pricing in the United States commands premiums three to four times higher than equivalent assays in India, reflecting reimbursement infrastructure gaps rather than technical differentiation.
United States
Integrated delivery networks in Texas and California are consolidating pharmacogenomic procurement under pharmacy departments, demanding enterprise contracts that span inpatient, outpatient, and retail settings. FDA companion diagnostic guidance and CLIA laboratory certification requirements filter out undercapitalized entrants, concentrating market access among established diagnostic laboratories. The Greater Boston cluster anchors hybrid long-read and short-read sequencing pilot programs for complex pharmacogene resolution.
Germany
University medical centers in Bavaria and Baden-Württemberg are expanding next-generation sequencing capacity for oncology companion diagnostic workflows. G-BA precision medicine assessments establish predictable payment pathways for preemptive pharmacogenomic panels beyond cancer therapeutics. The Rhine-Ruhr metropolitan region hosts contract research organizations reconfigured to support parallel EMA biomarker qualification and therapeutic marketing authorization submissions.
Japan
Cancer genomic medicine hubs in Tokyo and Osaka are embedding EGFR, KRAS, and BRCA testing into first-line treatment protocols, creating institutional demand pull for validated assays. PMDA genomic medicine reimbursement policies accelerate clinical adoption of pharmacogenomic panels in oncology and psychiatry. The Kansai region concentrates bioinformatics talent pipelines for variant classification and clinical interpretation.
United Kingdom
NHS Genomic Medicine Service alliances in London and the Southeast are standardizing pharmacogenomic test menus across regional laboratory networks. NICE technology appraisals for companion diagnostics shape procurement criteria for EGFR and ALK testing in non-small cell lung cancer. The Cambridge-Oxford-London golden triangle anchors academic-industry partnerships for preemptive panel validation in cardiovascular and psychiatric prescribing.
India
Diagnostic laboratory chains in Maharashtra and Karnataka are introducing cytochrome P450 screening for antiplatelet and psychiatric medication management at price points accessible to tier-two city populations. CDSCO regulatory pathways for in vitro diagnostics are evolving to accommodate pharmacogenomic assay registrations, though reimbursement infrastructure remains fragmented. The Hyderabad-Bengaluru corridor concentrates contract research activity supporting global pharmaceutical companion diagnostic development programs.
Global Pharmacogenomics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagents and consumables. The market structure concentrates around sequencing platform vendors with installed base advantages and reference laboratories with CLIA certification barriers. Three archetypes dominate: instrument-reagent system vendors, sample-to-insight automation providers, and bioinformatics interpretation platforms. Competitive moves center on reagent-instrument lock-in strategies and subscription-based clinical decision support licensing.
Within the instrument-reagent tier, Illumina, Inc. and Thermo Fisher Scientific Inc. exemplify platform integrators leveraging installed base economics to capture recurring consumable demand. QIAGEN occupies a position among sample-to-insight automation specialists, reducing hands-on time for nucleic acid extraction through variant interpretation workflows. These three entities anchor the competitive structure, representing distinct strategic postures toward clinical laboratory consolidation and point-of-care deployment.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Myriad Genetics, Inc. |
| Agilent Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
The San Diego-Boston sequencing technology corridor anchors global reagent manufacturing capacity, concentrating pricing power among platform vendors who bundle instruments with proprietary consumables. This geographic concentration of next-generation sequencing infrastructure creates downstream cost structures that hospital laboratories and diagnostic networks must absorb or circumvent through alternative procurement strategies.
Pricing Analysis
Customization-premium spreads in pharmacogenomics separate configured-to-order companion diagnostic assays from standard cytochrome P450 screening panels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA companion diagnostic certification status and analytical validity thresholds. Pricing pressure stems from hospital pharmacy departments consolidating procurement under enterprise contracts that demand volume discounts. Academic medical centers exhibit highest price sensitivity due to constrained research budgets, while integrated delivery networks leverage scale for preferential tier placement.
Supply Chain Analysis
Supplier-financing facilities from Illumina and Thermo Fisher Scientific extend payment terms for clinical laboratories acquiring sequencing platforms, embedding long-term consumable commitments into capital equipment transactions. Manufacturing concentrates in the United States, Germany, and Singapore for precision optics and microfluidic components. Reagent production draws from specialty chemical suppliers in Switzerland and Japan for polymerases and fluorescent dyes. Single-source vulnerability persists for semiconductor-based detection chips fabricated in Taiwan. Distribution runs through CLIA-certified reference laboratories and hospital-based molecular diagnostics units with direct platform vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from long-read sequencing platforms that resolve complex pharmacogene structural variation currently invisible to short-read workflows. Defense requires pre-emptive technology migration and lock-in reinforcement.
For Market Incumbents: Pre-empt long-read substitution by hybridizing existing short-read installed bases with complementary nanopore or single-molecule platforms for CYP2D6 copy number resolution. Secure backward integration into reagent manufacturing to defend margin position against specialty chemical cost volatility. Reinforce CLIA laboratory certification barriers through accelerated ISO 15189 accreditation in European expansion markets.
For New Entrants and Emerging Players: Build out pediatric pharmacogenomics service lines in United States academic medical centers where preemptive panel testing for warfarin and thiopurine dosing remains underpenetrated. Target direct-to-consumer subscription models for polypharmacy optimization in aging populations as FDA regulatory clarity on health risk reporting stabilizes. Deploy sample-to-insight automation platforms that reduce hands-on time for community hospital laboratories lacking dedicated molecular diagnostics staff.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because sequencing instrument-reagent lock-in economics create durable recurring revenue streams with high switching costs. Acquisition targets should display CLIA certification infrastructure and established hospital pharmacy procurement relationships. The signal to watch is EMA biomarker qualification pathway throughput acceleration as European contract research organizations reconfigure for parallel therapeutic-diagnostic submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Sequencing Platform Deployment | Combines short-read throughput with long-read resolution for complex pharmacogene regions. |
| CLIA Laboratory Certification Expansion | Filters undercapitalized entrants and consolidates market access among established diagnostic networks. |
| Sample-to-Insight Automation Development | Reduces hands-on time for nucleic acid extraction through variant interpretation in point-of-care settings. |
| Direct-to-Consumer Channel Maturation | Enables subscription-based medication management models as FDA regulatory clarity stabilizes. |
| EMA Biomarker Qualification Parallel Submission | Compresses development timelines by integrating diagnostic validation with therapeutic approval pathways. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA companion diagnostic guidance documents, EMA qualification pathway submissions, and hospital procurement database extracts. Conversations with molecular diagnostics laboratory directors, hospital pharmacy procurement managers, regulatory affairs specialists at sequencing platform vendors, and payer access strategists at integrated delivery networks informed demand-side dynamics. Secondary validation drew from ClinicalTrials.gov pharmacogenomic biomarker listings, CMS Medicare reimbursement data, and GPO contract archives. Bottom-up test volume modeling triangulated against top-down market sizing from platform installed base economics.
Forecast inputs span product type segmentation across genotyping assays, sequencing technologies, and PCR kits; application dimensions covering cancer therapeutics, personalized medicine, and cardiovascular risk assessment; and end-user categories including diagnostic laboratories, pharmaceutical companies, and research institutes. CAGRs were derived from elasticity modeling against reimbursement trajectory scenarios and technology substitution curves. Analysis window projections incorporate EMA biomarker qualification throughput assumptions and Japan PMDA genomic medicine reimbursement expansion patterns.
Stress conditions across CLIA certification backlog durations, semiconductor detection chip supply continuity, and companion diagnostic mandate enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway harmonization and hospital procurement centralization velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Targeted DNA RNA Sequencing Market
Genomics
North America Epigenetics Market
Genomics
China Genetic Testing Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Immunogenetics Market
Genomics
Next Generation Sequencing Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Microbiome Sequencing Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Genotyping Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
North America Microarray Market
Genomics
Restriction Endonucleases Market
Genomics
Omics Lab Services Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Pharmacogenomic (Pgx) Testing Market