
 Nanopore Sequencing Market | 2026-2036
Nanopore Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Nanopore Sequencing Market Insights
Synthetic polymer membranes is rebalancing cost structures in portable sequencing devices, replacing traditional silicon-based substrates that demanded expensive cleanroom fabrication. Oxford Nanopore Technologies leverages its vertically integrated membrane production to sustain pricing advantages in field-deployable instruments. Illumina competes through its established installed base, while Thermo Fisher Scientific anchors its position with integrated sample-to-answer workflows that span extraction through analysis.
Nanopore sequencing detects individual nucleic acid strands by measuring ionic current disruptions as molecules traverse nanoscale protein or synthetic pores, achieving read lengths exceeding two million base pairs in optimized conditions. The technology serves genomic assembly, epigenetic modification detection, and real-time pathogen surveillance where short-read methods fail. Reagents capture recurring revenue as consumable pull-through intensifies across high-throughput installations. Biotechnology companies represent the fastest-growing end user category as contract research organizations adopt electrical sequencing for client deliverables. Single-molecule sequencing leads technology adoption, though real-time sequencing gains traction in point-of-care infectious disease testing.
FDA oversight of nanopore-based diagnostic devices shapes product development timelines and clinical validation requirements for US market entrants. The EMA's In Vitro Diagnostic Regulation and CE marking requirements govern European commercialization, while China's NMPA accelerates review pathways for innovative sequencing platforms under its breakthrough device program. Stakeholders must monitor evolving reimbursement codes for long-read diagnostic applications and anticipate how dual-use export controls on biological data infrastructure affect instrument deployment across sensitive research domains.
Market Dynamics
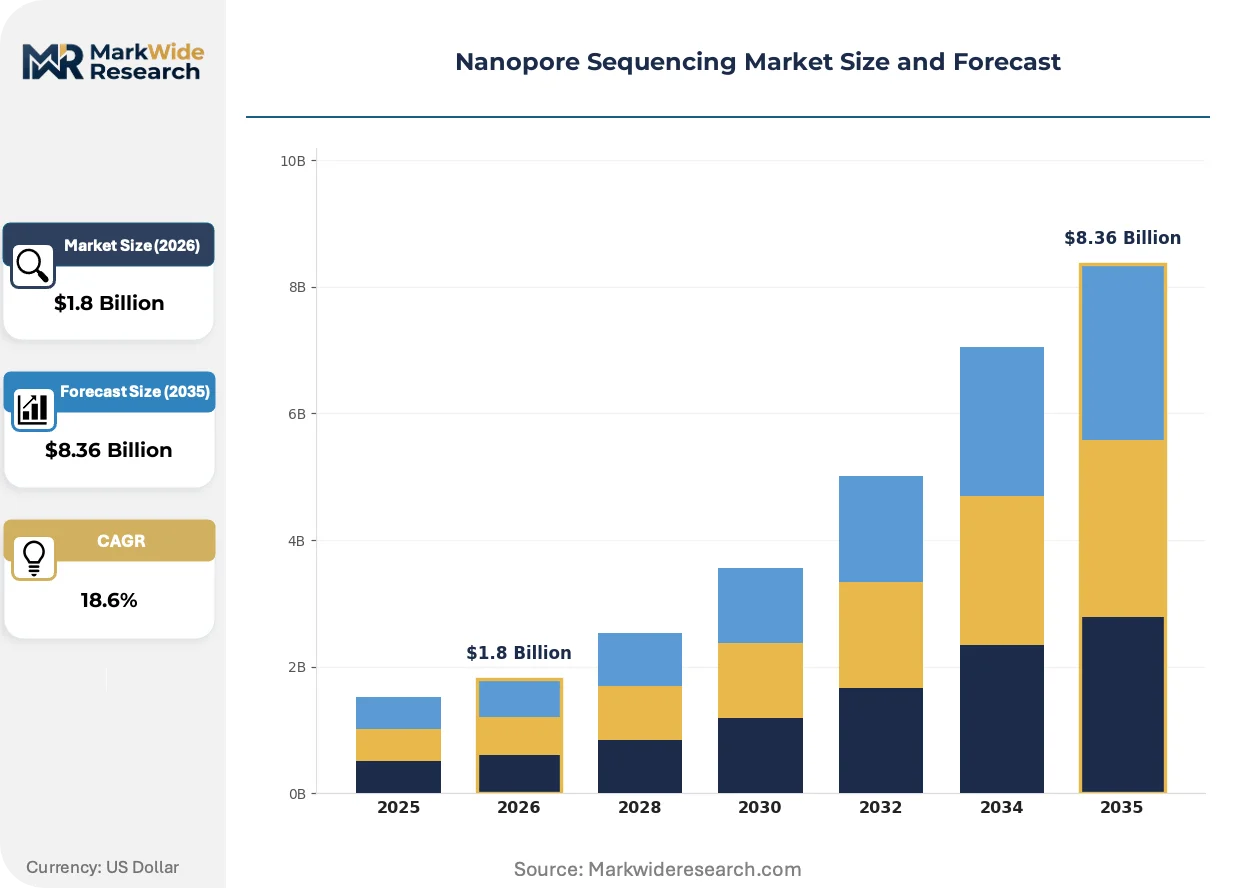
The transition from centralized sequencing core facilities to distributed point-of-need testing is compressing instrument footprints while elevating consumable economics as the dominant revenue architecture.
Growth Catalysts
- NIH genomic research funding:Sustained federal investment in long-read sequencing infrastructure accelerates adoption across academic medical centers and national laboratories in the United States.
- Real-time pathogen surveillance:Field-deployable nanopore platforms enable same-day genomic epidemiology for infectious disease outbreaks where laboratory turnaround times prove inadequate.
- Class II medical device pathway:FDA's streamlined premarket notification process reduces regulatory barriers for diagnostic applications of electrical sequencing technologies.
Market Restraints
- Membrane fabrication cost volatility:Synthetic polymer substrate production requires specialized cleanroom capacity concentrated among limited contract manufacturers.
- Base-calling accuracy limitations:Homopolymer regions and methylation-sensitive sites generate systematic error modes that short-read platforms circumvent through sequencing-by-synthesis chemistry.
- Reimbursement code gaps:CPT and HCPCS coding structures lack specific descriptors for long-read diagnostic procedures, creating payment uncertainty for clinical laboratories.
Strategic Opportunities
- Rural and resource-limited settings:Battery-operated portable sequencers address infrastructure gaps in sub-Saharan African and Southeast Asian healthcare systems where cold-chain logistics fail.
- Epigenetic diagnostic applications:Direct detection of DNA methylation and nucleosome positioning without bisulfite conversion opens oncology and prenatal testing categories.
- Integrated sample-to-answer workflows:Automated extraction-to-sequencing cartridges reduce operator skill requirements and contamination risk in point-of-care environments.
Industry Challenges
- Bioinformatics pipeline complexity:Long-read assembly algorithms and structural variant calling require computational infrastructure and trained analysts scarce in clinical settings.
- Proficiency testing standardization:External quality assessment programs for nanopore-based assays remain underdeveloped compared to established NGS frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanopore Sequencing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories End User: Research Laboratories, Hospitals, Academic Institutions, Biotechnology Companies Technology: Single-Molecule Sequencing, Real-Time Sequencing, Optical Sequencing, Electrical Sequencing Application: Genomic Research, Disease Diagnosis, Personalized Medicine, Environmental Monitoring |
| Companies Covered | Oxford Nanopore Technologies, Illumina, Thermo Fisher Scientific, Pacific Biosciences, F. Hoffmann-La Roche Ltd, QIAGEN, BGI Genomics, Agilent Technologies, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanopore Sequencing Market Trends and Innovations
Electrical detection architectures are absorbing functionality previously requiring optical instrumentation, collapsing cost structures while expanding deployment contexts beyond traditional laboratory environments.
Synthetic nanopore membranes are absorbing the substrate role from biological protein pores, enabling harsher chemical conditions and extended operational lifespans in field instruments. Materials science divisions at sequencing technology developers are scaling manufacturing of these polymeric alternatives to reduce lot-to-lot variability. The shift is absorbing cost premiums associated with recombinant protein production while preserving single-molecule sensitivity.
EMA's In Vitro Diagnostic Regulation is compressing commercialization timelines for European market entrants through stricter clinical evidence requirements and notified body capacity constraints. Manufacturers are responding by front-loading performance studies and establishing quality management systems aligned with MDR Annex IX procedures. The regulatory burden is absorbing smaller developers into partnership structures with established diagnostic firms possessing notified body relationships.
Service unbundling is fragmenting the traditional instrument-reagent-support bundle as high-throughput users negotiate direct consumable sourcing and self-maintain hardware. Large reference laboratories are absorbing field service functions internally, pressuring manufacturer service margins while accelerating response times. This procurement evolution is most pronounced in the United States where scale concentration among national laboratory networks creates negotiating leverage unavailable in fragmented European markets.
Nanopore Sequencing Market Segmentation
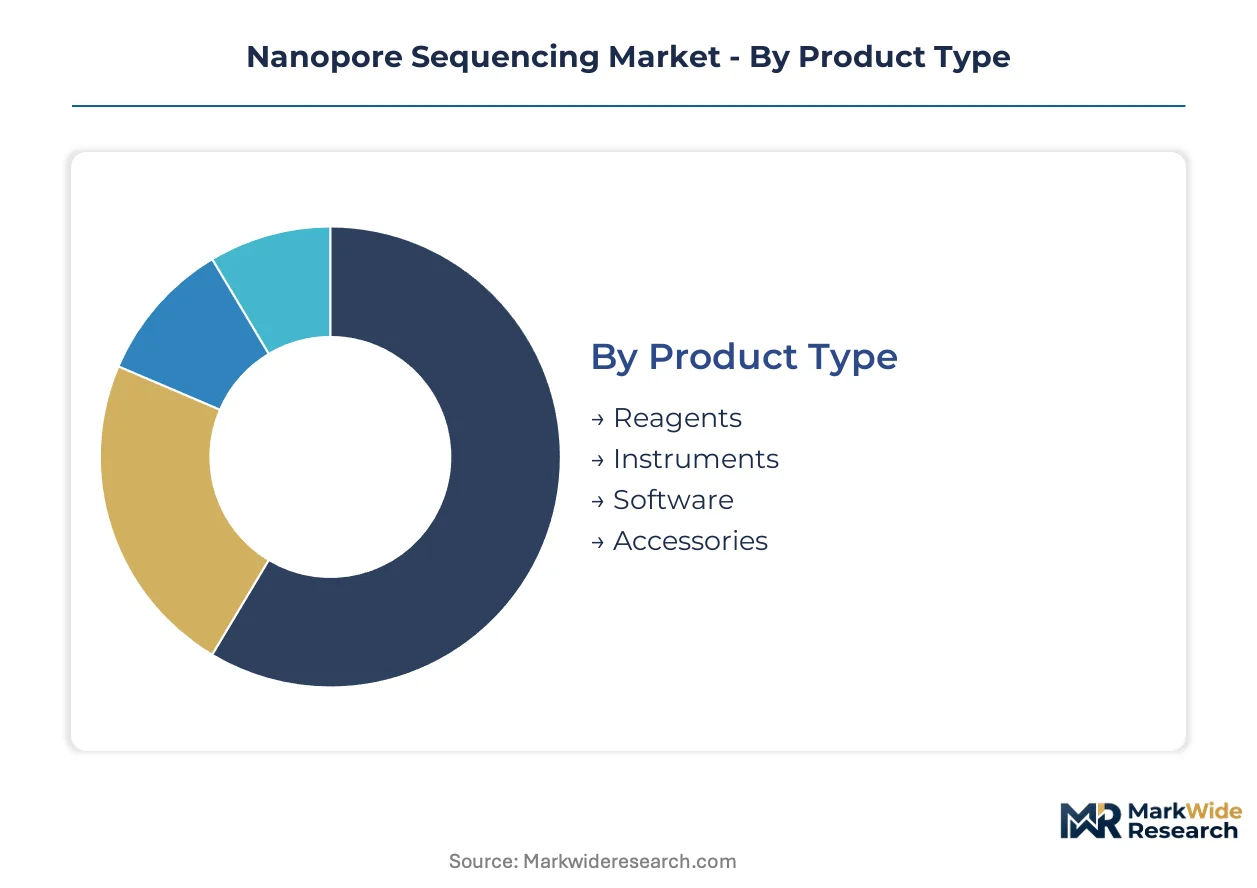
Nanopore sequencing markets fragment across multiple dimensions that determine procurement patterns and margin structures. Product architecture, end-user workflows, detection physics, and clinical versus research applications each create distinct competitive arenas with specialized vendor requirements.
Product Type:
Standalone instruments dominate capital expenditure budgets while embedded consumables drive recurring revenue in high-throughput installations.
- Reagents:Flow cell chemistry and library preparation kits constitute the consumable backbone of nanopore economics. Clinical diagnostic laboratories in the United States generate concentrated pull-through as FDA-cleared assays expand. These recurring purchases capture 60-70% of lifetime customer value per installed instrument.
- Instruments:Portable and benchtop sequencers span field-deployable MinION devices through high-throughput PromethION platforms. Academic medical centers deploy these systems for real-time pathogen surveillance where laboratory infrastructure remains fixed. Capital cycles extend 5-7 years with upgrade pathways preserving vendor relationships.
- Software:Base-calling algorithms and structural variant analysis pipelines process raw electrical signals into interpretable genomic data. Cloud-based deployments reduce computational infrastructure requirements for smaller research groups.
- Accessories:Flow cell adapters, temperature control modules, and sample preparation workstations complete operational workflows. These components address contamination control and throughput optimization in point-of-care environments.
Reagents lead volumes today; instruments are gaining share fastest in resource-limited settings.
End User:
Customer sophistication and purchasing authority create tiered service requirements from self-directed research groups through regulated clinical operations.
- Research Laboratories:Core sequencing facilities at institutions like the NIH-funded Broad Institute and Sanger Centre deploy multi-platform workflows. These users prioritize read length and real-time capabilities over regulatory certification.
- Hospitals:Clinical microbiology laboratories adopt nanopore systems for rapid infectious disease identification where turnaround time affects patient outcomes. Infection control departments in Boston and London academic medical centers drive validation studies for diagnostic claims.
- Academic Institutions:Graduate training programs and principal investigator laboratories represent price-sensitive entry-level demand. These users favor portable instruments with minimal infrastructure requirements.
- Biotechnology Companies:Contract research organizations and platform developers constitute expanding commercial demand. Genomic medicine startups in Cambridge, Massachusetts and South San Francisco integrate electrical sequencing into therapeutic discovery pipelines.
Research laboratories lead volumes today; biotechnology companies are expanding most quickly.
Technology:
Detection physics determines instrument architecture, with electrical methods displacing optical systems in distributed deployment scenarios.
- Single-Molecule Sequencing:Individual DNA strand analysis eliminates amplification bias and enables epigenetic modification detection. Oncology applications in European reference laboratories leverage direct methylation sensing without chemical conversion.
- Real-Time Sequencing:Data generation during molecular translocation supports same-day outbreak response. Public health agencies in the United Kingdom and Australia deploy these capabilities for genomic epidemiology.
- Optical Sequencing:Fluorescence-based detection retains established validation in certain clinical applications. These systems persist where regulatory precedent favors optical instrumentation.
- Electrical Sequencing:Ionic current measurement enables miniaturization and reduced power consumption. Field programs in sub-Saharan Africa and Southeast Asia rely on battery-operated electrical platforms.
Single-molecule sequencing leads volumes today; real-time sequencing is climbing the fastest.
Application:
Use case maturity spans established research workflows through emerging clinical categories with distinct reimbursement and regulatory profiles.
- Genomic Research:De novo assembly and structural variation discovery represent established demand from genome centers. The Vertebrate Genomes Project and similar initiatives in Germany and Japan generate sustained instrument utilization.
- Disease Diagnosis:Infectious disease identification and antimicrobial resistance profiling drive clinical adoption. Hospital laboratories in Singapore and California validate nanopore assays against culture-based methods.
- Personalized Medicine:Pharmacogenomic testing and rare disease diagnosis create emerging clinical categories. These applications await specific CPT code development for sustainable reimbursement.
- Environmental Monitoring:Biodiversity assessment and pathogen surveillance in water and agricultural systems expand deployment contexts. Regulatory agencies in Canada and the Netherlands pilot these approaches for food safety inspection.
Genomic research leads volumes today; disease diagnosis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cambridge's genomic technology cluster anchors nanopore sequencing deployment through Oxford Nanopore Technologies' headquarters and surrounding research infrastructure. The United States, United Kingdom, Germany, China, and Japan concentrate instrument installations and regulatory validation programs.
United States
NIH-funded genome centers at the Broad Institute and academic medical centers in Boston drive high-throughput adoption. The FDA's Class II medical device pathway accelerates diagnostic commercialization timelines. California's Bay Area biotech corridor integrates electrical sequencing into therapeutic discovery pipelines.
United Kingdom
Public Health England deploys real-time platforms for infectious disease surveillance during outbreak response. The Medicines and Healthcare products Regulatory Agency coordinates with the FDA on harmonized validation standards. Oxford's technology cluster sustains membrane manufacturing and algorithm development operations.
Germany
Reference laboratories in Berlin and Heidelberg validate long-read assays against established NGS workflows. The EMA's In Vitro Diagnostic Regulation shapes clinical evidence requirements for European market entry. Bavaria's precision medicine initiatives incorporate epigenetic detection capabilities.
China
The NMPA's breakthrough device program accelerates review pathways for innovative sequencing platforms. BGI Genomics and research hospitals in Beijing and Shenzhen scale domestic production and clinical validation. Yangtze River Delta biotech parks attract electrical sequencing infrastructure investments.
Japan
PMDA consultations guide diagnostic device development for oncology and prenatal testing applications. Tokyo and Osaka medical centers pilot methylation detection without bisulfite conversion. METI funding supports next-generation membrane materials research at national laboratories.
Nanopore Sequencing Market Competitive Landscape
Global majors compete with regional champions across technology licensing and installed base expansion. The market structure concentrates around vertically integrated membrane producers, diversified life science conglomerates, and specialized long-read platform developers. Three archetypes dominate: captive substrate manufacturers, multi-platform instrument vendors, and sequencing service integrators. Capacity expansion in polymer membrane fabrication and strategic partnerships for sample-to-answer workflows represent the primary competitive moves.
Within the vertically integrated tier, Oxford Nanopore Technologies exemplifies captive membrane production advantages. Among diversified life science conglomerates, Thermo Fisher Scientific and Illumina occupy positions spanning reagent supply through analytical instrumentation. These entities represent contrasting strategic approaches to electrical sequencing market development.
| Leading Market Players |
|---|
| Oxford Nanopore Technologies |
| Illumina |
| Thermo Fisher Scientific |
| Pacific Biosciences |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| BGI Genomics |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
Synthetic polymer membrane fabrication costs cascade through nanopore sequencing economics, with specialized cleanroom capacity in the United Kingdom and Germany absorbing margin pressure before pricing tiers crystallize for clinical diagnostic laboratories versus academic research buyers.
Pricing Analysis
Input-cost pass-through from recombinant protein production and polymer substrate manufacturing shapes instrument and consumable pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from research-grade instruments and portable field-deployable devices. Pricing pressure stems from service unbundling as large reference laboratories internalize field service functions and negotiate direct consumable sourcing. Academic institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while clinical diagnostic laboratories prioritize regulatory certification over unit cost.
Supply Chain Analysis
Workforce availability constraints in Cambridge, Massachusetts and South San Francisco biotech corridors limit membrane engineering talent pools for synthetic substrate development. Manufacturing concentrates in the United Kingdom, China, and Japan, with Oxford anchoring captive membrane production and Shenzhen scaling domestic instrument assembly. Raw material dependencies include photoresist polymers, recombinant pore proteins, and precision-machined flow cell housings. Single-source vulnerability around specialized cleanroom contractors for polymer membrane fabrication creates bottleneck risk. Distribution runs through direct sales teams for high-throughput installations and channel partners for portable device penetration in resource-limited settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in nanopore sequencing rests on synthetic membrane cost-down curves displacing biological protein substrates, while premium-tier diagnostic platforms capture pricing power through FDA Class II clearance pathways.
For Market Incumbents: Cement membrane manufacturing advantages through backward integration into polymer substrate production, insulating against cleanroom contractor concentration. Fortify installed base retention by embedding base-calling algorithms into cloud subscription tiers that raise switching costs for high-throughput users. Counter Illumina's optical sequencing installed base by accelerating integrated sample-to-answer workflow validation for infectious disease diagnostics. For New Entrants and Emerging Players: Launch via battery-operated portable sequencers targeting sub-Saharan African and Southeast Asian healthcare systems where cold-chain logistics failures create infrastructure gaps. Penetrate epigenetic diagnostic applications in European oncology laboratories where direct methylation detection without bisulfite conversion commands premium positioning. Partner with contract research organizations to embed electrical sequencing into client deliverables without bearing full instrument commercialization burden. For Investors and Strategic Acquirers: Consolidation pressure builds where bioinformatics pipeline complexity exceeds clinical laboratory computational infrastructure capacity, favoring acquisition of algorithm developers with FDA-validated structural variant calling. Long-term viability favors vertically integrated membrane producers over pure-play software vendors. Watch NMPA breakthrough device program approvals in China as inflection signal for geographic demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Membrane Manufacturing Scale-Up | Oxford Nanopore Technologies' captive production reduces lot-to-lot variability for field-deployable instruments. |
| Integrated Sample-to-Answer Workflow Development | Automated extraction-to-sequencing cartridges reduce operator skill requirements in point-of-care environments. |
| CE Marking Pathway Acceleration | EMA's In Vitro Diagnostic Regulation compliance front-loads performance studies for European commercialization timelines. |
| Hospital System Partnership | Academic medical centers in Boston and London validate diagnostic claims against culture-based infectious disease methods. |
| Reimbursement Strategy | CPT code development for long-read diagnostic procedures addresses payment uncertainty in clinical laboratory economics. |
Research Methodology
Bottom-up biotechnology company and clinical laboratory modeling reconciled against top-down instrument installation and consumable shipment tracking forms the analytical core. Primary interviews with sequencing core facility directors, FDA regulatory affairs specialists, hospital microbiology laboratory managers, and contract research organization procurement leads combined with secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, NIH RePORTER funding databases, and ISO 13485 quality management system registrations. Triangulation across these sources calibrates adoption rate assumptions and pricing tier distributions.
Input-output matrices map reagent consumption per installed instrument against capital expenditure cycles across portable, benchtop, and high-throughput platform tiers. Segmentation dimensions include product architecture, end-user sophistication, detection physics, and clinical versus research application maturity. CAGRs derive from instrument placement trajectories and consumable pull-through intensification in high-throughput installations. Forecast inputs incorporate membrane manufacturing yield improvements and regulatory pathway acceleration under breakthrough device programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement discretion shifts or dual-use export control expansion on biological data infrastructure. Material deviation in NIH genomic research funding levels or EMA notified body capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Nanopharmaceuticals Market