
 Middle East and Africa Genetic Testing Market | 2026-2036
Middle East and Africa Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Genetic Testing Market Foresight
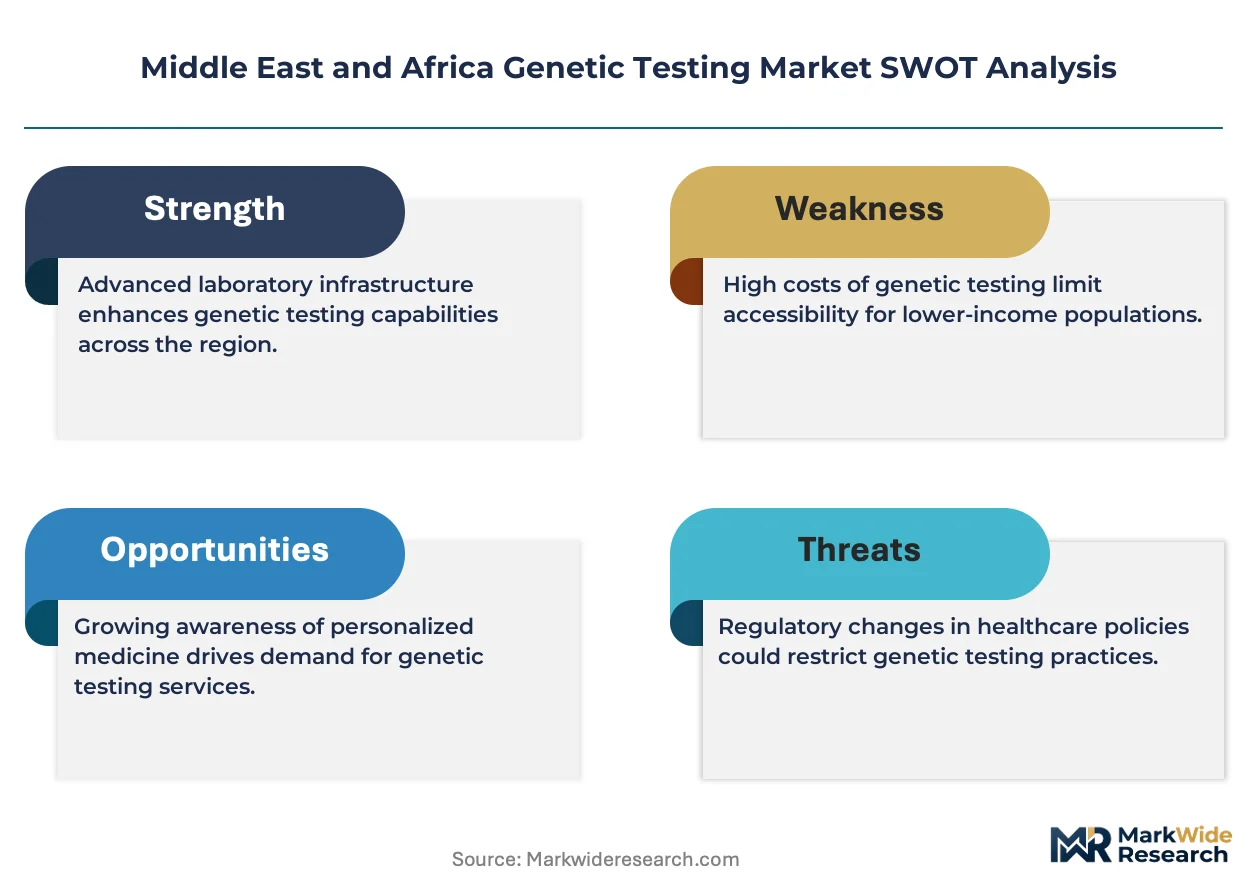
Next-generation sequencing is expanding access to pharmacogenomic profiling across Middle Eastern healthcare systems. Illumina leverages its installed base of sequencing platforms to anchor clinical partnerships in Gulf Cooperation Council states. Thermo Fisher Scientific sustains competitive positioning through integrated workflow solutions spanning sample prep to bioinformatics. QIAGEN specializes in companion diagnostic content that supports precision oncology programs across African research institutions.
Genetic testing encompasses molecular diagnostic methods that analyze DNA, RNA, chromosomes, proteins, and metabolites to detect heritable or somatic disease-related variants, typically requiring specimen extraction, amplification, and bioinformatic interpretation with turnaround times ranging from 48 hours to four weeks depending on assay complexity. Its primary purpose spans diagnostic confirmation, risk stratification, treatment selection, and carrier screening across clinical and research settings. Oncology applications dominate current revenue contribution given rising biobank-linked sequencing programs for hereditary cancer syndromes. Prenatal testing represents the fastest-growing application segment as non-invasive cell-free DNA screening displaces conventional amniocentesis in urban maternity networks. Next-generation sequencing technology commands the largest share of instrumentation investment while polymerase chain reaction retains volume leadership in point-of-care infectious disease contexts.
Saudi Arabia's SFDA and South Africa's national health laboratory service establish divergent regulatory pathways for clinical-grade assay validation, with the former accelerating approval timelines for locally manufactured kits under Vision 2030 biotech localization targets. The EU AI Act and GDPR extraterritorial provisions constrain cross-border genomic data transfers for multinational laboratory operators serving European patient populations from African hubs. Stakeholders must monitor evolving reimbursement frameworks for whole-exome sequencing in neonatal intensive care units across Gulf state health systems.
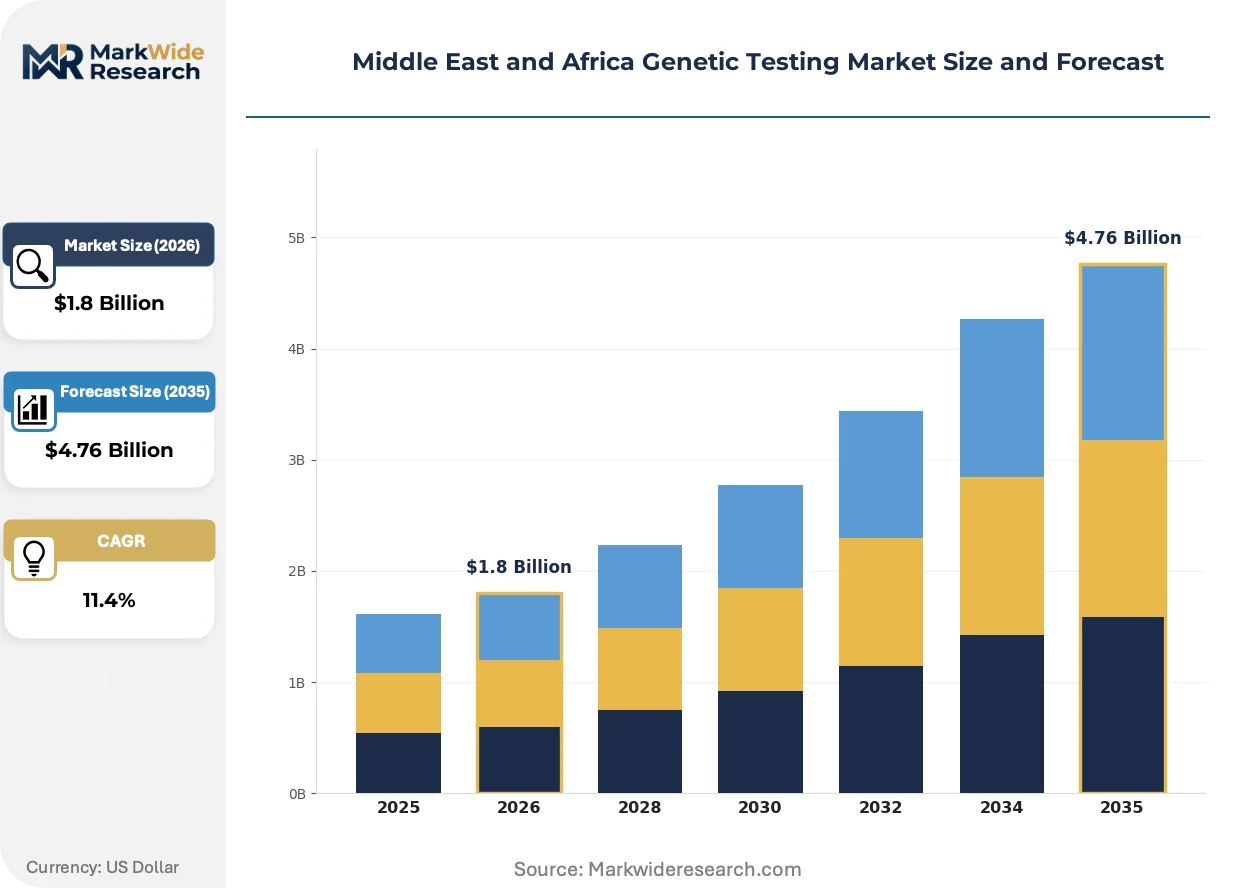
Market Dynamics
NGS platform commoditization is compressing margins across hospital laboratory networks while Saudi Arabia's Vision 2030 biotech localization mandates force multinational suppliers to establish domestic manufacturing partnerships or surrender procurement access.
Growth Catalysts
- SFDA accelerated approval pathways:Saudi Arabia's streamlined validation for locally manufactured diagnostic kits reduces commercialization timelines for regional manufacturers targeting hereditary cancer screening programs.
- Non-invasive prenatal testing expansion:Cell-free DNA screening protocols are displacing conventional amniocentesis across urban maternity networks in South Africa's private healthcare sector.
- Pharmacogenomic protocol integration:Gulf Cooperation Council health systems are embedding genomic profiling into oncology therapeutic decision-making, creating pull-through demand for companion diagnostic content.
Market Restraints
- Reagent import dependency:Cold-chain logistics for temperature-sensitive sequencing consumables concentrate supply risk through a limited corridor of European distribution hubs serving African laboratory networks.
- EU GDPR extraterritorial enforcement:Cross-border genomic data transfers from African processing centers to European patient populations face operational friction from data localization requirements.
- Specialist bioinformatician scarcity:Interpretation of complex variant calls requires trained personnel that remain concentrated in South Africa and Gulf state academic medical centers.
Strategic Opportunities
- Nigeria's diagnostic infrastructure gap:Underpenetrated molecular testing capacity outside Lagos and Abuja creates whitespace for hub-and-spoke sample referral networks targeting hereditary disease screening.
- AI-augmented variant interpretation:Machine learning classification tools are converging with NGS pipelines to reduce turnaround times for neonatal intensive care whole-exome sequencing decisions.
- UAE MOHAP precision medicine mandates:Federal health authority directives embedding pharmacogenomic testing into formulary coverage create procurement tailwinds for validated assay providers.
Industry Challenges
- Multi-jurisdiction quality certification:Laboratory accreditation requirements diverge between Saudi SFDA, South African NHLS, and UAE MOHAP standards, forcing redundant validation expenditure for cross-border service providers.
- LIMS integration complexity:Legacy hospital information systems across Gulf state public networks require bespoke middleware development to accommodate NGS data throughput and reporting formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Genetic Testing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Sequencing Services, Genetic Counseling, Screening Tests Application: Oncology, Prenatal Testing, Cardiovascular, Neurology End User: Hospitals, Laboratories, Research Institutions, Clinics Technology: Next-Generation Sequencing, Microarray, Polymerase Chain Reaction, Sanger Sequencing |
| Companies Covered | Illumina, Thermo Fisher Scientific, Roche Diagnostics, QIAGEN, Myriad Genetics, PerkinElmer, Invitae Corporation, CENTOGENE, Natera, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Genetic Testing Market Shifts & Advancements
Platform economics are fundamentally restructuring how genetic testing services are provisioned across Middle Eastern and African healthcare systems, with technology convergence and regulatory fragmentation operating as twin forces reshaping competitive boundaries.
Long-read sequencing is rewriting clinical validation standards for structural variant detection in hereditary disease panels. Saudi Arabia's King Faisal Specialist Hospital has adopted Pacific Biosciences platforms for resolving complex genomic rearrangements that short-read technologies miscall. This capability compression is forcing regional competitors to upgrade instrumentation or cede high-complexity oncology referrals to academic medical centers with captive long-read capacity.
South Africa's Health Products Regulatory Authority is tightening in vitro diagnostic registration requirements for laboratory-developed tests, mirroring EU MDR technical documentation standards. This regulatory convergence is elevating compliance costs for local molecular pathology laboratories while creating competitive shelter for multinational manufacturers with established quality management systems. Private hospital groups are responding by consolidating send-out volumes to centralized reference laboratories with pre-validated assay menus.
Direct-to-consumer genetic testing portals are capturing wellness-oriented demand that traditional clinical channels previously ignored. South African pharmacy retail chains are deploying self-collection kits for ancestry and pharmacogenomic screening, bypassing physician gatekeepers entirely. This channel disintermediation is most visible in Gauteng and Western Cape provinces where private health insurance penetration supports out-of-pocket spending on predictive health information.
Middle East and Africa Genetic Testing Market Segmentation
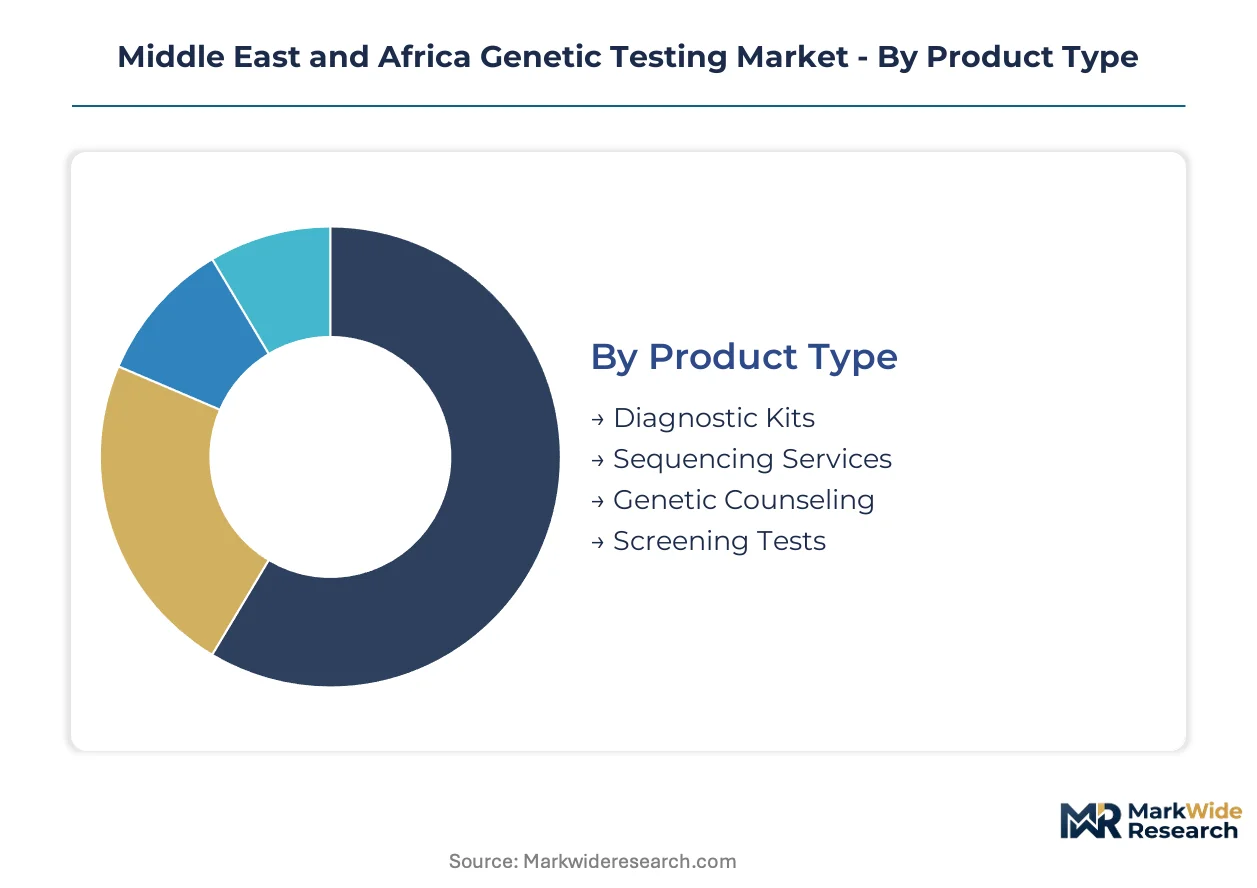
Genetic testing markets fragment across multiple dimensions that determine procurement patterns and margin structures. Product form factors, clinical applications, and technology platforms each create distinct competitive arenas with divergent supplier concentration and customer loyalty dynamics.
Product Type:
Supply concentration varies sharply across product categories, with kit manufacturing consolidating around multinational reagent suppliers while services remain geographically dispersed.
- Diagnostic Kits:Pre-formulated reagent panels for targeted mutation detection dominate hospital laboratory procurement in Saudi Arabia and South Africa. Cold-chain logistics constraints and SFDA localization mandates are forcing multinational suppliers to establish regional fill-finish partnerships or cede public sector tenders.
- Sequencing Services:Outsourced NGS workflows for whole-exome and whole-genome analysis concentrate in South Africa's private laboratory sector and Gulf state academic medical centers. Turnaround time compression and bioinformatic interpretation complexity create switching costs that anchor recurring revenue streams.
- Genetic Counseling:Interpretation support services bridge the gap between raw variant calls and clinical decision-making. Specialist workforce scarcity limits scalable delivery outside Johannesburg, Cape Town, and Gulf state capital cities.
- Screening Tests:Population-scale carrier screening and newborn panels constitute high-volume, lower-margin offerings. Demand clusters in UAE and Saudi national health screening programs with centralized procurement authority.
Today's leader: Diagnostic Kits. Tomorrow's challenger: Sequencing Services.
Application:
Clinical utility and reimbursement authorization create tiered market access, with oncology commanding premium pricing and prenatal applications expanding fastest through private pay channels.
- Oncology:Companion diagnostic testing for targeted therapeutics and hereditary cancer syndrome screening generates the largest revenue contribution. Biobank-linked sequencing programs at King Faisal Specialist Hospital and South African academic centers anchor demand.
- Prenatal Testing:Non-invasive cell-free DNA screening for fetal aneuploidy is displacing conventional amniocentesis across urban maternity networks. Private hospital groups in Gauteng and Western Cape provinces drive adoption through out-of-pocket payment models.
- Cardiovascular:Pharmacogenomic profiling for anticoagulant and statin response guides therapeutic selection in Gulf Cooperation Council health systems. UAE MOHAP formulary mandates are embedding testing into standard care pathways.
- Neurology:Rare disease exome sequencing for developmental delay and epilepsy presentations serves niche academic referral patterns. Long-read sequencing adoption at Saudi centers is resolving complex structural variants that short-read platforms miscall.
Oncology retains revenue dominance. Prenatal Testing climbs fastest through channel expansion.
End User:
Customer concentration and purchasing sophistication determine contract structures, with hospital networks consolidating volumes and research institutions demanding bespoke assay development.
- Hospitals:Integrated health systems in Saudi Arabia and South Africa are consolidating send-out volumes to captive laboratories or preferred reference partners. NGS platform standardization across hospital networks creates vendor lock-in effects.
- Laboratories:Independent and hospital-affiliated molecular pathology facilities constitute the primary service delivery infrastructure. South Africa's NHLS and private reference laboratories split public and private sector demand.
- Research Institutions:Academic medical centers and genomics institutes drive technology adoption for translational research applications. King Abdullah International Medical Research Center and comparable Gulf state facilities anchor instrumentation investment.
- Clinics:Outpatient specialty practices and primary care networks represent emerging access points for pharmacogenomic screening. Direct-to-consumer kit distribution through South African pharmacy retail chains bypasses traditional clinical channels.
Hospitals command procurement volume. Clinics represent the steepest expansion trajectory through channel disintermediation.
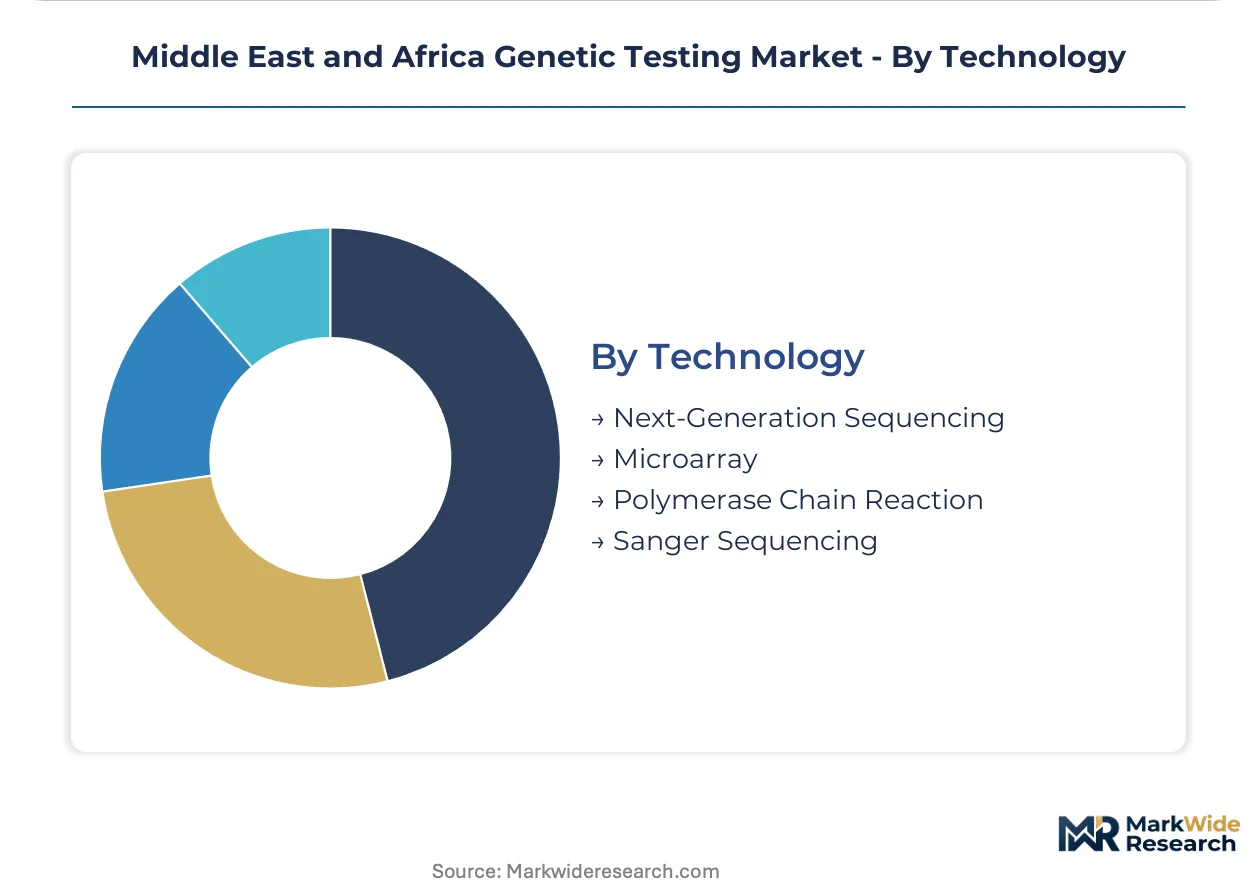
Technology:
Platform economics and workflow integration requirements segment the supplier base, with NGS commanding capital investment and PCR retaining point-of-care infectious disease dominance.
- Next-Generation Sequencing:Short-read platforms from Illumina and Thermo Fisher Scientific anchor clinical laboratory infrastructure across the region. Long-read sequencing adoption at Saudi academic centers is creating capability differentiation for complex variant detection.
- Microarray:Chromosomal microarray analysis for copy number variation detection serves prenatal and developmental disorder applications. Reagent cost advantages sustain positioning for high-volume screening programs with lower resolution requirements.
- Polymerase Chain Reaction:Real-time PCR retains volume leadership in infectious disease and targeted mutation detection. Point-of-care instrument deployment extends access beyond centralized laboratory networks.
- Sanger Sequencing:First-generation sequencing maintains niche utility for confirmatory testing and single-gene disorder analysis. Capital efficiency and established workflows preserve presence in resource-constrained settings.
Next-Generation Sequencing leads instrumentation investment. Polymerase Chain Reaction defends infectious disease volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's King Faisal Specialist Hospital anchors the Middle East's most advanced genomics infrastructure, with long-read sequencing platforms resolving complex structural variants that short-read technologies miscall.
Saudi Arabia
Vision 2030 biotech localization mandates and hereditary cancer screening programs drive procurement volumes. SFDA accelerated approval pathways reduce commercialization timelines for regionally manufactured diagnostic kits. Riyadh's academic medical centers anchor NGS platform deployment for oncology companion diagnostics.
South Africa
Private laboratory sector consolidation and non-invasive prenatal testing expansion fuel service demand. Health Products Regulatory Authority IVD registration requirements are tightening to mirror EU MDR documentation standards. Gauteng and Western Cape provinces concentrate send-out volumes to centralized reference laboratories with pre-validated assay menus.
United Arab Emirates
MOHAP precision medicine mandates embedding pharmacogenomic testing into formulary coverage create procurement tailwinds. Federal health authority directives standardize genomic profiling across oncology therapeutic pathways. Dubai's healthcare free zones attract multinational diagnostic manufacturers seeking Gulf market access.
Nigeria
Underpenetrated molecular testing capacity outside Lagos and Abuja generates whitespace for hub-and-spoke sample referral networks. National health insurance scheme expansion targets hereditary disease screening program integration. Lagos anchors private sector laboratory investment while northern states rely on centralized public health infrastructure.
Egypt
Academic medical center partnerships with Gulf state genomics institutes facilitate technology transfer and training programs. National research institutions prioritize rare disease sequencing capacity for regional referral patterns. Cairo's university hospitals concentrate specialist bioinformatician expertise for variant interpretation services.
Middle East and Africa Genetic Testing Market Competitive Landscape
Global majors compete with regional champions across technology platform access and regulatory pathway navigation. Market structure consolidates around multinational reagent suppliers while sequencing services fragment across geographically dispersed laboratory networks. Three archetypes dominate: integrated workflow solution providers, companion diagnostic content specialists, and platform-agnostic service laboratories. Strategic moves concentrate on domestic manufacturing partnerships and bioinformatics capability acquisition.
Among US-based instrumentation and reagent suppliers, Illumina and Thermo Fisher Scientific anchor the NGS platform tier through installed base expansion and clinical partnership development. QIAGEN occupies a position exemplifying companion diagnostic content specialization. These three represent divergent competitive vectors: platform economics, integrated workflow control, and precision oncology assay validation.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Roche Diagnostics |
| QIAGEN |
| Myriad Genetics |
| PerkinElmer |
| Invitae Corporation |
| CENTOGENE |
| Natera |
| Others |
Supply & Pricing Matrix
Certification-grade stratification between SFDA-validated diagnostic kits and unregistered laboratory-developed tests creates divergent margin structures across Middle Eastern and African procurement channels. This bifurcation concentrates pricing power with multinational manufacturers holding established quality management systems while regional laboratories absorb validation cost burdens that compress service-level economics.
Pricing Analysis
Reagent cost pass-through from European distribution hubs anchors kit pricing at import parity levels for African hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates Illumina-platformed oncology panels from PCR-based infectious disease assays and research-grade screening tests. Pricing pressure stems from NGS platform commoditization compressing per-sample margins in Gulf state hospital laboratories. Public sector tenders in Saudi Arabia exhibit highest price sensitivity due to Vision 2030 localization mandates, while South Africa's private reference laboratories retain pricing flexibility through turnaround time premiums.
Supply Chain Analysis
Dual-sourcing requirements for sequencing consumables are emerging as procurement policy across UAE MOHAP-contracted laboratory networks. Supply concentration centers on Germany, the Netherlands, and Singapore for temperature-sensitive reagent manufacturing. Cold-chain logistics for sequencing flow cells and library prep kits rest on specialized courier networks with limited African corridor capacity. Single-source vulnerability concentrates around Illumina's proprietary flow cell architecture, forcing regional distributors to maintain elevated safety stock. Distribution runs through Johannesburg and Dubai as primary hubs for onward African deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through embedded pharmacogenomic protocol integration across Gulf Cooperation Council health systems, creating recurring demand visibility for validated assay providers.
For Market Incumbents: Cement platform economics through captive bioinformatics partnerships that lock hospital networks into end-to-end NGS workflows. Defend against emerging long-read sequencing specialists by upgrading installed bases at King Faisal Specialist Hospital and comparable academic centers. Prioritize SFDA manufacturing partnerships to secure public sector tender access under localization mandates. For New Entrants and Emerging Players: AI-augmented variant interpretation tools offer technology-first wedge into neonatal intensive care whole-exome sequencing decisions where turnaround time compression commands premium pricing. Target Nigeria's hub-and-spoke sample referral networks as the most penetrable geography outside Lagos and Abuja. Pursue direct-to-consumer pharmacy retail distribution in South Africa's Gauteng and Western Cape provinces to bypass physician gatekeeper channels. For Investors and Strategic Acquirers: Asymmetric upside sits with platform-agnostic service laboratories possessing multi-jurisdiction quality certification. Five-to-ten year viability hinges on bioinformatician workforce development and AI tooling integration. Signal to watch: UAE MOHAP formulary expansion beyond oncology into cardiovascular pharmacogenomic coverage.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Manufacturing Partnership | Localization mandates under Vision 2030 require domestic fill-finish capacity for public tender eligibility. |
| Long-read Sequencing Platform Deployment | Pacific Biosciences adoption at Saudi academic centers resolves structural variants short-read technologies miscall. |
| AI Variant Interpretation Integration | Machine learning classification tools reduce turnaround times for neonatal intensive care sequencing decisions. |
| Hub-and-Spoke Sample Network Buildout | Lagos-Abuja corridor expansion targets Nigeria's underpenetrated molecular testing capacity outside major cities. |
| Direct-to-Consumer Channel Development | South African pharmacy retail chains bypass physician gatekeepers for ancestry and pharmacogenomic screening kits. |
Research Methodology
Bottom-up hospital laboratory procurement modeling reconciled against top-down reagent supplier shipment tracking forms the analytical core of this study. Primary interviews with clinical laboratory directors, SFDA regulatory affairs specialists, GPO contracts managers, and biomedical engineers across Riyadh, Johannesburg, and Dubai informed demand-side assumptions. Secondary validation drew from SFDA device registration databases, South African Health Products Regulatory Authority IVD filings, hospital procurement records, and GCC health authority formulary directives. Triangulation between these sources anchored market sizing with cross-referenced supply-side and demand-side estimates.
Historical trendline analysis across NGS platform installations, diagnostic kit import volumes, and sequencing service revenues established baseline growth trajectories. The projection framework models technology platform, clinical application, end-user category, and geographic market dimensions throughout the forecast period. CAGRs derive from regression-adjusted trend extrapolation incorporating pharmacogenomic protocol adoption curves and national genomics initiative spending commitments. Forecast inputs include SFDA approval timeline compression under localization targets and South African private health insurance penetration rates.
The model holds under stable regulatory enforcement of data localization requirements; deviation in EU GDPR extraterritorial interpretation or Saudi biotech localization ambition would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Next Generation Sequencing Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
DNA Sequencing Market
Genomics
Microarray Biochips Market
Genomics
Alagille Syndrome Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Omics Lab Services Market
Genomics
China Genetic Testing Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
AI in Genomics Market
Genomics
Europe Genetic Testing Market
Genomics
Mendelian Disorders Testing Market
Genomics
Global Microarray Analysis Market
Genomics
Glycan Sequencing Market
Genomics
Restriction Endonucleases Market