
 Global Digital PCR Market | 2026-2036
Global Digital PCR Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital PCR Market Foresight
Single-source reliance on internal reagent manufacturing is pivoting toward hybrid models that blend captive droplet chemistry production with outsourced microfluidic chip fabrication. Bio-Rad Laboratories leverages its end-to-end droplet generator and reader ecosystem to sustain installed-base loyalty across clinical and research accounts. Thermo Fisher Scientific anchors its position through deep integration with adjacent qPCR and sequencing workflows. QIAGEN competes by specializing in sample-to-insight automation that reduces hands-on time for high-complexity laboratories.
Digital PCR quantifies nucleic acid targets through absolute molecule counting via massive parallel partitioning, typically achieving sensitivity below one copy per microliter without standard curve dependency. Droplet digital PCR occupies the largest installed base, while chip-based digital PCR is gaining share where rapid turnaround and reduced sample volume matter most. Pharmaceutical companies represent the deepest end-user segment, with genotyping and copy number variation applications absorbing the majority of consumables pull-through.
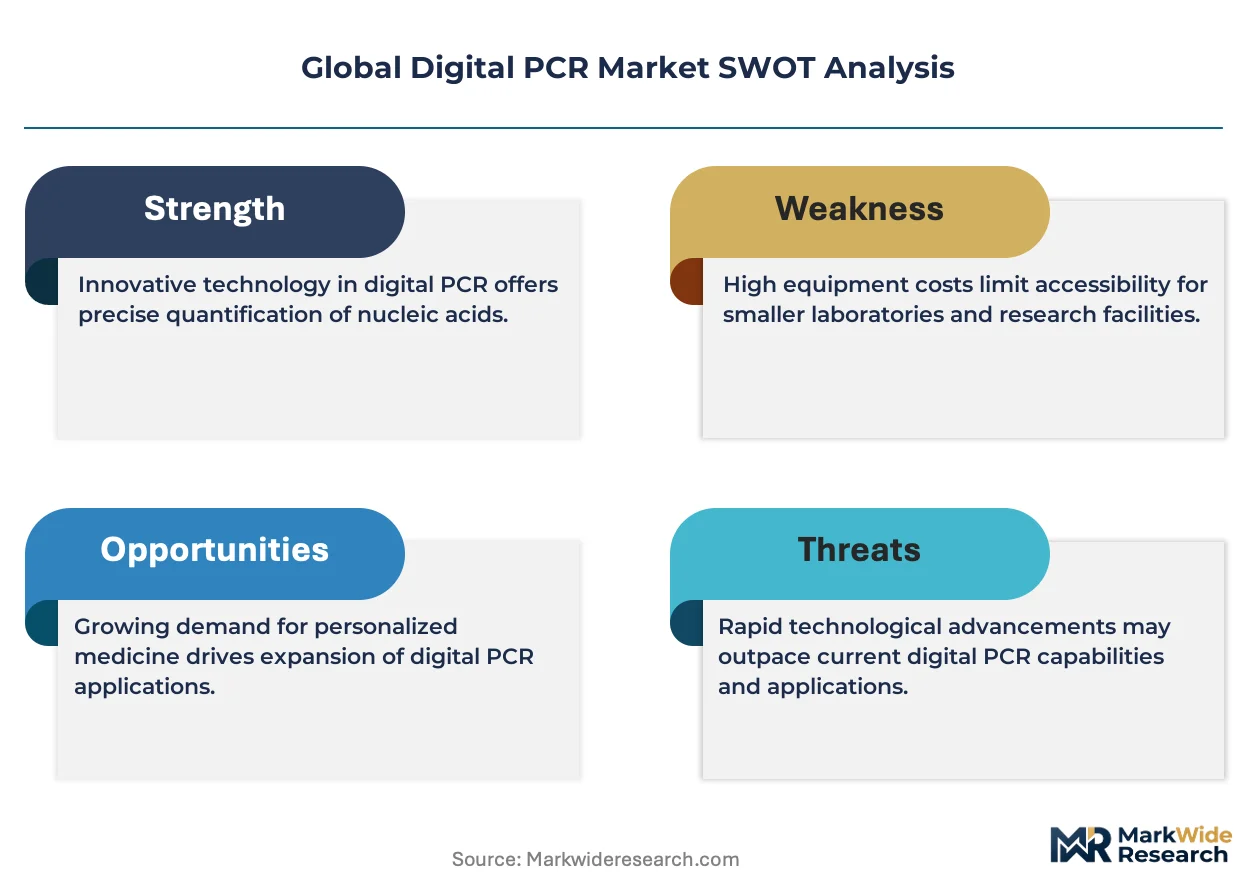
FDA oversight of laboratory-developed tests and companion diagnostics shapes product development priorities for US commercialization, while the EU IVDR imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. The EPA and OSHA frameworks influence reagent handling and waste protocols in high-throughput facilities. Stakeholders must monitor how evolving regulatory divergence between FDA and EMA pathways affects validation burden and time-to-market for multiplexed liquid biopsy assays.
Market Dynamics
Pharmaceutical pipelines for cell and gene therapy are compressing validation timelines for nucleic acid quantification, forcing dPCR vendors to recalibrate instrument throughput and consumables supply chains around CDMO batch-release workflows.
Growth Catalysts
- Companion diagnostic mandates:FDA's expanding oversight of oncology biomarker testing drives pharmaceutical sponsors to embed dPCR validation earlier in clinical trial design.
- EU IVDR analytical rigor:The regulation's stricter performance requirements for nucleic acid tests are accelerating laboratory upgrades to absolute quantification platforms.
- Cell therapy manufacturing scale-up:CDMOs in Massachusetts and North Carolina are installing high-throughput dPCR workflows for vector copy number determination.
Market Restraints
- Microfluidic chip supply concentration:Foundry capacity for precision-molded consumables concentrates among a handful of East Asian contract manufacturers.
- Reagent cold-chain complexity:Enzyme and probe stability requirements inflate logistics costs for distributed clinical sites.
- qPCR substitution in routine screening:Lower-cost quantitative PCR retains dominance in high-volume, low-sensitivity infectious disease panels.
Strategic Opportunities
- Point-of-care decentralization:Brazil's ANVISA pathway for near-patient oncology testing creates openings for chip-based systems with reduced sample input.
- Environmental DNA monitoring:EPA frameworks for aquatic pathogen surveillance are spawning demand for field-deployable absolute quantification.
- AI-assisted droplet classification:Machine learning integration with fluorescence readouts promises to compress analysis time and operator training burdens.
Industry Challenges
- Multiplex assay standardization:Absence of harmonized reference materials complicates cross-platform validation for liquid biopsy developers.
- Specialized field service density:Instrument uptime requirements in GMP environments outpace vendor technician deployment in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital PCR Market |
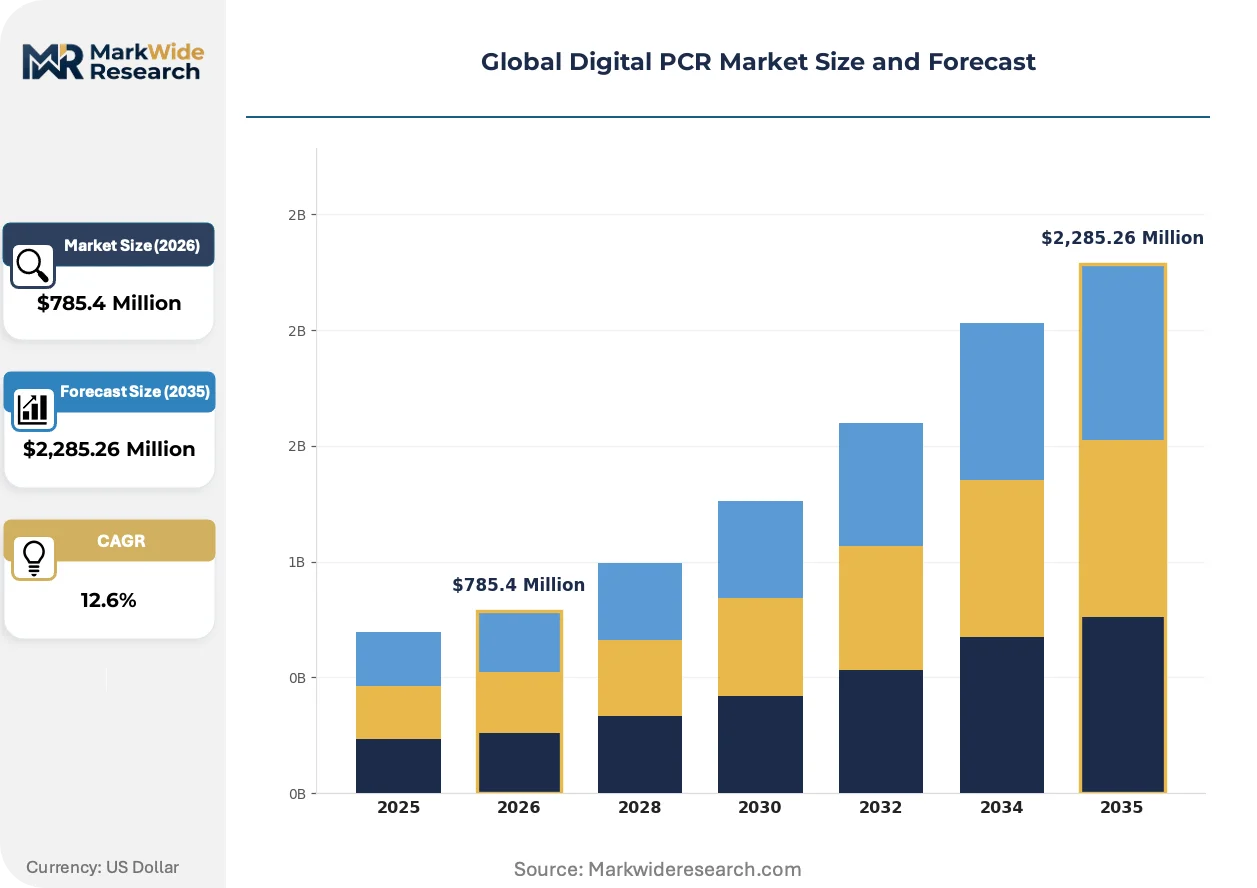
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $2,285.26 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Droplet Digital PCR, Chip-Based Digital PCR, Microfluidic Digital PCR, Chamber Digital PCR Technology: Partitioning by Water-in-Oil Emulsion, Microchambers, Microarrays, Digital Colorimetry Application: Genotyping, Gene Expression, Mutation Detection, Copy Number Variation End User: Pharmaceutical Companies, Biotechnology Firms, Agriculture Researchers, Forensic Laboratories |
| Companies Covered | Bio-Rad Laboratories, Thermo Fisher Scientific, QIAGEN, F. Hoffmann-La Roche Ltd, Danaher Corporation, Merck KGaA, Agilent Technologies, Sysmex Corporation, Standard BioTools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital PCR Market Shifts & Advancements
Partitioning chemistries and readout architectures are diverging as end-users fragment between centralized high-throughput facilities and distributed precision-medicine sites. This bifurcation is reshaping R&D allocation and partnership strategies across the supply base.
Chip-based digital PCR is decentralizing nucleic acid quantification by embedding microfluidic partitioning into cartridge formats compatible with standard laboratory automation. Academic medical centers in Germany and the Netherlands are piloting these systems for intraoperative tumor margin assessment. The technology is compressing the turnaround gap between centralized reference labs and hospital pathology departments.
REACH restrictions on perfluorinated compounds are forcing reagent formulators to reformulate droplet generation oils and surfactants. Manufacturers seeking CE marking under EU IVDR must resubmit stability data for reformulated consumables. European diagnostic laboratories face extended validation timelines as they reconcile legacy assay performance with modified chemistry lots.
Cell therapy developers are unbundling instrument procurement from consumables contracts, negotiating separate supply agreements for droplet generators and detection reagents. CDMOs in Singapore and South Korea are driving this fragmentation to secure dual-source redundancy for GMP manufacturing. The shift pressures vendors to disaggregate historically bundled pricing architectures.
Global Digital PCR Market Segmentation
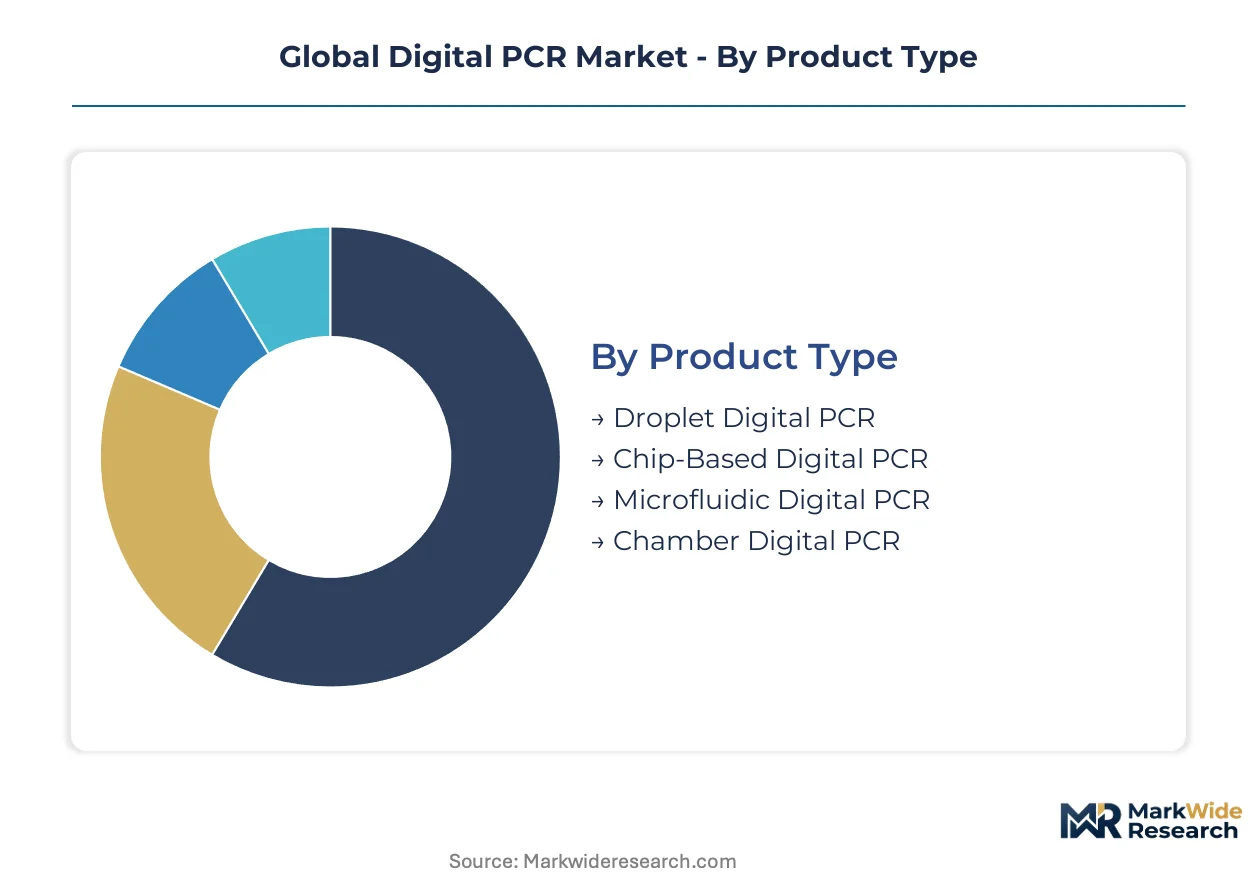
Segmentation in digital PCR reveals how partitioning architectures, readout chemistries, and end-user workflows diverge across precision medicine applications. Each dimension carries distinct supply chain implications and regulatory validation burdens.
Product Type:
Customization intensity varies sharply across this category, with cartridge-based systems demanding bespoke microfluidic engineering while droplet platforms scale through standardized consumables.
- Droplet Digital PCR:Water-in-oil emulsion partitioning generates millions of picoliter droplets through proprietary cartridge-and-reader architectures. Pharmaceutical sponsors in Massachusetts and North Carolina deploy these systems for cell therapy vector copy number determination under FDA companion diagnostic pathways.
- Chip-Based Digital PCR:Integrated microfluidic cartridges embed partitioning chambers directly onto disposable substrates. Academic medical centers in Germany and the Netherlands pilot these for intraoperative tumor margin assessment where rapid turnaround supersedes throughput.
- Microfluidic Digital PCR:Hybrid architectures combine continuous-flow microfluidics with discrete chamber isolation. Agriculture researchers in Brazil leverage these for field-deployable GMO quantification under ANVISA frameworks.
- Chamber Digital PCR:Fixed-array partitioning into nanoliter reaction wells suits reference laboratory standardization. Forensic laboratories favor this format for DNA quantification in degraded sample workflows.
Leading the category by volume: Droplet Digital PCR. Expanding most quickly: Chip-Based Digital PCR.
Technology:
Cost tier stratification separates mature emulsion chemistries from emerging readout modalities requiring specialized optical engineering.
- Partitioning by Water-in-Oil Emulsion:Surfactant-stabilized droplet generation dominates installed base economics through reagent recurring revenue models. REACH restrictions on perfluorinated surfactants are forcing reformulation of generation oils for CE marking compliance.
- Microchambers:Photolithographically etched silicon or polymer substrates enable precise volume control for absolute quantification. Biotechnology firms in Singapore adopt these for GMP batch release where volume traceability is mandatory.
- Microarrays:High-density spatial partitioning supports multiplexed target detection in liquid biopsy development. The absence of harmonized reference materials complicates cross-platform validation for this architecture.
- Digital Colorimetry:Label-free detection via chromogenic readouts reduces fluorescence hardware costs. Early-stage agriculture researchers in India evaluate these for cost-constrained pathogen surveillance under CDSCO guidance.
Dominating by installed base: Water-in-Oil Emulsion. Steepest expansion trajectory: Microchambers.
Application:
Customer type concentration varies by analytical complexity, with pharmaceutical sponsors driving high-value genotyping while public health laboratories anchor mutation detection volume.
- Genotyping:Allele discrimination via probe-based detection supports pharmacogenomic testing and companion diagnostic development. FDA oversight of oncology biomarker testing embeds dPCR validation earlier in clinical trial design for this application.
- Gene Expression:Absolute quantification of mRNA transcripts enables rare cell population characterization. Cell therapy CDMOs in South Korea deploy these workflows for potency assay development.
- Mutation Detection:Rare allele detection below 0.1% variant allele fraction supports liquid biopsy monitoring. EU IVDR analytical rigor accelerates laboratory upgrades to absolute quantification platforms for this use case.
- Copy Number Variation:Absolute gene dosage determination validates CRISPR editing efficiency and viral vector titer. Massachusetts-based cell therapy developers unbundle instrument procurement from consumables contracts to secure dual-source redundancy.
Highest revenue concentration: Genotyping. Gaining share fastest: Copy Number Variation.
End User:
Volume scale separates centralized pharmaceutical manufacturing from distributed forensic and agriculture deployments with diverging service intensity requirements.
- Pharmaceutical Companies:Integrated drug-diagnostic development teams demand validated workflows for regulatory submission. FDA companion diagnostic mandates compress validation timelines, forcing vendors to recalibrate throughput around CDMO batch-release cycles.
- Biotechnology Firms:Venture-funded developers prioritize platform flexibility for pipeline pivoting between therapeutic modalities. Singapore and South Korean CDMOs drive fragmentation of bundled pricing architectures.
- Agriculture Researchers:Seed developers and pathogen surveillance programs value field portability and reduced sample input. EPA frameworks for aquatic pathogen surveillance spawn demand for absolute quantification in this segment.
- Forensic Laboratories:Criminal justice and paternity testing workflows require chain-of-custody documentation and extended reagent stability. Cold-chain complexity for enzyme and probe logistics inflates distributed site costs.
Deepest consumables pull-through: Pharmaceutical Companies. Fastest adoption acceleration: Biotechnology Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsors in the United States absorb the deepest consumables pull-through, while academic medical centers in Germany and CDMOs in Singapore accelerate adoption curves through distinct regulatory and manufacturing incentives.
United States
FDA companion diagnostic mandates compress validation timelines for oncology biomarker testing, embedding dPCR workflows earlier in clinical trial design. Massachusetts-based cell therapy developers and North Carolina CDMOs install high-throughput systems for vector copy number determination under GMP batch-release protocols.
Germany
Academic medical centers in Heidelberg and Munich pilot chip-based systems for intraoperative tumor margin assessment where rapid turnaround supersedes throughput. REACH restrictions on perfluorinated surfactants force reagent reformulation for CE marking compliance under EU IVDR analytical rigor.
Singapore
Biotechnology firms and CDMOs drive fragmentation of bundled instrument-consumables contracts to secure dual-source redundancy for cell therapy manufacturing. The country's national pharmaceutical regulator aligns with international GMP standards to attract multi-regional clinical trial sponsors.
China
Agriculture researchers in the Yangtze River Delta evaluate field-deployable systems for GMO quantification under national biosafety frameworks. Domestic instrument fabricators compete on cost-constrained pathogen surveillance contracts for provincial CDC networks.
Brazil
ANVISA pathways for near-patient oncology testing create openings for chip-based systems with reduced sample input. São Paulo-based reference laboratories upgrade absolute quantification platforms to meet stricter analytical performance requirements for clinical nucleic acid testing.
Global Digital PCR Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors recalibrate around fragmented procurement patterns. The vendor base separates into three tiers: integrated life science conglomerates with end-to-end droplet ecosystems, specialized sample-to-insight automation providers, and emerging chip-based platform developers. Competitive positioning hinges on installed-base loyalty programs, consumables recurring revenue capture, and regulatory validation bundling for companion diagnostic submissions.
Within the integrated systems tier, Bio-Rad Laboratories and Thermo Fisher Scientific exemplify divergent anchoring strategies. Bio-Rad sustains clinical and research account loyalty through captive droplet generator and reader ecosystems. Thermo Fisher anchors positioning through deep integration with adjacent qPCR and sequencing workflows. QIAGEN occupies a specialist position, reducing hands-on time for high-complexity laboratories through sample-to-insight automation architectures.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies |
| Sysmex Corporation |
| Standard BioTools |
| Others |
Supply & Pricing Matrix
Captive droplet chemistry production anchors pricing power for integrated instrument vendors while outsourced microfluidic chip fabrication creates tiered supply dependencies. This hybrid integration pattern concentrates margin capture with reagent formulators and exposes cartridge-based system developers to foundry capacity bottlenecks in East Asian contract manufacturing hubs.
Pricing Analysis
Extended warranty and field service bundling separate premium-tier pharmaceutical accounts from economy-positioned research laboratories. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13485 certification status and GMP validation documentation. Cost compression in the economy tier intensifies because academic buyers prioritize capital expenditure minimization over throughput specifications. Biotechnology CDMOs exhibit lowest price sensitivity due to batch-release compliance requirements, while agriculture researchers in emerging markets drive procurement toward unbundled instrument-only configurations.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating restrict microfluidic chip sourcing to validated polymer foundries in Japan, Germany, and Singapore. Perfluorinated surfactant reformulation under REACH draws from specialty chemical suppliers in Switzerland and the United States. Single-source vulnerability concentrates in precision-molded consumables where photolithographic tooling costs deter supplier switching. Distribution runs through authorized service organizations for GMP-compliant installations and direct e-commerce channels for research-grade reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital PCR Market is becoming a vertical-integration race as vendors pursue captive control over droplet generation chemistries to defend consumables recurring revenue against unbundling pressures from cell therapy CDMOs.
For Market Incumbents: Anticipate chip-based platform encroachment by accelerating GMP-grade field service density in Massachusetts and North Carolina manufacturing clusters. Deepen backward integration into surfactant formulation to offset REACH-driven reagent reformulation costs. Lock in multi-year consumables contracts with pharmaceutical sponsors before EU IVDR validation timelines compress procurement flexibility. For New Entrants and Emerging Players: The gap between premium companion diagnostic-validated systems and economy research-grade platforms opens white-space at the mid-tier for semi-automated chip-based systems. Brazil's ANVISA pathway for near-patient oncology testing represents the most penetrable geography. Target environmental DNA monitoring applications with field-deployable absolute quantification to bypass entrenched clinical laboratory relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to life science conglomerates seeking droplet partitioning IP. Long-term viability hinges on recurring revenue capture ratios exceeding instrument depreciation cycles. Monitor FDA companion diagnostic mandate expansion as the inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EU IVDR analytical performance requirements accelerate CE marking investments for nucleic acid tests. |
| Manufacturing Scale-Up | High-throughput dPCR workflow deployment supports CDMO batch-release cycles in cell therapy hubs. |
| Backward Integration | In-house droplet chemistry production defends consumables margins against unbundling pressures. |
| Strategic Partnership | AI-assisted droplet classification alliances compress analysis time for distributed precision medicine sites. |
| Geographic Expansion | ANVISA pathway entry captures near-patient oncology testing demand in Brazilian reference laboratories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with instrument development executives, regulatory affairs specialists at IVD manufacturers, CDMO quality directors, and hospital laboratory managers combined with FDA 510(k) databases, EU IVDR technical documentation, and import-export manifests. Bottom-up instrument shipment tracking and top-down pharmaceutical R&D expenditure analysis provided triangulation validation.
Reconciliation of vendor-reported consumables pull-through against pharmaceutical sponsor procurement disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include partitioning architecture, readout chemistry, application complexity, and end-user regulatory environment. CAGRs derived from weighted average of historical adoption curves and pipeline-stage therapeutic modality forecasts. Cell therapy vector copy number determination workflows and liquid biopsy assay development timelines served as industry-specific demand inputs.
Inputs from FDA pre-submission meetings and EU notified body technical files were available through the study window; gaps in proprietary CDMO contract terms introduce uncertainty bands around consumables revenue attribution. Forecasts reflect documented assumptions regarding companion diagnostic mandate expansion rates and REACH surfactant reformulation adoption timelines. A model refresh is warranted upon material change in FDA oversight of laboratory-developed tests or EMA-EMA regulatory divergence on multiplexed liquid biopsy validation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Europe Digital PCR Market
Genomics
Mitochondrial DNA Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
Genetic Material Market
Genomics
Dna Polymerase Market
Genomics
Genomics Personalized Health Market
Genomics
Genetic Testing Service Market
Genomics
Single-Cell Omics Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
North America Genetic Testing Market
Genomics
Genomic Biomarkers Market
Genomics
Whole Genome Amplification Market
Genomics
Hereditary Testing Market
Genomics
Gene Sequencing Market