
 Next Generation in-Vehicle Networking (IVN) Market | 2026-2036
Next Generation in-Vehicle Networking (IVN) Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation in-Vehicle Networking (IVN) Market Analysis
Aftermarket service revenue is narrowing as OEMs tighten software-defined vehicle architectures and restrict third-party network access. Robert Bosch GmbH leverages its tier-1 supplier position to sustain dominance in gateway controller production. NXP Semiconductors anchors its growth in automotive Ethernet PHY portfolios. Infineon Technologies differentiates through silicon carbide integration at the power-network interface.
Next Generation in-Vehicle Networking comprises high-speed data backbone technologies—specifically multi-gigabit automotive Ethernet, CAN XL, and deterministic wireless links—that interconnect electronic control units across distributed zonal domains. These systems enable real-time sensor fusion, over-the-air updates, and functional safety partitioning for software-defined vehicles. Ethernet leads product type segments as bandwidth requirements for autonomous driving exceed legacy CAN-FD throughput ceilings. Wireless and V2X technology segments capture the fastest expansion as roadside infrastructure deployment accelerates. Application demand concentrates in autonomous driving and advanced driver assistance systems where latency below five milliseconds determines system architecture choices.
NHTSA cybersecurity guidelines, the EU Cyber Resilience Act, and China's GB/T vehicle network security standards collectively mandate encrypted in-vehicle communication and intrusion detection capabilities. These frameworks compel semiconductor vendors to embed hardware security modules directly into transceiver and switch silicon. Stakeholders must monitor protocol convergence timelines between IEEE 802.1 Time-Sensitive Networking and proprietary OEM implementations to anticipate interoperability certification requirements.
Market Dynamics
OEM procurement of zonal E/E architectures is collapsing the legacy domain-based controller topology, forcing semiconductor vendors to rearchitect switch silicon for deterministic multi-gigabit throughput across distributed compute zones.
Growth Catalysts
- EU Cyber Resilience Act:Mandates hardware security modules in connected vehicle components, compelling tier-1 suppliers to embed encryption at the PHY layer.
- Autonomous driving sensor fusion:Real-time LiDAR and camera data aggregation requires sub-five-millisecond latency that only multi-gigabit automotive Ethernet can deliver.
- German engineering clusters:Stuttgart and Munich anchor protocol standardization efforts for IEEE 802.1 Time-Sensitive Networking certification.
Market Restraints
- Silicon carbide substrate costs:Power-network interface integration at the zonal gateway level faces input cost volatility from limited 150mm wafer supply.
- Single-source switch silicon:Automotive Ethernet PHY production concentrates among three foundry-dependent vendors, creating geographic concentration risk.
- Legacy CAN-FD interoperability:Backward compatibility requirements impose bandwidth ceilings that throttle full Ethernet migration timelines.
Strategic Opportunities
- China's GB/T vehicle network security standards:Mandates for encrypted in-vehicle communication create regulatory tailwind for hardware security module vendors.
- V2X roadside infrastructure:Deterministic wireless links between vehicle and edge compute nodes open white space in cellular-V2X and DSRC convergence.
- Over-the-air update channels:OEM direct-to-vehicle software distribution is bypassing traditional tier-2 diagnostic tool suppliers.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for Ethernet switches requires 18-24 month validation cycles that delay platform launches.
- Cross-domain integration:Zonal gateway controllers must simultaneously manage power distribution, thermal management, and infotainment traffic with deterministic isolation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation in-Vehicle Networking (IVN) Market |
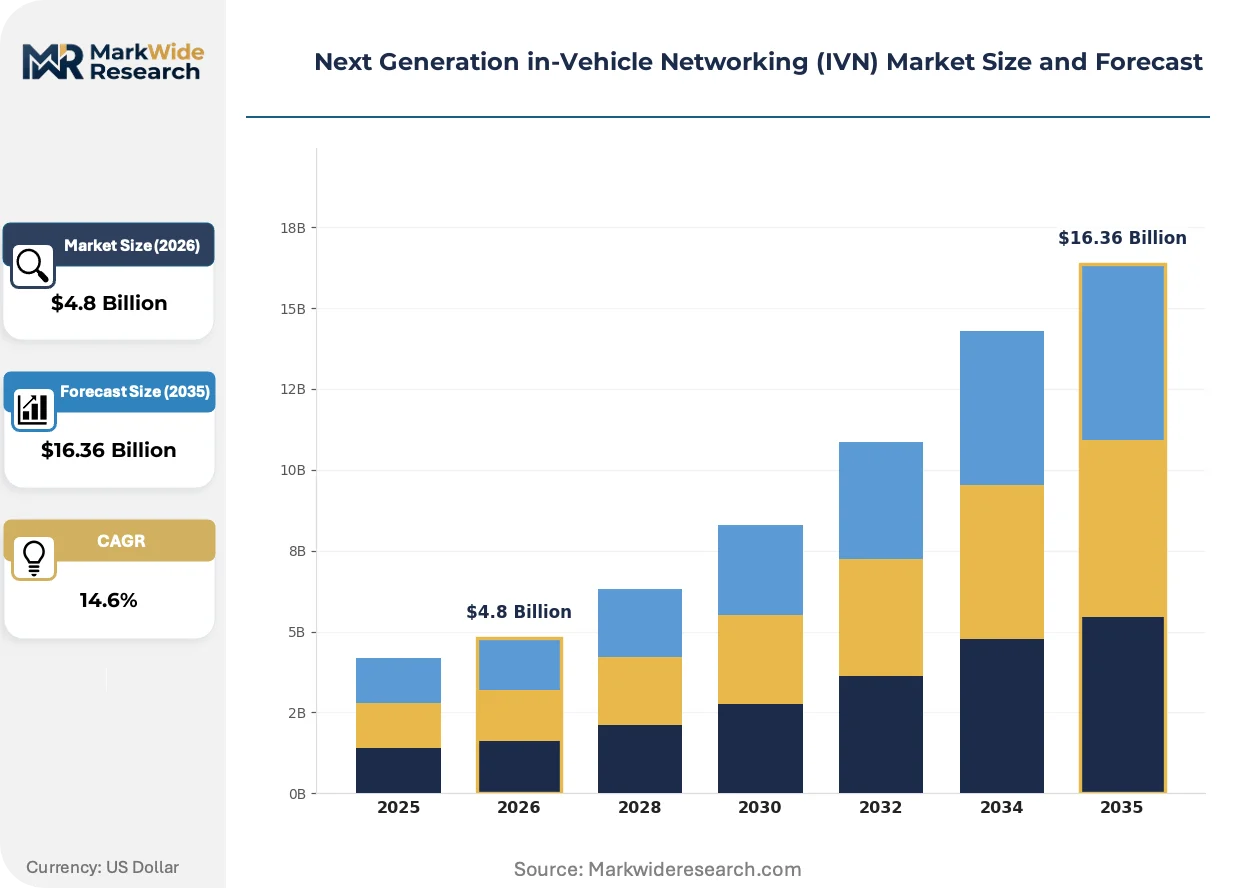
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethernet, CAN, LIN, FlexRay Technology: Wired, Wireless, V2X, Cloud-Based Application: Driver Assistance, Infotainment, Autonomous Driving, Telematics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Robert Bosch GmbH, Continental AG, NXP Semiconductors, Broadcom Inc., Infineon Technologies, Analog Devices, Renesas Electronics Corporation, Denso Corporation, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation in-Vehicle Networking (IVN) Market Emerging Trajectories
Protocol convergence between IEEE standards and proprietary OEM implementations is reshaping how semiconductor vendors architect transceiver silicon for deterministic automotive networks.
Multi-gigabit automotive Ethernet is collapsing the traditional separation between powertrain and infotainment network domains. OEMs adopting zonal architectures now route all vehicle data through unified Ethernet backbones. This convergence is compressing the addressable market for legacy CAN-FD transceivers while expanding switch port density requirements.
NHTSA cybersecurity guidelines now require intrusion detection systems in all new connected vehicles. The mandate forces gateway controller suppliers to embed deep packet inspection at line rate. Heavy-duty truck and commercial fleet segments face the steepest compliance costs due to longer vehicle lifecycles requiring sustained security patch support.
Buyer concentration among German and Japanese OEMs is squeezing tier-2 semiconductor distributors from gateway procurement channels. Direct supplier-OEM engineering relationships now dominate switch silicon selection. This channel consolidation is most visible in Stuttgart and Tokyo, where consolidated purchasing offices negotiate multi-platform supply agreements spanning five-year vehicle generation cycles.
Next Generation in-Vehicle Networking (IVN) Market Segmentation
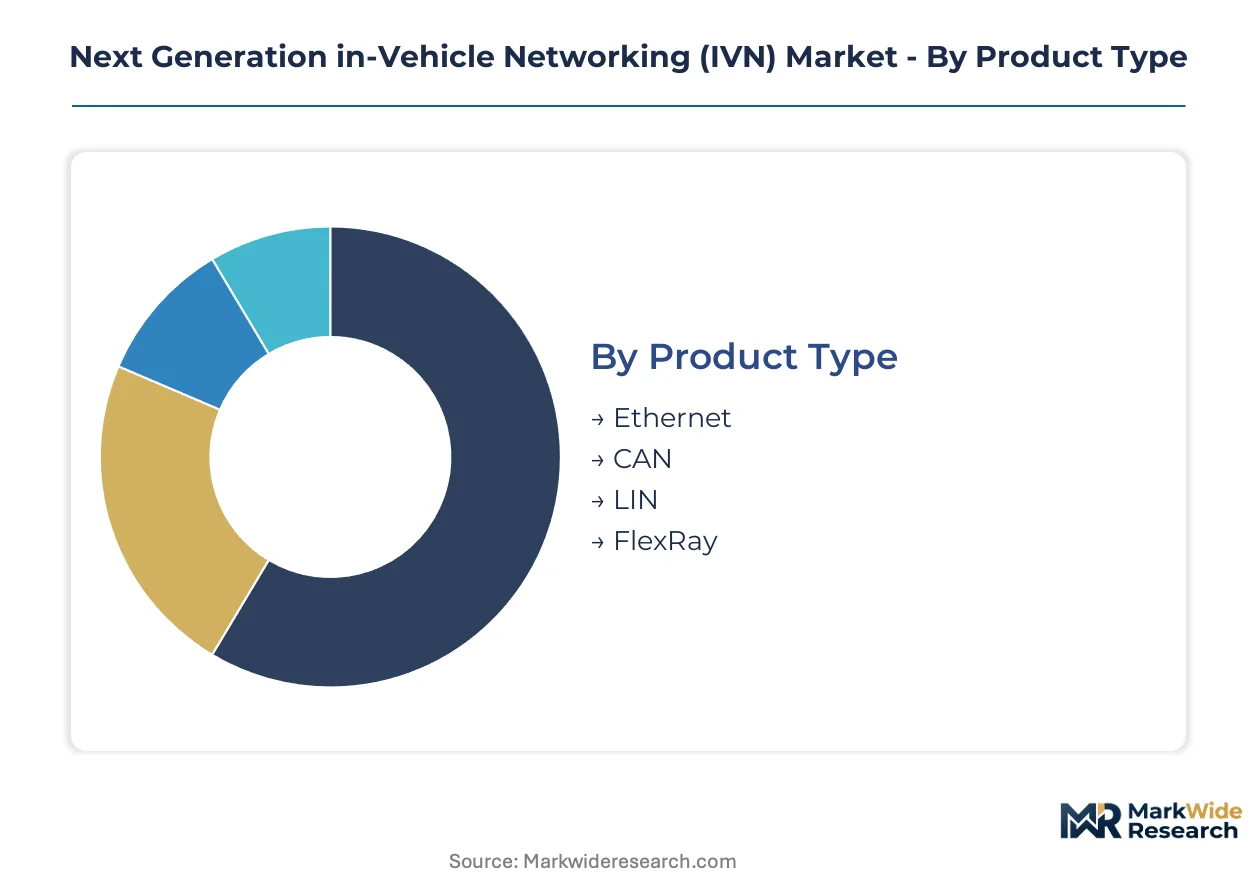
Segmentation in the Next Generation in-Vehicle Networking market reveals divergent refresh cycles across protocol layers and stakeholder types. Semiconductor procurement patterns vary dramatically between safety-critical domains requiring ISO 26262 recertification and infotainment subsystems with annual feature updates.
Product Type:
Ethernet transceivers turn over fastest as bandwidth requirements escalate with each autonomous driving level, while LIN controllers persist longest in body electronics where cost minimization dominates design cycles.
- Ethernet:Multi-gigabit automotive Ethernet PHYs deliver deterministic sub-five-millisecond latency through IEEE 802.1 Time-Sensitive Networking. Demand concentrates in German OEM zonal architectures where sensor fusion pipelines aggregate LiDAR and camera streams at central compute nodes.
- CAN:CAN XL extends the legacy bus protocol to 10 Mbps while preserving physical layer compatibility with decades of installed vehicle fleets. European powertrain applications in Stuttgart engineering clusters anchor procurement volumes despite Ethernet encroachment.
- LIN:Low-cost single-wire protocol for door modules, seat controls, and lighting subnetworks where 20 kbps bandwidth suffices.
- FlexRay:Deterministic time-triggered protocol retaining niche presence in chassis control systems requiring sub-microsecond synchronization.
Ethernet anchors the volume base while CAN XL gains share at the steepest rate as OEMs bridge legacy and next-generation architectures.
Technology:
Cost tiers separate physical layer implementations from edge-compute connectivity solutions, with wireless modules commanding premium pricing against copper-based alternatives.
- Wired:Shielded twisted-pair and optical fiber backbones dominate zonal gateway interconnections where electromagnetic immunity is non-negotiable.
- Wireless:Deterministic wireless links for in-cabin device pairing and diagnostic access points. Fleet operator demand in commercial vehicle segments accelerates deployment of cellular-V2X and DSRC convergence solutions for platooning coordination.
- V2X:Vehicle-to-everything communication enabling real-time hazard warnings and traffic signal prioritization through roadside unit integration.
- Cloud-Based:Over-the-air update channels and remote diagnostic pipelines bypass traditional tier-2 tool suppliers through OEM-direct software distribution infrastructure.
Wired technology retains the dominant cost tier position while cloud-based connectivity climbs the fastest as software-defined vehicle architectures mature.
Application:
Functional safety requirements create margin stratification, with ASIL-D certified domains supporting pricing premiums against QM-rated infotainment systems.
- Driver Assistance:ADAS sensor networks requiring deterministic latency for emergency braking and lane-keeping assistance.
- Infotainment:High-resolution display backbones and audio streaming networks where bandwidth demands scale with screen pixel counts.
- Autonomous Driving:Redundant multi-gigabit Ethernet rings for LiDAR point cloud transmission and AI inference input staging. German engineering clusters in Munich and Stuttgart drive protocol standardization for these safety-critical pipelines.
- Telematics:Cellular modem integration for stolen vehicle tracking, usage-based insurance, and predictive maintenance alerting.
Driver assistance anchors the volume base while autonomous driving gains share at the steepest rate as Level 3+ deployments expand.
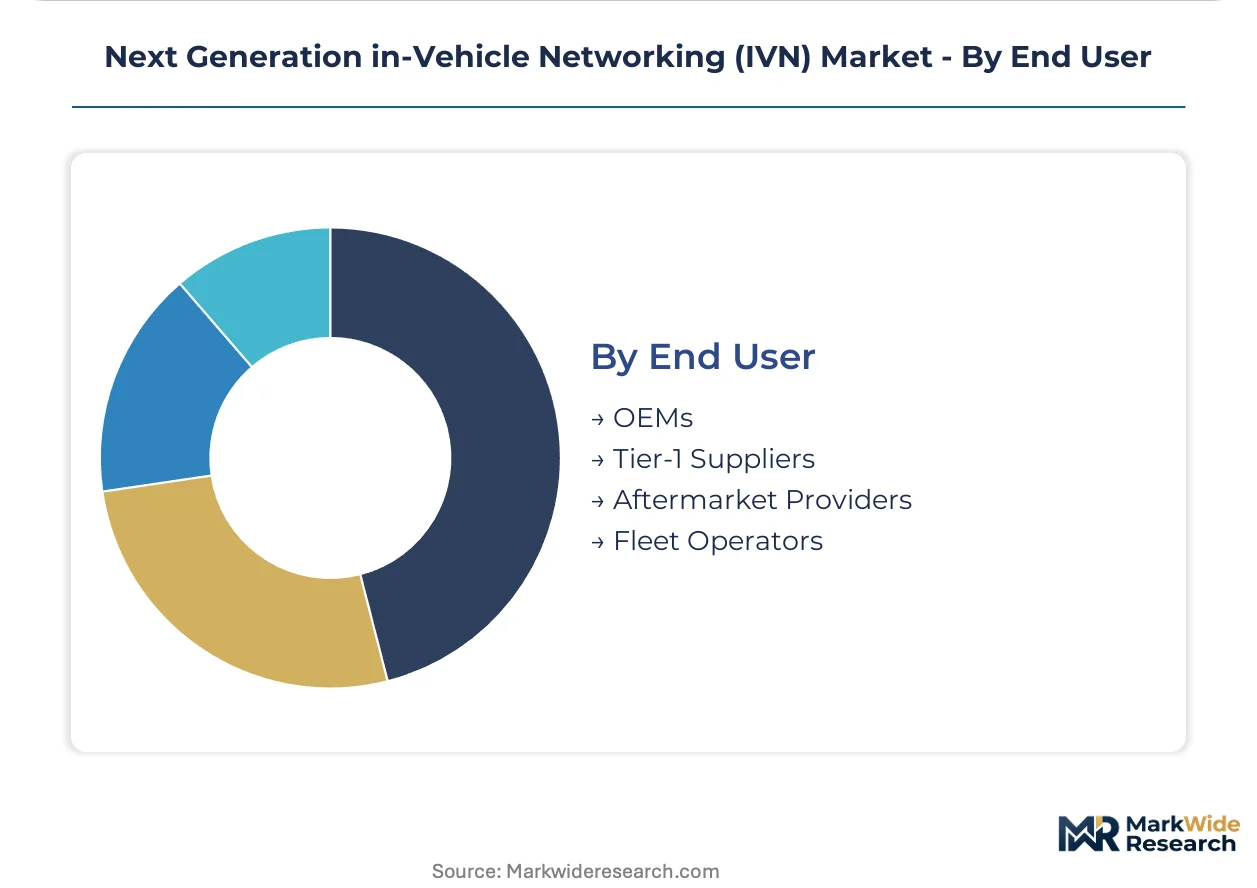
End User:
Customer type determines procurement channel structure, with consolidated OEM purchasing offices squeezing tier-2 distributors through direct supplier relationships.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz negotiate multi-platform supply agreements spanning five-year vehicle generation cycles through consolidated Stuttgart and Munich purchasing offices.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG leverage gateway controller integration expertise to capture switch silicon selection authority.
- Aftermarket Providers:Diagnostic tool and retrofit connectivity vendors face narrowing service revenue as OEMs restrict third-party network access through software-defined vehicle architectures.
- Fleet Operators:Commercial vehicle and heavy-duty truck segments requiring sustained security patch support across decade-long lifecycles under NHTSA cybersecurity guidelines.
OEMs anchor the volume base while fleet operators gain share at the steepest rate as connected commercial vehicle mandates expand across North America and Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany demonstrate the lowest price elasticity for IVN components, absorbing ASIL-D certification premiums without volume reduction. Chinese OEMs exhibit the highest sensitivity, driving aggressive localization mandates for switch silicon procurement. Japanese buyers occupy the middle tier, prioritizing supplier longevity over per-unit cost minimization.
United States
NHTSA cybersecurity guidelines mandate intrusion detection systems in all new connected vehicles, compelling gateway controller redesigns. The IRA's domestic semiconductor production incentives accelerate foundry investments in Arizona and Texas. Detroit's engineering clusters anchor zonal architecture procurement for Ford and General Motors.
Germany
The EU Cyber Resilience Act mandates hardware security modules in connected vehicle components, forcing PHY layer encryption integration. Stuttgart and Munich engineering clusters drive IEEE 802.1 Time-Sensitive Networking protocol standardization. Mercedes-Benz and BMW procurement offices negotiate five-year multi-platform supply agreements from consolidated purchasing hubs.
China
GB/T vehicle network security standards mandate encrypted in-vehicle communication, creating regulatory tailwind for hardware security module vendors. MIIT's autonomous driving roadmap accelerates multi-gigabit Ethernet deployment for LiDAR fusion pipelines. Shanghai and Beijing anchor domestic switch silicon design centers serving BYD and NIO.
Japan
METI's connected vehicle infrastructure program funds V2X roadside unit deployment for cellular-V2X convergence. Toyota and Honda procurement patterns prioritize supplier relationship continuity over aggressive cost reduction. Nagoya and Tokyo engineering clusters specialize in deterministic wireless link certification for platooning coordination.
South Korea
MFDS automotive cybersecurity guidelines align with global ISO/SAE 21434 standards, harmonizing export compliance for domestic suppliers. Hyundai and Kia's zonal architecture adoption drives demand for high-port-density switch silicon. Seoul Capital Area fabs anchor domestic automotive Ethernet PHY production for captive supply integration.
Next Generation in-Vehicle Networking (IVN) Market Vendor Landscape
Diversified automotive conglomerates and specialized semiconductor suppliers split the market along integration depth lines. Tier-1 system integrators leverage gateway controller expertise to capture switch silicon selection authority. Three strategic archetypes dominate: vertically integrated automotive suppliers, fabless semiconductor specialists, and diversified electronics conglomerates. Competitive moves concentrate on strategic partnerships for protocol certification and backward integration into captive foundry capacity.
Within the diversified automotive supplier tier, Robert Bosch GmbH and Continental AG exemplify gateway controller integration expertise. Among fabless semiconductor specialists, NXP Semiconductors occupies a position representing automotive Ethernet PHY portfolio concentration. Infineon Technologies anchors the power-network interface specialization archetype through silicon carbide integration capabilities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| NXP Semiconductors |
| Broadcom Inc. |
| Infineon Technologies |
| Analog Devices |
| Renesas Electronics Corporation |
| Denso Corporation |
| Texas Instruments |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in Taiwan is compressing automotive Ethernet PHY lead times and emboldening tier-1 suppliers to extract volume-commitment premiums from German OEM procurement offices. This utilization squeeze simultaneously inflates input costs for switch silicon vendors and reinforces direct supplier-OEM contracting over distributor channels.
Pricing Analysis
After-sales service revenue from security patch subscriptions and over-the-air update infrastructure now exceeds hardware margins in lifetime value calculations for gateway controller suppliers. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and QM-rated economy levels separates safety-critical autonomous driving pipelines from infotainment backbones. Cost compression in entry-level Ethernet PHYs is intensifying because Chinese OEMs are driving aggressive localization mandates. Fleet operators demonstrate the lowest price sensitivity, absorbing certification premiums for decade-long security support, while Chinese OEMs exhibit the highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for automotive semiconductor procurement. Taiwan, South Korea, and Germany anchor foundry and packaging capacity for multi-gigabit transceivers, while silicon carbide substrates draw from limited 150mm wafer supply concentrated in Japan and the United States. Single-source switch silicon vulnerability persists because automotive Ethernet PHY production rests on three foundry-dependent vendors. Distribution runs through direct OEM engineering relationships that bypass traditional tier-2 distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cyber Resilience Act and NHTSA cybersecurity guidelines together constitute a regulatory inflection that is accelerating hardware security module adoption faster than silicon vendors can recertify production lines. This compliance compression creates asymmetric advantage for pre-certified incumbents.
For Market Incumbents: Build certification moats around ISO 26262 ASIL-D Ethernet switch platforms before 18-24 month validation cycles lock out competitors. Secure captive foundry capacity in Taiwan and South Korea through multi-year wafer agreements. Defend against fabless entrants by controlling gateway controller integration authority. For New Entrants and Emerging Players: China's domestic switch silicon design centers in Shanghai and Beijing represent underpenetration zones where GB/T security standards favor local hardware security module vendors. Target commercial fleet telematics segments where NHTSA patch-support mandates exceed incumbent service capacity. Pursue cellular-V2X roadside infrastructure partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive Ethernet PHY production as 800G process nodes require advanced packaging investments. Fabless semiconductor specialists with existing IEEE 802.1 TSN certification pipelines represent the optimal acquisition archetype. Monitor zonal architecture procurement announcements from Stuttgart and Munich OEM offices as the signal for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Integration | EU Cyber Resilience Act mandates PHY-layer encryption for all connected vehicle components by tier-1 suppliers. |
| IEEE 802.1 TSN Certification | German engineering clusters in Stuttgart anchor protocol standardization for deterministic sub-five-millisecond latency. |
| Silicon Carbide Gateway Integration | Infineon's power-network interface specialization reduces thermal losses at zonal distribution nodes. |
| Cellular-V2X Roadside Partnership | METI's connected vehicle infrastructure program funds edge compute node deployment across Japanese highways. |
| Over-the-Air Update Infrastructure | OEM-direct software distribution bypasses traditional tier-2 diagnostic tool suppliers in aftermarket channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with OEM platform engineers, tier-1 supplier procurement directors, semiconductor foundry planners, and aftermarket diagnostic tool vendors. Secondary validation drew from NHTSA regulatory filings, EU Cyber Resilience Act implementation guidance, GB/T vehicle network security standards documentation, and IHS Markit vehicle production databases. Bottom-up bill-of-materials analysis across zonal E/E architectures was triangulated against top-down OEM procurement budget disclosures.
Calibration against historical adoption curves for CAN-FD and Ethernet in automotive applications anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include protocol type, functional safety certification tier, vehicle propulsion architecture, and regional regulatory cluster. CAGRs were derived from compound growth trajectory fitting against OEM platform launch timelines. Content-per-vehicle escalations for autonomous driving levels and security module penetration rates served as primary forecast inputs.
Practitioners should monitor foundry capacity utilization reports, IEEE 802.1 TSN interoperability certification timelines, and zonal architecture procurement announcements from German OEM offices for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
V2X Communication Module Market