
 North America Automotive Infotainment System Market | 2026-2036
North America Automotive Infotainment System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Infotainment System Market Analytics
The capability gap between semiconductor-owning platform developers and hardware-assemblers is rotating competitive investment toward in-house silicon design. Harman International leverages its Samsung parentage to sustain vertical integration across chip-to-cockpit stacks. Continental AG anchors its position through manufacturing scale in Mexican assembly plants serving Detroit Three customers.
North America automotive infotainment systems integrate computing platforms, display modules, audio processors, and wireless transceivers into centralized electronic architectures governing navigation, entertainment, and vehicle settings. These systems typically operate on 12-volt vehicle electrical architectures with transition to 48-volt mild-hybrid platforms enabling higher-resolution displays and faster processing. Connectivity Systems command margin pools as automakers monetize subscription-based over-the-air update revenue streams. Voice Recognition technology differentiates premium offerings as drivers demand hands-free control compliant with NHTSA distraction guidelines.
NHTSA guidelines shape interface design mandates limiting manual task duration while FCC spectrum allocations determine cellular-V2X deployment timelines across the United States. Transport Canada coordinates with U.S. regulators on cross-border cybersecurity standards for connected vehicle platforms. Stakeholders must monitor divergence between EPA fleet electrification timelines and infotainment power-draw budgets as battery-electric architectures redefine thermal and electrical constraints on cabin electronics.
Market Dynamics
The 48-volt electrical architecture migration is compressing development cycles for cockpit electronics suppliers, forcing simultaneous hardware redesigns across display, audio, and processing subsystems while NHTSA distraction guidelines harden interface requirements.
Growth Catalysts
- EPA fuel-economy tracking mandates:Automakers embed real-time efficiency displays and predictive navigation routing as standard features, expanding screen real estate and processing requirements across vehicle lineups.
- Cellular-V2X spectrum allocation:FCC rulings on 5.9 GHz band usage enable vehicle-to-infrastructure communication modules, creating integrated infotainment-telecom hardware demand for traffic optimization and safety alerts.
- Southern California design clusters:UX talent concentration around Los Angeles and San Diego accelerates human-machine interface iteration cycles, compressing time-to-market for gesture and voice control systems.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance system chip foundries in Taiwan constrain allocation for infotainment processors, creating procurement bottlenecks for Detroit Three automakers.
- Lithium-ion battery thermal budgets:Electric vehicle battery management systems prioritize range preservation, limiting cabin electronics power draw and display brightness specifications.
- NHTSA distraction-mitigation compliance costs:Interface task-duration testing and documentation requirements extend validation timelines, inflating engineering overhead for multi-function screen designs.
Strategic Opportunities
- Canadian cold-climate testing infrastructure:Northern Ontario and Manitoba facilities enable year-round validation of touchscreen responsiveness and voice recognition performance in sub-zero conditions.
- Over-the-air update monetization:Subscription revenue models for navigation map refreshes, streaming service integration, and feature unlocks create recurring income streams beyond initial hardware sales.
- Voice-recognition and head-up display convergence:Combined hands-free control and windshield-projected information reduce driver gaze diversion, satisfying both safety regulators and premium buyer preferences.
Industry Challenges
- Embedded software engineering scarcity:Automotive-grade Linux and QNX operating system specialists command premium compensation, constraining supplier scaling in the U.S. Midwest manufacturing corridor.
- Cross-platform integration complexity:Harmonizing Apple CarPlay, Android Auto, and proprietary automaker interfaces within unified hardware architectures demands extensive compatibility testing.
- Cybersecurity certification timelines:Transport Canada and NHTSA coordinated standards for connected vehicle data protection require encryption protocol validation that extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Infotainment System Market |
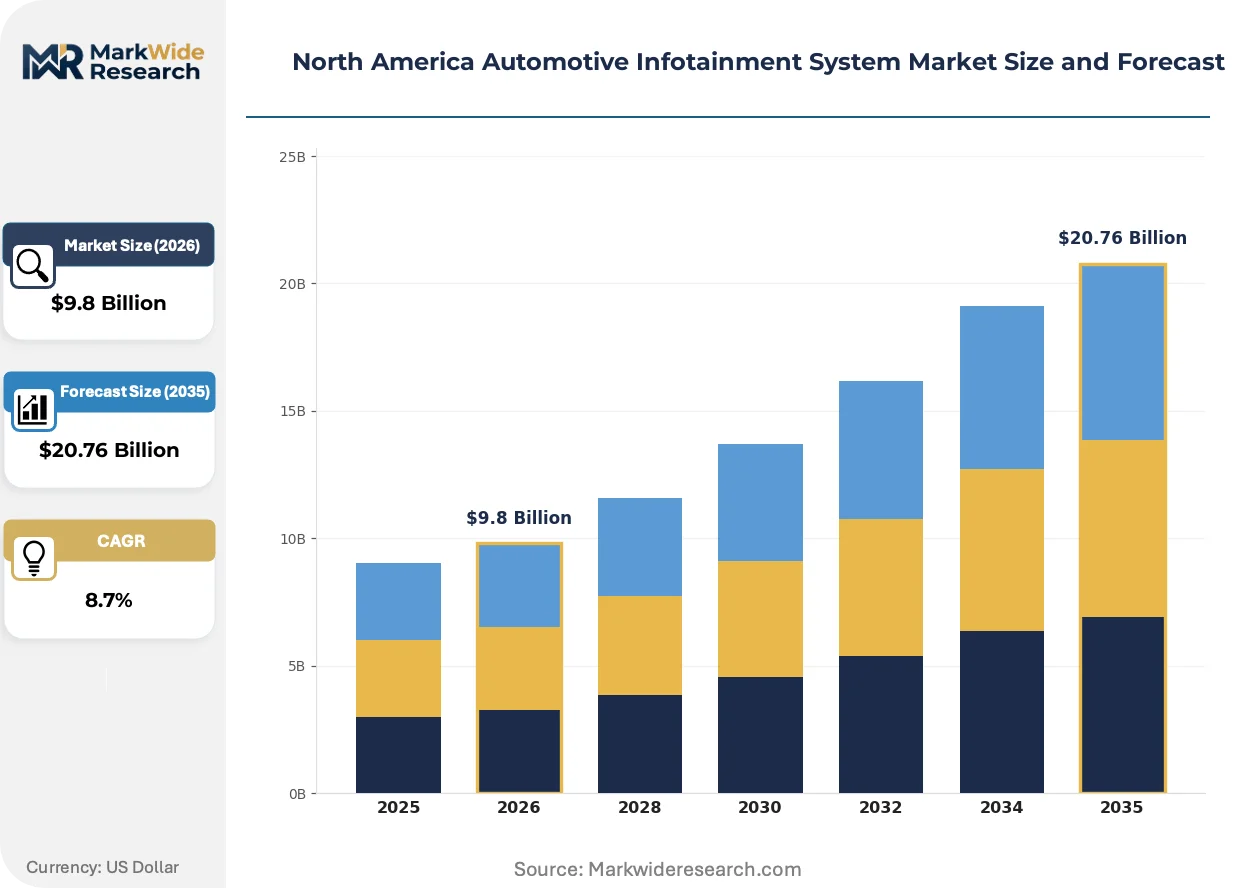
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Audio Systems, Video Systems, Connectivity Systems Technology: Touchscreen, Voice Recognition, Gesture Control, Cloud Connectivity End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Harman International, Continental AG, Denso Corporation, Bosch, Panasonic Corporation, Alpine Electronics, Delphi Technologies, Visteon Corporation, Pioneer Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Infotainment System Market Evolving Landscape
Software-defined vehicle architectures are decoupling hardware refresh cycles from feature deployment, enabling function upgrades through cloud-connected platforms rather than physical component replacement.
Organic light-emitting diode display technology is supplanting traditional thin-film transistor liquid crystal panels in premium vehicle segments. BMW and Mercedes-Benz configurations now specify curved OLED surfaces exceeding 14 inches diagonal. This transition compresses supply chain margins for legacy display assemblers while elevating content value per vehicle for panel-integrated controller suppliers.
NHTSA distraction-mitigation guidelines are hardening into de facto design mandates across the United States. The administration's visual-manual task-duration limits now shape touchscreen menu hierarchies and voice-command grammar structures. Tier-1 suppliers in Michigan and Ontario have restructured human-factors engineering teams to embed compliance testing within initial concept phases rather than post-design validation.
Fleet procurement patterns among rental and commercial operators are compressing replacement cycles for infotainment hardware. Enterprise buyers now specify modular head-unit designs permitting field-swappable connectivity modules rather than full-system replacement. This specification shift concentrates in Florida and Arizona fleet management hubs where vehicle utilization rates drive faster technology obsolescence.
North America Automotive Infotainment System Market Segmentation
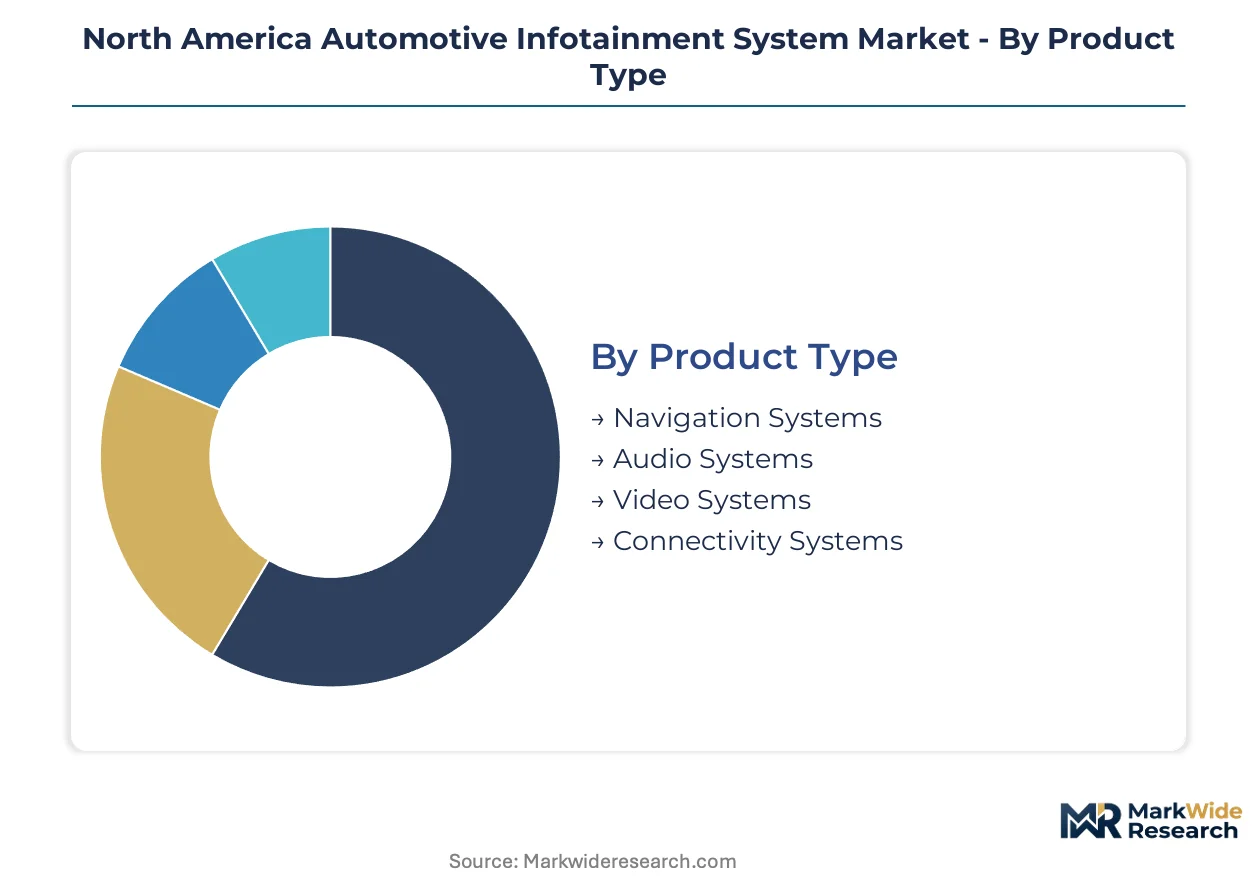
Automotive infotainment segmentation reveals how hardware specifications, interface modalities, and supply chain positions determine margin capture across North American vehicle production. Channel alignment between OEM direct procurement and aftermarket distribution shapes competitive positioning for each segment category.
Product Type:
Channel flows split between OEM factory-installed systems and aftermarket retrofit units, with connectivity modules increasingly bundled through subscription revenue models rather than standalone hardware sales.
- Navigation Systems:GPS-enabled positioning platforms integrate real-time traffic data and predictive routing algorithms. Demand concentrates in Michigan and Ohio assembly plants where EPA fuel-economy tracking mandates require efficiency-optimized route guidance as standard equipment.
- Audio Systems:Multi-channel amplifiers and speaker arrays process high-fidelity digital streams. Southern California design clusters drive specification upgrades as premium brands compete on acoustic performance differentiation.
- Video Systems:Rear-seat entertainment screens and dashboard displays process multimedia content through centralized vehicle networks.
- Connectivity Systems:Cellular and Wi-Fi transceivers enable over-the-air software updates and streaming service integration.
By volume, Audio Systems leads. By growth pace, Connectivity Systems is expanding most quickly.
Technology:
Cost tiering separates premium multi-modal interfaces from standard single-input systems, with price points clustering around processing power requirements and sensor integration complexity.
- Touchscreen:Capacitive and resistive display panels process haptic inputs across menu hierarchies. NHTSA distraction-mitigation guidelines limit task-duration tolerances, compressing interface design cycles for suppliers in Ontario and Michigan.
- Voice Recognition:Natural language processors execute hands-free commands through embedded or cloud-connected architectures. Canadian cold-climate testing infrastructure validates performance in sub-zero conditions where microphone sensitivity degrades.
- Gesture Control:Infrared and camera-based sensors interpret hand movements for non-contact interface operation.
- Cloud Connectivity:Persistent cellular links enable real-time data synchronization and remote feature activation.
Touchscreen dominates unit shipments. Cloud Connectivity commands the steepest expansion trajectory as automakers monetize subscription services.
End User:
Customer type determines specification authority, with OEMs retaining design control over embedded systems while aftermarket providers target replacement cycles and upgrade pathways.
- OEMs:Vehicle manufacturers specify integrated cockpit electronics through direct supplier relationships. Detroit Three procurement patterns concentrate volume in the U.S. Midwest manufacturing corridor.
- Tier-1 Suppliers:Component integrators assemble subsystems for factory installation. Mexican assembly plants anchor Continental AG's manufacturing scale for regional customers.
- Aftermarket Providers:Independent distributors serve replacement and upgrade demand outside factory warranty periods.
- Vehicle Assemblers:Contract manufacturers integrate infotainment modules during final vehicle assembly.
OEMs capture the largest revenue share. Aftermarket Providers are gaining share fastest as fleet operators specify modular field-swappable designs.
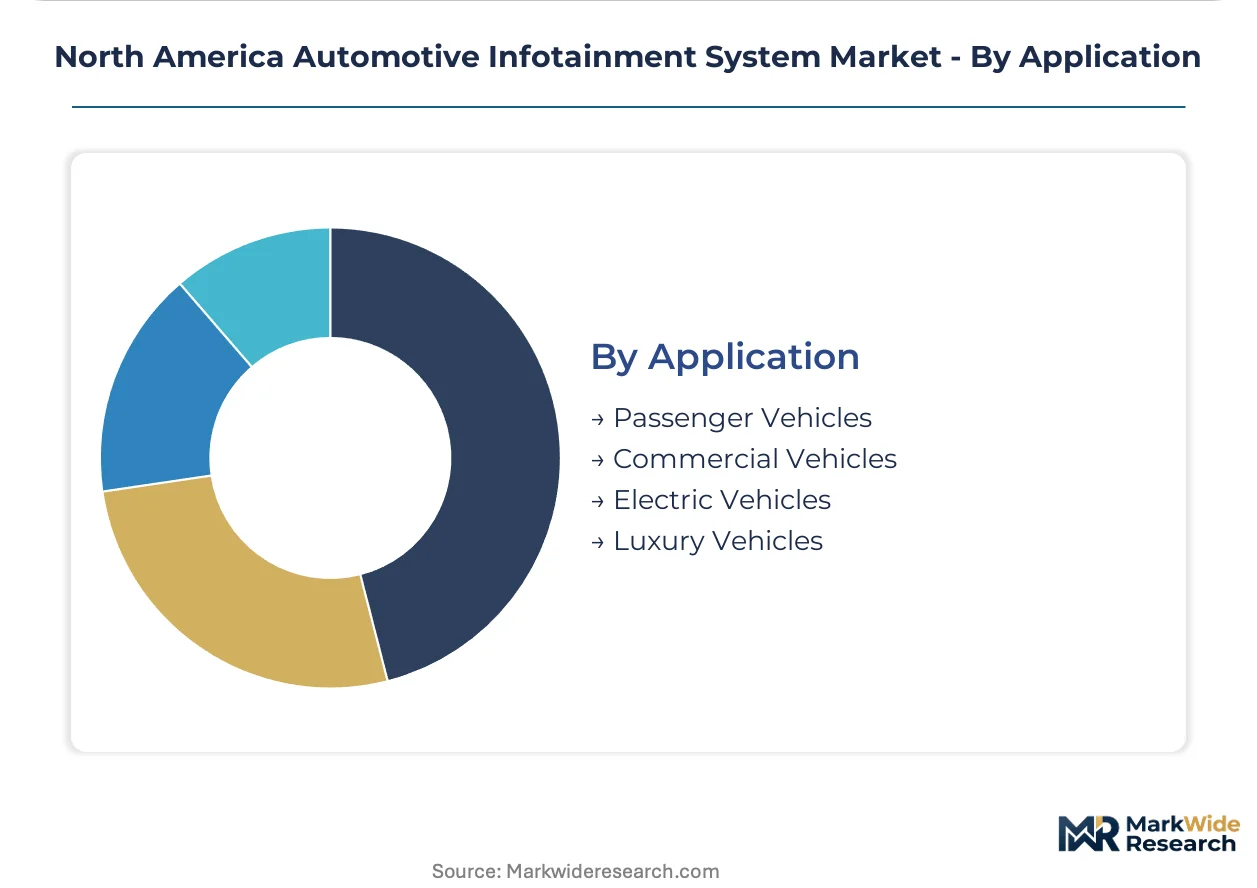
Application:
Application segmentation aligns with vehicle electrification trajectories and thermal budget constraints that reshape power-draw specifications for cabin electronics.
- Passenger Vehicles:Light-duty consumer automobiles integrate full-featured infotainment suites. California and Texas registration volumes drive specification clustering around smartphone mirroring and streaming integration.
- Commercial Vehicles:Fleet-operated trucks and vans prioritize durability and standardized interfaces. Florida and Arizona fleet hubs compress replacement cycles through high-utilization patterns.
- Electric Vehicles:Battery-electric architectures impose strict thermal and electrical constraints on display brightness and processing loads.
- Luxury Vehicles:Premium segments specify curved OLED surfaces and multi-modal control systems exceeding 14 inches diagonal.
Passenger Vehicles leads by installed base. Electric Vehicles shows the fastest climb as EPA fleet electrification timelines accelerate hardware redesigns for 48-volt and high-voltage architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in automotive infotainment hardware tilt toward import dependency for finished systems, with the United States and Canada sourcing substantial volumes from Mexican assembly plants and Asian component suppliers to balance domestic production gaps.
United States
EPA fuel-economy tracking mandates and NHTSA distraction-mitigation guidelines drive embedded connectivity and voice-recognition specifications across vehicle lineups. FCC spectrum allocations on the 5.9 GHz band enable cellular-V2X module integration for traffic optimization. Southern California tech-design clusters around Los Angeles and San Diego accelerate human-machine interface iteration cycles for gesture and voice control systems.
Canada
Transport Canada coordinates cross-border cybersecurity standards with NHTSA for connected vehicle platforms, creating regulatory alignment that smooths integrated system deployment. Cold-climate validation infrastructure in Northern Ontario and Manitoba enables year-round testing of touchscreen responsiveness and voice recognition in sub-zero conditions. Ontario's manufacturing corridor anchors Continental AG and other Tier-1 suppliers serving Detroit Three customers.
Mexico
Assembly plant scale in Mexican border states supports just-in-time delivery schedules for U.S. Midwest automotive manufacturing corridors. Mexican facilities concentrate on hardware integration and final system assembly rather than semiconductor or display panel fabrication. Nuevo León and Baja California production hubs leverage proximity to Texas and California distribution networks for reduced logistics costs.
North America Automotive Infotainment System Market Competitive Landscape
Concentration sits with diversified electronics conglomerates that span semiconductor ownership through final system integration. The vendor base organizes around three strategic archetypes: platform developers with captive silicon design capabilities, hardware assemblers scaling through manufacturing footprint, and specialized audio-visual component suppliers. Competitive moves cluster on backward integration into chip design and strategic partnerships for 48-volt electrical architecture compatibility.
Within the platform-developer tier, Harman International and Denso Corporation exemplify archetypes that combine upstream semiconductor access with downstream cockpit integration. Continental AG occupies a position representing manufacturing-scale assemblers anchored in regional production geography. Bosch and Panasonic Corporation sit within the diversified conglomerate category, their breadth spanning adjacent automotive electronics segments that share procurement and validation infrastructure with infotainment divisions.
| Leading Market Players |
|---|
| Harman International |
| Continental AG |
| Denso Corporation |
| Bosch |
| Panasonic Corporation |
| Alpine Electronics |
| Delphi Technologies |
| Visteon Corporation |
| Pioneer Electronics |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between Detroit Three automakers and Tier 1 suppliers lock in semiconductor allocation priority while fixing component pricing across multi-year vehicle platform cycles. These arrangements embed NHTSA compliance testing costs upfront, transferring regulatory validation risk from assemblers to subsystem integrators.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing for connectivity modules, with automakers monetizing over-the-air updates through recurring revenue streams rather than transactional hardware sales. Price differentiation rests on processing tier and display resolution, with curved OLED configurations commanding substantial premiums over thin-film transistor liquid crystal alternatives. Cost compression in standard audio systems is intensifying because Mexican assembly plants optimize labor arbitrage for Detroit Three volume contracts. Fleet operators exhibit highest price sensitivity, negotiating modular field-swappable designs that minimize total cost of ownership across compressed replacement cycles.
Supply Chain Analysis
Just-in-time inventory preferences dominate final vehicle assembly, yet strategic stockpiling of display panels and audio processors buffers against Taiwan semiconductor foundry allocation constraints. Geographic supply concentration centers on Taiwan for advanced processors, South Korea for OLED display substrates, and Mexico for hardware integration and final system assembly. Raw material dependencies include silicon wafers, rare-earth magnets for speaker arrays, and lithium compounds for battery-backed memory modules. Single-source vulnerability in Taiwan semiconductor fabrication creates procurement bottlenecks for voice-recognition chipsets. Distribution runs through direct OEM procurement channels with aftermarket providers serving replacement demand through independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around NHTSA distraction-mitigation guidelines creates substantial switching costs for automakers, embedding incumbent Tier 1 suppliers within validated supply chains that resist rapid displacement.
For Market Incumbents: Shield market position through captive silicon design capabilities that reduce dependency on Taiwan foundry allocation, while expanding cold-climate validation infrastructure in Northern Ontario to differentiate voice-recognition performance. Prioritize backward integration into display panel controller production as OLED technology supplants legacy formats, compressing margins for pure-play assemblers. For New Entrants and Emerging Players: Lead with cloud-connected feature activation platforms targeting aftermarket fleet operators in Florida and Arizona, where high-utilization patterns compress replacement cycles and modular designs gain specification traction. White-space opportunity concentrates in subscription-based navigation map refreshes and streaming service integration, segments where recurring revenue models offset lower initial hardware margins. For Investors and Strategic Acquirers: Capital is best deployed toward platform developers with captive semiconductor access and established NHTSA validation records, archetypes that capture margin pools as software-defined architectures decouple hardware refresh cycles from feature deployment. Long-term viability hinges on 48-volt electrical architecture compatibility and cross-platform integration capabilities spanning Apple CarPlay, Android Auto, and proprietary automaker interfaces. Signal to monitor: Transport Canada cybersecurity certification timelines, where acceleration would compress launch schedules and favor incumbent suppliers with established encryption protocol validation.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables feature upgrades through cloud-connected platforms without physical component replacement. |
| Battery Supply Agreement | Secures lithium-ion allocation for electric vehicle infotainment thermal budget compliance. |
| Geographic Manufacturing Footprint | Mexican assembly plants anchor just-in-time delivery for U.S. Midwest automotive corridors. |
| Platform Standardization | Harmonizes multi-modal interfaces across vehicle lineups to reduce NHTSA validation overhead. |
| Charging Infrastructure Partnership | Integrates infotainment-telecom hardware for vehicle-to-infrastructure communication modules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC automotive supplier filings, NHTSA regulatory dockets, and vehicle production databases. Primary interviews engaged Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers across Michigan, Ontario, and Northern Mexico. Secondary validation drew from EPA fuel-economy compliance records, FCC spectrum allocation rulings, and Transport Canada cybersecurity coordination documents. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive registration data.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs were derived from production volume trajectories and content-per-vehicle escalation curves. Industry-specific forecast inputs include 48-volt electrical architecture migration timelines and EPA fleet electrification schedules reshaping thermal and power-draw specifications.
Forecasts assume regulatory continuity in NHTSA distraction-mitigation guidelines and Transport Canada cybersecurity standards; material policy shifts would require re-modeling interface design mandates and encryption protocol requirements. Specific risks that could revise projections include Taiwan semiconductor supply disruption, lithium-ion battery thermal budget tightening, and divergence between EPA electrification timelines and infotainment power-draw constraints. Revision becomes warranted when cellular-V2X spectrum allocation rulings cross deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Commercial Vehicle Telematics Market