
 V2X Communication Module Market | 2026-2036
V2X Communication Module Market Size, Share, and Industry Trends Forecast 2026-2036
V2X Communication Module Market Analytics
Chinese module foundries are repositioning capacity toward automotive-grade chip packaging to serve the surge in V2X orders. Qualcomm leverages its Snapdragon Automotive platform to dominate cellular-V2X silicon design. NXP Semiconductors anchors European supply through its dedicated secure element portfolio for DSRC and C-V2X protocols. Autotalks specializes in dual-mode chipsets that bridge legacy and next-generation vehicle networks.
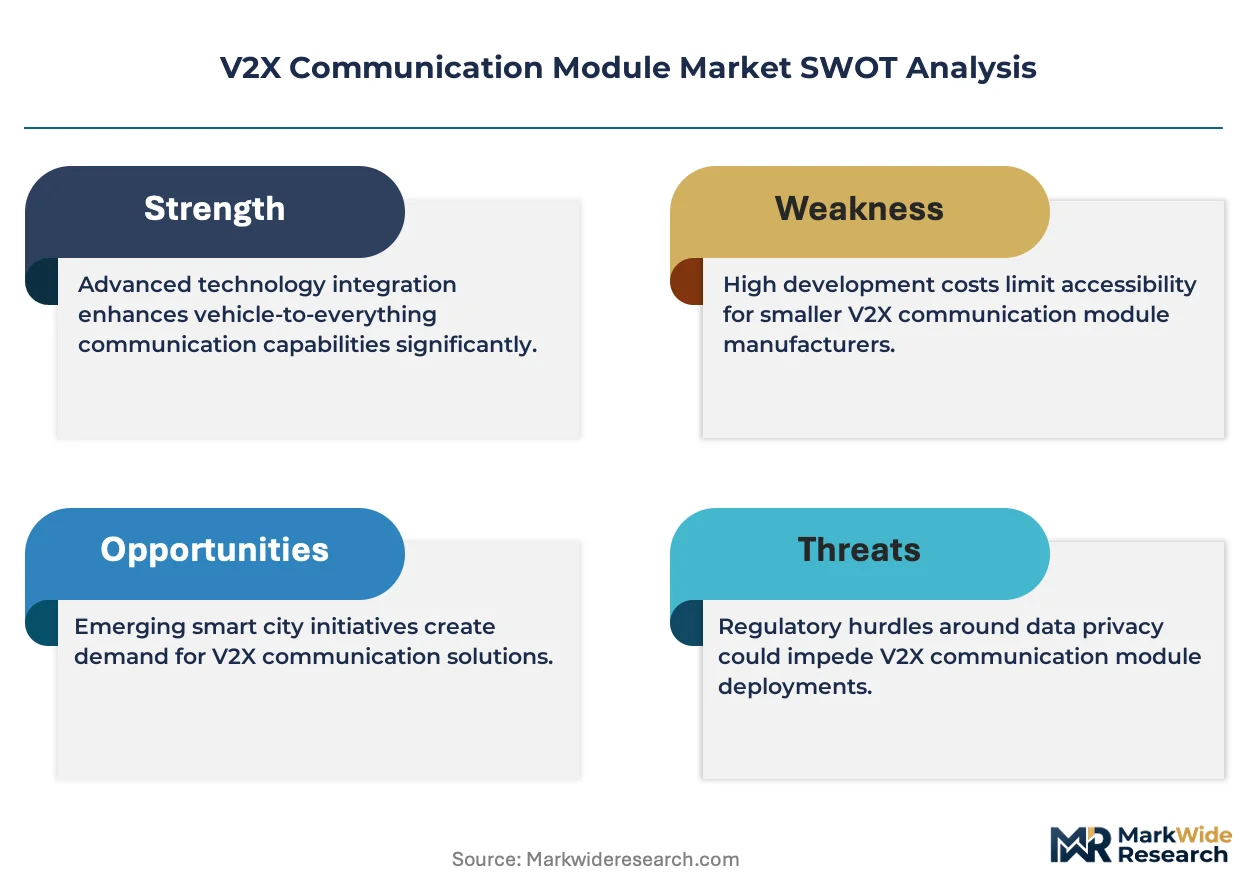
A V2X Communication Module is a radio-frequency transceiver assembly operating in the 5.9 GHz ITS band or licensed cellular spectrum, incorporating hardware security modules, antenna diversity systems, and protocol stacks compliant with IEEE 802.11p or 3GPP Release 14+ specifications; its purpose is to enable real-time data exchange between vehicles, infrastructure, pedestrians, and cloud networks for cooperative intelligent transport. DSRC-based installations retain cost advantages for low-latency safety applications, while 5G-V2X modules capture the fastest expansion trajectory due to their integration with autonomous driving sensor fusion architectures. Onboard Units constitute the dominant installation category, though Integrated Systems are displacing standalone modules as OEMs embed V2X capability directly into domain controllers.
The US NHTSA and FCC jointly shape V2X demand through spectrum allocation rulings and proposed mandate timelines for vehicle-to-vehicle communication. Europe's ETSI and CE marking frameworks enforce interoperability standards that determine market access for module suppliers. China's MIIT issues GB standards for connected-vehicle radio equipment that foreign vendors must satisfy for domestic OEM qualification. Stakeholders must monitor regulatory divergence between DSRC-preferring jurisdictions and C-V2X-mandating markets to avoid stranded technology investments.
Market Dynamics
The V2X Communication Module Market is bifurcating along protocol lines as DSRC-preferring safety regulators clash with C-V2X-mandating jurisdictions, forcing suppliers to engineer dual-mode architectures that absorb redundant certification costs.
Growth Catalysts
- FCC Spectrum Reallocation:The US FCC's 5.9 GHz band rulings are compelling module suppliers to redesign RF front-ends for coexistence with Wi-Fi 6E, accelerating hardware refresh cycles across the installed base.
- Fleet Telematics Integration:Commercial vehicle operators are mandating V2X capability in new procurements to qualify for insurance premium reductions and platooning efficiency gains.
- Cross-Border Harmonization:The EU's C-ITS roadmap alignment with US DOT guidance is reducing engineering fragmentation for suppliers serving transatlantic OEM programs.
Market Restraints
- Automotive-Grade Silicon Shortage:Foundry capacity constraints for AEC-Q100 qualified chip packaging are extending lead times for secure element modules beyond 26 weeks.
- Protocol Uncertainty:Divergent national mandates—DSRC in Japan versus C-V2X in China—are forcing suppliers to maintain dual inventory stocks and duplicate certification pipelines.
- Antenna Integration Complexity:Vehicle roofline redesigns for aerodynamic efficiency are compressing available mounting space for diversity antenna arrays, degrading link budget margins.
Strategic Opportunities
- Pedestrian Handset Integration:Smartphone OEMs are embedding V2X client stacks to enable vulnerable road user alerts, opening a consumer electronics channel parallel to automotive supply.
- Roadside Unit Retrofit Programs:Germany's federal highway operator is tendering DSRC-to-C-V2X migration contracts for 12,000 existing infrastructure endpoints.
- Sensor Fusion Convergence:Integration of V2X latency data with LiDAR point clouds is enabling predictive collision algorithms that reduce false-positive braking events.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-D qualification for V2X control paths requires 18-24 month validation cycles that delay platform launches.
- RF Coexistence Engineering:Mitigating interference between 5G-V2X and automotive radar in the 77-81 GHz band demands specialized anechoic chamber testing capacity that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | V2X Communication Module Market |
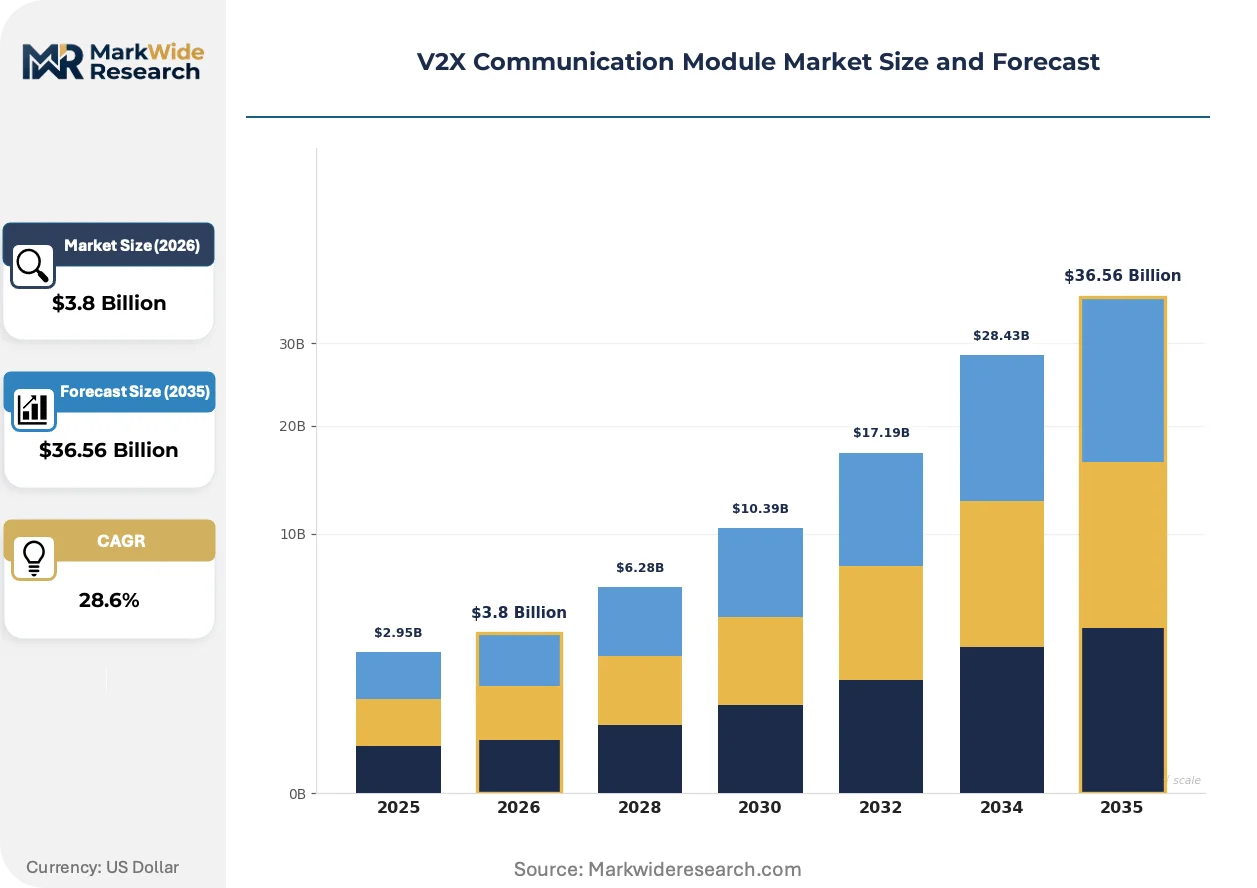
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: V2V, V2I, V2P, V2N Technology: Dedicated Short Range Communications, Cellular, 5G, Bluetooth End User: OEMs, Tier-1 Suppliers, Fleet Operators, Transportation Authorities Installation: Onboard Units, Roadside Units, Integrated Systems, Standalone Units |
| Companies Covered | Qualcomm, Huawei, NXP Semiconductors, Continental AG, Robert Bosch GmbH, Autotalks, Infineon Technologies AG, Aptiv, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
V2X Communication Module Market Evolving Landscape
Module architectures are compressing from discrete subsystems into software-defined radio platforms that reconfigure protocol stacks through firmware updates rather than hardware swaps.
Dual-mode chipsets supporting concurrent DSRC and C-V2X operation are modularizing the supplier base by decoupling RF transceiver design from baseband processing. Tier-1 integrators are adopting these unified platforms to reduce BOM line-item count and simplify vehicle-level electromagnetic compliance testing. The structural consequence is that standalone DSRC-only module vendors are modularizing into software licensors or exiting the market entirely.
The EU's F-Gas Regulation is tightening refrigerant containment standards for thermal management of V2X roadside units, forcing infrastructure suppliers to redesign sealed enclosures with predictive leak detection. Industrial consequence includes accelerated adoption of solid-state cooling alternatives to compressor-based systems. German and French tollway operators are most affected, specifying fanless designs in new procurement tenders to preempt compliance retrofit costs.
Automotive OEMs are unbundling V2X module sourcing from telematics control unit contracts, creating direct procurement relationships with semiconductor vendors that bypass traditional Tier-1 aggregators. This channel disintermediation is most visible in German premium vehicle programs, where engineering teams specify chip-level requirements and manage antenna integration in-house. The shift compresses supplier margins while accelerating iteration cycles for security patch deployment.
V2X Communication Module Market Segmentation
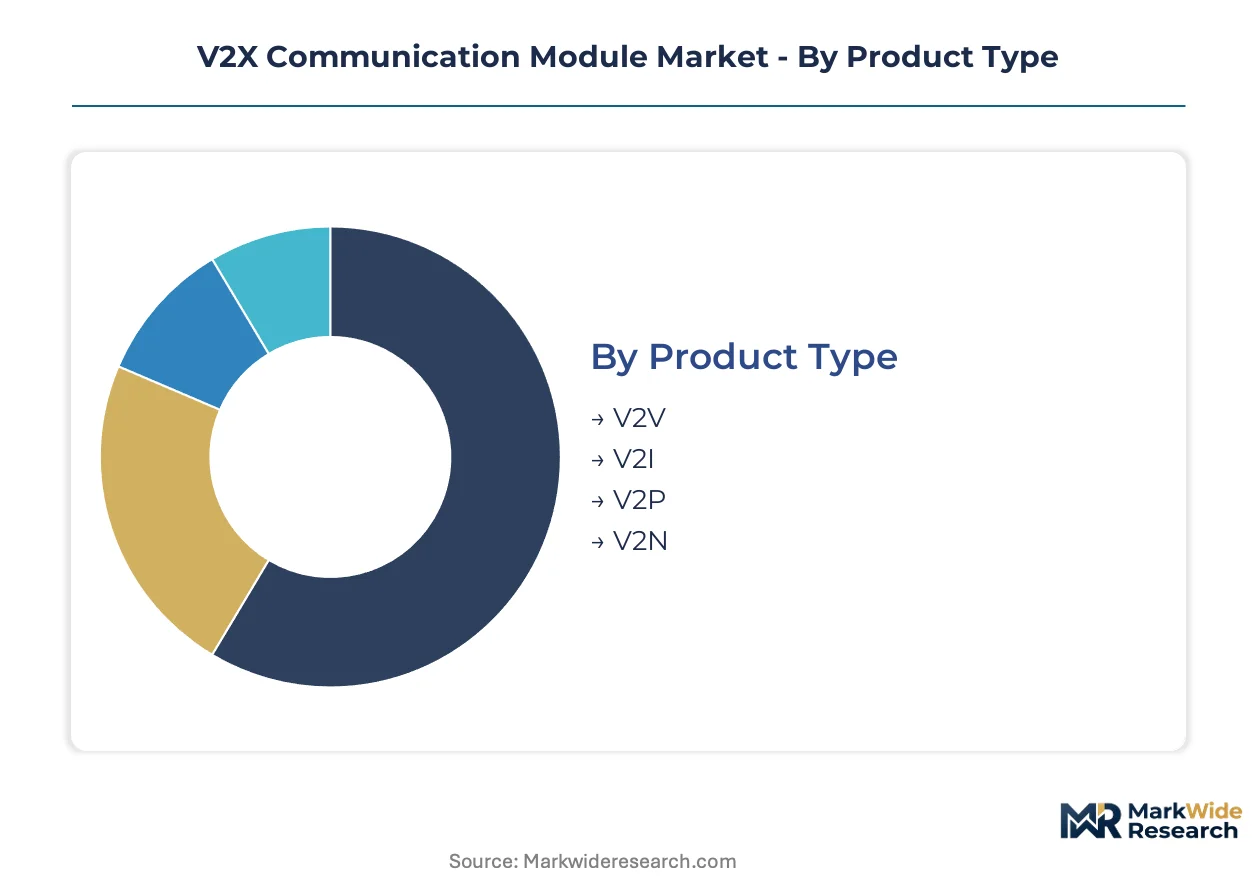
V2X Communication Module Market segmentation reveals how protocol diversity and installation preferences fragment procurement patterns across automotive and infrastructure channels. Understanding these divisions exposes where engineering investments concentrate and where margin pressure differentially affects supplier tiers.
Product Type:
Supply concentration tilts heavily toward vehicle-centric communication modes, with infrastructure and pedestrian-facing variants capturing residual manufacturing capacity.
- V2V:Vehicle-to-vehicle modules enable direct peer-to-peer exchange of position, velocity, and trajectory data without infrastructure mediation. German premium OEMs and Japanese safety regulators mandate this capability for collision avoidance systems, concentrating demand in markets with aggressive autonomy timelines.
- V2I:Vehicle-to-infrastructure modules connect mobile units with roadside units for signal phase timing and work zone alerts. US state DOT procurement programs in Michigan and Arizona are absorbing the bulk of deployment volume as federal highway funding flows toward smart corridor pilots.
- V2P:V2P modules broadcast to vulnerable road users carrying compatible handsets or wearables.
- V2N:V2N modules route data through cellular networks to cloud-based traffic management platforms.
V2V absorbs the bulk of installed capacity; V2N is expanding most quickly as 5G network slicing enables low-latency cloud connectivity.
Technology:
Cost tier stratification separates legacy safety-certified modules from premium cellular platforms commanding higher ASPs.
- Dedicated Short Range Communications:IEEE 802.11p-based modules operate in the 5.9 GHz ITS band with sub-50ms latency for time-critical safety applications. Japanese regulators and US NHTSA guidance sustain demand despite cellular encroachment, particularly for intersection collision warning systems.
- Cellular:C-V2X Release 14 modules leverage licensed spectrum for extended range and network-orchestrated services. Chinese MIIT mandates and European C-ITS roadmap alignment are accelerating procurement for connected highway corridors.
- 5G:5G-V2X modules integrate with autonomous driving compute platforms for sensor fusion and cooperative perception.
- Bluetooth:Bluetooth Low Energy modules serve short-range pedestrian detection and in-vehicle device pairing.
DSRC retains the largest installed base; 5G-V2X is climbing the fastest as OEMs integrate next-generation autonomous platforms.
End User:
Customer type determines contract structure, with direct OEM relationships displacing Tier-1 aggregation in premium vehicle programs.
- OEMs:Automotive manufacturers specify module requirements directly, managing antenna integration and software stack validation in-house. German and US premium brands are consolidating procurement to accelerate security patch deployment cycles.
- Tier-1 Suppliers:System integrators bundle V2X capability into telematics control units and domain controllers for mid-market vehicle platforms.
- Fleet Operators:Commercial vehicle procurement teams mandate V2X for insurance premium reductions and platooning efficiency.
- Transportation Authorities:Public agencies deploy roadside units for traffic signal coordination and incident management.
OEMs absorb the bulk of installed capacity; fleet operators are gaining share fastest as commercial procurement mandates proliferate.
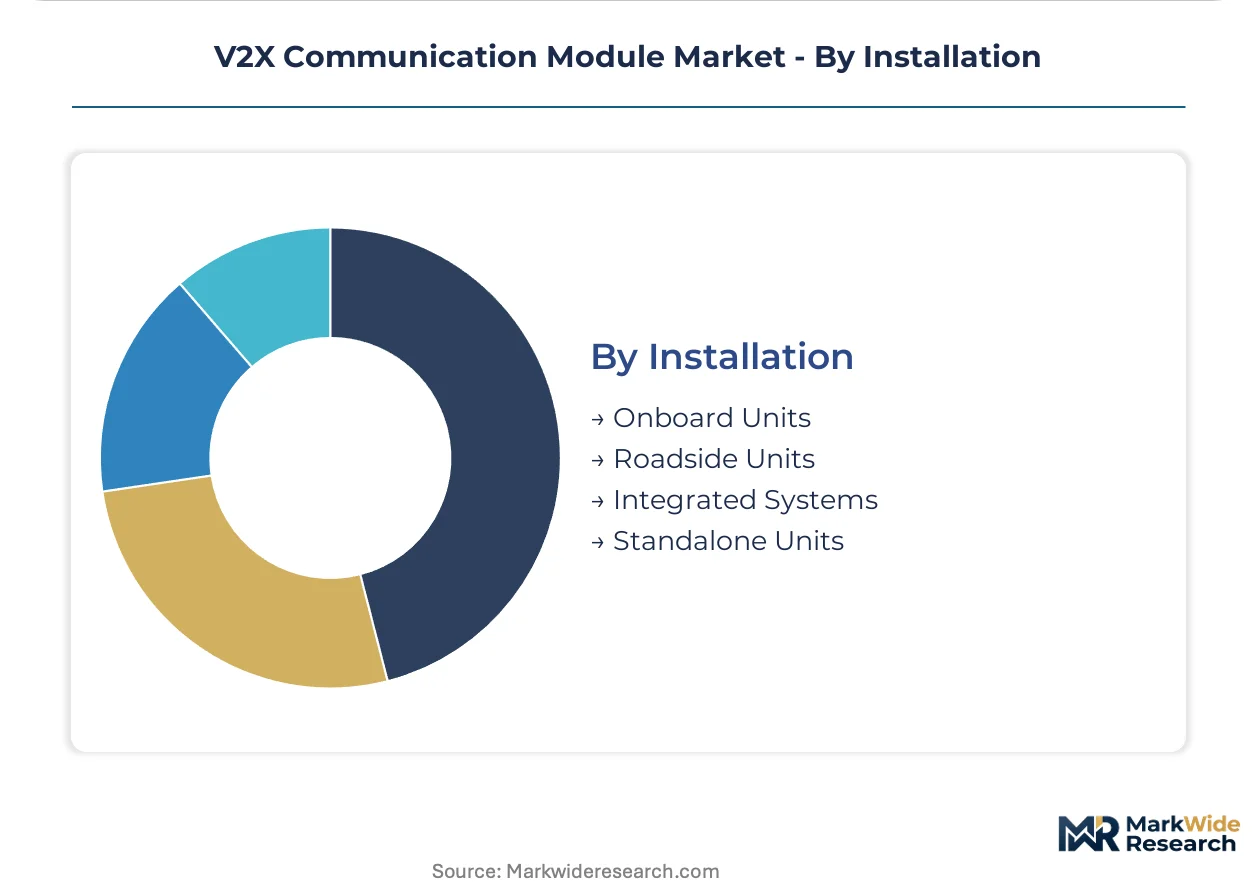
Installation:
Maturity differentiation separates legacy standalone hardware from integrated architectures displacing discrete module procurement.
- Onboard Units:Discrete vehicle-mounted transceivers with dedicated antenna arrays and hardened enclosures. Retrofit demand from commercial fleets and municipal transit operators sustains volume despite OEM integration trends.
- Integrated Systems:V2X capability embedded directly into domain controllers and central compute platforms. German premium OEMs are specifying chip-level procurement that bypasses traditional module suppliers entirely.
- Roadside Units:Infrastructure-mounted equipment for intersection and corridor deployment.
- Standalone Units:Aftermarket add-on devices for vehicle retrofit and pilot program evaluation.
Onboard Units retain the largest installed base; Integrated Systems are gaining share fastest as OEMs consolidate compute architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors V2X module supply chains, with automotive-grade packaging migrating toward Chinese and Southeast Asian facilities to serve regional OEM demand.
United States
NHTSA and FCC spectrum rulings drive DSRC-to-C-V2X migration timelines for vehicle safety mandates. The DOT's V2X deployment guidance channels federal highway funding toward smart corridor pilots in Michigan and Arizona. Detroit's automotive engineering clusters concentrate Tier-1 integration activity for domestic OEM programs.
Germany
Premium OEM procurement teams specify chip-level V2X requirements directly, bypassing traditional module aggregators. The EU's C-ITS roadmap and KBA type-approval frameworks enforce cross-border interoperability standards. Stuttgart and Munich anchor Continental and Bosch engineering centers for next-generation platform integration.
China
MIIT mandates for C-V2X equipment qualification accelerate domestic OEM adoption and foreign vendor localization requirements. GB standards for connected-vehicle radio equipment determine market access. Shanghai and Shenzhen foundries reposition capacity toward AEC-Q100 automotive packaging to serve surge in module orders.
Japan
METI and MLIT sustain DSRC preference for intersection collision warning systems despite global cellular migration. JIS standards and PSE certification maintain distinct regulatory pathways for module suppliers. Nagoya's automotive supplier belt concentrates Tier-1 integration for Toyota and Honda safety platforms.
South Korea
MFDS spectrum coordination and KSA certification align with global C-V2X trajectories for Hyundai-Kia autonomous driving timelines. Government-funded K-City testbeds validate module performance for export qualification. Seoul's Pangyo Techno Valley clusters semiconductor design houses for automotive RF development.
V2X Communication Module Market Competitive Landscape
Global majors compete with regional champions across protocol certification and automotive qualification timelines, producing a tiered structure where semiconductor vendors hold upstream leverage over system integrators. The vendor base stratifies between silicon designers, secure element specialists, and dual-mode platform engineers. Two dominant competitive moves define positioning: direct OEM procurement relationships that disintermediate Tier-1 aggregators, and dual-mode architecture investments that absorb redundant certification costs across DSRC and C-V2X jurisdictions.
Within the semiconductor archetype, Qualcomm, NXP Semiconductors, and Autotalks occupy positions spanning cellular baseband design, European secure element supply, and dual-mode protocol bridging respectively. Qualcomm represents the scale-driven cellular platform anchor. NXP exemplifies regional qualification depth for DSRC and C-V2X secure modules. Autotalks sits within the specialist tier addressing protocol transition risks.
| Leading Market Players |
|---|
| Qualcomm |
| Huawei |
| NXP Semiconductors |
| Continental AG |
| Robert Bosch GmbH |
| Autotalks |
| Infineon Technologies AG |
| Aptiv |
| Harman International |
| Others |
Value Network & Pricing Analysis
AEC-Q100 automotive-grade silicon wafer spot indices cascade through V2X module cost structures, compressing margins for DSRC-only suppliers while dual-mode chipset vendors capture pricing power through protocol-flexible architectures. Tier-1 integrators facing 26-week secure element lead times are unbundling module procurement from telematics contracts, forcing standalone vendors toward software-licensing models or exit.
Pricing Analysis
Warranty and firmware-update bundling separate premium-tier module suppliers from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade and antenna integration complexity. Price differentiation stems from ISO 26262 functional safety tier and geographic delivery logistics to German versus Chinese OEM programs. Cost compression in standard-tier DSRC modules is intensifying because Chinese foundries are repositioning capacity toward C-V2X orders. Fleet operators exhibit highest price sensitivity; German premium OEMs prioritize security patch velocity over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German and US OEMs require module suppliers to qualify Taiwanese and Chinese foundries simultaneously for automotive-grade packaging. Geographic supply concentration centers on Taiwan, China, and South Korea for RF transceiver fabrication and secure element assembly. Raw material dependencies include 5.9 GHz band RF front-end components, hardware security modules, and diversity antenna substrates. Single-source vulnerability in anechoic chamber testing capacity for 5G-V2X and radar coexistence certification creates bottleneck risk. Distribution runs through direct OEM procurement channels that disintermediate traditional Tier-1 aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU C-ITS roadmap and US FCC spectrum rulings erect regulatory moats favoring dual-mode certified suppliers over single-protocol specialists.
For Market Incumbents: Anchor dual-mode architecture investments to absorb redundant DSRC and C-V2X certification costs across jurisdictions. Deepen backward integration into secure element design to defend against Qualcomm's Snapdragon platform dominance. Prioritize direct OEM procurement relationships in Stuttgart and Munich engineering clusters to bypass margin compression from Tier-1 disintermediation. For New Entrants and Emerging Players: Begin with pedestrian handset V2X client stack development for smartphone OEMs, the least penetrated parallel channel to automotive supply. Target roadside unit retrofit programs in Germany's federal highway migration tenders as the most accessible infrastructure entry point. Pursue sensor fusion convergence partnerships with LiDAR vendors as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor dual-mode chipset specialists with existing KBA and MIIT type approvals in Germany and China. Long-term viability hinges on protocol-agnostic software-defined radio platforms that reconfigure through firmware rather than hardware swaps. Watch FCC final rulings on 5.9 GHz spectrum reallocation as the critical inflection signal for DSRC asset impairment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Chipset Platform Standardization | Enables Autotalks and NXP to serve both DSRC-preferring Japan and C-V2X-mandating China without duplicate inventory. |
| Automotive-Grade Foundry Capacity Expansion | Taiwanese and Chinese packaging facilities repositioning toward AEC-Q100 qualification reduce 26-week secure element lead times. |
| Direct OEM Procurement Channel Development | German premium brands bypassing Continental and Bosch aggregators accelerates security patch deployment cycles. |
| Roadside Unit Retrofit Program Execution | Germany's 12,000-unit DSRC-to-C-V2X migration tenders create immediate infrastructure revenue visibility. |
| Sensor Fusion Algorithm Partnership | Integration with LiDAR point clouds enables predictive collision systems that reduce false-positive braking events. |
Research Methodology
Multi-period observation of FCC spectrum rulings, MIIT mandate timelines, and EU C-ITS roadmap milestones anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, semiconductor foundry operations managers, and transportation authority technology officers. Secondary validation drew from NHTSA guidance documents, ETSI interoperability standards, GB certification databases, and vehicle production registration data. Bottom-up module shipment estimates triangulated against top-down automotive electronics spending forecasts.
Input-output matrices mapped V2V, V2I, V2P, and V2N segment volumes against DSRC, C-V2X, and 5G technology adoption curves across the projection horizon. Segmentation dimensions included protocol type, installation architecture, end-user category, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle acceleration, and autonomous driving platform integration timelines. Forecast inputs incorporated foundry capacity utilization rates and cross-border harmonization progress between US DOT and EU frameworks.
Protocol mandate reversals, foundry capacity constraints extending beyond current lead times, and autonomous driving timeline delays are the dominant revision risks. Deviation in FCC 5.9 GHz final rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Automotive Infotainment Market