
 Vehicle-To-Infrastructure (V2I) Communication Market | 2026-2036
Vehicle-To-Infrastructure (V2I) Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle-To-Infrastructure (V2I) Communication Market Analytics
The EU Green Deal's connected mobility mandates is recalibrating procurement priorities across European infrastructure tenders. Qualcomm Technologies anchors its position through chipset-level integration for roadside units. Continental AG competes on module specialization for traffic signal controllers. Robert Bosch GmbH extends its footprint through manufacturing scale in automotive-grade sensor fusion systems.
Vehicle-to-infrastructure communication denotes wireless data exchange between road vehicles and roadside equipment such as traffic signals, lane markers, and toll stations, typically operating at 5.9 GHz in DSRC or sub-6 GHz in C-V2X protocols to enable real-time hazard warnings and signal phase timing. Its primary purpose is to reduce collisions, optimize traffic flow, and support autonomous vehicle path planning through sub-100-millisecond latency requirements. Cellular V2X is gaining traction where 5G network density permits over-the-air updates and edge analytics, while Dedicated Short Range Communication retains dominance in legacy deployments where low infrastructure cost governs selection. Government Agencies represent the most concentrated end-user segment given their control of right-of-way and procurement budgets for intelligent transportation systems.
The U.S. Department of Transportation's Federal Highway Administration shapes deployment through V2I deployment guidance and funding corridors, while the European Commission's C-ITS framework mandates interoperability standards across member states. China's Ministry of Industry and Information Technology accelerates domestic C-V2X scale through GB standard certification and dual carbon-aligned smart city investments. Stakeholders must monitor spectrum allocation decisions at the FCC and MIIT, as these will determine whether DSRC or C-V2X becomes the de facto physical layer for next-generation roadside infrastructure procurement.
Market Dynamics
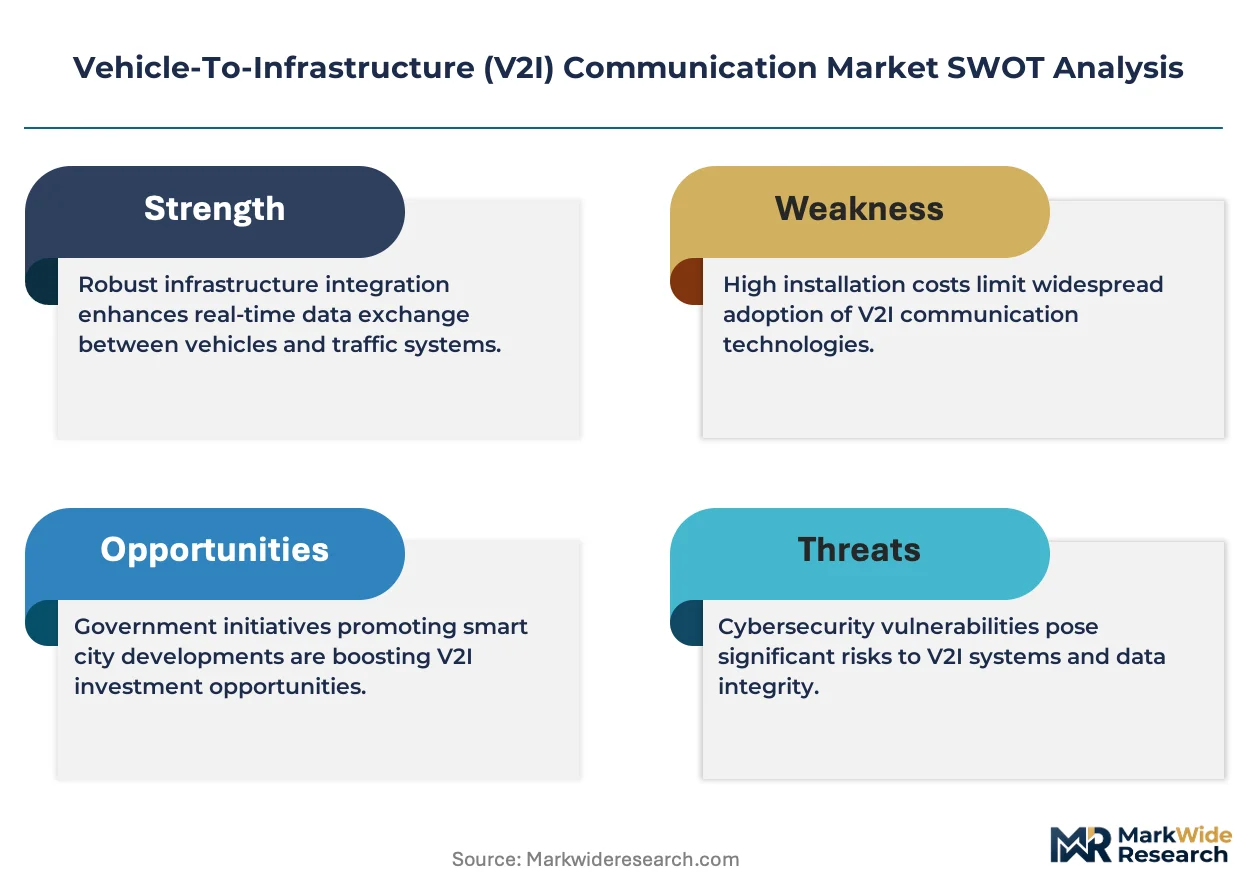
The V2I Communication Market is undergoing a fundamental protocol bifurcation as spectrum allocation decisions at the FCC and MIIT determine whether DSRC or C-V2X becomes the dominant physical layer for roadside infrastructure procurement.
Growth Catalysts
- EU C-ITS Framework Mandates:The European Commission's interoperability standards are compelling member states to synchronize cross-border V2I deployments along major freight corridors.
- China's Smart City Clusters:Municipal governments in Shenzhen and Suzhou are embedding C-V2X roadside units into dual carbon-aligned urban infrastructure tenders.
- 5G Network Density Expansion:Telecommunications infrastructure rollouts in Germany's automotive corridor are enabling edge analytics capabilities that DSRC cannot match.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for DSRC chipsets concentrates in East Asian foundries, exposing roadside unit manufacturers to geopolitical supply disruptions.
- Spectrum Auction Uncertainty:The FCC's pending 5.9 GHz reallocation proceedings are freezing procurement cycles among US municipal transit authorities awaiting regulatory clarity.
- Legacy Traffic Signal Integration:Existing traffic management systems deployed by state departments of transportation require costly hardware retrofits to achieve sub-100-millisecond latency thresholds.
Strategic Opportunities
- Autonomous Vehicle Corridors:Highway operators in the United States are piloting dedicated V2I lanes where C-V2X enables cooperative perception beyond line-of-sight sensor range.
- GB Standard Certification:China's Ministry of Industry and Information Technology certification pathway creates captive demand for domestic roadside unit vendors.
- Edge Computing Convergence:The integration of roadside units with municipal fiber networks and edge data centers is opening recurring revenue streams through traffic analytics subscriptions.
Industry Challenges
- Cross-Functional Engineering Talent:The intersection of telecommunications protocol expertise and civil infrastructure project management skills remains scarce among systems integrators.
- Multi-Stakeholder Deployment Coordination:Successful V2I rollouts require synchronized investment from departments of transportation, telecommunications carriers, and automotive OEMs with misaligned procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle-To-Infrastructure (V2I) Communication Market |
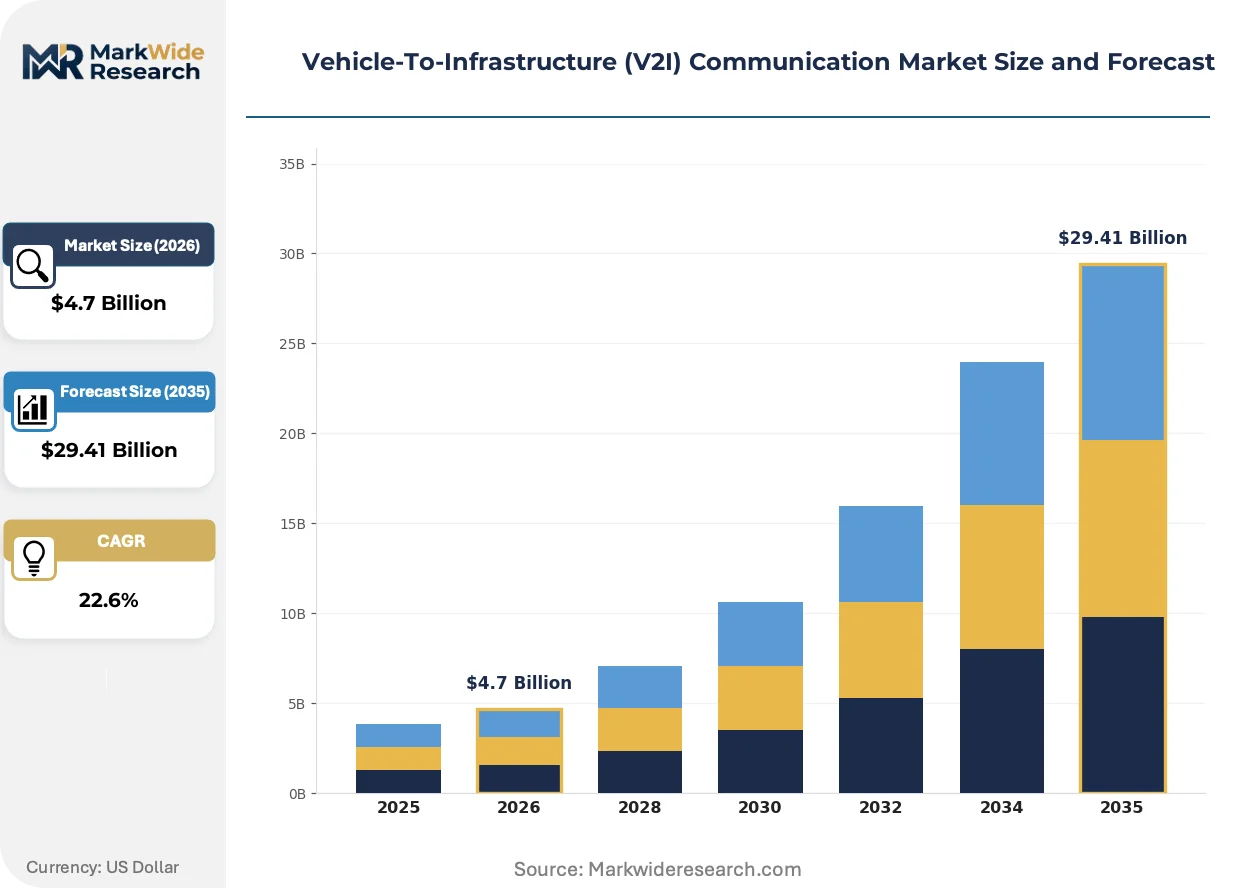
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Dedicated Short Range Communication, Cellular V2X, Wi-Fi, Satellite Communication Application: Traffic Management, Safety Notifications, Emergency Vehicle Assistance, Smart Parking End User: Government Agencies, Automotive Manufacturers, Infrastructure Developers, Fleet Operators Deployment Model: Cloud-Based, On-Premises, Hybrid Solution, Edge Computing |
| Companies Covered | Qualcomm Technologies, Continental AG, NXP Semiconductors, Denso Corporation, Robert Bosch GmbH, Savari Inc., Autotalks Ltd., Cohda Wireless, Kapsch TrafficCom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle-To-Infrastructure (V2I) Communication Market Evolving Landscape
Protocol standardization battles and edge computing architectures are actively restructuring how roadside infrastructure intelligence gets deployed and monetized across municipal networks.
Cellular V2X technology is unifying previously siloed transportation data streams by enabling direct vehicle-to-cloud communication without intermediary roadside processing. State departments of transportation in Michigan and Colorado are deploying C-V2X units at scale for real-time work zone warnings. This unification is compressing the traditional separation between traffic management centers and vehicle onboard systems into single integrated command layers.
The EU Green Deal's connected mobility mandates are recalibrating procurement specifications across European infrastructure tenders to prioritize carbon-footprint transparency in roadside unit manufacturing. Infrastructure operators must now document embodied emissions across semiconductor supply chains. German municipal authorities are responding by bundling V2I deployments with renewable energy-powered edge computing installations.
Municipal procurement patterns are fragmenting as city governments bypass state-level transportation departments to issue direct smart intersection contracts. Technology vendors are establishing municipal sales divisions that displace traditional channel relationships with regional systems integrators. This fragmentation is most pronounced in China's prefecture-level cities where local MIIT offices exercise independent certification authority over roadside unit deployments.
Vehicle-To-Infrastructure (V2I) Communication Market Segmentation
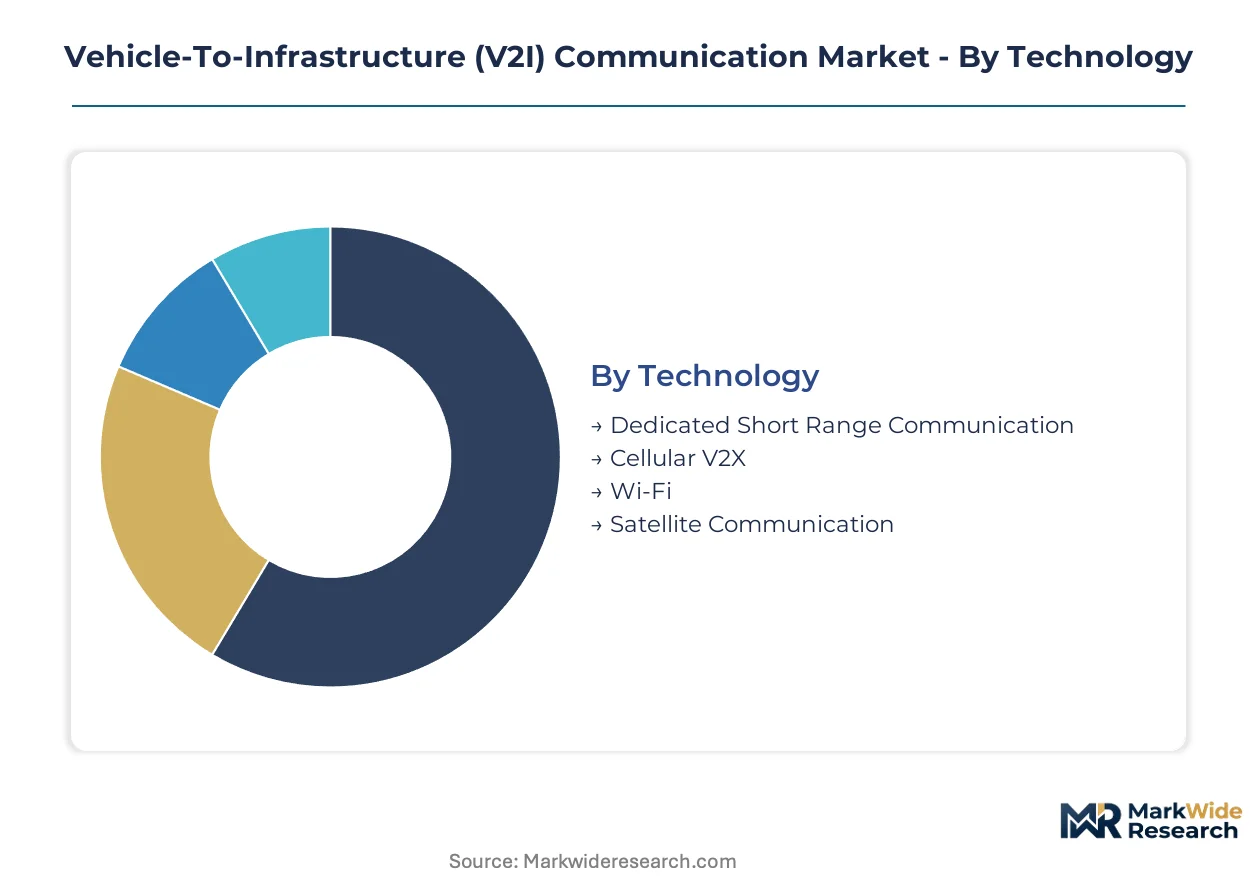
V2I procurement patterns diverge sharply across technology protocols and deployment architectures. Understanding these splits reveals where infrastructure budgets concentrate and which stakeholder groups drive specification requirements.
Technology:
Volume deployment favors legacy low-cost protocols, while premium positioning attaches to cellular-enabled systems with over-the-air upgrade capabilities.
- Dedicated Short Range Communication:Operates in the 5.9 GHz band with sub-50-millisecond latency for basic safety messaging. State departments of transportation in the United States favor DSRC for legacy intersection retrofits where minimal hardware cost governs selection.
- Cellular V2X:Leverages sub-6 GHz spectrum and 5G network density for edge analytics and cooperative perception. Germany's automotive corridor and China's Shenzhen cluster are embedding C-V2X into new smart city infrastructure where latency requirements exceed DSRC capabilities.
- Wi-Fi:Provides supplemental connectivity for indoor parking structures and enclosed transit hubs where cellular penetration degrades.
- Satellite Communication:Enables coverage in rural highway corridors lacking terrestrial infrastructure density.
Mature deployment sits with Dedicated Short Range Communication. Newer deployment is concentrated in Cellular V2X.
Application:
Safety-critical functions command procurement priority over convenience-oriented services in current municipal budgeting cycles.
- Traffic Management:Signal phase timing and congestion optimization through real-time vehicle flow data. China's Ministry of Industry and Information Technology mandates this capability in prefecture-level smart city tenders.
- Safety Notifications:Hazard warnings for work zones, icy conditions, and pedestrian crossings. The U.S. Department of Transportation's Federal Highway Administration prioritizes this application in funding corridor designations.
- Emergency Vehicle Assistance:Preemption signaling for ambulances and fire apparatus requiring dedicated bandwidth allocation.
- Smart Parking:Vacancy detection and automated payment integration in urban commercial districts.
Established deployment centers on Traffic Management. Accelerating deployment targets Safety Notifications.
End User:
Budget authority determines specification control, with public-sector procurement cycles running 18-36 months longer than private fleet decisions.
- Government Agencies:Departments of transportation and municipal transit authorities controlling right-of-way access and infrastructure budgets. The EU C-ITS framework compels interoperability investments across member state agencies.
- Automotive Manufacturers:OEMs pre-installing V2I modules to meet regulatory mandates and differentiate autonomous vehicle platforms.
- Infrastructure Developers:Private toll road operators and highway concession holders deploying cooperative perception systems.
- Fleet Operators:Logistics companies equipping commercial vehicles for platooning and predictive maintenance.
Procurement volume concentrates with Government Agencies. Technology specification influence is shifting toward Automotive Manufacturers.
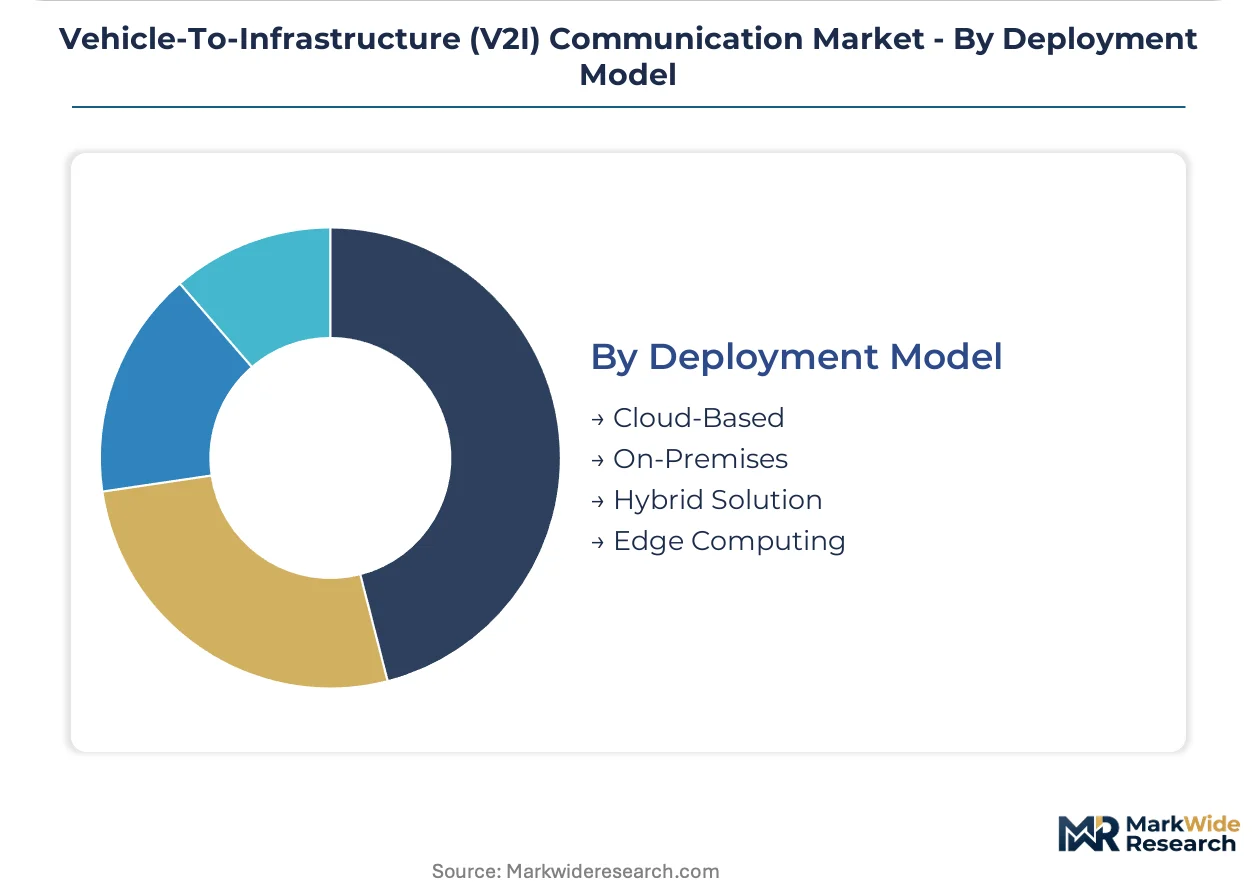
Deployment Model:
Latency requirements and data sovereignty concerns fragment architecture preferences across municipal and federal jurisdictions.
- Cloud-Based:Centralized processing enabling traffic analytics subscriptions and over-the-air firmware updates. German municipal authorities bundle this with renewable-powered edge installations under EU Green Deal procurement rules.
- On-Premises:Dedicated traffic management center servers satisfying data localization requirements in certain jurisdictions.
- Hybrid Solution:Split processing between roadside units and municipal data centers balancing latency and analytics depth.
- Edge Computing:Roadside unit-integrated processing achieving sub-100-millisecond response for autonomous vehicle path planning.
Legacy architecture persists in On-Premises installations. The steepest expansion trajectory belongs to Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian semiconductor foundries, while consumption clusters in German automotive corridors, Chinese smart city clusters, and US municipal transit authorities. This geographic split creates supply chain exposure for roadside unit manufacturers dependent on DSRC chipset fabrication. Regulatory fragmentation across spectrum allocation regimes further complicates cross-border deployment standardization.
United States
Municipal transit authorities in Michigan and Colorado are deploying C-V2X units for real-time work zone warnings. The FCC's pending 5.9 GHz reallocation proceedings are freezing procurement cycles among state departments of transportation awaiting regulatory clarity. The US Department of Transportation's Federal Highway Administration shapes deployment through V2I deployment guidance and funding corridor designations concentrated in the Midwest and Mountain West.
Germany
Telecommunications infrastructure rollouts in the automotive corridor are enabling edge analytics capabilities that DSRC cannot match. The EU C-ITS framework compels interoperability investments across member state agencies. Municipal authorities in Bavaria and Baden-Württemberg are bundling V2I deployments with renewable energy-powered edge computing installations under EU Green Deal procurement rules.
China
Municipal governments in Shenzhen and Suzhou are embedding C-V2X roadside units into dual carbon-aligned urban infrastructure tenders. The Ministry of Industry and Information Technology accelerates domestic C-V2X scale through GB standard certification. Prefecture-level cities exercise independent certification authority over roadside unit deployments, fragmenting procurement patterns across the Yangtze River Delta and Pearl River Delta clusters.
Japan
METI coordinates cross-ministry initiatives linking automotive OEMs with telecommunications carriers for C-V2X pilot programs. The country's national standards body mandates interoperability testing for imported roadside units. Industrial concentration in the Chubu region around Nagoya anchors supplier relationships between tier-1 automotive electronics manufacturers and domestic infrastructure developers.
South Korea
The Seoul Capital Area hosts government-funded testbeds for cooperative perception systems linking autonomous buses with traffic signal controllers. The national telecommunications regulator allocates dedicated spectrum for C-V2X deployment along the Busan-Ulsan freight corridor. Domestic semiconductor manufacturers supply chipsets for both domestic roadside unit production and export markets.
Vehicle-To-Infrastructure (V2I) Communication Market Competitive Landscape
The competitive structure tilts toward technology conglomerates with semiconductor fabrication capabilities and automotive tier-1 suppliers with established OEM relationships. Market concentration is moderate, with chipset specialists, module fabricators, and systems integrators occupying distinct functional layers. Two strategic archetypes dominate: semiconductor firms anchoring physical-layer supply and automotive suppliers controlling vehicle-side integration. Competitive moves center on strategic partnerships between telecommunications carriers and roadside unit manufacturers, plus portfolio diversification into edge analytics software.
Among semiconductor-focused players, Qualcomm Technologies exemplifies the chipset-integrated archetype through roadside unit component supply. Continental AG and Robert Bosch GmbH occupy positions within the automotive-tier supplier tier, leveraging manufacturing scale in sensor fusion systems. These three companies represent the dominant competitive positioning vectors: silicon-level integration, module specialization, and automotive-grade production scale.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Continental AG |
| NXP Semiconductors |
| Denso Corporation |
| Robert Bosch GmbH |
| Savari Inc. |
| Autotalks Ltd. |
| Cohda Wireless |
| Kapsch TrafficCom |
| Others |
Value Network & Pricing Analysis
Semiconductor fabrication costs for DSRC chipsets concentrate in East Asian foundries, cascading through three pricing tiers that separate automotive-grade roadside units from municipal retrofit kits and economy-grade signal controllers. This upstream concentration grants foundry operators outsized leverage over module fabricators bidding for state department of transportation contracts.
Pricing Analysis
Throughput-based pricing anchors municipal procurement decisions, with roadside unit vendors charging per-intersection licensing fees tied to vehicle-count analytics rather than hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates C-V2X edge-enabled systems from DSRC legacy hardware and unlicensed Wi-Fi supplements. Cost compression in the standard tier is intensifying because Chinese GB-certified vendors are undercutting European module specialists on volume tenders. Government agencies exhibit the highest price sensitivity due to 18-36 month budget cycles, while autonomous vehicle corridor operators prioritize latency performance over unit cost.
Supply Chain Analysis
5.9 GHz RF component supply rests on Taiwanese specialty semiconductor houses and South Korean memory fabricators, with packaging and testing concentrated in Malaysian facilities. Critical inputs include gallium nitride substrates for power amplifiers, automotive-grade MCUs from NXP and Renesas supply bases, and precision timing oscillators from Japanese manufacturers. Single-source vulnerability runs through the RF front-end segment where Qualcomm and Autotalks dominate chipset certification. Distribution runs through tier-1 automotive electronics distributors serving municipal systems integrators and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The V2I Communication Market sits at a protocol transition inflection, with Cellular V2X displacing Dedicated Short Range Communication wherever 5G network density permits edge analytics deployment.
For Market Incumbents: Anchor manufacturing scale in automotive-grade sensor fusion systems to defend against semiconductor firms encroaching on module assembly. Prioritize backward integration into RF front-end design to reduce dependency on Qualcomm's chipset roadmap. Secure certification pre-approvals under China's GB standards and the EU C-ITS framework to lock out late entrants from cross-border tender eligibility. For New Entrants and Emerging Players: Municipal sales divisions bypassing state transportation departments offer the most penetrable channel structure for direct smart intersection contracts. Target prefecture-level Chinese cities where local MIIT offices exercise independent procurement authority fragmented from provincial coordination. Lead with edge analytics software subscriptions bundled into roadside unit hardware to displace legacy traffic management center relationships. For Investors and Strategic Acquirers: FCC spectrum reallocation proceedings concluding in favor of C-V2X is the leading indicator that DSRC-dependent hardware portfolios face stranded asset risk. Long-term viability favors semiconductor-integrated platform vendors over pure-play roadside unit assemblers. Watch for GB standard certification announcements from domestic Chinese vendors as the signal for captive market capture accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Certification Investment | GB standard and C-ITS pre-approvals unlock municipal tender eligibility across China and EU member states. |
| Edge Computing Partnership | Fiber network integration with municipal data centers creates recurring analytics revenue beyond hardware sales. |
| Semiconductor Backward Integration | In-house RF front-end design reduces dependency on Qualcomm's chipset allocation and pricing power. |
| Municipal Direct Sales Channel | Bypassing state DOT procurement cycles accelerates contract velocity in fragmented smart city markets. |
| Autonomous Vehicle Corridor Pilot | Highway operator partnerships validate cooperative perception capabilities for OEM platform integration. |
Research Methodology
Document review covered FCC spectrum allocation proceedings, EU C-ITS framework mandates, MIIT GB standard certifications, and municipal infrastructure tender databases, complemented by interviews with roadside unit procurement managers at state departments of transportation, platform engineers at telecommunications carriers, and regulatory affairs leads at automotive OEMs. Secondary validation drew from SEC filings of semiconductor vendors, customs records of DSRC chipset imports, and IHS Markit vehicle production data. Bottom-up unit deployment estimates triangulated against top-down infrastructure budget allocations across the analysis window.
Historical deployment trajectories in Michigan, Bavaria, and Shenzhen cross-referenced against panel input from municipal transit authorities and tier-1 automotive suppliers. Segmentation modeling spanned technology protocol, deployment architecture, end-user budget authority, and regional regulatory cluster. CAGRs were derived from slope analysis of infrastructure procurement cycles and spectrum allocation timelines. Forecast inputs incorporated 5G network density buildout schedules and dual carbon-aligned smart city investment flows.
Caveats apply where FCC reallocation decisions, MIIT certification delays, or semiconductor supply disruptions could materially shift the outlook. Forecasts reflect assumptions about cross-border interoperability standardization and municipal budget continuity. A small set of named triggers—spectrum rulings, GB certification timelines, and foundry allocation shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market