
 Vehicle Digital Cockpit Market | 2026-2036
Vehicle Digital Cockpit Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Digital Cockpit Market Insights
ISO 26262 functional safety certification is bifurcating the supplier base into qualified tier-one electronics providers and excluded smaller competitors. Continental AG leverages its vertical integration across display modules and software stacks to sustain program wins with German premium OEMs. Robert Bosch GmbH anchors its position through R&D intensity in augmented reality head-up display systems. Visteon Corporation competes by specializing in digital cluster integration for electric vehicle platforms.
A vehicle digital cockpit integrates multiple display surfaces, human-machine interface technologies, and software-defined functionality into a unified driver and passenger experience system, typically incorporating processing units capable of rendering multiple simultaneous video streams across resolutions exceeding 4K. Its primary commercial purpose is to consolidate previously discrete instrument clusters, infotainment screens, and climate controls into seamless, upgradeable digital surfaces that reduce hardware complexity while enabling subscription revenue models. Touchscreen technology dominates current production volumes while head-up display penetration grows fastest among premium segments as OEMs seek differentiation through augmented reality navigation overlays. Embedded deployment architectures retain the largest installed base though cloud-based configurations capture expanding margin pools through over-the-air feature activation and data services.
NHTSA guidelines on driver distraction and visual demand shape interface design requirements for US-bound vehicles, while EU Green Deal emissions targets indirectly accelerate cockpit consolidation by reducing wiring harness mass through domain centralization. China's MIIT mandates connected-vehicle data localization that influences cloud architecture choices for multinational suppliers. Stakeholders must monitor evolving cybersecurity certification schemes as software-defined cockpits become attack surfaces requiring continuous threat assessment and update orchestration.
Market Dynamics
Domain centralization is compressing cockpit electronics from distributed ECU architectures into zonal compute clusters, slashing wiring harness mass while forcing tier-one suppliers to consolidate software competencies or exit.
Growth Catalysts
- EU Green Deal emissions mandates:Mass reduction targets compel OEMs to consolidate cockpit domains, eliminating redundant controllers and copper wiring.
- Head-up display penetration in premium segments:Augmented reality navigation overlays command higher ASPs and lock in multi-year platform contracts.
- Software-defined vehicle architectures:Over-the-air update capability transforms cockpits into recurring revenue surfaces through feature subscription models.
Market Restraints
- Display panel supply concentration:Korean and Taiwanese panel makers control high-resolution automotive OLED capacity, creating allocation bottlenecks during demand spikes.
- ISO 26262 ASIL-D certification barriers:Functional safety qualification timelines extend 18-24 months, freezing out mid-tier suppliers without captive validation labs.
- Silicon wafer input volatility:Automotive-grade SoC fabrication depends on mature-node capacity where foundry pricing swings compress module margins unpredictably.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Localized cockpit module production attracts tariff advantages for export into ASEAN markets.
- Biometric driver monitoring integration:Camera-based attention tracking converges with health sensing to enable usage-based insurance partnerships.
- Cloud-native cockpit configurations:Thin-client architectures stream rendered content from edge servers, opening margin pools in data services beyond hardware shipment.
Industry Challenges
- Embedded software talent scarcity:Automotive UI/UX engineering and functional safety verification skills concentrate at Continental and Bosch, forcing competitors to poach or outsource.
- Legacy platform integration friction:12-volt electrical architectures in mass-market vehicles resist zonal compute retrofits, fragmenting R&D across incompatible voltage domains.
- Cybersecurity certification orchestration:UN R155 and ISO/SAE 21434 compliance demands continuous threat monitoring infrastructure that smaller suppliers cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Digital Cockpit Market |
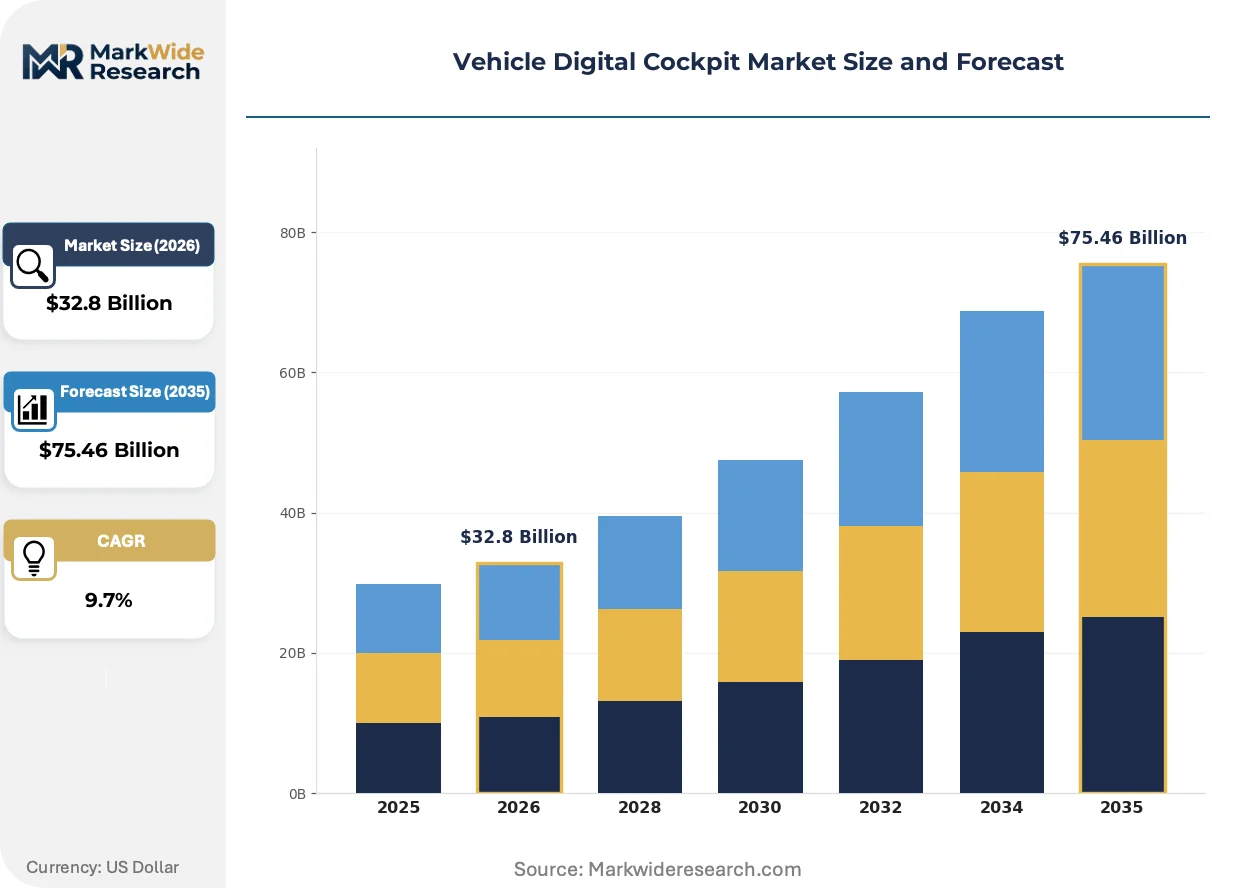
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Touchscreen, Voice Recognition, Gesture Control, Head-Up Display End User: OEMs, Aftermarket Providers, Fleet Operators, Ride-Hailing Services Deployment: On-Premise, Cloud-Based, Hybrid, Embedded Feature: Navigation, Infotainment, Connectivity, Safety Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Visteon Corporation, Harman International, Aptiv PLC, Panasonic Holdings Corp., Hyundai Mobis, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Digital Cockpit Market Trends and Innovations
Software-defined functionality is divorcing cockpit hardware from feature roadmaps, enabling OEMs to monetize the same silicon through post-sale activation rather than model-year redesigns.
Hypervisor-based virtualization is decomposing monolithic cockpit software into independently updatable partitions. Premium electric vehicle platforms from Mercedes-Benz and BMW deploy this architecture to isolate safety-critical cluster functions from third-party infotainment apps. The separation is decomposing traditional tier-one integration roles, inviting specialist software vendors into previously closed supply relationships.
NHTSA visual demand guidelines are forcing interface designers to constrain touchscreen interaction sequences to two-second glances. US-bound vehicles now mandate physical control retention for critical functions, compressing pure touchscreen roadmaps. German OEMs respond by reintroducing rotary controllers and steering-wheel haptic surfaces to maintain US market access without duplicating cockpit SKUs.
Fleet procurement of standardized cockpit modules is displacing bespoke retail configurations. Rental and mobility-service operators specify identical hardware across vehicle classes, activating features through subscription tiers rather than trim differentiation. This compression is most visible in Germany's corporate fleet channel, where Volkswagen Group and BMW now offer cockpit feature pools rather than fixed equipment lists.
Vehicle Digital Cockpit Market Segmentation
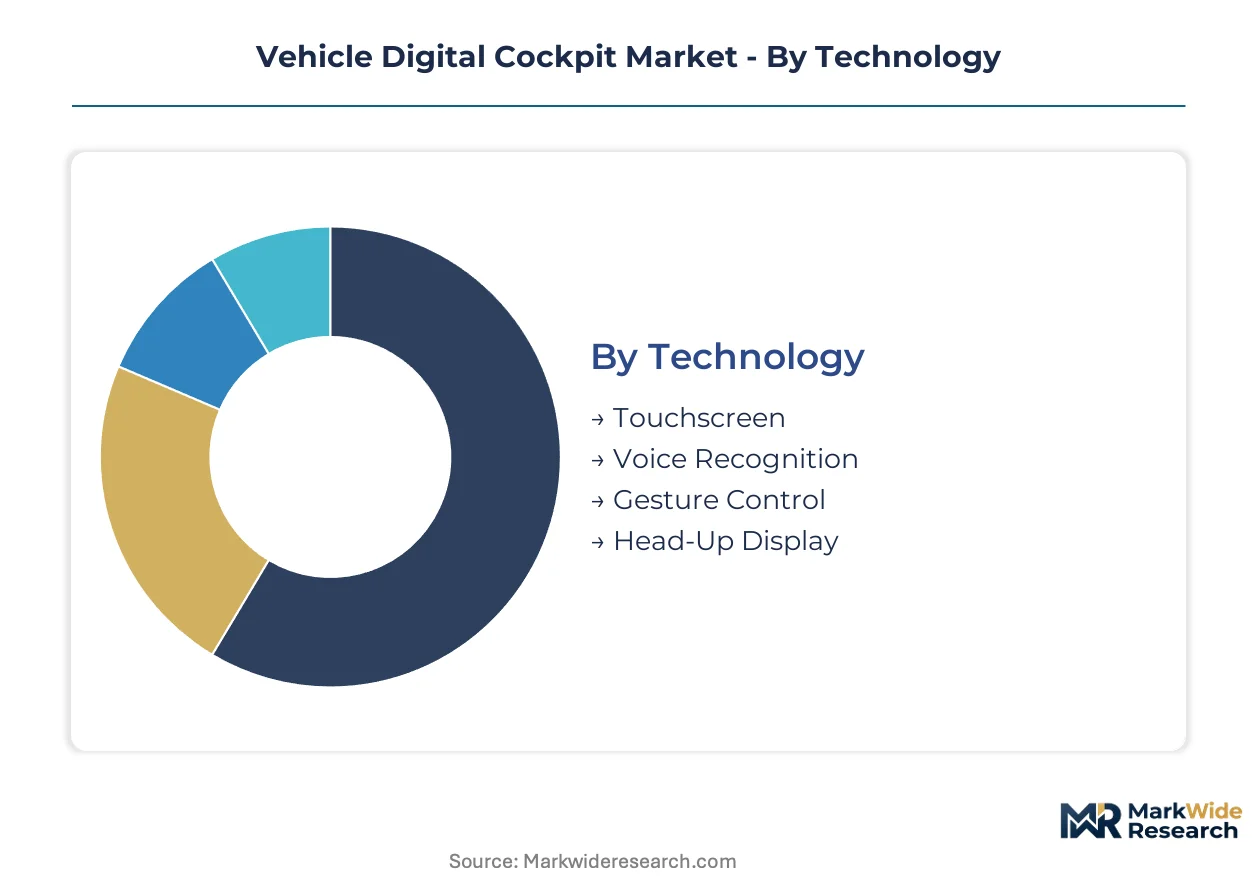
Technology substitution pressures reshape cockpit supplier strategies as voice and gesture interfaces displace touchscreen dependency. End-user concentration in OEM channels versus fleet procurement models creates divergent margin structures across deployment architectures.
Technology:
Touchscreen dominance faces intensifying substitution pressure from hands-free alternatives as regulators tighten driver distraction protocols.
- Touchscreen:Capacitive multi-touch panels with haptic feedback layers constitute the baseline interface across mass-market and premium vehicles. German OEMs anchor procurement volumes, though NHTSA visual demand guidelines compel redundant physical control retention for US-bound platforms.
- Head-Up Display:Windshield-projected augmented reality overlays render navigation guidance and hazard alerts within driver sightlines. Mercedes-Benz and BMW specify wide-field AR-HUDs as standard equipment on electric flagship models, locking in multi-year supply contracts with specialized optical suppliers.
- Voice Recognition:Natural language processing engines enable hands-free climate, navigation, and media control. Cloud-connected architectures from Amazon Alexa and Google Assistant penetrate mass-market segments through white-label integration.
- Gesture Control:Time-of-flight cameras interpret mid-air hand motions for non-contact interface manipulation. BMW deploys this technology selectively on high-end electric platforms to differentiate premium positioning.
Touchscreen retains volume leadership; head-up display holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive OEM programs from asset-light aftermarket and mobility-service procurement models.
- OEMs:Original equipment manufacturers specify cockpit modules during vehicle development cycles spanning 36-48 months. Volkswagen Group, BMW, and Mercedes-Benz consolidate purchasing power through platform-sharing strategies across multiple nameplates.
- Fleet Operators:Rental and corporate mobility providers demand standardized hardware configurations with software-activated feature tiers. Germany's corporate fleet channel drives standardization as operators specify identical cockpit modules across vehicle classes.
- Aftermarket Providers:Independent installers retrofit legacy vehicles with portable or integrated display systems. Regulatory fragmentation across national type-approval schemes constrains cross-border product scaling.
- Ride-Hailing Services:Uber and Lyft partner fleets prioritize durability and passenger-facing entertainment over driver-centric feature depth. Procurement concentrates on high-utilization electric vehicle platforms with simplified interface requirements.
OEMs retain volume leadership; fleet operators are climbing the fastest as subscription-based feature activation displaces trim-level differentiation.
Deployment:
Application-specific latency requirements fragment architecture choices between deterministic embedded systems and flexible cloud-streamed configurations.
- Embedded:Local processing units render all cockpit content without external connectivity dependency. ISO 26262 ASIL-D certification requirements extend development timelines and exclude mid-tier suppliers lacking captive validation infrastructure.
- Cloud-Based:Edge servers stream rendered content to thin-client displays, enabling continuous feature updates without hardware replacement. China's MIIT data localization mandates force architectural bifurcation for multinational suppliers serving domestic versus export markets.
- Hybrid:Partitioned architectures isolate safety-critical cluster functions locally while offloading infotainment to cloud resources. Hypervisor-based virtualization from specialist software vendors decomposes traditional tier-one integration roles.
- On-Premise:Private server deployments within OEM data centers address cybersecurity and latency constraints for premium connected vehicle services. UN R155 compliance demands continuous threat monitoring infrastructure that concentrates supply among qualified cybersecurity providers.
Embedded retains volume leadership; cloud-based configurations gain share fastest through over-the-air revenue expansion.
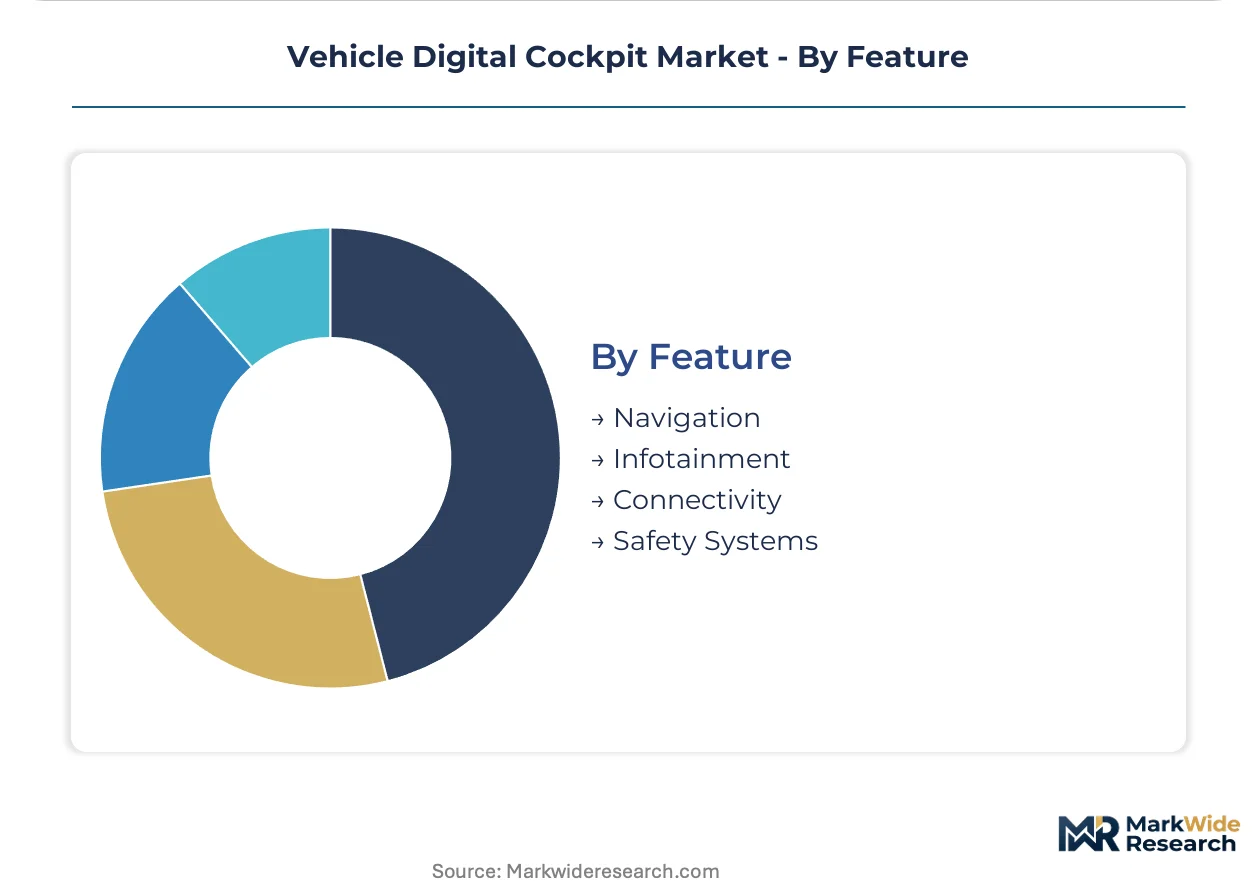
Feature:
Customer type divergence separates safety-mandated functionality from discretionary infotainment and connectivity services.
- Navigation:Real-time routing engines integrate traffic, charging station availability, and predictive energy consumption for electric platforms. Augmented reality overlays project turn-by-turn guidance onto head-up displays, commanding premium module pricing.
- Safety Systems:Driver monitoring cameras and collision warning interfaces fall under UN ECE R79 and NHTSA regulatory mandates. Biometric attention tracking converges with health sensing to enable usage-based insurance data partnerships.
- Infotainment:Media streaming, gaming, and productivity applications target passenger engagement during autonomous operation. Third-party app ecosystems from Apple CarPlay and Android Auto dominate smartphone integration.
- Connectivity:V2X communication modules enable vehicle-to-infrastructure and vehicle-to-vehicle data exchange. EU Green Deal emissions tracking requirements accelerate telematics integration for fleet carbon accounting.
Safety systems retain volume leadership; navigation features show the steepest expansion trajectory through AR-HUD penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions mandates and UN ECE R79 driver distraction regulations are reshaping cockpit electronics procurement across major automotive production clusters. OEMs in Germany, the United States, China, Japan, and South Korea are consolidating domain architectures to meet divergent regulatory timelines.
Germany
Mercedes-Benz, BMW, and Volkswagen anchor premium cockpit electronics demand through platform-sharing strategies. UN ECE R79 compliance requires redesigned human-machine interfaces with constrained visual demand. Stuttgart and Munich host concentrated R&D operations where Continental AG and Robert Bosch GmbH validate augmented reality head-up display systems.
United States
NHTSA visual demand guidelines cap touchscreen interaction sequences at two-second glances for US-bound vehicles. Detroit-based OEM procurement favors physical control retention alongside digital surfaces. Michigan's automotive corridor drives embedded software development for safety-critical cluster functions.
China
MIIT connected-vehicle data localization mandates force architectural bifurcation for multinational suppliers. Domestic electric vehicle platforms from BYD and NIO accelerate adoption of integrated cockpit systems. Shanghai and Shenzhen cluster display module production alongside foundry capacity for automotive-grade SoCs.
Japan
METI carbon neutrality targets compress wiring harness mass through domain centralization. Toyota and Honda specify cockpit modules with ISO 26262 ASIL-D certification for hybrid and electric platforms. Nagoya and Tokyo metropolitan areas concentrate tier-one electronics engineering talent.
South Korea
MFDS and national semiconductor self-sufficiency programs support captive automotive display panel capacity. Hyundai Mobis and Samsung Display anchor domestic supply chains for high-resolution OLED modules. Seoul and Gyeonggi Province host concentrated software development for hypervisor-based virtualization architectures.
Vehicle Digital Cockpit Market Competitive Landscape
Player mix skews toward diversified automotive electronics conglomerates with captive software competencies. Consolidation pressure from ISO 26262 certification timelines excludes mid-tier suppliers lacking validation infrastructure. Two strategic archetypes dominate: vertically integrated display-to-software providers and specialized cluster integration specialists. Competitive moves concentrate on strategic partnerships for hypervisor licensing and geographic expansion into India's PLI scheme jurisdictions.
Among Germany-based diversified suppliers, Continental AG and Robert Bosch GmbH occupy positions as archetype representatives for integrated cockpit electronics provision. Visteon Corporation exemplifies the specialist tier focused on digital cluster integration. Hyundai Mobis anchors Korean supply capacity for display-centric module production. These three entities collectively illustrate the geographic and capability bifurcation pressuring smaller competitors toward exit or acquisition.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Visteon Corporation |
| Harman International |
| Aptiv PLC |
| Panasonic Holdings Corp. |
| Hyundai Mobis |
| Faurecia |
| Others |
Pricing and Supply Chain Analysis
ISO 26262 ASIL-D certification gates both supplier qualification and price differentiation simultaneously, concentrating cockpit module procurement among tier-one electronics providers with captive validation infrastructure while freezing out mid-tier competitors from premium platform contracts.
Pricing Analysis
Certification level creates the primary spread across cockpit electronics procurement, with ASIL-D qualified modules commanding substantial premiums over lower-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects the intersection of functional safety grade and display resolution tier. Cost compression in standard-grade touchscreen modules is intensifying because Korean and Taiwanese panel makers control high-resolution automotive OLED capacity. Fleet operators exhibit highest price sensitivity through standardized hardware specifications, while German premium OEMs prioritize AR-HUD integration over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate mass-market cockpit assembly, though strategic stockpiling of automotive-grade SoCs is emerging among tier-one suppliers exposed to foundry capacity volatility. Manufacturing concentrates in Germany, South Korea, and China, with Stuttgart and Munich anchoring R&D-intensive cluster integration and Seoul hosting captive OLED module production. Supply chains draw from silicon wafer foundries, high-resolution display panels, and hypervisor software licenses. Single-source vulnerability in mature-node semiconductor fabrication poses structural risk. Distribution runs through OEM platform engineering channels and direct tier-one supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice and gesture interface substitution threatens touchscreen-centric incumbents as NHTSA and UN ECE R79 regulations tighten driver distraction protocols, forcing defensive repositioning across human-machine interface portfolios.
For Market Incumbents: Secure ASIL-D certification lock-in through captive validation lab investment, insulating program wins from mid-tier supplier encroachment. Deepen software-defined vehicle competencies to capture recurring revenue from over-the-air feature activation, countering hardware commoditization pressure from cloud-native cockpit architectures. For New Entrants and Emerging Players: Anchor in India's PLI scheme jurisdictions to exploit tariff advantages for ASEAN export markets, bypassing entrenched German and Korean supply relationships. Target biometric driver monitoring integration as the most penetrable white-space segment, partnering with usage-based insurance providers for data monetization pathways. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hypervisor software and cybersecurity certification infrastructure, favoring asset-light specialist acquisitions over greenfield capacity buildout. Prioritize targets with ISO/SAE 21434 compliance capabilities and existing OEM validation relationships. Watch for inflection when UN R155 enforcement thresholds trigger mandatory threat monitoring infrastructure spend.| Strategic Initiative | Industry Significance |
|---|---|
| Hypervisor Licensing Partnership | Mercedes-Benz and BMW deployments validate specialist software vendor entry into tier-one relationships. |
| AR-HUD Supply Agreement | Wide-field augmented reality head-up displays lock in multi-year platform contracts with premium electric vehicle architectures. |
| India PLI Manufacturing Footprint | Localized cockpit module production captures tariff advantages for export into ASEAN fleet procurement channels. |
| Biometric Integration Development | Camera-based attention tracking converges with health sensing to enable usage-based insurance data partnerships. |
| Cybersecurity Certification Investment | UN R155 and ISO/SAE 21434 compliance concentrates supply among qualified providers with continuous threat monitoring infrastructure. |
Research Methodology
Cross-validation between OEM platform engineering interviews and tier-one supplier procurement disclosures anchors the qualitative findings, with secondary triangulation against vehicle production databases and IHS Markit registration data. Primary fieldwork encompassed cockpit electronics procurement managers, functional safety verification leads, automotive UI/UX engineering directors, and fleet operator specification officers. Bottom-up unit economics modeling and top-down market sizing reconciliation validated volume estimates.
Sensitivity analysis across deployment architecture adoption curves and display technology substitution rates stress-tested projection robustness. Segmentation dimensions modeled include vehicle propulsion architecture, OEM tier classification, content per vehicle tier, and regional production cluster. CAGRs were derived from fitted growth curves against historical penetration benchmarks. Industry-specific forecast inputs incorporated UN ECE R79 implementation timelines and EU Green Deal emissions mandate compliance deadlines.
Decision-makers should treat outputs as directional under base assumptions of sustained semiconductor capacity expansion and stable regulatory enforcement trajectories; material deviation would warrant model refresh. Revision becomes warranted when automotive-grade SoC foundry pricing volatility or cybersecurity certification scheme evolution crosses threshold impacts on supplier economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Fleet Telematics System Market