
 Electric Vehicle Infotainment Market | 2026-2036
Electric Vehicle Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Infotainment Market Intelligence
Subscription-based financing for embedded software stacks is narrowing the competitive field to capitalized platform providers. Panasonic Corporation leverages its vertical integration into display and battery management systems to sustain long-term OEM contracts. HARMAN International anchors its position through audio-centric differentiation that commands premium bundling across European and North American vehicle lines.
Electric vehicle infotainment encompasses the integrated hardware-software systems that deliver navigation, media, telematics, and human-machine interface functions within battery-electric powertrain vehicles, typically centering on multi-core processor architectures with over-the-air update capability and real-time operating system latency below 50 milliseconds. Touch screen systems dominate current production volumes, though voice recognition interfaces are capturing the fastest expansion as natural language processing reduces driver distraction liability. Cloud computing infrastructure underpins the emerging margin pool, enabling tiered service monetization that extends beyond initial hardware shipment.
The EU AI Act classifies autonomous driving interface algorithms as high-risk AI systems, mandating conformity assessments that filter out under-resourced software vendors. In the United States, NHTSA guidelines on driver attention monitoring are pressuring OEMs to integrate camera-based gaze tracking into infotainment hardware. China's MIIT cybersecurity standards for connected vehicles require localized data processing architectures that reshape supplier qualification criteria. Stakeholders must monitor which regulatory jurisdiction sets the de facto compliance ceiling for multi-region platform deployment.
Market Dynamics
Subscription-based software financing is narrowing the competitive field to capitalized platform providers capable of sustaining multi-year OEM development cycles. This structural force concentrates procurement power around vertically integrated architecture partners with demonstrated over-the-air deployment capabilities.
Growth Catalysts
- Premium SUV Platform Adoption:Integrated cockpit systems are capturing design wins across high-volume electric SUV programs, consolidating multiple displays and control domains into unified compute architectures.
- EU AI Act Conformity Requirements:High-risk AI system classifications for autonomous driving interfaces are filtering out under-resourced software vendors, elevating qualified suppliers with established validation frameworks.
- Natural Language Processing Advancement:Voice recognition interfaces are displacing touch-dominant interaction models as NLP latency reductions below 50 milliseconds enable hands-free control with reduced driver distraction liability.
Market Restraints
- Semiconductor Supply Concentration:Multi-core processor fabrication for automotive-grade infotainment systems depends on concentrated advanced node capacity in Taiwan and South Korea, exposing platforms to geopolitical disruption risk.
- EU Cyber Resilience Act Compliance Burden:Software validation documentation requirements for connected vehicle interfaces are extending development timelines and inflating qualification costs for tier-two suppliers.
- Legacy Fleet Electrification Lag:Internal combustion vehicle platforms with proprietary CAN bus architectures resist seamless infotainment retrofit, limiting aftermarket expansion for integrated EV-native systems.
Strategic Opportunities
- India Production-Linked Incentive Capture:The PLI scheme for automotive electronics manufacturing is attracting component localization investments that qualify suppliers for domestic OEM procurement preferences.
- Camera-Based Gaze Tracking Integration:NHTSA driver attention monitoring guidelines are mandating hardware upgrades that create new content monetization vectors through personalized interface adaptation.
- Edge-Cloud Convergence Architecture:Split computing models distributing AI inference between vehicle processors and regional cloud nodes are enabling tiered service monetization beyond initial hardware shipment.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 certified systems architects command premium compensation that strains mid-tier supplier staffing models.
- Over-the-Air Validation Complexity:Real-time operating system updates below 50 millisecond latency thresholds require continuous regression testing infrastructure that consumes substantial capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Infotainment Market |
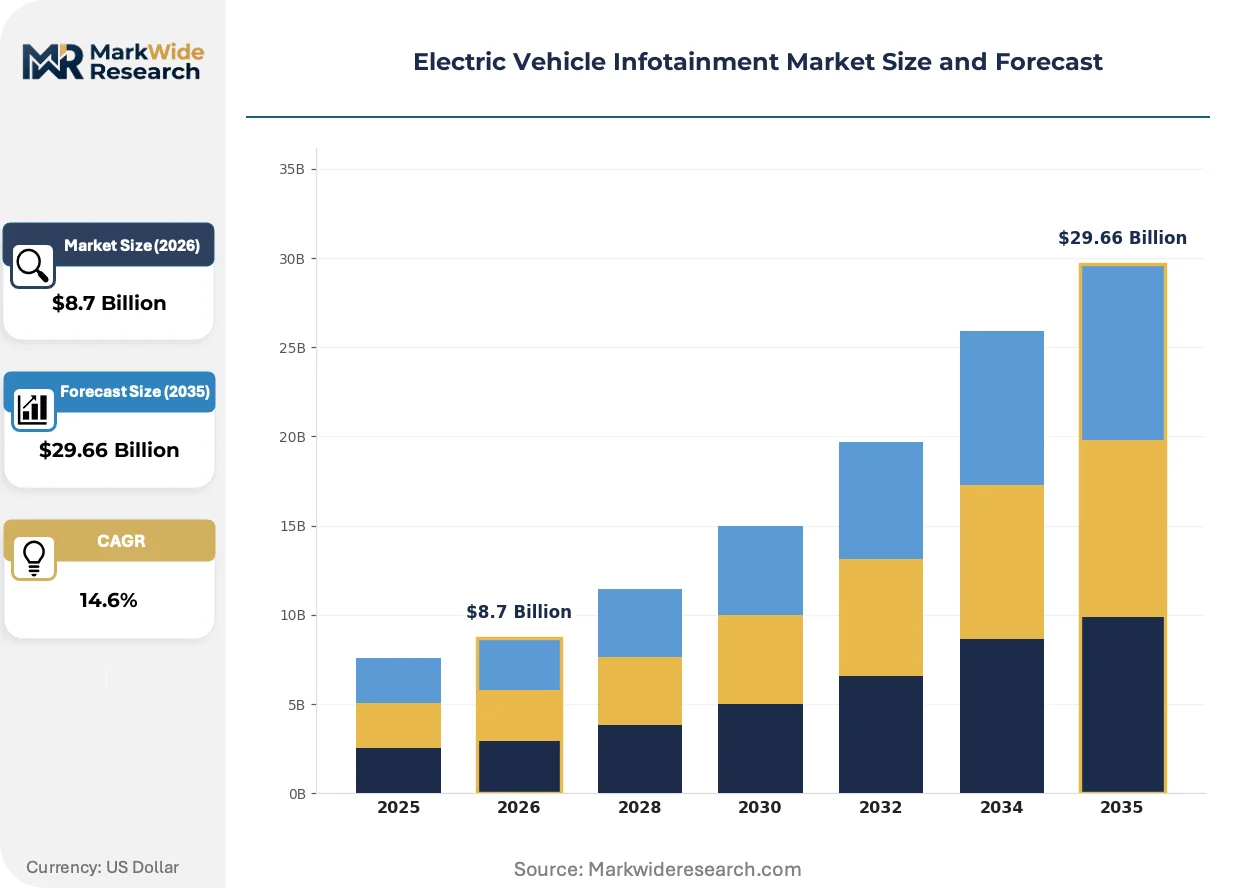
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Display, Touch Screen Systems, Voice Recognition, Navigation Systems Technology: 5G Connectivity, V2X Communication, Cloud Computing, Artificial Intelligence End User: OEMs, Aftermarket Providers, Fleet Operators, Consumers Delivery Model: Subscription-Based, One-Time Purchase, Software Update, Bundled Services |
| Companies Covered | Panasonic Corporation, HARMAN International, ALPINE ELECTRONICS, Inc., Continental AG, DENSO CORPORATION, Robert Bosch GmbH, Pioneer Corporation, Garmin Ltd., Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Infotainment Market Strategic Shifts & Innovations
Three converging forces are restructuring how infotainment value is created and captured. Technology virtualization, regulatory algorithm classification, and procurement model compression are collectively elevating platform-scale competitors over point-solution vendors.
Hypervisor-based domain consolidation is virtualizing historically separate instrument cluster, head unit, and rear-seat entertainment compute loads onto single system-on-chip architectures. Tier-one suppliers with automotive hypervisor certifications are capturing consolidated design wins that previously distributed across three or four discrete electronic control units. This compression is virtualizing hardware margins into software licensing pools with recurring revenue profiles.
The EU AI Act's high-risk classification for autonomous driving interface algorithms mandates third-party conformity assessment before market deployment. German OEMs are restructuring supplier qualification protocols to front-load documentation requirements, favoring incumbent platform providers with established regulatory affairs capabilities. The Cyber Resilience Act's software bill of materials obligations are accelerating comparable compliance investments across Netherlands and France-based supplier development centers.
Fleet procurement managers are compressing supplier panels from twelve-plus vendors to three or four strategic architecture partners capable of spanning display, audio, telematics, and human-machine interface domains. This concentration is displacing specialized audio and navigation suppliers from sole-source positions into subsystem licensing relationships. The pattern is most visible in North American premium electric vehicle programs where vertical integration mandates from OEM parent companies are reshaping competitive access.
Electric Vehicle Infotainment Market Segmentation
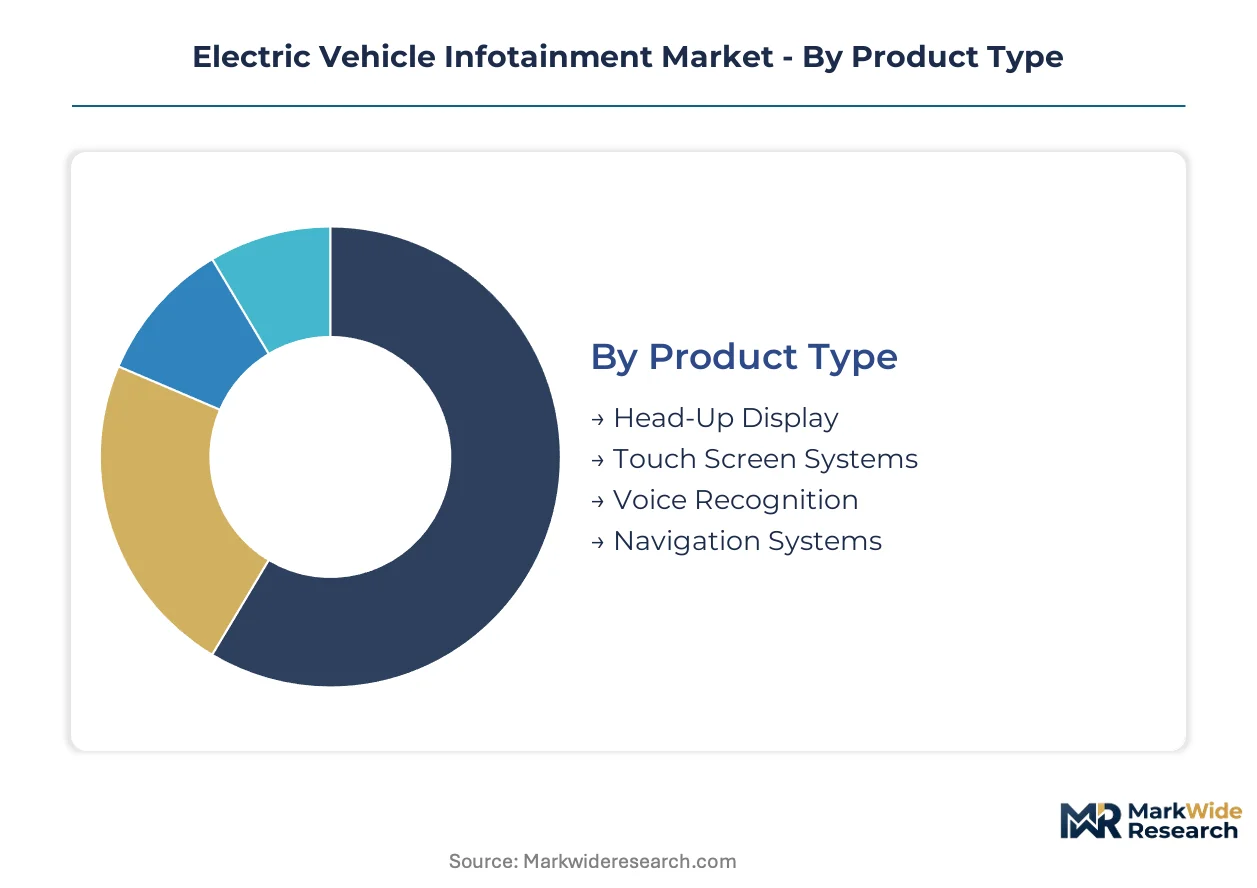
Infotainment segmentation in electric vehicles reflects divergent paths toward monetization and user experience. Product architecture choices determine whether suppliers capture value through hardware shipment or recurring software licensing.
Product Type:
Touch-dominant interfaces still anchor most production programs, though voice and augmented reality displays are rewriting interaction paradigms across premium platforms.
- Touch Screen Systems:Multi-core processor architectures drive 10-inch and larger center stack displays with haptic feedback layers. German OEM consolidation around scalable cockpit platforms concentrates procurement volume with vertically integrated display suppliers.
- Voice Recognition:Natural language processing engines with sub-50 millisecond latency enable hands-free climate, navigation, and media control. NHTSA driver distraction guidelines in the United States accelerate hardware integration mandates for gaze-tracking-compatible voice stacks.
- Head-Up Display:Windshield-projected augmented reality overlays navigation prompts onto driver sightlines.
- Navigation Systems:Cloud-connected routing with real-time traffic prediction and charging station availability.
The dominant share belongs to Touch Screen Systems, while Voice Recognition is closing the gap fastest.
Technology:
Connectivity infrastructure and AI inference capabilities separate premium platform bids from commodity hardware tenders.
- Artificial Intelligence:Edge-based neural networks process driver biometric data and predictive maintenance signals without cloud round-trips. EU AI Act high-risk system classifications force conformity assessment investments that filter out under-resourced algorithm vendors.
- Cloud Computing:Regional server nodes enable over-the-air feature activation and tiered subscription monetization. China's MIIT cybersecurity standards mandate localized data processing architectures that reshape supplier qualification protocols for domestic OEM programs.
- 5G Connectivity:Ultra-reliable low-latency links support high-definition streaming and real-time map updates.
- V2X Communication:Vehicle-to-infrastructure messaging for traffic signal timing and hazard warnings.
Artificial Intelligence commands the largest development budget allocation, with Cloud Computing expanding most quickly as OEMs build recurring revenue infrastructure.
End User:
Procurement authority concentrates with vehicle manufacturers, though fleet managers and direct consumers are emerging as separate monetization channels.
- OEMs:Original equipment manufacturers specify integrated cockpit architectures across electric SUV and sedan programs. Panasonic Corporation and HARMAN International sustain long-term contracts through demonstrated over-the-air deployment capabilities.
- Fleet Operators:Commercial vehicle managers demand telematics integration with route optimization and driver behavior monitoring. Subscription-based financing models align software costs with vehicle utilization rates.
- Aftermarket Providers:Retrofit specialists serving legacy internal combustion fleets with CAN bus adapter solutions.
- Consumers:Direct-to-owner app store purchases for entertainment and productivity services.
OEMs retain the dominant procurement volume, while Fleet Operators are gaining share fastest as commercial electrification accelerates.
Delivery Model:
Revenue recognition timing separates capitalized platform providers from hardware-shipment-dependent competitors.
- Subscription-Based:Monthly or annual licensing for navigation, streaming, and advanced driver assistance interface features. German OEMs favor this model for its alignment with vehicle lease structures and predictable service revenue.
- Bundled Services:Multi-year contracts combining hardware, software, and connectivity in single procurement vehicles. North American premium electric programs increasingly mandate vertical integration across display, audio, and telematics domains.
- One-Time Purchase:Perpetual licenses for navigation maps and feature unlocks at point of sale.
- Software Update:Transactional over-the-air feature activations post-delivery.
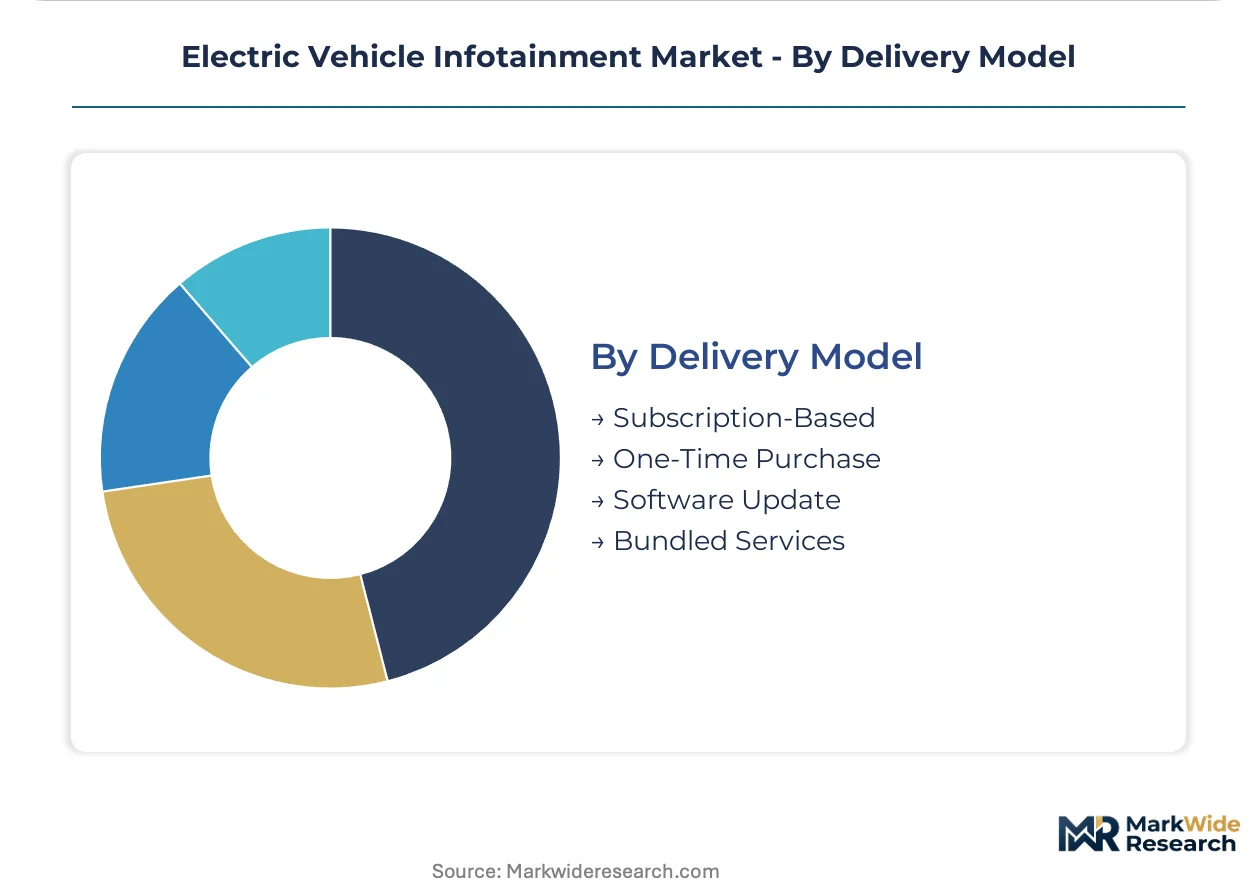
Subscription-Based models hold the dominant revenue share, while Bundled Services are climbing the fastest as procurement panels consolidate around full-stack architecture partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and regulatory frameworks are redirecting electric vehicle infotainment procurement toward concentrated manufacturing clusters in five key economies. Subsidies for domestic electronics production, combined with emissions mandates, are accelerating localized supplier qualification.
Germany
Premium SUV platform launches from BMW, Mercedes-Benz, and Volkswagen are consolidating cockpit system procurement around scalable architecture partners. The EU AI Act and Cyber Resilience Act impose conformity assessments that filter out under-resourced software vendors. Stuttgart and Munich anchor supplier development centers where HARMAN International and Continental AG maintain embedded software validation facilities.
China
MIIT cybersecurity standards mandate localized data processing architectures for connected vehicles, reshaping supplier qualification for domestic OEM programs. The dual carbon goals accelerate battery-electric vehicle penetration, expanding addressable infotainment hardware volumes. Shanghai and Shenzhen host concentrated electronics manufacturing clusters where display and processor module production scales for BYD, NIO, and XPeng programs.
United States
NHTSA driver attention monitoring guidelines pressure OEMs to integrate camera-based gaze tracking into infotainment hardware. The Inflation Reduction Act's domestic content incentives attract electronics assembly investments serving Detroit Three electrification programs. Michigan and California retain design authority for integrated cockpit architectures, though module production increasingly sources from Mexico border states.
Japan
METI funding for automotive software development supports domestic tier-one suppliers competing for integrated cockpit design wins. JIS standards for human-machine interface latency establish performance benchmarks that influence global OEM specifications. Nagoya and Tokyo metropolitan areas concentrate processor architecture development for Toyota, Honda, and Nissan electric platforms.
India
The PLI scheme for automotive electronics manufacturing attracts component localization investments qualifying suppliers for domestic OEM procurement preferences. BIS certification requirements for connected vehicle systems extend development timelines for international vendors. Tamil Nadu and Maharashtra host emerging electronics assembly corridors serving Tata Motors and Mahindra electric vehicle programs.
Electric Vehicle Infotainment Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated platform providers. Tier-one suppliers with demonstrated over-the-air deployment capabilities capture multi-domain design wins that previously distributed across discrete electronic control units. Three archetypes dominate: diversified automotive electronics conglomerates, audio-centric differentiation specialists, and display-processor integration leaders. Competitive moves concentrate on strategic partnerships for scalable cockpit architectures and backward integration into semiconductor supply.
Within the diversified conglomerate tier, Panasonic Corporation and Continental AG exemplify capitalized platform providers sustaining long-term OEM relationships through multi-domain competence. HARMAN International occupies a position exemplifying audio-centric differentiation that commands premium bundling across vehicle lines. These three anchors represent distinct competitive vectors—display-battery integration, full-stack cockpit systems, and acoustic experience specialization—that structure procurement panel consolidation around demonstrated over-the-air capabilities.
| Leading Market Players |
|---|
| Panasonic Corporation |
| HARMAN International |
| ALPINE ELECTRONICS, Inc. |
| Continental AG |
| DENSO CORPORATION |
| Robert Bosch GmbH |
| Pioneer Corporation |
| Garmin Ltd. |
| Visteon Corporation |
| Others |
Cost & Logistics Intelligence
Taipei and Hsinchu semiconductor fabrication clusters anchor global multi-core processor supply for automotive infotainment, concentrating pricing leverage with foundry operators who command premium wafer allocations during capacity constraints. This geographic concentration cascades downstream through tier-one module suppliers to OEM procurement offices in Stuttgart and Detroit.
Pricing Analysis
Certification level creates the primary spread between automotive-grade and consumer-grade system-on-chip modules. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-safety-critical tiers reflects ISO 26262 validation burden and liability exposure. Cost compression in mid-tier voice recognition hardware is intensifying because NHTSA gaze-tracking mandates force camera subsystem bundling. Fleet operators exhibit highest price sensitivity due to utilization-based total cost of ownership calculations, while premium SUV programs absorb certification premiums without volume negotiation.
Supply Chain Analysis
Export control restrictions on advanced node lithography equipment limit capacity expansion in Taiwan and South Korea, tightening supply for 7-nanometer and below automotive processors. Multi-layer ceramic capacitors and high-bandwidth memory modules draw from concentrated Japanese and South Korean component suppliers. Single-source vulnerability runs through TSMC's automotive foundry allocation system. Distribution runs through tier-one cockpit integrators who consolidate display, audio, and compute module sourcing for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from smartphone-derived computing platforms repurposed for vehicle integration, threatening proprietary automotive stack margins. Defense requires pre-emptive architecture moves that entrench differentiated value.
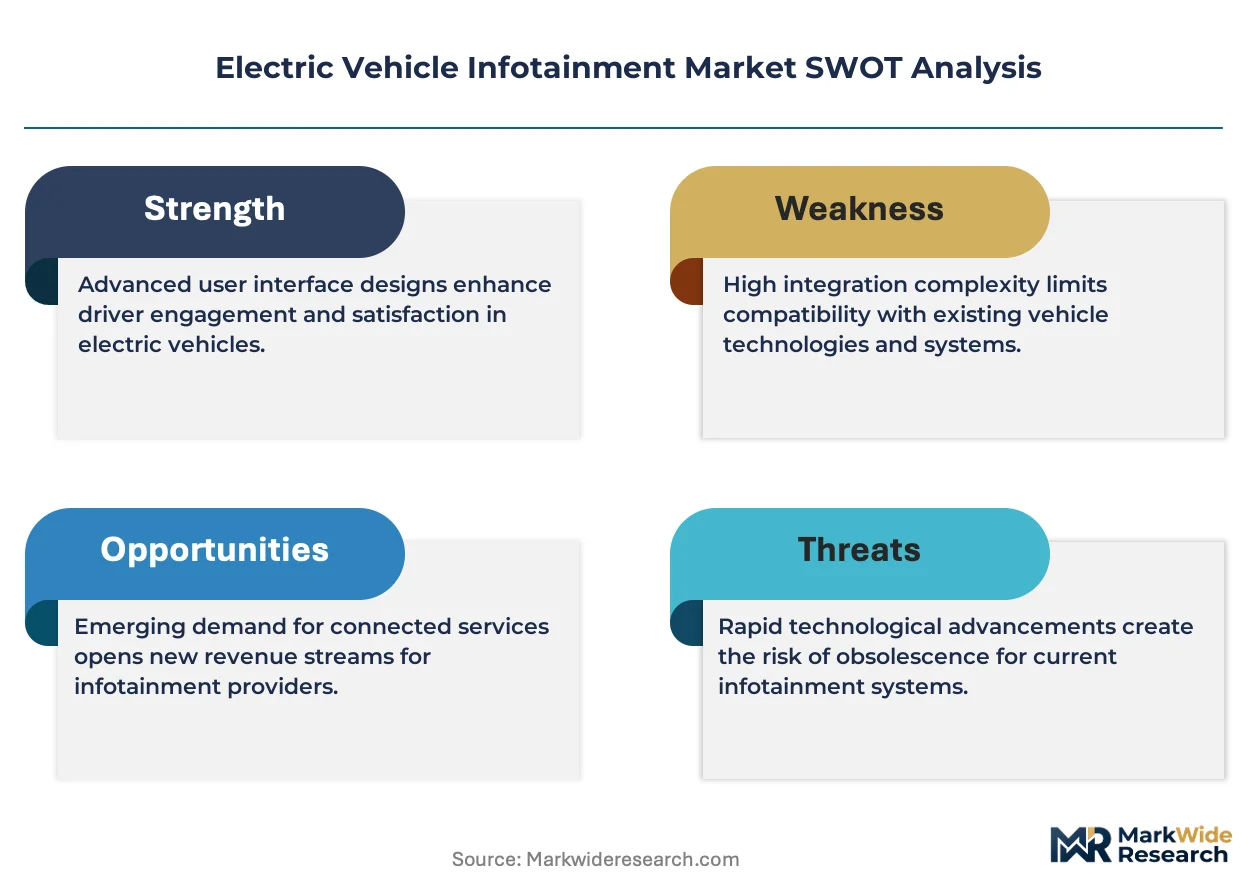
For Market Incumbents: Pre-empt smartphone platform encroachment by embedding functional safety certification deeper into hypervisor layers that consumer silicon cannot replicate. Consolidate procurement panel positions through captive software validation facilities in Germany that satisfy EU AI Act conformity assessment requirements. Secure multi-year battery management system bundling to lock display-processor integration contracts. For New Entrants and Emerging Players: Mid-market commercial fleet operators in India represent the most penetrable entry point, as PLI scheme localization requirements disqualify established international vendors from domestic OEM preference programs. Voice recognition subsystem licensing for retrofit telematics platforms offers second white-space access with lower certification burden. Pursue direct fleet operator relationships bypassing tier-one procurement consolidation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive hypervisor certification holders with demonstrated over-the-air deployment infrastructure. Long-term viability hinges on software recurring revenue capture rather than hardware shipment dependence. Watch NHTSA rulemaking on driver monitoring mandate timing as inflection signal for camera subsystem demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated cockpit architectures reduce electronic control unit count across BMW and Mercedes-Benz electric SUV programs. |
| Battery Supply Agreement | Panasonic's captive cell production secures long-term infotainment integration contracts with Toyota and Tesla. |
| Software-Defined Vehicle Investment | Edge-cloud split computing enables tiered subscription monetization beyond initial hardware shipment. |
| Geographic Manufacturing Footprint | Tamil Nadu PLI qualification attracts component localization serving Tata Motors electrification timeline. |
| Charging Infrastructure Partnership | Navigation system bundling with charging network data creates recurring revenue attachment points. |
Research Approach
Cross-validation between OEM platform engineering directors and tier-one supplier procurement leads anchors the qualitative findings in operational reality. Primary interviews with cockpit system architects, functional safety engineers, fleet telematics managers, and automotive regulatory affairs specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC automotive segment disclosures, and MIIT cybersecurity filings. Bottom-up bill-of-materials costing and top-down OEM procurement budget triangulation establish volume and value estimates.
Calibration against historical infotainment content-per-vehicle trajectories and electric vehicle production ramp schedules shapes the projection framework. Segmentation dimensions span product type, connectivity technology, end-user procurement authority, and delivery model revenue recognition timing. CAGRs derive from fitted adoption curves applied to regional electrification policy mandates and OEM platform launch schedules. Cloud infrastructure capex disclosures and automotive processor foundry utilization rates feed supply-side constraints.
Macroeconomic conditions sit as an overlay; deviation in battery raw material costs and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timing and OEM consolidation behavior. Material shifts in EU AI Act enforcement stringency or NHTSA driver distraction rulemaking would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Car Generated Data Market