
 Automotive Human Machine Interface (HMI) Market | 2026-2036
Automotive Human Machine Interface (HMI) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Human Machine Interface (HMI) Market Analytics
Premium-grade HMI systems with augmented reality overlays is rotating the competitive focus toward software-defined cockpit architectures. Continental AG leverages its integrated systems portfolio to dominate instrument cluster supply across European OEMs. Robert Bosch GmbH sustains R&D intensity in gesture control modules through captive semiconductor partnerships. Visteon Corporation anchors North American production with specialized head-up display manufacturing lines.
Automotive Human Machine Interface encompasses the hardware and software systems enabling driver-vehicle interaction, including capacitive touch panels operating at 60 Hz refresh rates, far-field microphone arrays with noise cancellation, and optical projection systems rendering navigation data onto windshields. The primary commercial purpose centers on reducing driver cognitive load while consolidating climate, infotainment, and advanced driver assistance controls into unified interfaces. Touchscreen technology leads product type revenue pools due to universal deployment across passenger and commercial vehicle segments, while augmented reality represents the fastest-growing technology category as automakers integrate real-time hazard visualization. Voice recognition occupies mature margin positions in luxury vehicles but extends into economy segments through cloud-connected natural language processing.
The EU AI Act imposes algorithmic transparency mandates on biometric driver monitoring systems, while GDPR restricts cross-border transfer of in-cabin behavioral data collected by HMI platforms. NHTSA guidelines in the United States shape distraction-minimization standards for touchscreen response latency and menu depth. Stakeholders must monitor diverging regulatory timelines for software update certification across jurisdictions to align product roadmaps with compliance windows.
Market Dynamics
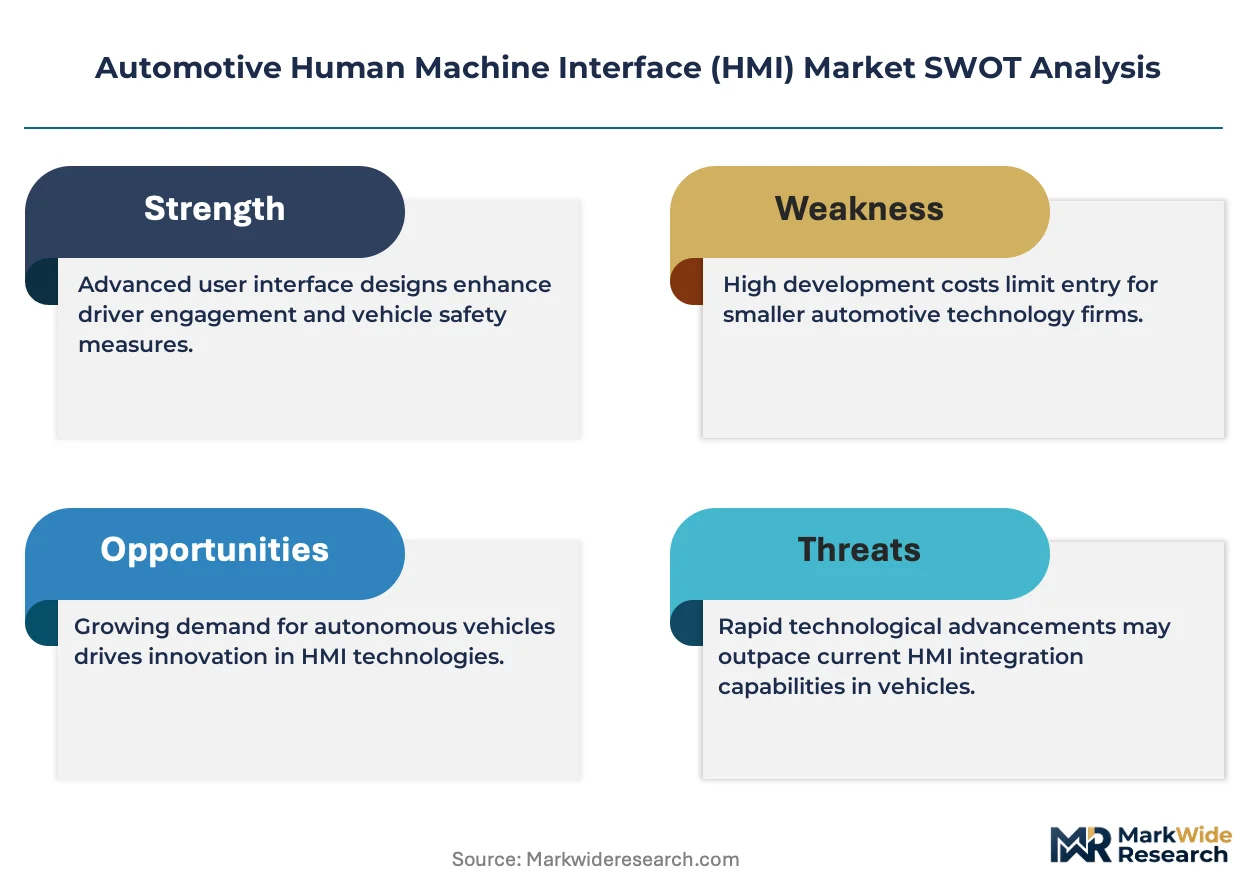
Software-defined cockpit architectures are consolidating climate, infotainment, and ADAS controls into unified computing platforms, compressing hardware supplier margins while elevating middleware and UX software valuations across the automotive supply chain.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements for biometric driver monitoring systems are accelerating OEM investment in explainable AI interfaces, creating certified supplier tiers.
- Touchscreen refresh rate escalation:60 Hz capacitive panels are becoming baseline specifications across economy vehicle segments, expanding addressable hardware volumes beyond luxury classifications.
- German production clustering:Continental AG and Robert Bosch GmbH anchor concentrated supplier ecosystems around Stuttgart and Hanover, reducing logistics costs for European OEM integration programs.
Market Restraints
- Semiconductor input volatility:Far-field microphone arrays and optical projection chipsets face allocation constraints from captive foundry capacity, compressing gross margins on voice recognition modules.
- GDPR cross-border data friction:Behavioral biometrics collected by in-cabin HMI platforms face restricted transfer outside European Economic Area jurisdictions, fragmenting cloud architecture deployments.
- Windshield projection technical ceiling:Augmented reality head-up displays confront sunlight readability limitations and thermal management constraints in equatorial climates, delaying mass-market penetration timelines.
Strategic Opportunities
- India BIS certification pathway:Domestic automotive production growth under PLI scheme incentives creates demand for localized HMI assembly and software customization services.
- Voice-natural language convergence:Edge AI processing combined with 5G vehicle-to-cloud connectivity enables real-time multilingual command interpretation without latency penalties.
- NHTSA distraction-minimization guidelines:Response latency and menu depth standards in the United States are mandating simplified interface designs that reduce OEM development cycle complexity.
Industry Challenges
- Embedded systems UX talent scarcity:Automotive-grade interface design requires rare cross-functional expertise combining ISO functional safety certification with consumer electronics usability standards.
- Legacy platform integration complexity:CAN bus and Ethernet backbone coexistence demands protocol translation layers that increase software validation burden and defect surface area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Human Machine Interface (HMI) Market |
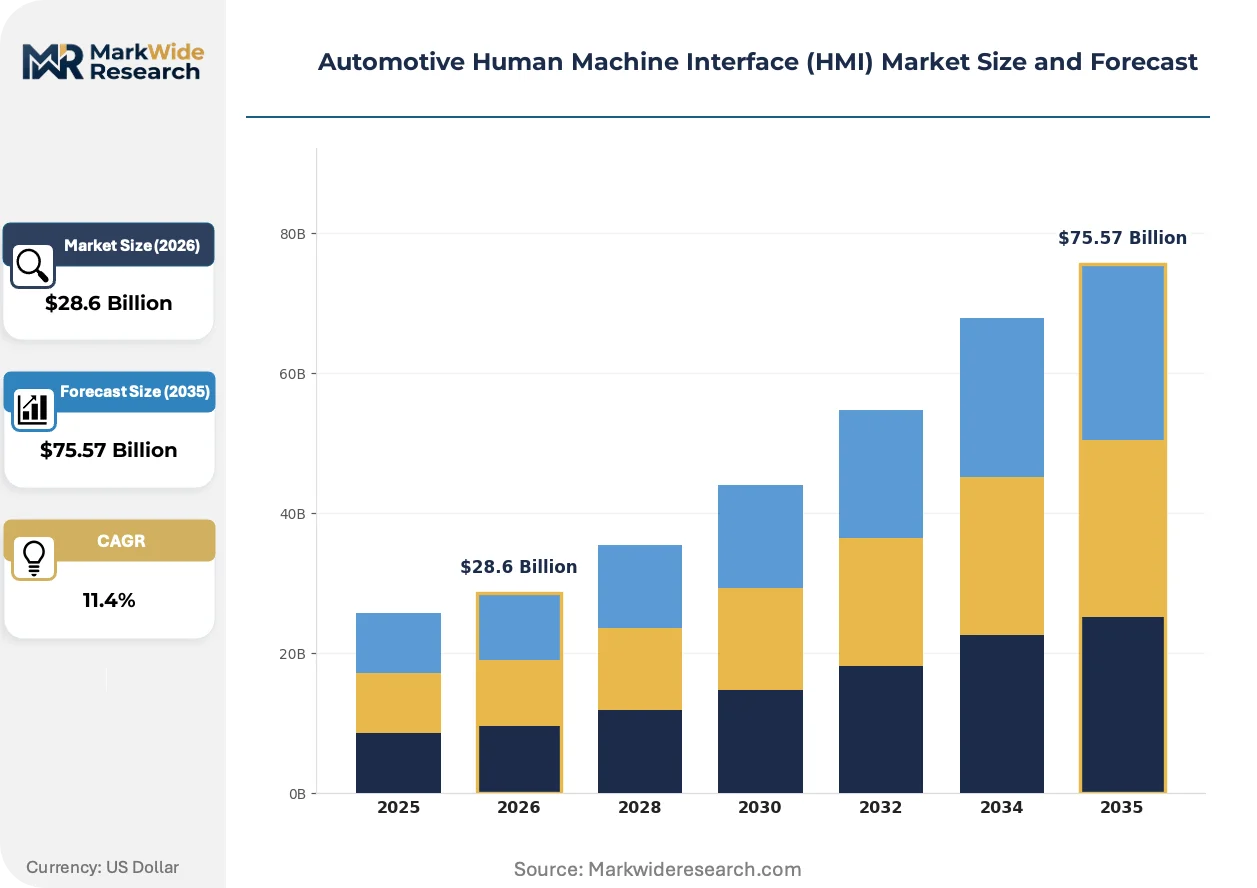
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Touchscreen, Voice Recognition, Gesture Control, Augmented Reality Product Type: Instrument Cluster, Head-Up Display, Central Console, Rear Seat Entertainment End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Form Factor: Standalone Units, Integrated Systems, Modular Designs, Custom Solutions |
| Companies Covered | Continental AG, Visteon Corporation, Aptiv, HARMAN International, Synaptics Incorporated, Robert Bosch GmbH, Denso Corporation, Valeo SA, Luxoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Human Machine Interface (HMI) Market Evolving Landscape
Augmented reality visualization is migrating from premium option packages toward standard safety equipment, while regulatory pressure on driver distraction is forcing fundamental interface architecture redesigns across all vehicle classes.
Optical projection systems for windshield-integrated navigation guidance are fragmenting the traditional instrument cluster supplier landscape. Tier 1 electronics manufacturers are adopting micro-LED and laser-scanning micro-mirror technologies to achieve 10,000-nit brightness targets. European luxury OEMs are integrating real-time hazard overlay functions that compress the competitive relevance of conventional head-up display architectures.
The EU AI Act's algorithmic transparency requirements are mandating documented decision pathways for biometric emotion detection and drowsiness classification systems. OEMs must maintain technical files demonstrating human oversight capabilities for all in-cabin AI functions. German and French regulators are conducting conformity assessments that delay product launches by 8-14 months for systems lacking pre-certified software components.
Fleet operators and mobility service providers are consolidating procurement specifications around standardized API architectures that enable third-party application integration. Traditional tiered supplier relationships are giving way to direct software licensing agreements between OEMs and specialized UX studios. North American commercial vehicle segments exhibit the most aggressive unbundling of hardware from recurring software subscription revenue models.
Automotive Human Machine Interface (HMI) Market Segmentation
HMI procurement patterns diverge sharply across vehicle electrification tiers and regulatory jurisdictions. EU AI Act compliance requirements and NHTSA distraction guidelines reshape how OEMs allocate development budgets across interface modalities.
Technology:
GDPR cross-border restrictions and EU AI Act algorithmic transparency mandates create divergent certification burdens across interface modalities.
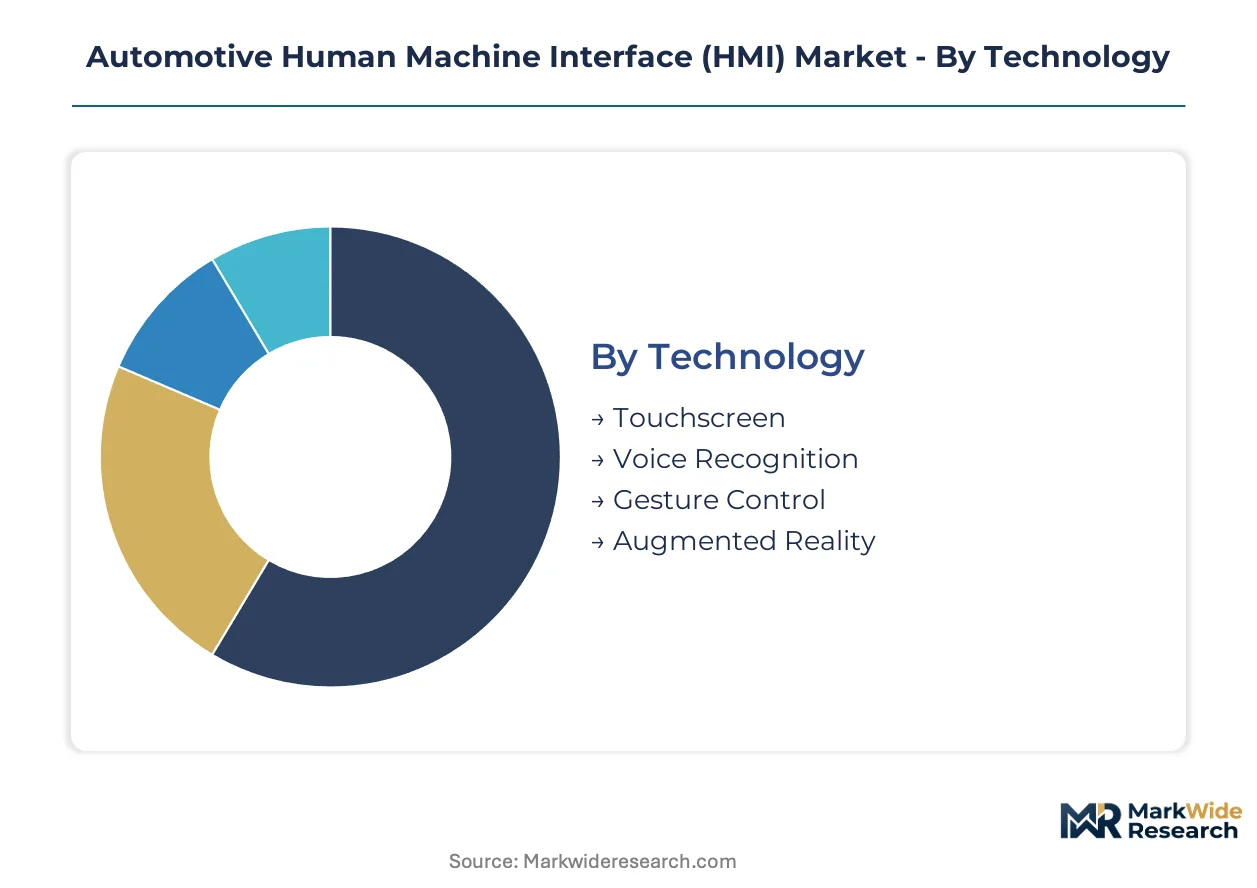
- Touchscreen:Capacitive panels operating at 60 Hz refresh rates dominate hardware procurement volumes across economy and mid-range vehicle segments. German OEMs anchor demand in Stuttgart and Wolfsburg production clusters, where Continental AG and Robert Bosch GmbH supply integrated display modules meeting ISO 26262 functional safety grades.
- Augmented Reality:Optical projection systems rendering navigation data onto windshields achieve 10,000-nit brightness targets through micro-LED and laser-scanning micro-mirror technologies. European luxury manufacturers concentrate adoption in Munich and Ingolstadt assembly plants, driven by real-time hazard overlay requirements under EU vehicle safety frameworks.
- Voice Recognition:Far-field microphone arrays with noise cancellation face semiconductor allocation constraints from captive foundry capacity.
- Gesture Control:Optical and radar-based tracking modules require ISO 26262 certification for driver distraction compliance.
Established volume favors touchscreen; emerging adoption favors augmented reality.
Product Type:
Cost tier differentiation separates premium safety equipment from standard infotainment across OEM lineups.
- Instrument Cluster:Digital display modules consolidating speedometer, tachometer, and ADAS warning systems into unified screens. Continental AG dominates supply contracts with European OEMs in Germany and France, where KBA and ANSM regulators enforce cybersecurity certification timelines.
- Head-Up Display:Windshield projection systems presenting speed and navigation data within driver line-of-sight. Visteon Corporation anchors North American manufacturing in Michigan and Ontario, serving Detroit Three OEMs under NHTSA distraction-minimization guidelines.
- Central Console:Touchscreen modules integrating climate, media, and vehicle settings face thermal management constraints in equatorial climates.
- Rear Seat Entertainment:Deployable screens and streaming interfaces target luxury and family vehicle segments with extended cabin footprints.
Revenue concentration clusters in instrument clusters; steepest expansion trajectory appears in head-up displays.
End User:
Application-specific requirements separate passenger convenience from commercial fleet durability specifications.
- Passenger Vehicles:Mass-market HMI deployments prioritize cost-optimized touchscreen modules with standardized UX frameworks. Production volumes concentrate in Germany, Japan, and the United States, where NHTSA, KBA, and METI regulators maintain divergent response latency standards.
- Electric Vehicles:Battery-electric platforms demand consolidated cockpit architectures integrating energy management displays with navigation and charging station locators. Chinese and South Korean OEMs lead integration depth, leveraging MIIT and MFDS software certification pathways.
- Commercial Vehicles:Fleet operators mandate standardized API architectures enabling third-party telematics integration.
- Luxury Vehicles:Premium segments absorb development costs for augmented reality and gesture control before economy migration.
Passenger vehicles capture baseline volume; electric vehicles are gaining share fastest.
Form Factor:
Supply chain configuration separates captive integrated production from outsourced modular procurement.
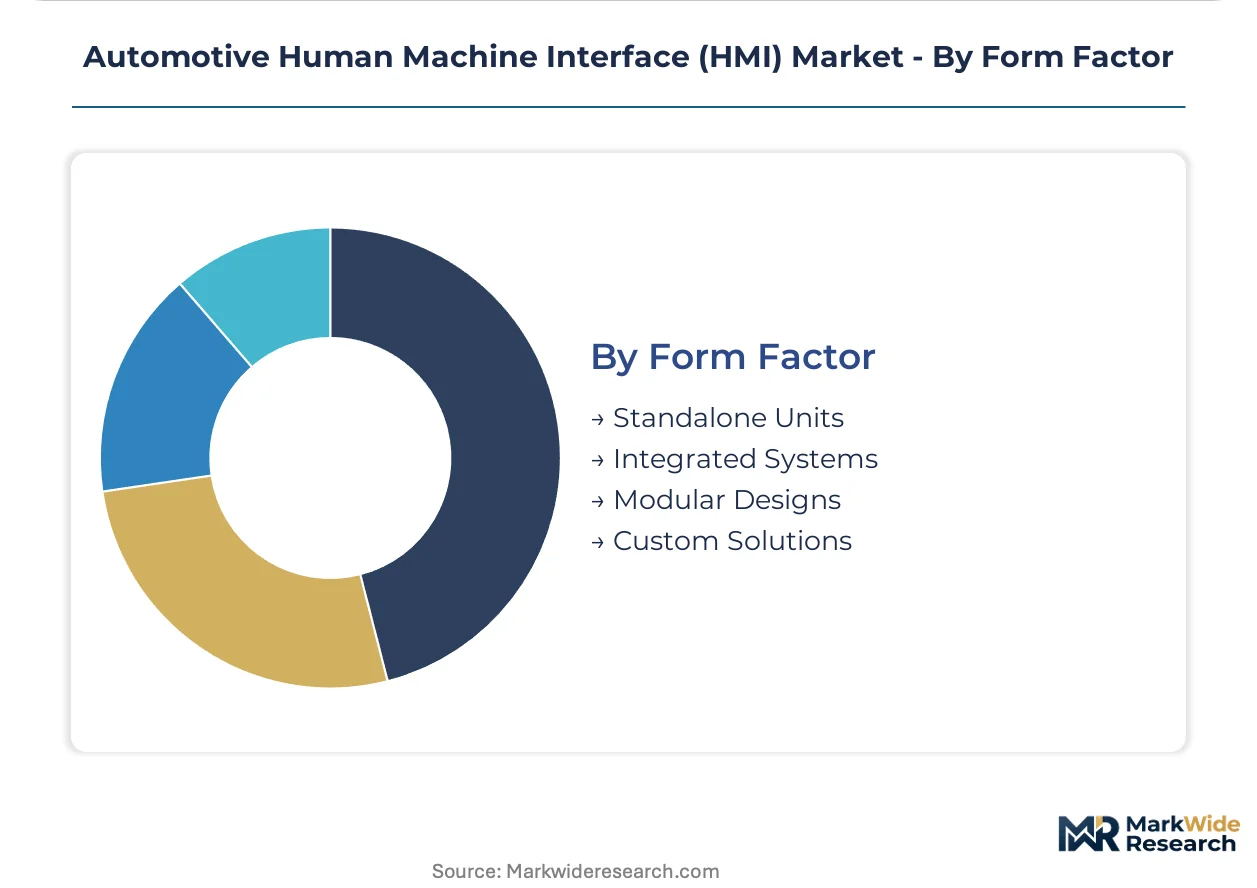
- Integrated Systems:Unified computing platforms consolidating multiple HMI functions into single hardware units. Tier 1 suppliers in Germany and Japan dominate, where Bosch and Denso maintain captive semiconductor partnerships reducing foundry allocation risk.
- Modular Designs:Swappable display and control units enabling post-sale feature upgrades through software licensing. North American commercial vehicle segments exhibit aggressive unbundling of hardware from recurring subscription revenue models.
- Standalone Units:Discrete components for aftermarket replacement and repair channels face price pressure from generic competitors.
- Custom Solutions:Bespoke interface designs for ultra-luxury and limited-production vehicles carry extended development cycles.
Integrated systems anchor OEM supply agreements; modular designs attract fleet and mobility service procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing clusters over emerging assembly locations. Germany and China maintain substantial component surpluses in display modules and optical systems, while India and Mexico absorb growing import volumes for localized vehicle production integration.
Germany
Stuttgart and Hanover production clusters anchor European HMI supply chains for instrument clusters and head-up displays. KBA cybersecurity certification timelines and EU AI Act algorithmic transparency mandates compress product launch windows for biometric monitoring systems. Continental AG and Robert Bosch GmbH dominate captive semiconductor partnerships around Wolfsburg assembly corridors.
United States
NHTSA distraction-minimization guidelines shape touchscreen response latency specifications across Detroit Three OEM programs. Michigan and Ontario manufacturing corridors concentrate head-up display production for commercial and passenger vehicle segments. Visteon Corporation anchors specialized optical projection lines serving North American electrification roadmaps.
China
MIIT software certification pathways accelerate consolidated cockpit architectures for battery-electric platforms. Yangtze River Delta and Pearl River Delta clusters integrate energy management displays with charging infrastructure locators. Domestic OEMs leverage GB standards and dual carbon goals to localize HMI component sourcing away from import dependency.
India
PLI scheme incentives for domestic automotive production create demand for localized HMI assembly and software customization services. BIS certification requirements reshape procurement specifications for touchscreen and voice recognition modules. Maharashtra and Tamil Nadu manufacturing corridors attract tier-1 supplier investments for modular cockpit system integration.
Japan
METI standards and JIS certification frameworks govern functional safety grades for gesture control and augmented reality interfaces. Kanto and Chubu industrial regions maintain integrated systems production for hybrid and electric vehicle exports. Denso Corporation exemplifies captive semiconductor strategies reducing foundry allocation exposure for far-field microphone arrays.
Automotive Human Machine Interface (HMI) Market Competitive Landscape
Concentration sits with diversified tier-1 electronics suppliers possessing captive semiconductor partnerships and integrated software-hardware portfolios. The supplier base exhibits tiered stratification between full-system integrators and specialized module manufacturers. Three archetypes dominate: German diversified industrials with functional safety certification depth, North American display specialists with head-up display manufacturing scale, and Japanese component suppliers with vertical control over sensor inputs. Competitive moves center on strategic partnerships for middleware licensing and geographic expansion into Indian and Southeast Asian assembly corridors.
Within the German diversified tier, Continental AG and Robert Bosch GmbH exemplify integrated systems capabilities spanning instrument clusters, gesture control modules, and regulatory compliance infrastructure. Visteon Corporation represents the North American specialist archetype with concentrated manufacturing in Michigan and Ontario. These three entities anchor distinct competitive vectors—functional safety certification, optical projection scale, and semiconductor supply security—rather than competing directly on identical product specifications.
| Leading Market Players |
|---|
| Continental AG |
| Visteon Corporation |
| Aptiv |
| HARMAN International |
| Synaptics Incorporated |
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo SA |
| Luxoft |
| Others |
Value Network & Pricing Analysis
Stuttgart and Hanover production clusters achieve 15-20% unit cost advantages through shared logistics infrastructure and captive semiconductor partnerships, compressing price floors for instrument cluster modules while elevating margins for software-defined cockpit architectures. Continental AG and Robert Bosch GmbH leverage this scale to enforce three-tier pricing structures across premium, standard, and economy certification grades, with EU AI Act compliance timelines adding 8-14 month premiums for biometric monitoring systems.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale discounts and certification-tier premiums. Price differentiation separates ISO 26262 ASIL-D functional safety grades from economy touchscreen modules, with GDPR-compliant data architectures commanding 12-18% premiums. Cost compression in voice recognition modules is intensifying because captive foundry allocation constraints on far-field microphone arrays are squeezing tier-2 supplier margins. Fleet operators exhibit highest price sensitivity due to standardized API procurement specifications, while luxury OEMs absorb premium AR head-up display costs with minimal negotiation leverage.
Supply Chain Analysis
Port congestion on Rotterdam-Hamburg container routes and semiconductor equipment backlogs at Taiwan foundries are extending inbound logistics cycles for optical projection chipsets. Manufacturing concentrates in Germany, China, and Japan, with Yangtze River Delta clusters feeding domestic EV platforms and Kanto regions supplying hybrid exports. The chain draws from Taiwan for micro-LED backplanes, South Korea for OLED driver ICs, and German captive fabs for gesture control sensors. Single-source vulnerability in laser-scanning micro-mirror technology creates allocation risk for augmented reality head-up displays. Distribution runs through tier-1 system integrators directly to OEM platform engineering teams, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software licensing and over-the-air update subscriptions are expanding faster than hardware shipments as OEMs unbundle cockpit functionality from initial vehicle transactions. This service-attach dynamic favors suppliers with middleware platforms and recurring revenue architectures over pure component manufacturers.
For Market Incumbents: Secure captive semiconductor partnerships in Taiwan and South Korea to insulate voice recognition and AR projection modules from foundry allocation shocks. Consolidate instrument cluster supply positions through ISO 26262 certification depth, as emerging Chinese tier-1s threaten European dominance in digital display modules. Prioritize middleware licensing agreements that embed UX frameworks into OEM software-defined vehicle roadmaps, reducing exposure to hardware margin compression.
For New Entrants and Emerging Players: Fleet telematics API standardization gaps in North American commercial vehicle segments offer white-space entry where incumbents under-serve third-party integration demand. Target India's PLI scheme corridors for localized touchscreen assembly and BIS certification services, leveraging Maharashtra and Tamil Nadu manufacturing incentives before German suppliers establish regional footprints. Pursue direct software licensing models with mobility service providers rather than tier-1 hardware supply relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors UX studios with embedded automotive functional safety expertise and cloud-edge hybrid architectures. Long-term viability rests on software-defined vehicle transition completion, with tier-1 suppliers possessing middleware platforms outperforming pure hardware manufacturers. Watch NHTSA distraction-minimization guideline enforcement intensity as inflection signal—accelerated response latency standards would compress development cycle advantages for certified incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Consolidates climate, infotainment, and ADAS controls into unified computing platforms elevating middleware valuations. |
| Geographic Manufacturing Footprint | India PLI scheme and BIS certification pathways reduce import dependency for domestic OEM integration programs. |
| Strategic Partnership | Captive semiconductor agreements with Taiwan foundries insulate voice recognition modules from allocation constraints. |
| Platform Standardization | EU AI Act algorithmic transparency mandates accelerate certified supplier tier formation for biometric monitoring systems. |
| Charging Infrastructure Partnership | Energy management display integration with charging station locators deepens cockpit architecture consolidation for EV platforms. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, dealership operations heads, and aftermarket distributors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, regulatory filing repositories, and customs trade records. Bottom-up segment sizing triangulated with top-down market envelope checks across technology, product type, end user, and form factor dimensions.
Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs derived from logistic growth curve fitting with S-curve inflection points calibrated to electrification adoption rates and regulatory compliance timelines. Industry-specific inputs encompassed EU AI Act certification delay distributions, NHTSA guideline enforcement probability, and semiconductor foundry capacity allocation schedules.
Forecasts assume regulatory continuity in EU AI Act implementation and NHTSA distraction-minimization enforcement; material policy shifts would require re-modeling. Supply chain disruption scenarios, tariff regime changes, or accelerated software-defined vehicle transitions present revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Commercial Telematics Market