
 In Vehicle Infotainment Market | 2026-2036
In Vehicle Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
In Vehicle Infotainment Market Intelligence
Software-defined cockpit architecture is fragmenting traditional tier-one supply relationships as automakers pursue direct control over user experience layers. Harman International leverages its Samsung parent ecosystem to sustain integrated hardware-software development across multiple OEM programs. Continental AG anchors European production with manufacturing scale in infotainment control units, while Visteon Corporation competes through specialization in digital cluster integration.
In Vehicle Infotainment encompasses embedded computing platforms, display interfaces, audio processing hardware, and connectivity modules that deliver navigation, entertainment, telematics, and human-machine interaction functions within automobiles. These systems typically integrate multi-core processors operating at 1-2 GHz, support multiple high-resolution displays exceeding 12 inches, and execute on QNX, Linux, or Android Automotive operating systems with functional safety ratings up to ASIL-B. Display Systems command the largest revenue pool among product type segments as dashboard digitization replaces analog instrumentation across vehicle classes. Android Auto and Apple CarPlay connectivity technologies are displacing proprietary smartphone mirroring protocols as consumer expectations shift toward seamless device integration. OEM end users dominate volume absorption, though aftermarket providers capture margin in vehicle aging and retrofit applications.
NHTSA distraction guidelines and FCC wireless certification requirements constrain interface design and connectivity module approval pathways in the United States. Europe's ECE R10 and GDPR data handling provisions impose parallel compliance burdens on systems collecting driver behavior and location data. Stakeholders must monitor regulatory divergence between cybersecurity mandates in major automotive markets as software-defined vehicle architectures expand attack surfaces and liability exposure.
Market Dynamics
Software-defined vehicle architectures are dissolving traditional tier-one supplier hierarchies as automakers reclaim control over user experience layers and over-the-air update pipelines.
Growth Catalysts
- 5G-V2X Deployment:Cellular vehicle-to-everything infrastructure mandates in China and Germany are accelerating demand for low-latency connectivity modules in premium and mass-market vehicle segments.
- GDPR-Compliant Data Monetization:Europe's data handling provisions are creating standardized frameworks for driver behavior analytics, enabling subscription-based feature activation revenue streams.
- Japan's Aging Fleet Retrofit Demand:Extended vehicle lifecycles and consumer preference for technology upgrades are expanding aftermarket infotainment replacement cycles beyond traditional 5-7 year windows.
Market Restraints
- Semiconductor Supply Concentration:Advanced SoC fabrication for automotive displays remains concentrated among Taiwan-based foundries, exposing OEMs to geographic supply disruption risks.
- NHTSA Distraction Compliance:Interface interaction time limits and glance-duration guidelines are constraining feature complexity and extending human-factors validation timelines.
- Functional Safety Certification Costs:ASIL-B rating requirements for instrument cluster integration are inflating development budgets and squeezing margin for mid-tier system suppliers.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentive structures for semiconductor assembly and display manufacturing are attracting component localization investments from global tier-one suppliers.
- Rear-Seat Entertainment Convergence:Streaming service integration and gaming-optimized displays are opening new content monetization channels in luxury and family vehicle configurations.
- Harmonized Cybersecurity Standards:UN R155 vehicle cybersecurity regulations are creating certification economies of scale for suppliers serving multiple European and Asian markets simultaneously.
Industry Challenges
- Embedded Software Talent Scarcity:Shortages of QNX and Android Automotive OS specialists are extending development timelines and inflating compensation costs for in-house cockpit engineering teams.
- Legacy Fleet Integration Complexity:Retrofitting connected services into vehicles with CAN-based architectures requires gateway hardware that fragments software update deployment pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vehicle Infotainment Market |
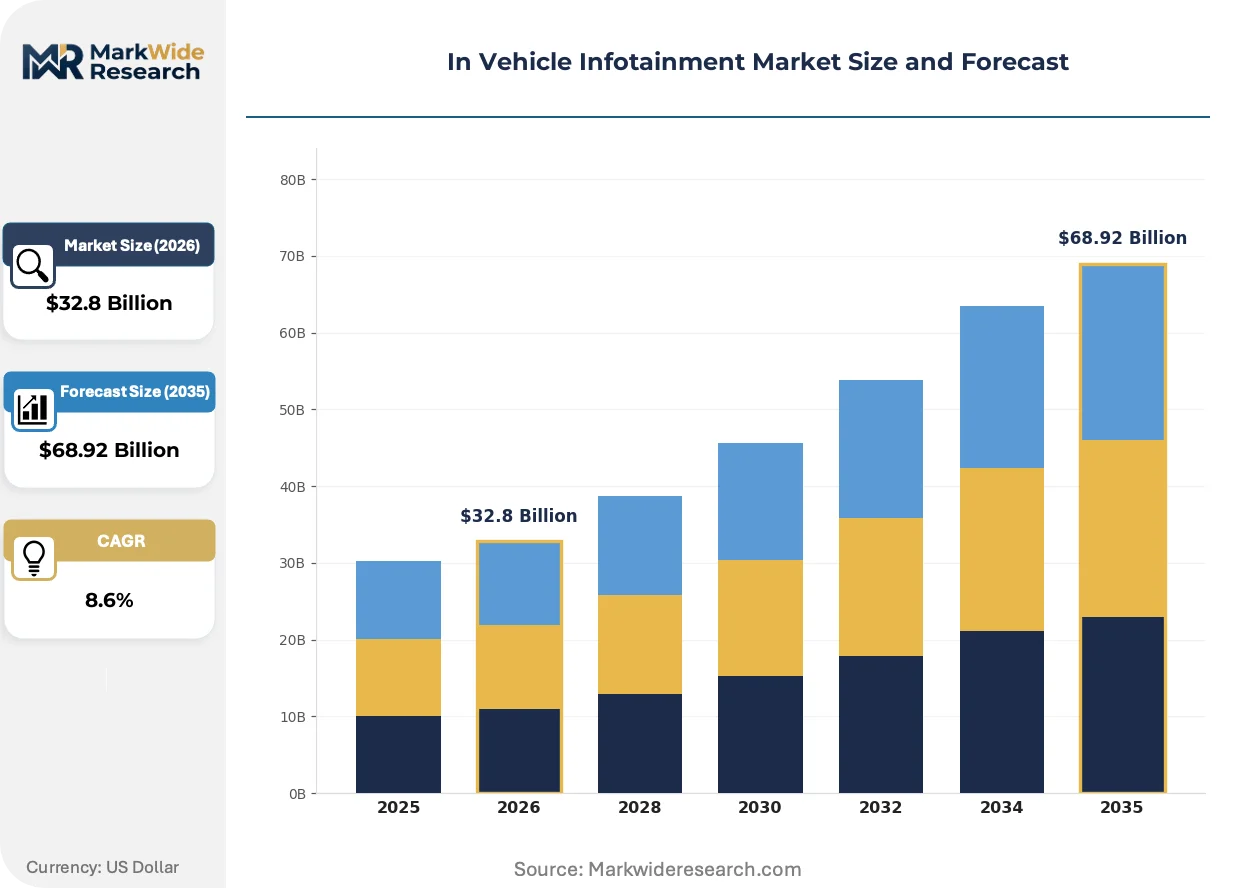
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $68.92 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Audio Systems, Smartphone Integration, Display Systems Technology: Android Auto, Apple CarPlay, Bluetooth, Wi-Fi Direct End User: OEMs, Aftermarket Providers, Fleet Operators, Car Rentals Distribution Channel: Online Retailers, Direct Sales, Specialty Stores, Automotive Dealerships |
| Companies Covered | Harman International, Panasonic Corporation, Continental AG, Robert Bosch GmbH, Alps Alpine Co., Ltd., Denso Corporation, Alpine Electronics, Pioneer Corporation, Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vehicle Infotainment Market Strategic Shifts & Innovations
Convergence between consumer electronics interfaces and automotive safety requirements is compressing design cycles while elevating hardware performance thresholds across all vehicle classes.
Hypervisor-based domain consolidation is migrating from prototype fleets to production programs as automakers seek to reduce ECU count and wiring harness complexity. German and Japanese OEMs are deploying single-SoC architectures spanning instrument cluster, center stack, and passenger displays. This consolidation is compressing tier-one hardware margins while expanding software licensing revenue pools.
Europe's CSRD sustainability disclosure requirements are mandating lifecycle carbon accounting for infotainment hardware, forcing suppliers to document Scope 3 emissions from rare earth extraction through end-of-life recycling. Display panel manufacturers serving French and German OEMs are accelerating low-temperature polysilicon process adoption to meet embodied carbon thresholds.
Fleet operators and ride-hailing platforms are unbundling infotainment specifications from base vehicle procurement, creating direct supplier relationships for driver-facing productivity tools. This disintermediation is most visible in California and Texas, where commercial EV deployments are specifying custom HMI configurations independent of OEM standard offerings.
In Vehicle Infotainment Market Segmentation
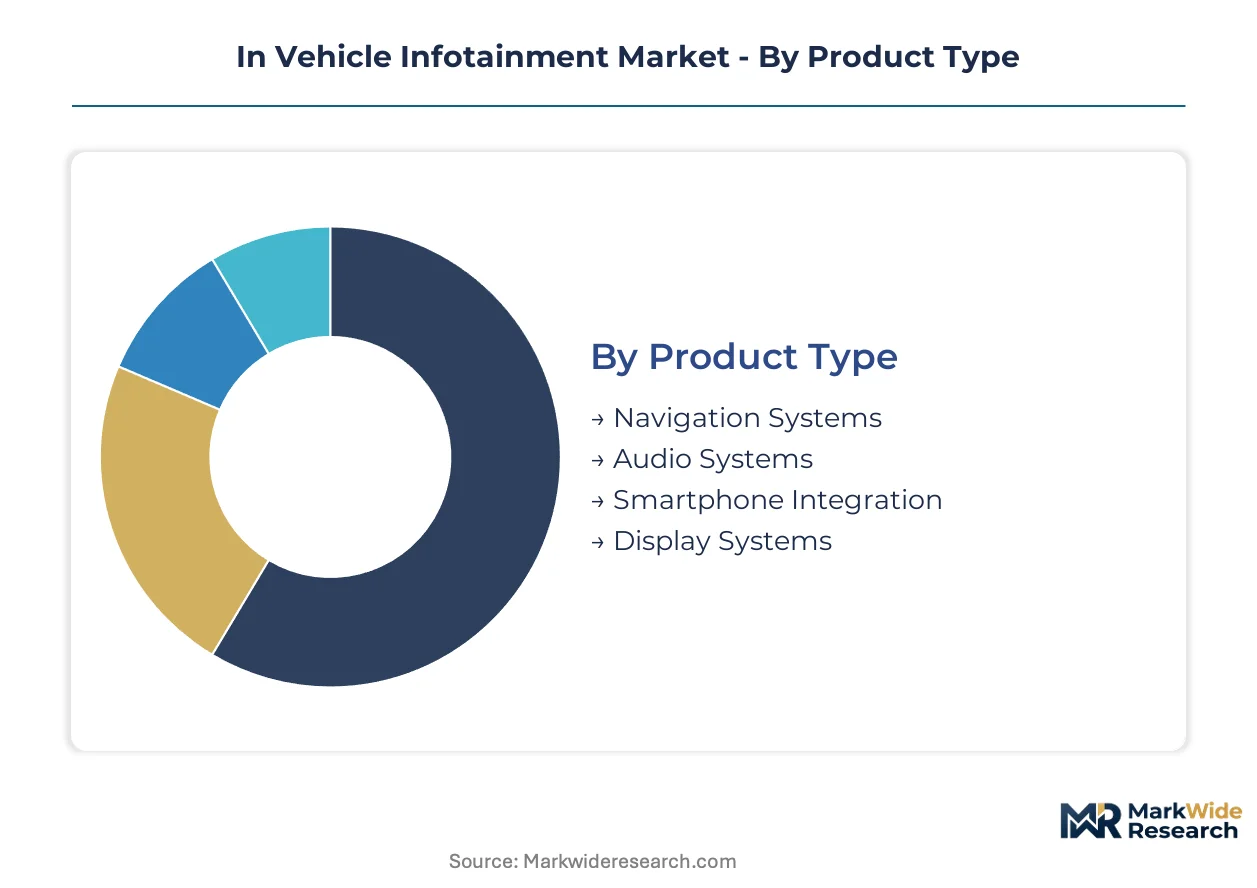
In vehicle infotainment segmentation reflects divergent technology maturities and procurement pathways across automotive supply chains. Distinct hardware-software bundles, connectivity protocols, and channel structures create specialized competitive arenas with unique margin profiles and certification requirements.
Product Type:
Mature dashboard digitization converges with emerging rear-cabin entertainment and augmented reality navigation layers across this hardware-centric category.
- Display Systems:Multi-panel configurations spanning 12-inch instrument clusters through 17-inch center-stack touchscreens dominate bill-of-materials allocation in premium vehicle programs. German and Japanese OEMs specify OLED and low-temperature polysilicon LCD technologies to meet CSRD embodied carbon thresholds while sustaining sunlight readability. Demand concentrates in electric vehicle platforms where screen real estate substitutes for conventional controls.
- Navigation Systems:Embedded GNSS receivers with real-time traffic overlay and predictive routing algorithms retain stickiness despite smartphone displacement in entry segments. China mandates BeiDou constellation compatibility for domestic market homologation, forcing chipset diversification beyond GPS-GLONASS dual-mode architectures. Fleet operators in Texas and California specify custom mapping layers for commercial route optimization independent of OEM standard offerings.
- Audio Systems:Multi-channel amplifiers with active noise cancellation and spatial audio processing defend margin in luxury configurations.
- Smartphone Integration:Mirroring protocols and wireless casting modules bridge consumer device ecosystems with vehicle HMI layers.
Display Systems retains volume leadership; Navigation Systems holds the steepest expansion curve.
Technology:
Consumer electronics platform dominance collides with automotive functional safety requirements across connectivity protocol selection.
- Android Auto:Google Automotive Services integration enables over-the-air application deployment and voice-controlled media streaming through vehicle-native interfaces. Indian and Brazilian OEMs leverage Android Automotive OS full-stack licensing to accelerate development timelines amid embedded software talent scarcity. NHTSA distraction guidelines constrain notification prioritization algorithms and glance-time budgeting in US-market implementations.
- Apple CarPlay:iOS ecosystem lock-in drives specification in North American and Western European premium segments where iPhone penetration exceeds sixty percent. Wireless certification through FCC Part 15 and ETSI standards bodies adds six-to-nine month lead times for module approval. BMW and Mercedes-Benz programs specify dual-protocol support to avoid alienating either user base.
- Bluetooth:Audio streaming and hands-free telephony protocols sustain ubiquity across all vehicle classes as baseline connectivity.
- Wi-Fi Direct:High-bandwidth device-to-device content mirroring enables rear-seat entertainment and over-the-air update sideloading.
Apple CarPlay captures premium specification density; Android Auto climbs fastest in mass-market penetration.
End User:
Direct OEM procurement authority fragments as fleet operators and mobility platforms disintermediate traditional supply relationships.
- OEMs:Volkswagen, Toyota, and Ford retain volume absorption leadership through integrated cockpit program specifications spanning hardware, software, and connectivity bundles. Tier-one suppliers face margin compression as automakers reclaim user experience layer control and over-the-air update pipeline ownership. ASIL-B functional safety certification requirements for instrument cluster integration inflate development budgets and squeeze mid-tier system suppliers.
- Fleet Operators:Uber, Lyft, and commercial EV logistics platforms unbundle infotainment specifications from base vehicle procurement in California and Texas deployments. Custom driver-facing productivity tools and passenger entertainment configurations create direct supplier relationships bypassing OEM standard offerings. This disintermediation accelerates as software-defined vehicle architectures enable post-purchase feature activation.
- Aftermarket Providers:Retrofit demand extends replacement cycles beyond traditional five-to-seven year windows in Japan's aging fleet.
- Car Rentals:Standardized HMI configurations and telematics integration dominate procurement criteria for fleet refresh programs.
OEMs retain volume leadership; Fleet Operators command the steepest expansion trajectory.
Distribution Channel:
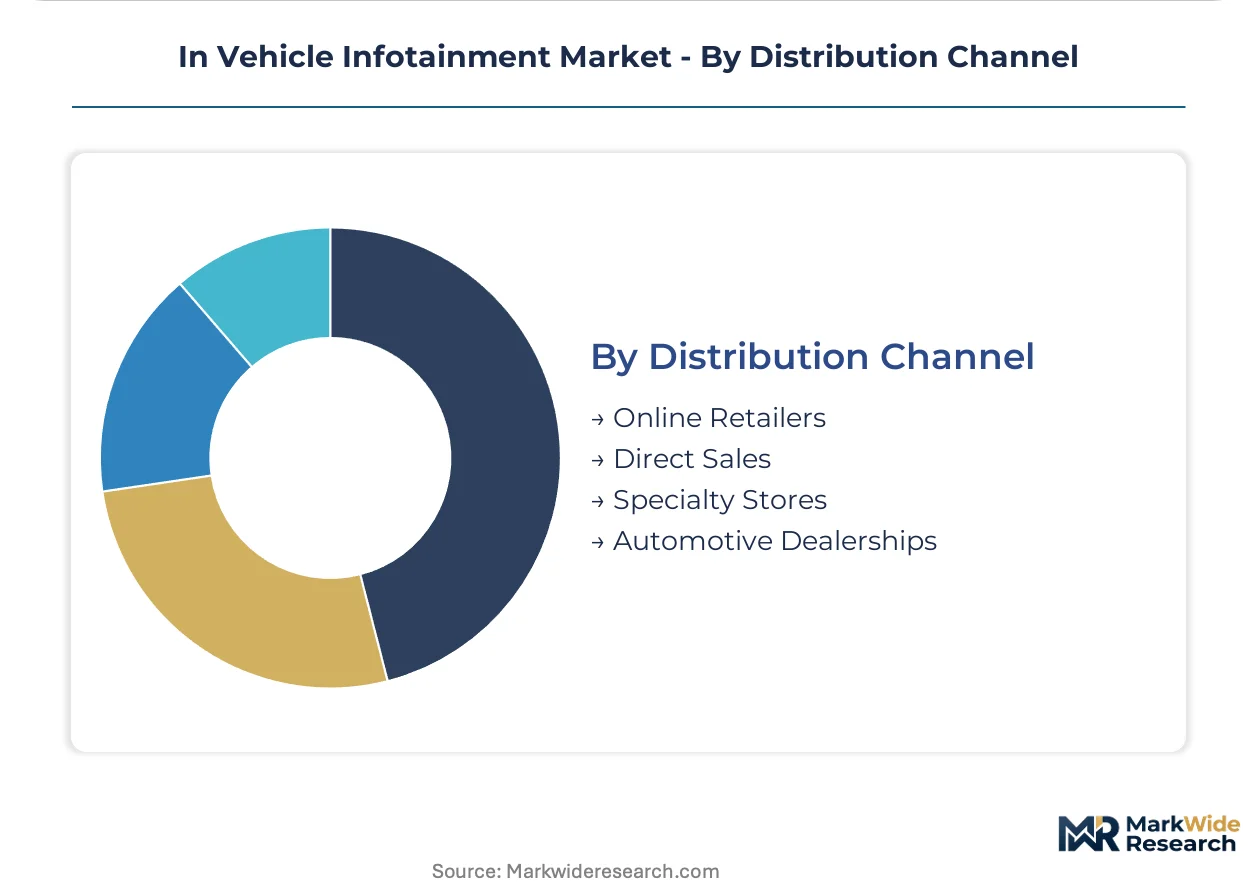
Physical retail persistence competes with direct digital procurement pathways across component and system sales.
- Automotive Dealerships:Franchise networks handle warranty-integrated upgrades and factory-option specification during new vehicle purchase. German OEM dealer contracts mandate exclusive infotainment accessory distribution to protect brand experience consistency. Service bay capacity constraints limit retrofit installation throughput during peak demand periods.
- Direct Sales:Tier-one suppliers including Harman International and Visteon Corporation pursue direct OEM relationships for integrated cockpit program awards. Samsung ecosystem leverage enables Harman to bundle semiconductor, display, and audio components across multiple automotive customer programs. Contract structures emphasize software licensing recurring revenue over hardware unit margins.
- Online Retailers:Amazon and specialized automotive e-commerce platforms capture consumer-direct replacement and upgrade demand.
- Specialty Stores:Installer networks concentrate in aftermarket audio and navigation retrofit services for vehicle aging segments.
Automotive Dealerships retains volume leadership; Direct Sales gains share fastest in integrated program awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports integrated cockpit systems to North American premium OEMs, while Japan supplies display modules to European and Asian vehicle programs. Taiwan-based foundries ship advanced SoCs to assembly plants across multiple continents.
United States
Fleet operators in California and Texas unbundle infotainment specifications from base vehicle procurement for commercial EV deployments. NHTSA distraction guidelines constrain interface interaction time limits and glance-duration budgeting. Detroit-area engineering centers concentrate OEM program management for integrated cockpit development.
Germany
Premium vehicle production clusters drive demand for multi-panel OLED and low-temperature polysilicon LCD configurations. ECE R10 electromagnetic compatibility standards shape hardware certification requirements for export-bound systems. Bavaria-based suppliers anchor European manufacturing scale in infotainment control units.
Japan
Extended vehicle lifecycles expand aftermarket infotainment replacement cycles beyond traditional five-to-seven year windows. METI standards frameworks govern connected vehicle data handling and cybersecurity provisions. Nagoya-area electronics manufacturers specialize in digital cluster integration and audio processing hardware.
China
Domestic EV platforms substitute screen real estate for conventional controls, accelerating dashboard digitization across vehicle classes. MIIT mandates BeiDou constellation compatibility for navigation system homologation. Yangtze River Delta assembly plants concentrate 5G-V2X connectivity module production for local and export markets.
India
Production-linked incentive structures for semiconductor assembly attract component localization investments from global tier-one suppliers. BIS certification requirements govern automotive electronics safety and electromagnetic compatibility. Tamil Nadu and Karnataka manufacturing corridors host display panel and connectivity module assembly operations.
In Vehicle Infotainment Market Key Industry Players
On the supply side, the industry is consolidating around integrated hardware-software bundles as automakers reduce supplier counts for cockpit programs. Tier-one relationships fragment along domain specialization lines, with distinct competitive arenas forming around display systems, audio processing, and connectivity modules. Two strategic archetypes dominate: diversified electronics conglomerates leveraging parent ecosystem resources, and focused automotive specialists defending position through functional safety certification depth. Competitive moves center on direct OEM relationship cultivation and software licensing revenue model expansion.
Within the diversified electronics tier, Harman International and Panasonic Corporation exemplify parent-ecosystem leverage strategies, while Continental AG occupies a position representing European manufacturing scale archetypes. Harman International anchors integrated hardware-software development across multiple OEM programs through Samsung ecosystem access. Panasonic Corporation sits within Japanese conglomerate structures that span consumer electronics and automotive verticals. Continental AG represents the European fabrication specialist model with concentrated infotainment control unit production.
| Leading Market Players |
|---|
| Harman International |
| Panasonic Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Alps Alpine Co., Ltd. |
| Denso Corporation |
| Alpine Electronics |
| Pioneer Corporation |
| Visteon Corporation |
| Others |
Cost & Logistics Intelligence
Taiwan-based foundry concentration for automotive-grade SoCs concentrates margin capture upstream, forcing tier-one suppliers to defend position through software licensing revenue models downstream. Display panel procurement from Korean and Chinese manufacturers further fragments pricing power across the value chain.
Pricing Analysis
Next-generation OLED and low-temperature polysilicon LCD modules command substantial premiums over incumbent a-Si LCD configurations, while legacy TN panel pricing erodes in aftermarket replacement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-B certification grade and display resolution tiers. Cost compression in mid-tier instrument cluster integration intensifies because OEMs are reclaiming user experience layer control. Fleet operators exhibit highest price sensitivity due to volume procurement scale, while luxury OEMs prioritize performance over unit cost.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs are squeezing working capital for tier-one infotainment control unit suppliers, accelerating supply-chain finance facility adoption. Component sourcing draws from Taiwan for advanced SoCs, South Korea for OLED display substrates, and China for connectivity module assembly. Rare earth elements for display phosphors and lithium for battery-backed systems create raw material dependencies. Single-source vulnerability around Taiwan-based foundry capacity constitutes the dominant structural risk. Distribution runs through direct OEM program awards rather than aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are multiplying as fleet operators and mobility platforms disintermediate traditional OEM supply relationships, creating direct procurement channels for specialized HMI configurations.
For Market Incumbents: Pre-empt disintermediation by deepening direct fleet operator relationships before mobility platforms consolidate procurement authority. Secure ASIL-B certification depth in instrument cluster integration to defend against software-defined vehicle architecture entrants. Backward integration into display panel sourcing from Korean manufacturers reduces exposure to foundry concentration.
For New Entrants and Emerging Players: Establish a beachhead in rear-seat entertainment convergence for luxury and family vehicle configurations where content monetization channels remain underdeveloped. Target India's PLI scheme corridors for semiconductor assembly localization to bypass incumbent supply relationships. Lead with streaming service integration partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward tier-one suppliers with demonstrated Android Automotive OS and QNX expertise, as embedded software talent scarcity extends development timelines across the industry. Long-term viability favors specialists with functional safety certification depth and direct OEM program relationships. Monitor 5G-V2X infrastructure deployment timelines in China and Germany as the critical inflection signal for connectivity module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Direct control over OTA update pipelines shifts margin from hardware to software licensing. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts component localization investments from global tier-one suppliers. |
| Platform Standardization | Hypervisor-based domain consolidation reduces ECU count and compresses tier-one hardware margins. |
| Battery Supply Agreement | Electric vehicle platforms substitute screen real estate for conventional controls, elevating display demand. |
| Charging Infrastructure Partnership | Commercial EV deployments in California and Texas unbundle infotainment specifications from base vehicle procurement. |
Research Approach
A standing panel of OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations managers provided ongoing calibration across primary fieldwork. Secondary validation drew from vehicle production databases, IHS Markit registration data, FCC certification filings, and ECE R10 homologation records. Bottom-up segment modeling triangulated against top-down market sizing from automotive electronics trade associations.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions spanned product type, connectivity protocol, end-user archetype, and regional production cluster. CAGRs derived from fitted growth curves applied to volume and value baselines. Forecast inputs incorporated 5G-V2X deployment mandates, CSRD embodied carbon thresholds, and NHTSA distraction guideline evolution.
Sensitivities concentrate around semiconductor supply disruption, cybersecurity regulatory divergence, and fleet operator procurement consolidation. Forecasts embed assumptions regarding software-defined vehicle architecture adoption rates and embedded software talent availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Electric Vehicle Infotainment Market