
 Video Telematics Market | 2026-2036
Video Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Video Telematics Market Analysis
The EU AI Act is rebalancing compliance costs for video telematics vendors selling into European commercial fleet markets. Netradyne leverages its edge-AI architecture to process driver behavior analytics without cloud dependency, reducing latency for real-time coaching alerts. Samsara anchors its position through integrated fleet management software that bundles video telematics with vehicle diagnostics and dispatch optimization. Geotab competes on open-platform connectivity, allowing third-party camera hardware to feed unified data lakes for insurance and safety scoring.
Video telematics systems combine onboard cameras, GPS receivers, accelerometers, and cellular modems to capture, transmit, and analyze driver-facing and road-facing video streams with location and kinematic metadata. These systems primarily serve commercial fleet operators seeking objective documentation of incidents, automated risk scoring, and real-time intervention capabilities to reduce collision frequency and severity. Cloud-based platforms currently lead solution-type deployment due to lower capital requirements and scalable storage architectures, while AI analytics represents the fastest-growing technology segment as machine learning models improve at detecting distracted driving, fatigue, and near-miss events without human review. Integrated systems command premium positioning by unifying video, telematics, and fleet management workflows, though mobile solutions gain traction among smaller operators prioritizing deployment speed and minimal infrastructure.
The US Department of Transportation, through FMCSA hours-of-service enforcement, and the European Commission, through the General Safety Regulation mandating advanced driver assistance and event data recording, collectively shape product certification requirements and procurement timelines for fleet technology buyers. ELD compliance deadlines in North America and EU-type approval processes for intelligent speed assistance and driver drowsiness detection are compressing vendor development cycles and expanding addressable market boundaries. Stakeholders must monitor divergent regulatory trajectories across jurisdictions, as fragmentation in data privacy standards for biometric driver monitoring threatens to complicate single-platform global deployment strategies.
Market Dynamics
Commercial fleet operators face simultaneous pressure from insurance carriers demanding granular risk data and regulators mandating intelligent driver monitoring systems. Edge-AI processing architectures are compressing hardware refresh cycles as vendors race to deliver real-time coaching without cloud latency penalties.
Growth Catalysts
- EU General Safety Regulation:Mandates for intelligent speed assistance and driver drowsiness detection are forcing commercial vehicle retrofits across German, French, and Italian logistics corridors.
- Commercial auto liability:Insurance carriers now require objective incident documentation for policy renewal, accelerating dashcam deployment among long-haul trucking fleets.
- Edge computing:Onboard GPU acceleration enables real-time distracted-driving detection without cellular connectivity dependency, reducing operational costs for rural route operators.
Market Restraints
- Semiconductor supply concentration:GPU and image sensor fabrication concentrates in Taiwanese and South Korean foundries, exposing vendors to geopolitical supply interruptions.
- Cellular data cost volatility:Fleet operators face unpredictable bandwidth expenses from high-resolution video uploads, compressing margins on fixed-fleet-management contracts.
- Biometric privacy friction:GDPR and emerging US state privacy laws restrict driver-facing camera analytics, limiting behavioral scoring deployment in cross-border operations.
Strategic Opportunities
- Last-mile delivery electrification:E-commerce van fleets in India and Brazil remain underpenetrated by integrated video-telematics systems, offering greenfield deployment potential.
- Usage-based insurance convergence:Telematics data streams are merging with parametric insurance pricing models, creating embedded revenue sharing with underwriters.
- 5G-V2X integration:Vehicle-to-everything communication protocols are enabling predictive collision alerts by fusing dashcam vision with roadside infrastructure data.
Industry Challenges
- Computer vision engineering scarcity:Fleet technology vendors compete aggressively for machine learning specialists capable of optimizing edge inference on thermal-constrained automotive hardware.
- Multi-jurisdiction certification complexity:FMCSA ELD compliance, EU type-approval processes, and divergent data residency requirements fragment product roadmaps and delay launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Telematics Market |
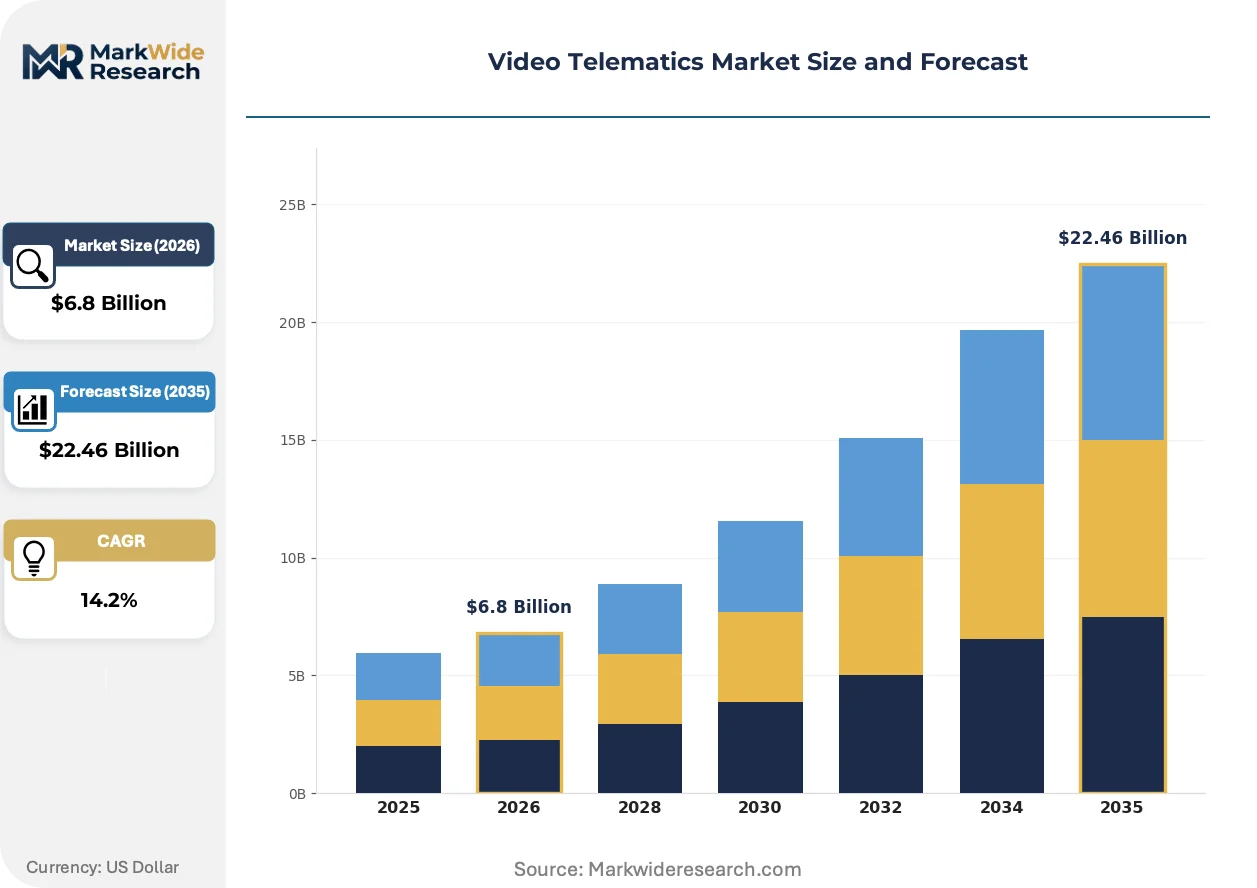
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Integrated Systems, Mobile Solutions, Cloud-Based Platforms, Hybrid Solutions End User: Commercial Fleets, Insurance Companies, Public Transport, Logistics Providers Technology: GPS Tracking, AI Analytics, Real-Time Monitoring, Video Capture Application: Driver Safety, Fleet Management, Accident Reconstruction, Insurance Claims |
| Companies Covered | Netradyne, Omnitracs, Verizon Connect, Geotab, SmartWitness, Samsara, SmartDrive, MiX Telematics, Lytx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Telematics Market Emerging Trajectories
Video telematics is pivoting from passive incident recording toward predictive risk intervention systems. Three concurrent developments are compressing vendor differentiation windows and reshaping procurement criteria.
Edge-AI inference engines are unifying driver behavior analytics, vehicle diagnostics, and cargo monitoring onto single onboard compute modules. Large national trucking fleets are adopting these consolidated platforms to eliminate multiple hardware installations per cab. This convergence is collapsing the addressable market for standalone dashcam vendors without integrated fleet management software stacks.
The EU AI Act's risk-classification framework for biometric identification systems is forcing equipment redesigns before 2026 enforcement deadlines. Vendors must now document algorithmic transparency and human oversight protocols for driver-facing cameras sold into European markets. German and Dutch fleet operators are accelerating procurement to complete deployments ahead of certification bottlenecks.
Fleet procurement departments are consolidating vendor relationships around full-stack platform providers rather than best-of-breed point solutions. Small and mid-sized operators previously buying dashcams through equipment distributors now contract directly with telematics platforms offering bundled hardware, software, and cellular connectivity. This channel compression is most visible in the United States, where Amazon Relay and other digital freight brokers are embedding video telematics into carrier onboarding requirements.
Video Telematics Market Segmentation
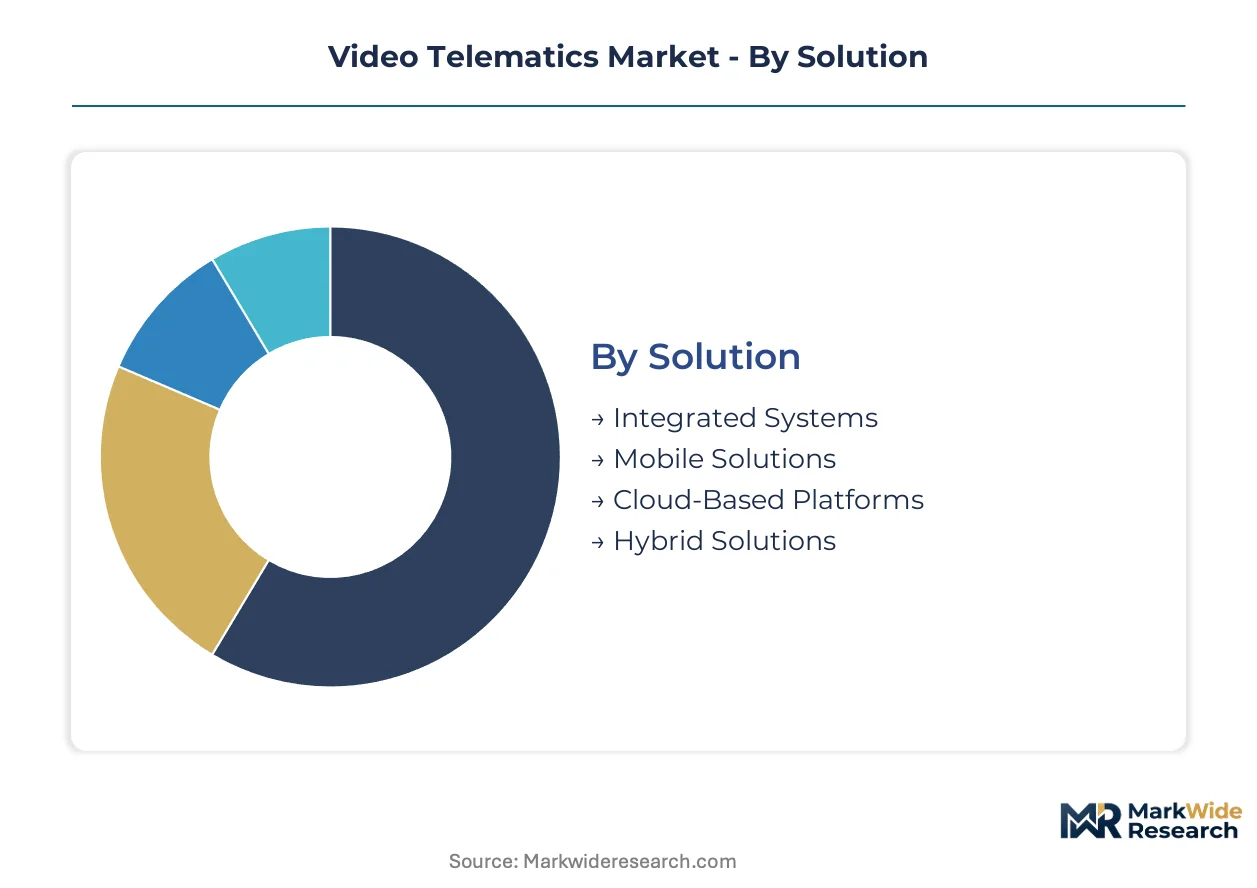
Video telematics procurement patterns diverge sharply across fleet size, regulatory exposure, and IT infrastructure maturity. Buyers select solution architectures and technology bundles based on collision liability thresholds, driver turnover rates, and existing fleet management system investments.
Solution:
Fleet operators differentiate primarily by capital deployment preference and integration complexity tolerance.
- Cloud-Based Platforms:These architectures centralize video storage, AI processing, and fleet dashboards on vendor-managed infrastructure. Demand concentrates among mid-sized US trucking fleets seeking predictable operating expenditures and minimal on-premise IT overhead.
- Integrated Systems:Unified hardware-software stacks combine dashcams, telematics gateways, and fleet management software from single vendors. Large European logistics operators in Germany and France prioritize these for streamlined EU AI Act compliance certification and consolidated vendor relationships.
- Mobile Solutions:Smartphone-dependent deployments leverage driver devices for video capture and cellular transmission. Small last-mile operators in India and Brazil favor rapid rollout without dedicated hardware procurement.
- Hybrid Solutions:Split architectures process critical safety events at the edge while archiving non-urgent footage to cloud repositories. Rural North American fleets with intermittent cellular coverage adopt these to balance real-time alerting against bandwidth constraints.
Cloud-based platforms lead volumes today; integrated systems are gaining share fastest.
End User:
Procurement authority and risk ownership shape technology requirements across buyer categories.
- Commercial Fleets:Trucking, delivery, and service vehicle operators purchase directly to reduce insurance premiums and DOT violation exposure. Long-haul carriers in Texas and California dominate hardware volumes, driven by FMCSA hours-of-service enforcement and nuclear verdict liability concerns.
- Insurance Companies:Underwriters deploy video telematics as policy condition or claims verification tool. US commercial auto carriers increasingly mandate dashcam installation for fleet policy renewal, compressing procurement timelines.
- Logistics Providers:Third-party freight brokers and warehousing operators extend visibility to subcontracted carriers. Digital freight platforms embed video requirements into carrier onboarding, standardizing safety documentation across dispersed vehicle bases.
- Public Transport:Municipal bus and rail agencies deploy driver-facing and passenger-facing systems for incident documentation and operator protection. European cities face accelerated replacement cycles under EU General Safety Regulation mandates.
Commercial fleets anchor current demand; insurance company procurement is climbing the fastest.
Technology:
Capability sophistication and processing location determine competitive positioning within each technology layer.
- AI Analytics:Machine learning models detect distracted driving, fatigue, and collision precursors from video streams. Edge-AI deployments in German and Dutch fleets process inference locally to satisfy GDPR biometric restrictions while enabling real-time coaching alerts.
- GPS Tracking:Location telemetry fused with video metadata enables geofenced incident reconstruction and route optimization. This foundational layer sees stable demand across all fleet sizes but commands diminishing premium pricing as commoditization advances.
- Real-Time Monitoring:Live video streaming and instant alert distribution to dispatch centers. High-value cargo operators and passenger transport authorities prioritize these capabilities for immediate incident response.
- Video Capture:Onboard recording hardware encompassing road-facing, driver-facing, and cabin cameras. Resolution and storage specifications stratify by fleet risk profile, with 1080p dual-camera configurations becoming baseline for commercial auto insurance compliance.
Video capture dominates installed base; AI analytics shows the steepest expansion trajectory.
Application:
Use case priority determines feature bundling and pricing tier selection during procurement.
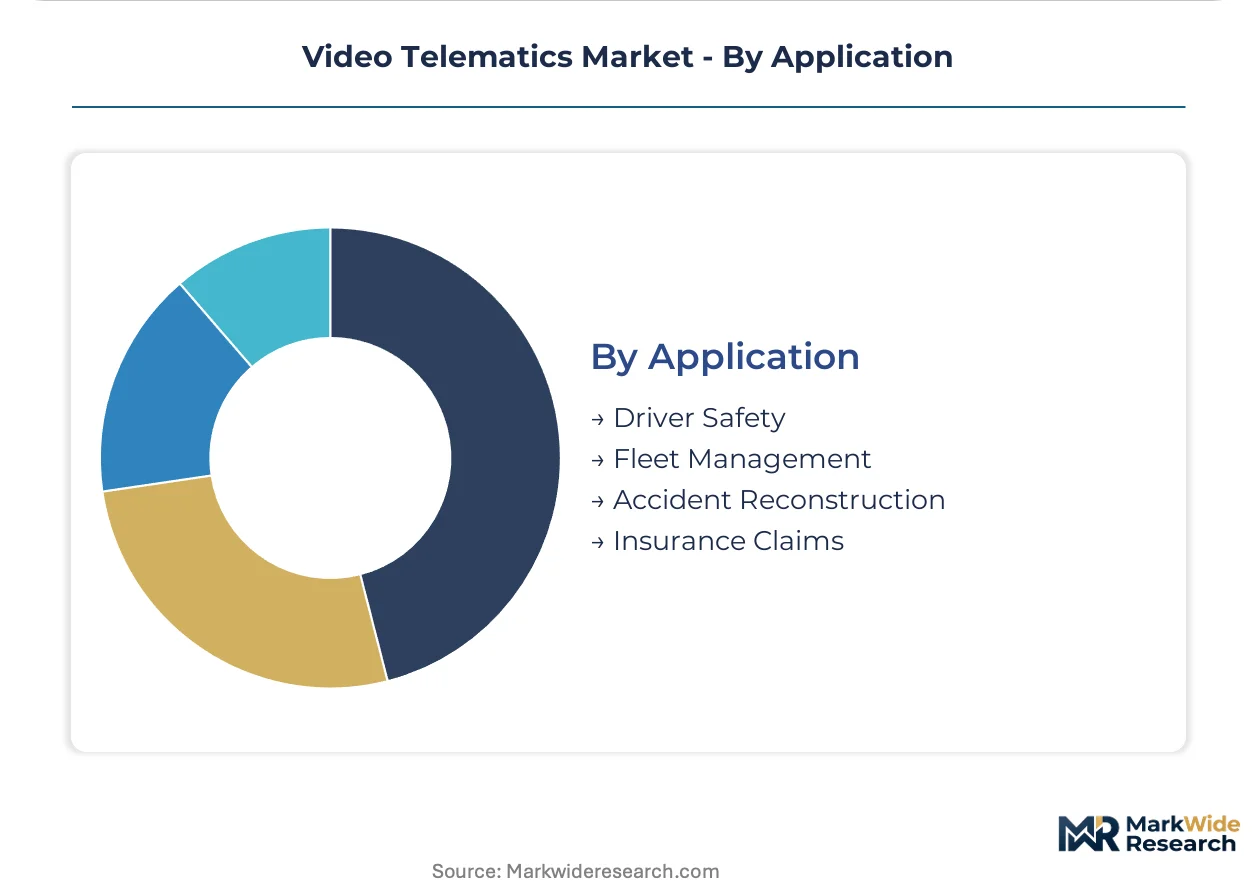
- Driver Safety:Behavior scoring, coaching workflows, and incentive programs targeting collision reduction. US for-hire trucking fleets allocate largest budgets here, linking telematics data to driver retention bonuses and insurance dividend programs.
- Fleet Management:Unified dispatch, maintenance scheduling, and compliance documentation. European logistics corridors prioritize these integrated workflows to streamline cross-border regulatory reporting under divergent national transport authorities.
- Accident Reconstruction:High-resolution video with kinematic data for liability determination and litigation defense. Nuclear verdict exposure in US jurisdictions drives premium pricing for extended storage and legal-grade chain-of-custody features.
- Insurance Claims:Automated first notice of loss and fraud detection through video verification. Parametric insurance pilots in Brazil and India embed these capabilities directly into policy pricing models.
Driver safety commands current spending; insurance claims integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Silicon Valley, Munich, and Bangalore anchor video telematics innovation clusters. Fleet density and regulatory enforcement intensity determine regional adoption velocity.
United States
Long-haul trucking fleets in Texas and California drive hardware volumes under FMCSA hours-of-service enforcement. Nuclear verdict liability exposure accelerates dashcam deployment for litigation defense. The Dallas-Fort Worth logistics corridor concentrates telematics platform engineering and fleet management software development.
Germany
Commercial vehicle OEMs and logistics operators face compressed upgrade cycles under EU General Safety Regulation mandates. The KBA enforces type-approval processes for intelligent speed assistance and driver drowsiness detection systems. Stuttgart and Munich host edge-AI engineering clusters optimizing inference for thermal-constrained automotive hardware.
United Kingdom
Insurance carriers mandate objective incident documentation for commercial auto policy renewal. The Department for Transport aligns enforcement with EU-derived safety standards while adapting post-Brexit certification pathways. The Midlands logistics belt concentrates last-mile delivery fleet operators deploying integrated telematics stacks.
India
E-commerce van fleets in Maharashtra and Karnataka remain underpenetrated by integrated video-telematics systems. The Ministry of Road Transport and Highways advances vehicle tracking mandates for commercial vehicles under AIS-140 standards. Bangalore anchors machine learning engineering talent for computer vision model development.
Brazil
Parametric insurance pilots embed telematics data directly into commercial fleet pricing models. ANVISA and national transport regulators advance vehicle safety monitoring requirements for interstate cargo operations. São Paulo's logistics corridor concentrates digital freight broker platforms standardizing carrier safety documentation.
Video Telematics Market Vendor Landscape
The competitive structure tilts toward full-stack platform providers over standalone hardware vendors. Tier-one fleet management software companies absorb video telematics functionality into bundled offerings. Three archetypes dominate: edge-AI specialists, integrated fleet management platforms, and open-platform connectivity providers. Consolidation accelerates through strategic acquisitions and technology licensing arrangements as vendors race to unify driver behavior analytics with vehicle diagnostics.
Within the integrated platform tier, Samsara and Geotab exemplify full-stack positioning, while Netradyne occupies a specialist position in edge-AI inference architectures. These companies represent divergent technical approaches to real-time driver coaching and regulatory compliance certification. Verizon Connect anchors a connectivity-first archetype leveraging telecommunications infrastructure for fleet data transmission.
| Leading Market Players |
|---|
| Netradyne |
| Omnitracs |
| Verizon Connect |
| Geotab |
| SmartWitness |
| Samsara |
| SmartDrive |
| MiX Telematics |
| Lytx |
| Others |
Supply Flow & Price Mechanics
Large European logistics operators concentrated in German and French freight corridors drive bundled platform procurement, locking in subscription-based SaaS pricing with hardware-as-a-service add-ons. This buyer concentration shifts pricing power toward full-stack vendors capable of consolidating video telematics, fleet management software, and cellular connectivity into single vendor relationships.
Pricing Analysis
Bundled platform subscriptions versus standalone hardware purchases split the pricing landscape across fleet size tiers. Three-tier pricing structure across enterprise, mid-market, and small-operator levels reflects integration depth and AI analytics inclusion, with certification grade for EU AI Act compliance commanding premium positioning. Cost compression in mid-market segments intensifies as Samsara and Geotab compete for multi-year fleet contracts. Small last-mile operators in India and Brazil exhibit highest price sensitivity, driving mobile-first deployment models.
Supply Chain Analysis
Reverse-logistics flows for dashcam hardware refurbishment remain underdeveloped, creating aftermarket service gaps as fleets accelerate refresh cycles. GPU and image sensor fabrication concentrates in Taiwan and South Korea, drawing from specialized semiconductor foundries and CMOS sensor foundries. Single-source vulnerability in advanced automotive-grade processors exposes vendors to geopolitical disruption. Distribution runs through direct enterprise sales teams for large fleets and telematics platform partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in video telematics rests on edge-AI chip cost curves flattening and premium-tier integrated systems capturing larger share of fleet IT budgets. Vendors achieving certification velocity under EU AI Act timelines capture pricing power from compliance-constrained competitors.
For Market Incumbents: Acquire edge-AI engineering talent pools to consolidate real-time inference capabilities before 2026 enforcement deadlines. Incumbents must defend against standalone dashcam vendors pivoting toward integrated platforms by accelerating hardware-software bundling and securing exclusive cellular connectivity partnerships with Verizon Connect archetypes. For New Entrants and Emerging Players: The mid-market pricing gap between Samsara-tier premium platforms and mobile-only solutions creates white-space opportunity for hybrid edge-cloud architectures. New entrants should target underpenetrated e-commerce van fleets in São Paulo and Mumbai with rapid-deployment kits bundling third-party cameras with proprietary AI analytics layers. For Investors and Strategic Acquirers: Fleet management software platforms are the most active acquirer in this space, seeking computer vision capabilities to complete full-stack positioning. Long-term viability favors vendors with GDPR-compliant edge processing and FMCSA certification pathways already secured. Monitor EU AI Act implementation bottlenecks at KBA and notified bodies as inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Hardware Acquisition | Netradyne's inference architecture demonstrates defensible technical moat for real-time coaching without cloud dependency. |
| EU AI Act Certification Investment | KBA type-approval processes for driver-facing cameras compress vendor development cycles and expand addressable market boundaries. |
| Cellular Connectivity Partnership | Verizon Connect leverages telecommunications infrastructure to capture fleet data transmission revenue from hardware vendors. |
| Insurance Underwriter Integration | Parametric pricing pilots in Brazil embed telematics directly into policy structures, creating recurring revenue sharing models. |
| Last-Mile Electrification Bundle | Indian e-commerce van fleets in Maharashtra present greenfield deployment opportunity for integrated video-telematics systems. |
Methodological Framework
Bottom-up commercial fleet modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with fleet operations directors, insurance underwriters, telematics platform engineers, and regulatory affairs specialists at EU notified bodies combined with secondary validation from FMCSA ELD compliance databases, EU General Safety Regulation implementation reports, and cellular carrier IoT deployment disclosures. Triangulation across stakeholder perspectives and supply-side production data ensures coverage of both demand drivers and hardware availability constraints.
Historical trendline analysis of fleet technology refresh cycles and AI adoption curves informed projection modeling across the analysis window. Segmentation dimensions include solution architecture, fleet size tier, technology layer, and application priority, with CAGRs derived from regression analysis against regulatory enforcement timelines and insurance mandate expansion. Edge-AI processing penetration rates and 5G-V2X infrastructure deployment schedules served as industry-specific forecast inputs.
Caveats apply where EU AI Act enforcement delays or semiconductor supply interruptions could materially shift the outlook. Practitioners should monitor KBA certification queue lengths and Taiwan foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market