
 Motorcycle Infotainment System Market | 2026-2036
Motorcycle Infotainment System Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Infotainment System Market Foresight
REACH compliance is shifting the cost-of-entry calculus for motorcycle infotainment suppliers targeting European riders. Garmin Ltd. leverages its deep GPS heritage to dominate navigation-centric product architectures. Bosch sustains manufacturing scale across sensor fusion and display integration for factory-installed platforms. Sena Technologies Inc. specializes in mesh communication protocols that anchor its position within the aftermarket segment.
A motorcycle infotainment system integrates audio processing, GPS navigation, wireless communication, and touchscreen or handlebar-controlled display interfaces into a unified rider-accessible platform, typically operating through CAN bus integration with the vehicle's electronic architecture and supporting Bluetooth 5.0 or higher for helmet-to-helmet connectivity. Its primary commercial purpose is to reduce rider distraction while delivering real-time route guidance, entertainment, and inter-rider communication. Navigation devices and communication modules command the strongest margin pools as these categories demand proprietary software ecosystems and recurrent map or firmware update revenue. Display units compete most intensely on screen brightness, glove-friendly touch response, and weather-sealing specifications that differentiate premium from standard tiers.
The EU's ECE R10 electromagnetic compatibility framework, the FCC's Part 15 rules in the United States, and Japan's METI radio equipment regulations collectively shape transmitter certification, spectrum allocation, and market access timelines for connected motorcycle hardware. India's BIS and CDSCO-aligned automotive electronics standards are tightening as domestic production scales, compelling suppliers to maintain parallel certification pipelines. Stakeholders must monitor how harmonization between regional radio-type approval regimes affects platform development costs and geographic rollout sequencing.
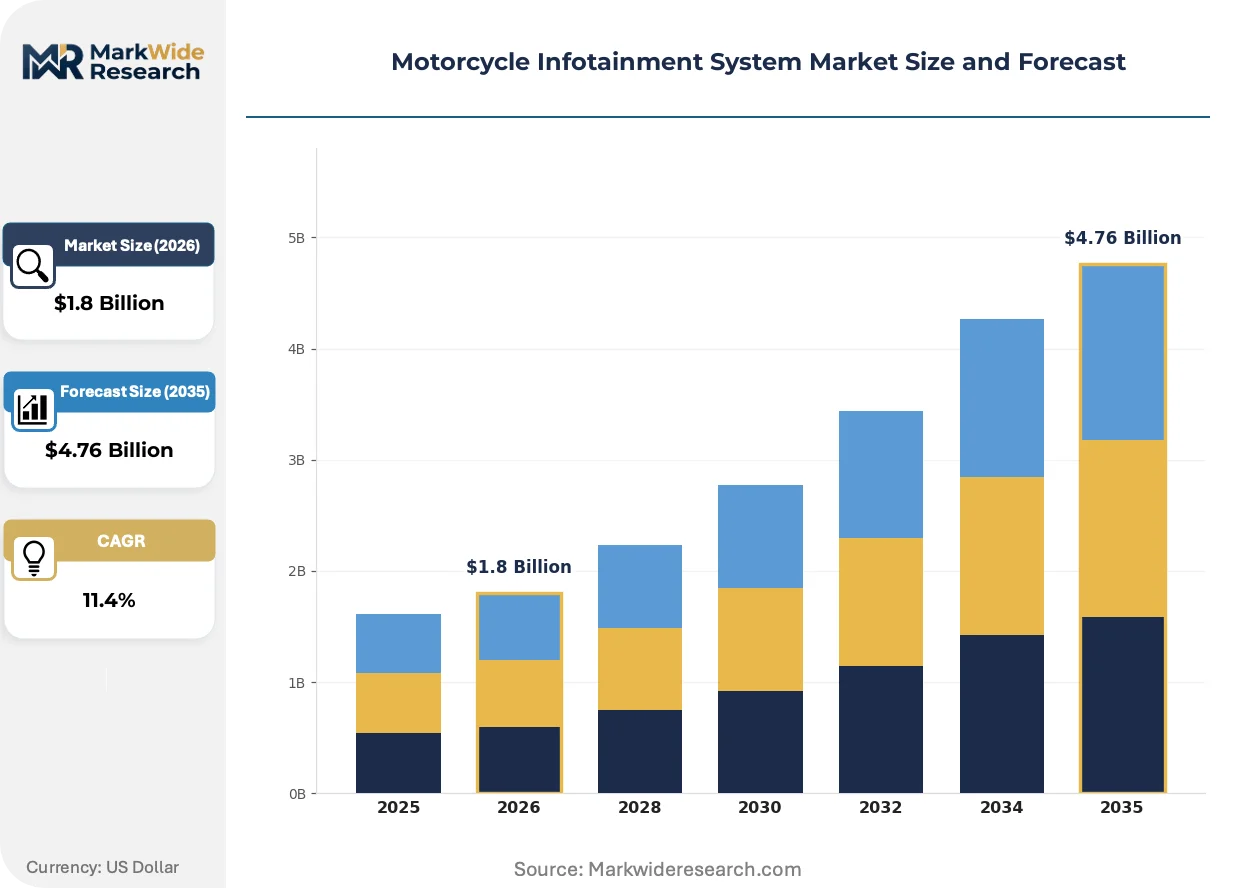
Market Dynamics
Integrated helmet-to-helmet mesh communication protocols are compressing upgrade cycles as riders demand seamless inter-bike connectivity without aftermarket installation friction, forcing OEMs to bundle factory-installed platforms into premium touring configurations.
Growth Catalysts
- ECE R10 electromagnetic compatibility standards:The EU's tightening certification framework accelerates R&D investment in shielded transmitter designs, filtering out low-tier competitors and elevating technical specifications across the supply base.
- Premium touring motorcycle segment:Long-distance riders purchasing factory-equipped touring bikes prioritize unified navigation-audio-communication platforms, creating pull-through demand for integrated infotainment architectures.
- Bluetooth 5.0 and higher protocols:Enhanced data throughput and reduced latency enable real-time helmet-to-helmet voice and music sharing, expanding the addressable rider base beyond solo commuters to group touring enthusiasts.
Market Restraints
- Display panel supply concentration:High-brightness, glove-responsive touchscreen modules rely on concentrated Asian manufacturing, exposing OEMs to input cost volatility and extended lead times during demand surges.
- F-Gas Regulation compliance burden:The EU's fluorinated gas restrictions complicate thermal management system designs for sealed outdoor-rated displays, adding certification cycles and engineering overhead.
- Smartphone mounting substitutes:Handlebar phone holders paired with consumer navigation apps capture price-sensitive riders, compressing addressable volume in the entry-tier aftermarket segment.
Strategic Opportunities
- India's domestic production scaling:BIS-aligned automotive electronics standards are tightening alongside manufacturing growth, creating first-mover advantage for suppliers establishing local certification pipelines and distribution partnerships.
- Voice-controlled interface convergence:Natural language processing integration with noise-canceling helmet microphones reduces manual touchscreen interaction, addressing safety concerns and differentiating premium platform tiers.
- Subscription-based map and firmware updates:Recurring revenue models for navigation data and feature unlocks transform one-time hardware sales into sustained customer relationships with predictable cash flows.
Industry Challenges
- Embedded software engineering scarcity:CAN bus integration expertise combined with real-time audio processing and GPS algorithm development concentrates in limited talent pools, inflating compensation and extending development timelines.
- Parallel certification pipeline management:Simultaneous FCC Part 15, METI radio equipment, and BIS compliance testing fragments engineering resources and delays geographic rollout sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Infotainment System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Systems, Navigation Devices, Communication Modules, Display Units Technology: Bluetooth, Wi-Fi, NFC, USB Connectivity End User: Motorcycle Enthusiasts, Commuters, Tourists, Commercial Riders Installation: Factory Installed, Aftermarket Kits, Custom Installations, Retrofitting |
| Companies Covered | TomTom International BV, Harley-Davidson Inc., Garmin Ltd., Sena Technologies Inc., Honda Motor Co. Ltd., Bosch, BMW AG, Polaris Inc., Harman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Infotainment System Market Shifts & Advancements
Mesh network topologies and augmented reality head-up displays are restructuring how riders consume navigation and communication data, shifting competitive advantage toward software-defined platform architectures.
Wireless mesh communication systems are overtaking traditional Bluetooth pairing as the dominant inter-rider connectivity standard. Premium touring motorcycle buyers now expect seamless multi-rider voice networks without manual re-pairing interruptions. This shift is compressing margins for legacy point-to-point communication module suppliers while rewarding firmware-centric platform vendors.
The EU's F-Gas Regulation is tightening thermal design requirements for sealed motorcycle displays exposed to extreme ambient temperatures. Manufacturers must now engineer passive cooling solutions or approved refrigerant-based systems, extending certification timelines. Factory-installed platform suppliers with established ECE R10 compliance pipelines capture disproportionate share in European markets.
Direct-to-rider digital distribution channels are displacing traditional aftermarket retail networks for firmware updates and feature subscriptions. OEMs are unbundling hardware sales from recurring service contracts, capturing lifetime value through connected platform ecosystems. This behavioral shift concentrates most visibly in Germany, where BMW and Bosch anchor integrated rider account management systems.
Motorcycle Infotainment System Market Segmentation
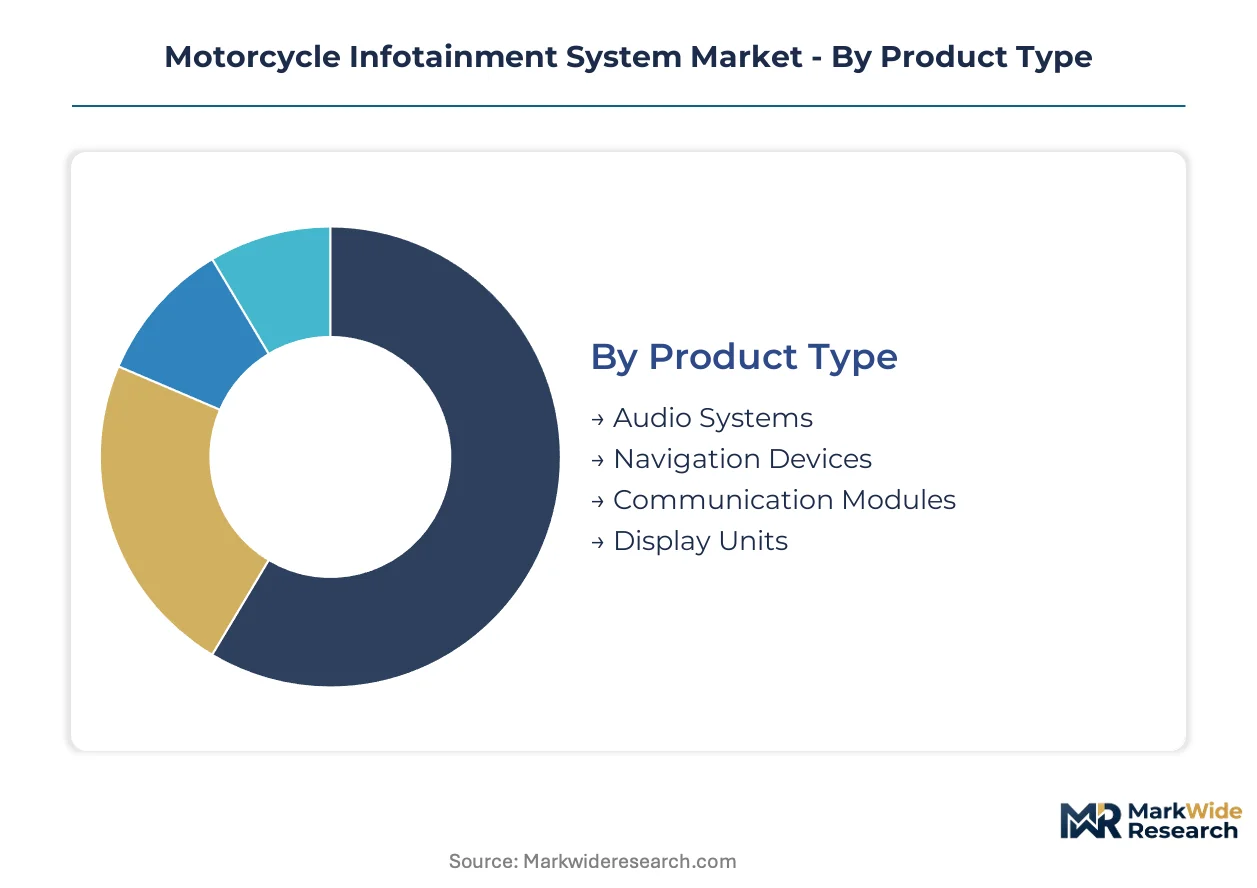
Motorcycle infotainment segmentation reflects divergent certification burdens across product architectures. ECE R10 electromagnetic compliance, F-Gas thermal management standards, and regional radio-type approvals fragment supplier strategies across hardware categories.
Product Type:
Certification intensity varies sharply: navigation devices and communication modules face ECE R10 transmitter testing and FCC Part 15 spectrum allocation, while display units contend with F-Gas thermal sealing requirements.
- Audio Systems:Multi-channel amplifiers with helmet-optimized frequency response integrate noise-canceling microphone inputs for voice command processing. Demand concentrates in Germany's premium touring segment, where BMW Motorrad factory specifications mandate CAN bus-native audio architectures with glove-friendly rotary controllers.
- Navigation Devices:GPS receivers with GLONASS and Galileo multi-constellation support operate through shock-mounted, weather-sealed enclosures rated for vibration exposure. Garmin's dominance in European touring configurations reflects proprietary map data licensing and recurrent update revenue models that hardware-only competitors cannot replicate.
- Communication Modules:Mesh network transceivers enabling helmet-to-helmet voice bridging with automatic multi-rider pairing.
- Display Units:High-brightness TFT or OLED panels with glove-responsive capacitive touch and anti-glare optical bonding.
Leading the category by volume: Display Units. Growing fastest: Communication Modules.
Technology:
Protocol selection determines geographic certification pipelines and interoperability depth with OEM electronic architectures.
- Bluetooth:Low-energy and classic audio profiles with version 5.0 or higher specification deliver helmet-to-helmet mesh connectivity with sub-40ms latency for synchronized music sharing. Sena Technologies' firmware stack dominates aftermarket adoption in North American group touring communities where multi-brand helmet compatibility is non-negotiable.
- Wi-Fi:Dual-band 802.11ac modules enabling high-speed map data downloads and over-the-air firmware updates without smartphone tethering.
- NFC:Contactless pairing initiation for rapid helmet-to-device authentication in commercial fleet deployments.
- USB Connectivity:Type-C power delivery and data interfaces supporting fast charging and wired audio fallback.
Bluetooth commands installed base dominance. Wi-Fi is climbing the fastest as OTA update architectures proliferate.
End User:
Rider archetype dictates price sensitivity, feature prioritization, and installation channel preference across market tiers.
- Motorcycle Enthusiasts:Performance-oriented riders with high technical literacy demand open-architecture platforms supporting third-party app sideloading and customizable dashboard layouts. This segment drives aftermarket premium in Germany, where club-organized touring culture rewards inter-bike communication mesh density.
- Commuters:Urban riders prioritizing compact, theft-resistant form factors with essential navigation and hands-free calling.
- Tourists:Rental fleet participants and long-distance travelers requiring intuitive interfaces with minimal learning curves.
- Commercial Riders:Delivery and courier operators integrating dispatch communication with route optimization and proof-of-delivery logging.
Commercial Riders generate steepest expansion trajectory as last-mile logistics electrification accelerates two-wheeled fleet connectivity mandates.
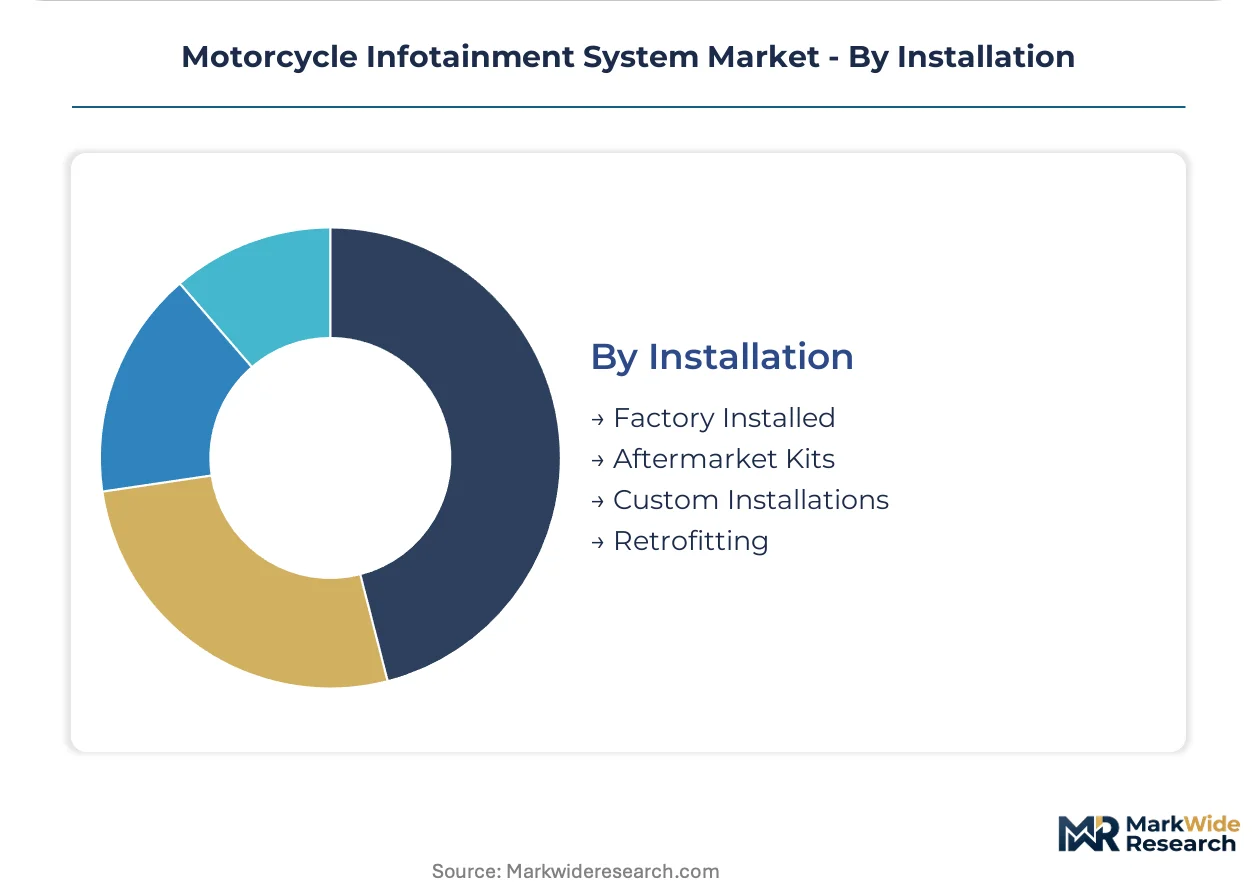
Installation:
Channel structure determines margin capture, warranty liability, and software update control for platform vendors.
- Factory Installed:CAN bus-integrated systems engineered to OEM specification with sealed harnessing and dealer-diagnostic compatibility. Bosch's manufacturing scale supplies BMW, KTM, and Ducati assembly lines, embedding sensor fusion and display integration within vehicle electronic architectures from design inception.
- Aftermarket Kits:Handlebar-mounted or fairing-integrated packages with universal wiring adapters and self-installation documentation.
- Custom Installations:Specialist-fabricated solutions for non-standard motorcycle architectures or vintage platform modernization.
- Retrofitting:Upgrade pathways adding communication or navigation capability to previously audio-only factory systems.
Factory Installed captures value concentration. Aftermarket Kits are gaining share fastest as smartphone-averse riders seek integrated alternatives to handlebar phone mounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's automotive technology corridor concentrates factory-installed infotainment engineering, while F-Gas Regulation enforcement across the European Union shapes thermal management certification pipelines for sealed outdoor displays.
Germany
Premium touring motorcycle production at BMW Motorrad and Bosch manufacturing scale anchors European demand for CAN bus-integrated navigation-audio-communication platforms. ECE R10 electromagnetic compatibility standards filter low-tier competitors from German market access. Munich and Stuttgart engineering clusters specialize in sensor fusion and glove-responsive touchscreen development for factory specifications.
United States
Group touring culture across the American West and Appalachian corridor drives aftermarket mesh communication adoption. FCC Part 15 spectrum allocation rules govern transmitter certification timelines for helmet-to-helmet connectivity hardware. Sena Technologies anchors firmware development in California's Bay Area for multi-brand helmet compatibility protocols.
India
Last-mile logistics electrification and two-wheeled fleet connectivity mandates accelerate commercial rider segment expansion. BIS-aligned automotive electronics standards tighten alongside domestic manufacturing scaling under PLI scheme incentives. Tamil Nadu and Karnataka assembly corridors attract component suppliers establishing localized certification pipelines.
Japan
Precision manufacturing heritage supports high-reliability display module production for extreme ambient temperature exposure. METI radio equipment regulations structure transmitter approval processes for connected motorcycle hardware. Nagoya and Tokyo electronic clusters concentrate on anti-glare optical bonding and vibration-resistant enclosure engineering.
China
Display panel manufacturing concentration supplies high-brightness TFT and OLED modules for global OEM integration. MIIT radio-type approval frameworks parallel FCC and ECE R10 certification requirements for export-bound platforms. Yangtze River Delta fabrication centers dominate glove-responsive capacitive touch sensor output.
Motorcycle Infotainment System Market Competitive Landscape
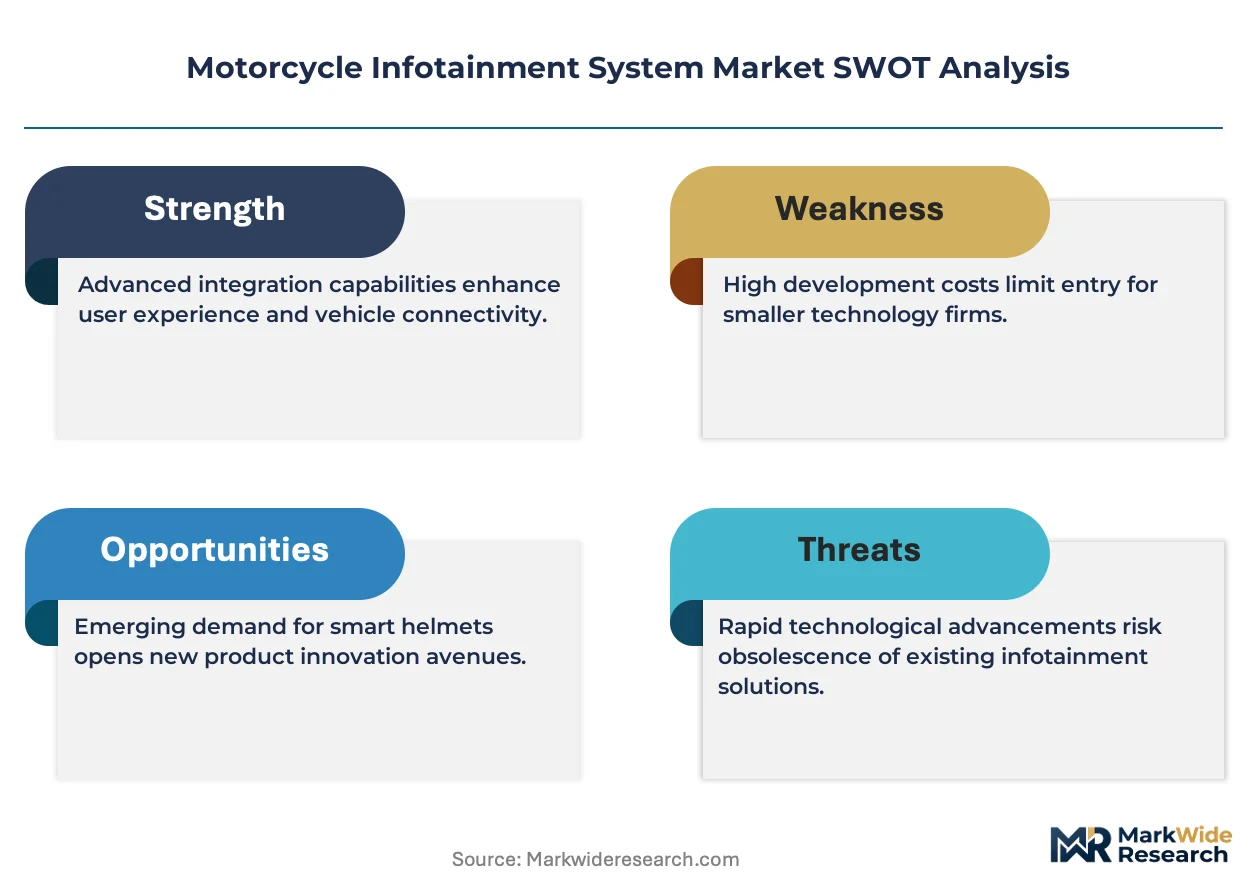
German producers anchor the factory-installed tier with CAN bus-native architectures; American specialists hold aftermarket communication and navigation positions. The structure concentrates around three strategic archetypes: diversified automotive electronics conglomerates, GPS heritage navigation pure-plays, and mesh communication firmware developers. Competitive moves center on strategic partnerships for OEM bundling and vertical integration into display module sourcing to secure supply continuity.
Within the diversified automotive tier, Bosch exemplifies scale-driven manufacturing integration across sensor fusion and vehicle electronic architectures. Garmin Ltd. occupies the navigation-centric position, leveraging map data licensing heritage. Sena Technologies Inc. represents the aftermarket communication specialist archetype, anchoring mesh protocol development for multi-rider connectivity ecosystems.
| Leading Market Players |
|---|
| TomTom International BV |
| Harley-Davidson Inc. |
| Garmin Ltd. |
| Sena Technologies Inc. |
| Honda Motor Co. Ltd. |
| Bosch |
| BMW AG |
| Polaris Inc. |
| Harman |
| Others |
Supply & Pricing Matrix
Premium touring motorcycle manufacturers' factory-installed platform mandates are compressing aftermarket pricing power and forcing component suppliers toward dual-source qualification for high-brightness display modules and mesh communication chipsets. This procurement consolidation elevates volume-scale pricing advantages for tier-one electronics conglomerates while fragmenting margin capture among specialized firmware developers.
Pricing Analysis
Lead-time premiums for F-Gas-compliant thermal management systems and ECE R10-certified transmitter modules command price differentiation of fifteen to twenty-five percent above standard-tier alternatives. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the entry-tier aftermarket segment is intensifying because smartphone mounting substitutes capture price-sensitive commuters. Commercial riders and fleet operators exhibit lowest price sensitivity due to connectivity mandates, while solo commuters demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for glove-responsive capacitive touch sensors and anti-glare optical bonding materials concentrate manufacturing scale across China, Japan, and South Korea. Raw material dependencies include high-purity indium tin oxide for transparent conductors, specialized fluorinated polymers for weather sealing, and rare-earth phosphors for display backlighting. Single-source vulnerability in MIIT-regulated radio module fabrication exposes OEMs to export licensing delays. Distribution runs through authorized dealer networks for factory-installed platforms and direct-to-rider digital channels for firmware subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures from parallel certification pipeline management and embedded software engineering scarcity will eliminate undercapitalized competitors lacking ECE R10 and FCC Part 15 compliance infrastructure. Survivors will capture disproportionate share in European and North American premium touring configurations.
For Market Incumbents: Anticipate margin compression from smartphone-averse riders demanding integrated alternatives to handlebar phone mounts by deepening captive supply of high-brightness display modules and securing exclusive CAN bus integration protocols with BMW Motorrad and Bosch manufacturing lines. Invest in voice-controlled interface convergence to differentiate premium platform tiers against emerging mesh communication specialists.
For New Entrants and Emerging Players: Commercial rider fleets in India's Tamil Nadu and Karnataka corridors represent the most penetrable buyer archetype, as last-mile logistics electrification accelerates two-wheeled connectivity mandates without entrenched supplier relationships. Target BIS-aligned certification pipelines as a first-mover wedge, leveraging local assembly partnerships to undercut import-dependent incumbents on total cost of ownership.
For Investors and Strategic Acquirers: The window for entry favors aftermarket communication module specialists with established mesh protocol firmware stacks and multi-brand helmet compatibility. Long-term viability hinges on recurring revenue transformation through subscription-based map and firmware update architectures. Watch for inflection when direct-to-rider digital distribution channels displace traditional retail networks for feature unlocks.
| Strategic Initiative | Industry Significance |
|---|---|
| ECE R10 Certification Investment | Filters low-tier competitors from German and EU market access, elevating technical specifications. |
| Mesh Protocol Firmware Development | Enables seamless multi-rider voice networks without manual re-pairing interruptions for group touring. |
| Display Module Backward Integration | Secures supply continuity for high-brightness TFT and OLED panels amid Asian manufacturing concentration. |
| Direct-to-Rider Digital Distribution | Captures lifetime value through connected platform ecosystems and recurring service contracts. |
| Voice-Controlled Interface Integration | Reduces manual touchscreen interaction, addressing safety concerns and differentiating premium tiers. |
Research Methodology
Multi-period observation of factory-installed platform bundling rates, aftermarket kit adoption curves, and regional certification pipeline timelines anchored the trend analysis, supplemented by interviews with motorcycle OEM platform engineers, Tier 1 electronics procurement leads, aftermarket distributor operations heads, and mesh communication firmware developers. Secondary validation drew from ECE R10 compliance filings, FCC Part 15 equipment authorization databases, BIS automotive electronics registrations, and vehicle production data from IHS Markit. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrices modeled demand across product type, technology protocol, end-user archetype, and installation channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted price evolution. Industry-specific forecast inputs included premium touring motorcycle production schedules and regional radio-type approval harmonization progress.
Revisions become necessary when ECE R10 electromagnetic compatibility standards tighten beyond current shielding specifications, F-Gas Regulation enforcement accelerates thermal design disqualifications, or smartphone navigation app functionality encroaches on dedicated hardware value propositions. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market