
 Ballistic Protection Market | 2026-2036
Ballistic Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Protection Market Intelligence
The European Union's push for circular economy principles, including end-of-life material accountability for protective gear, is realigning procurement criteria for defense agencies. DuPont de Nemours, Inc. leverages its deep material science expertise in aramid fibers to meet these evolving standards. Honeywell International Inc. competes on the performance of its polyethylene-based materials, while Teijin Limited specializes in high-tenacity fiber solutions for both hard and soft armor applications.
Ballistic protection involves materials engineered to absorb and dissipate the kinetic energy from projectiles, preventing penetration and mitigating blunt force trauma. Performance depends on the high tensile strength of components like aramid fibers or the hardness of ceramic plates. While military combat applications command the largest market share, demand from law enforcement agencies is expanding rapidly. Aramid fibers and advanced polyethylene constitute the core material segments, with composites gaining traction for lightweight solutions.
Product performance and market access are governed by stringent certification standards, such as the NIJ framework in the United States. In Europe, CE marking is mandatory for personal protective equipment, while NATO STANAGs define interoperability requirements for allied military forces. Future material innovation will concentrate on resolving the persistent trade-off between higher threat-level protection and reducing the wearer's physical burden.
Market Dynamics
The fundamental dynamic shaping the ballistic protection market is the persistent trade-off between increasing threat-level protection and reducing the physical burden on the wearer. This tension drives material science innovation toward lightweight composites that can meet stringent performance standards without compromising mobility.
Growth Catalysts
- Modernization Programs:Large-scale procurement cycles within police, paramilitary, and military forces, particularly in countries like India, are creating sustained demand for new personal protective equipment to replace aging inventories.
- Composite Material Adoption:The development and maturation of lightweight composite materials, blending ceramics, polymers, and fibers, enable higher levels of protection at a reduced weight, expanding their use in both hard and soft armor.
- Law Enforcement Mandates:Heightened operational risks for domestic law enforcement and first responders are leading to new departmental mandates and funding for body armor that meets advanced threat protection standards.
Market Restraints
- Input Material Costs:The high production cost and specialized nature of core materials like high-performance aramid fibers and ultra-high-molecular-weight polyethylene (UHMWPE) create a significant cost barrier for end-users.
- Inherent Performance Trade-offs:A fundamental technical constraint remains the direct correlation between the level of ballistic protection and the armor's weight and rigidity, which can impede wearer mobility and endurance.
- Certification Bottlenecks:The rigorous and time-consuming testing required to achieve certifications such as the NIJ standard in the United States or CE marking in Europe can delay market entry for new products.
Strategic Opportunities
- Smart Armor Integration:Incorporating sensors for impact detection, health monitoring, and location tracking into ballistic vests presents an opportunity to add significant value for military and first responder applications.
- Sustainable Materials:The push for circular economy principles in Europe creates a significant opportunity for manufacturers who can develop and commercialize effective ballistic materials that are recyclable or biodegradable.
- Civilian and Private Security:Expanding product lines to address the specific needs of non-state actors, including corporate security, journalists in conflict zones, and cash-in-transit services, opens a new customer segment.
Industry Challenges
- Supply Chain Concentration:The global supply of critical raw materials, especially high-tenacity aramid fibers, is concentrated among a small number of producers, creating potential for price volatility and supply disruptions.
- Harmonization of Standards:Manufacturers face operational complexity and increased costs in designing and testing products to meet multiple, non-harmonized standards like US NIJ and NATO STANAG requirements.
- End-of-Life Management:Establishing effective and scalable processes for the collection, decommissioning, and safe disposal of expired body armor presents a logistical and environmental challenge for the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Protection Market |
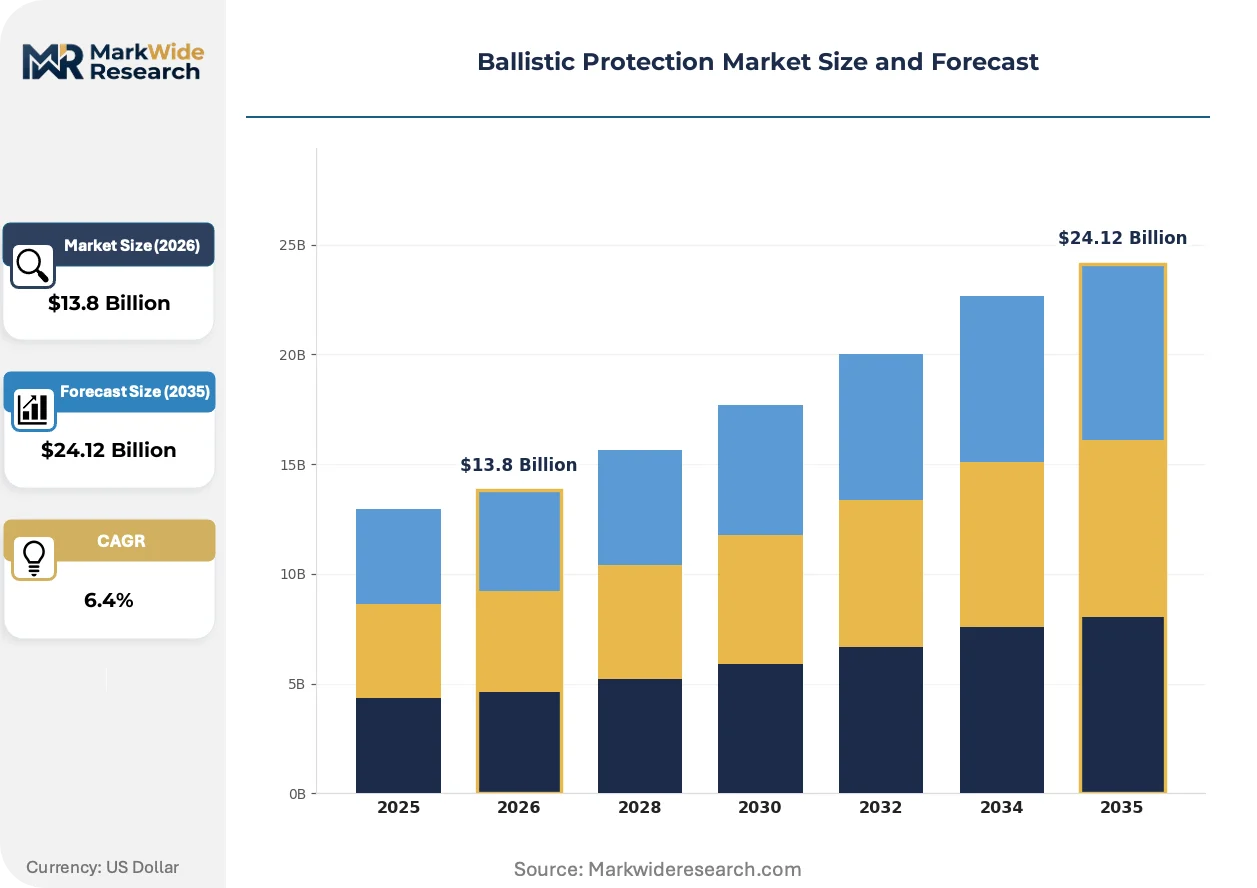
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmet, Vest, Shields, Gloves, Ballistic Glass Material: Aramid Fibers, Polyethylene, Ceramic Plates, Steel, Composite Materials Application: Military Combat, Law Enforcement, Personal Security, Private Security Firms End User: Defense Agencies, Police Units, Security Contractors, Correctional Facilities |
| Companies Covered | Avon Protection, DuPont de Nemours, Inc., BAE Systems, TenCate Advanced Armor, Teijin Limited, Safariland LLC, Honeywell International Inc., Rheinmetall AG, Point Blank Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Protection Market Strategic Shifts & Innovations
Material science innovation is moving beyond stopping projectiles to address new demands for data integration and sustainability. The next generation of ballistic protection will be defined by its ability to perform multiple functions while complying with stricter lifecycle mandates.
Sensor-integrated fabrics represent a significant product evolution. These materials embed micro-electronics to monitor the wearer's vital signs or detect the location and severity of a non-penetrating impact. Special operations forces are the primary early adopters, seeking enhanced situational awareness and casualty care data. The core function of ballistic resistance is converging with wearable health technology, providing a more holistic soldier system.
European Union circular economy directives are reshaping design criteria for armor systems. These policies compel manufacturers to account for the end-of-life disposal of protective gear, favoring materials that can be recycled or safely decommissioned. This regulatory pressure particularly affects producers of composite armor, who must now invest in R&D for more sustainable bonding agents and fiber matrices to meet future procurement requirements.
A notable shift in buying behavior involves the adoption of comprehensive lifecycle management services by large agencies. This model replaces one-off transactional purchases with long-term contracts covering armor inspection, maintenance, data tracking, and scheduled replacement. This trend is most prominent in North American and European law enforcement agencies aiming to ensure compliance and manage total cost of ownership across thousands of personnel.
Ballistic Protection Market Segmentation
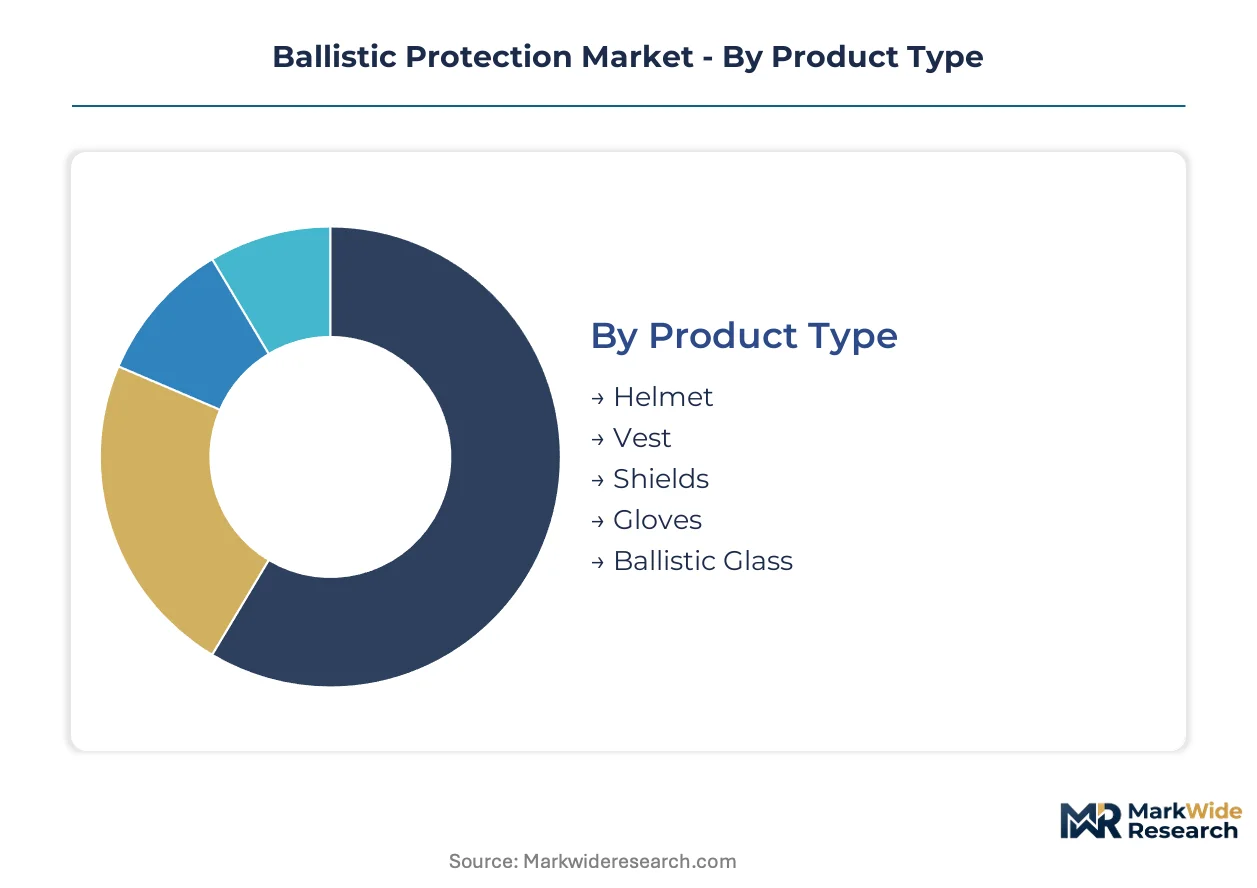
Understanding the ballistic protection market requires a detailed examination of its constituent parts, as performance requirements and purchasing drivers vary significantly across different product types, materials, applications, and end-user segments. This segmentation provides clarity on where innovation is most impactful and where demand is concentrated.
Product Type:
Buyers in this category are differentiated by the specific body part or area requiring protection, influencing the form factor and design constraints of the ballistic gear.
- Vest:These garments cover the torso, utilizing multiple layers of soft armor or incorporating hard plates for enhanced protection against higher threats. Demand for ballistic vests is substantial across military and law enforcement, driven by the need for core body protection in operational environments.
- Helmet:Designed to protect the head from ballistic impacts and blunt force trauma, helmets integrate advanced composite materials for lightweight performance. Military and special forces operations heavily rely on advanced ballistic helmets for critical head protection and integration with communication systems.
- Shields:Primarily used by law enforcement and tactical units, ballistic shields offer mobile, temporary cover against direct fire in high-risk situations.
- Gloves:Specialized ballistic gloves protect hands from fragments and low-velocity projectiles, often used by EOD teams or in specific combat roles.
- Ballistic Glass:Engineered transparent materials provide protection in vehicles, buildings, and observation posts, safeguarding occupants without obstructing visibility.
Vest leads volumes today; Helmet is gaining share fastest.
Material:
The selection of materials is primarily driven by the balance between ballistic performance, weight, and cost, with each material offering distinct advantages for specific threat levels and applications.
- Aramid Fibers:These high-strength, heat-resistant synthetic fibers, such as Kevlar, are widely used in soft armor for their excellent energy absorption and flexibility. Aramid fibers remain a foundational component in personal protective equipment, particularly for law enforcement and military soft armor applications.
- Polyethylene:Ultra-high-molecular-weight polyethylene (UHMWPE) offers superior strength-to-weight ratios, making it ideal for lightweight hard and soft armor solutions. Honeywell International Inc. leverages its advanced polyethylene materials to produce lighter ballistic plates and inserts, reducing wearer burden.
- Ceramic Plates:Composed of materials like alumina or silicon carbide, ceramic plates provide rigid, high-level protection against rifle rounds when integrated into body armor.
- Steel:While heavier, steel plates offer cost-effective ballistic protection, finding use in less weight-sensitive applications such as vehicle armor or static shields.
- Composite Materials:These multi-layered structures combine various fibers, ceramics, and polymers to achieve optimized ballistic performance and weight reduction.
Innovation is driving shifts in material composition and manufacturing processes.
Application:
The market for ballistic protection is segmented by the operational context and threat environment, which dictates the required protection level and product specifications.
- Military Combat:This segment encompasses protective gear for soldiers in active combat zones, requiring maximum protection against a wide range of threats including rifle rounds and fragmentation. Military modernization programs globally, especially in countries like India, are driving significant procurement of advanced ballistic protection systems.
- Law Enforcement:Protective equipment for police officers and domestic security forces focuses on mitigating threats from handguns and blunt force trauma, with an increasing need for rifle-rated protection. Heightened operational risks for police units in urban environments are leading to new mandates for advanced body armor.
- Personal Security:This category includes protective solutions for high-risk individuals, such as VIPs or journalists operating in conflict zones, often prioritizing discretion and comfort.
- Private Security Firms:Security contractors and personnel guarding critical infrastructure or assets require ballistic protection tailored to specific operational profiles and threat assessments.
Demand for specialized solutions is expanding across these varied applications.
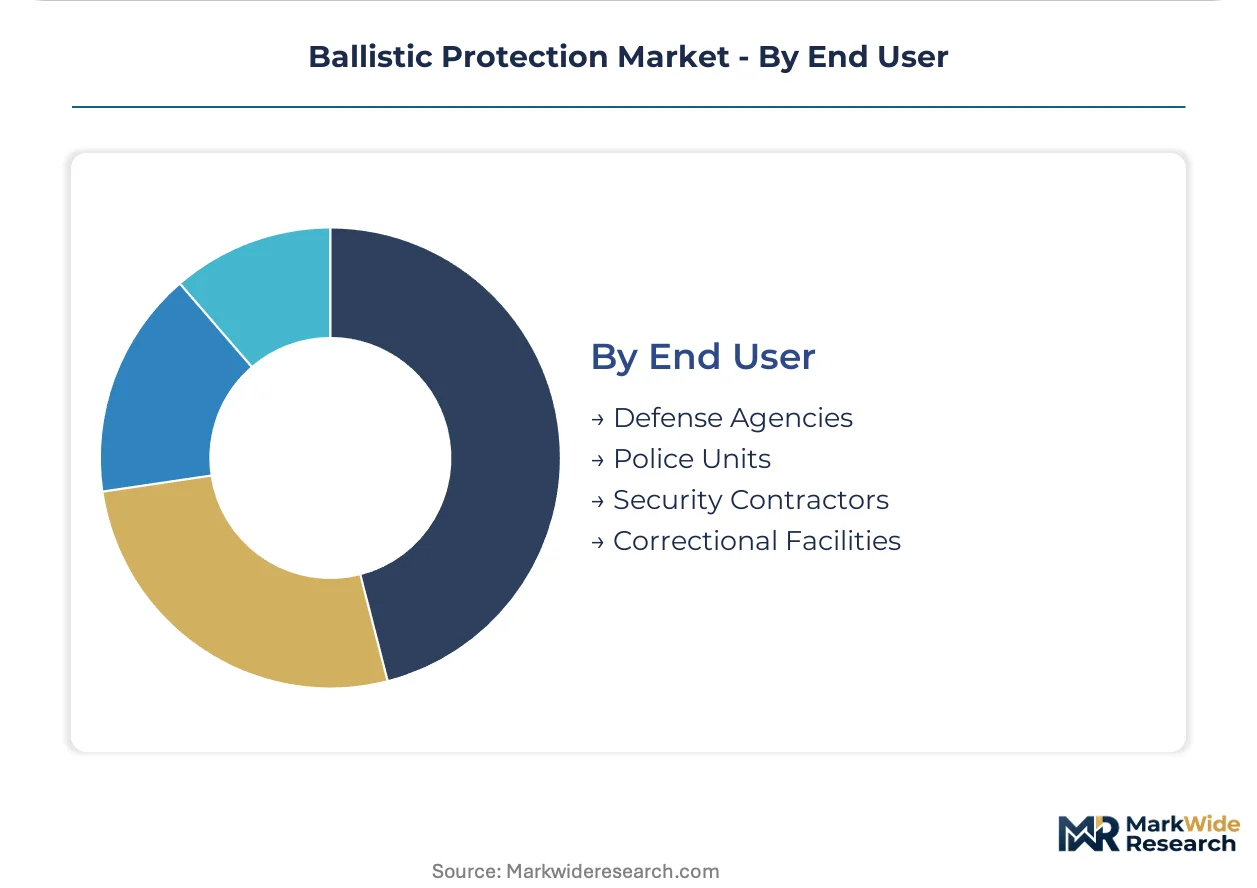
End User:
End-user segmentation reflects the primary purchasing entities and their distinct procurement processes and funding mechanisms for ballistic protection equipment.
- Defense Agencies:National defense ministries and military branches are the largest procurers, driven by national security mandates and large-scale troop deployments. Defense agencies prioritize advanced protection technologies and comprehensive lifecycle management services for their personnel.
- Police Units:Local, regional, and national police forces acquire ballistic gear to protect officers from domestic threats, often influenced by departmental budgets and public safety initiatives. Police units frequently adopt new body armor to meet evolving threat profiles and ensure officer safety.
- Security Contractors:Private military and security companies purchase equipment for their personnel deployed in various roles, from executive protection to facility guarding.
- Correctional Facilities:These institutions acquire protective gear for guards and staff to manage inmate populations and respond to potential disturbances.
Procurement cycles influence spending patterns across these end-user groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ballistic protection industry originated from early military requirements for personal armor, evolving significantly with the advent of modern materials. Its scaling accelerated during 20th-century conflicts, driving demand for advanced protective gear from defense agencies. Today, market evolution continues across diverse global regions, each shaped by unique procurement cycles and regulatory frameworks.
United States
Demand for military combat applications and law enforcement protection remains consistently high across the United States. The NIJ framework sets rigorous performance standards for all body armor procurement programs, influencing product development. Major defense contractors in areas like Virginia and Maryland drive innovation in integrated soldier systems and advanced materials.
Germany
European defense modernization programs fuel demand for advanced ballistic solutions, particularly lightweight armor systems. CE marking is mandatory for personal protective equipment, guiding product development and market entry across the region. Research centers in Bavaria and North Rhine-Westphalia collaborate on next-generation composite materials for defense applications.
India
Large-scale police and paramilitary force upgrades create substantial demand for new personal protective equipment in India. The PLI scheme supports domestic manufacturing of defense equipment, influencing local procurement strategies and reducing import reliance. Production hubs in Maharashtra and Gujarat are expanding capabilities for ballistic textile and plate fabrication.
Japan
Military and special forces units seek advanced, lightweight protective gear with enhanced mobility and stealth capabilities. JIS standards ensure quality and performance for locally produced ballistic materials and components within the country. Tokyo-based firms and material science companies invest in R&D for high-tenacity fibers and stealth integration technologies.
United Kingdom
Modernization initiatives within the British Armed Forces drive demand for advanced, multi-threat protective systems. The UK's DEF STAN procurement standards emphasize interoperability and performance for military equipment. Defense technology clusters in the Southeast and Scotland focus on developing integrated armor solutions and sustainable materials.
Ballistic Protection Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the ballistic protection market, creating a diverse competitive landscape. The industry features a mix of large, vertically integrated manufacturers and specialized material science companies focusing on specific components. Strategic archetypes include global defense contractors, niche material innovators, and regional assemblers serving specific end-user segments. Key competitive moves involve technology licensing, strategic partnerships to access advanced materials, and continuous portfolio diversification.
Material science expertise anchors competitive positioning for several key players in the ballistic protection market. DuPont de Nemours, Inc. exemplifies a global chemical company leveraging its aramid fiber legacy to develop high-performance protective solutions for diverse applications. Similarly, Honeywell International Inc. occupies a strong position with its advanced polyethylene-based materials, enabling lighter and more effective armor systems across military and law enforcement segments. Japanese firm Teijin Limited represents another significant player, specializing in high-tenacity fiber solutions for both hard and soft armor, often collaborating on composite material innovation.
| Leading Market Players |
|---|
| Avon Protection |
| DuPont de Nemours, Inc. |
| BAE Systems |
| TenCate Advanced Armor |
| Teijin Limited |
| Safariland LLC |
| Honeywell International Inc. |
| Rheinmetall AG |
| Point Blank Enterprises |
| Others |
Cost & Logistics Intelligence
High-performance fiber prices, influenced by petrochemical feedstocks, cascade through the ballistic protection supply chain, shaping the cost structure of soft and hard armor solutions.
Pricing Analysis
Contract-based long-term agreements for critical components govern the ballistic protection market, favoring established suppliers. Price differentiation hinges on NIJ certification levels and the degree of material customization for specific threat profiles. Pricing pressure stems from the high production cost of advanced materials like UHMWPE and aramid fibers. Law enforcement agencies often exhibit higher price sensitivity compared to military special operations units, who prioritize maximum protection.
Supply Chain Analysis
Rigorous certification requirements, such as NIJ standards in the United States, gate access for new suppliers in the ballistic protection market. Critical raw material supply, including aramid fibers and UHMWPE, concentrates among a few producers in Japan, the Netherlands, and the United States. This concentration creates single-source vulnerability for specialized components. Distribution primarily runs through direct sales channels to defense agencies and specialized integrators for law enforcement and private security firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ballistic protection market offers geographic arbitrage opportunities, particularly given the cost differential in manufacturing between Western Europe and Southeast Asia.
For Market Incumbents: Hedge against potential supply chain disruptions by establishing dual-source agreements for critical components such as UHMWPE. Pursue strategic acquisitions of niche material science firms to counter the threat of disruptive lightweight composite technologies. Deepen vertical integration into advanced fiber production to control input costs. Invest in localized manufacturing capabilities in regions like India, leveraging government incentives like the PLI scheme, to mitigate tariff exposure.
For New Entrants and Emerging Players: Launch via specialized distribution networks targeting the underserved civilian and private security segments, focusing on customizable solutions. Prioritize white-space opportunities in smart armor integration, embedding sensors for health monitoring and impact detection. The most penetrable segment remains high-risk individuals and corporate security requiring discrete, lightweight protection. Leverage agile product development cycles and rapid certification pathways for regional market entry.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized material science innovators developing next-generation lightweight composites that address both protection and sustainability. The market offers compelling long-term viability, driven by continuous modernization programs across defense and law enforcement over the next decade. Acquisition targets should include firms with patented sustainable ballistic materials or advanced sensor integration expertise. A critical signal to watch is the increasing adoption of comprehensive lifecycle management services by major defense agencies.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture for Composite R&D | Accelerates development of lighter, stronger materials for military and law enforcement applications. |
| Capacity Expansion in UHMWPE Production | Addresses growing demand for lightweight armor from police units and defense agencies. |
| CE Marking Certification Investment | Facilitates market entry and compliance for personal protective equipment across Europe. |
| Integration of Sensor Technology | Enhances situational awareness and health monitoring for special operations forces personnel. |
| Sustainable Material Development | Meets European circular economy directives and future procurement requirements for defense agencies. |
Research Approach
Bottom-up military combat application modeling reconciled against top-down aramid fiber supply tracking forms the analytical core of this study. Primary interviews with defense procurement officers, material science engineers, law enforcement tactical unit leaders, and private security firm managers provided qualitative insights. Secondary validation drew from NATO STANAG documents, NIJ certification databases, and national defense budget reports. This approach ensured comprehensive data capture and cross-referencing.
Input-output matrices defined volume and value flows across the ballistic protection market over the projection horizon. Segmentation dimensions included product type, material composition, application, and end-user, alongside regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical data and anticipated technological advancements in composite materials. Forecast inputs considered defense spending allocations and law enforcement modernization program budgets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical instability or rapid material science breakthroughs. These projections reflect current understanding and documented assumptions regarding market dynamics. A model refresh is warranted upon material change in defense procurement cycles or regulatory standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
US Perforating Gun Market