
 Europe Cruise Missile Market | 2026-2036
Europe Cruise Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cruise Missile Market Foresight
Export-credit-backed leasing arrangements for defense procurement is rewriting competitive access across European navies and air forces. Kongsberg Gruppen ASA leverages its NSM family footprint to anchor Nordic and Baltic contracts. MBDA sustains Franco-British joint-program economies of scale through Storm Shadow/SCALP production. Saab AB differentiates via modular seeker architectures that reduce integration costs for smaller European militaries.
A cruise missile is a self-propelled, precision-guided munition that maintains controlled flight through aerodynamic lift, typically employing turbofan or turbojet propulsion at subsonic or supersonic speeds with ranges from hundreds to thousands of kilometers; its primary purpose is to destroy high-value fixed or mobile targets while keeping launch platforms outside enemy air-defense envelopes. Naval platforms currently dominate procurement volumes as surface combatants and submarines prioritize stand-off strike over direct engagement. Long-range segments attract the fastest investment growth, driven by requirements to penetrate layered integrated air-defense systems. Terminal homing guidance systems command premium positioning due to discrimination demands against hardened and relocatable targets.
The European Defence Agency coordinates joint capability development, while REACH and RoHS frameworks constrain propellant chemistry and materials selection for continental production. EMA and national military airworthiness bodies impose certification burdens that extend development timelines and favor incumbents with established regulatory relationships. Stakeholders must weigh whether to absorb compliance costs in-house or partner with primes that already hold cleared supply chains.
Market Dynamics
Export-credit-backed leasing arrangements are rewriting competitive access across European navies and air forces, while the EU Green Deal's carbon-footprint disclosure rules force propulsion system redesigns that favor incumbents with cleared supply chains.
Growth Catalysts
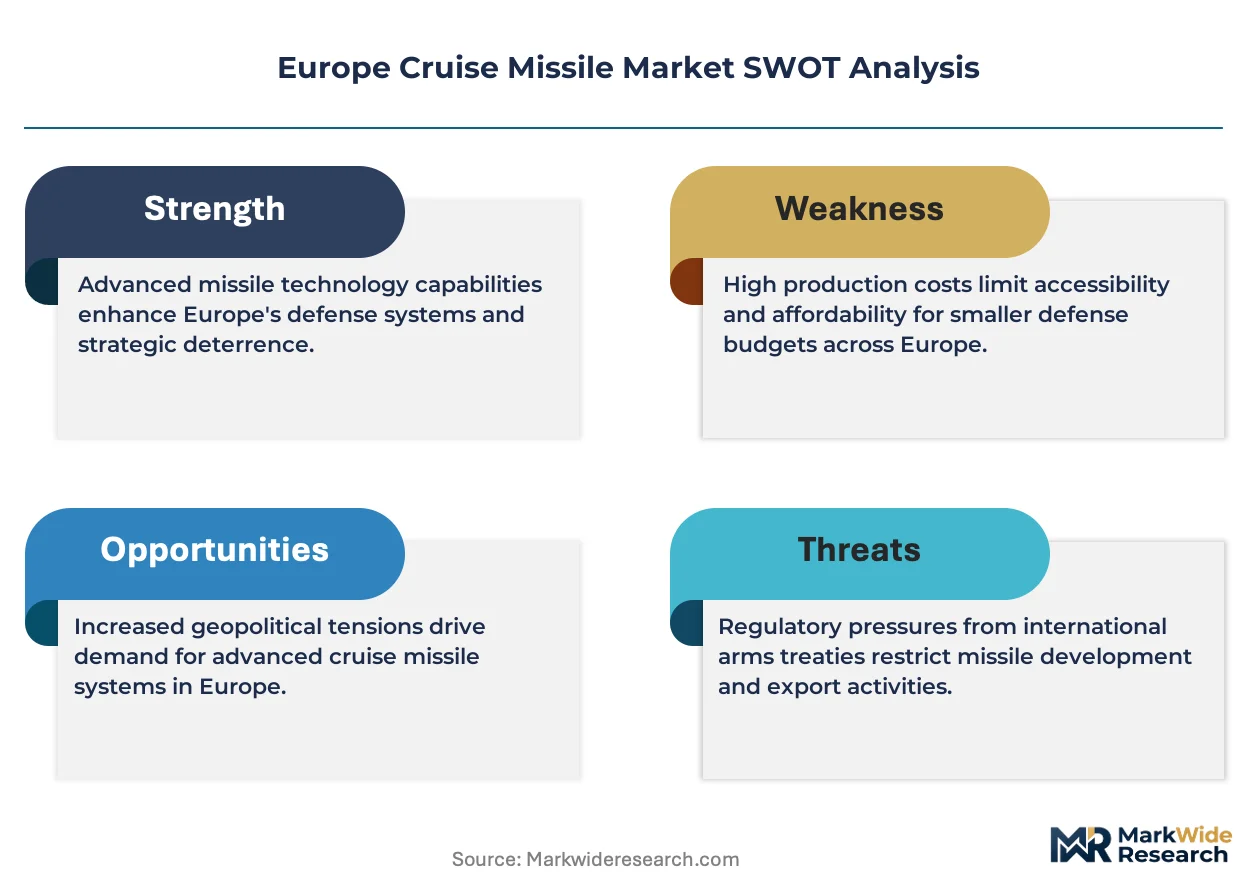
- Naval strike platform modernization:European surface combatants and submarines prioritize stand-off strike over direct engagement, expanding procurement volumes for precision weapons with ranges exceeding layered air-defense envelopes.
- REACH and RoHS frameworks:These regulations constrain propellant chemistry and materials selection, creating certification barriers that extend development timelines and reinforce relationships between primes and established military airworthiness bodies.
- Deep-strike capability requirements:France, the United Kingdom, and Poland are modernizing their arsenals to penetrate integrated air-defense systems, concentrating demand for long-range segments with terminal homing guidance.
Market Restraints
- Turbofan propulsion cost structure:Specialized engine components and low production volumes keep unit economics elevated, limiting procurement scale for smaller European militaries.
- Supply concentration in cleared defense industrial bases:Propulsion systems and seeker electronics depend on a narrow supplier set within France, the United Kingdom, and Norway, creating vulnerability to single-source disruptions.
- EMA and national military airworthiness certification:Extended validation timelines for new propellant formulations and guidance architectures delay fielding by 18-36 months compared to non-European alternatives.
Strategic Opportunities
- Poland's accelerated defense spending:Warsaw's procurement timeline for stand-off weapons runs ahead of continental peers, creating first-mover advantages for contractors establishing local maintenance and integration facilities.
- Modular seeker architectures:Convergence of multi-mode seekers with open mission systems enables smaller militaries to field discriminating capabilities against hardened targets without full platform replacement.
- EU Green Deal industrial carbon mandates:Manufacturers redesigning propulsion for disclosure compliance can capture premium positioning in forthcoming Nordic and Baltic tenders with stringent sustainability criteria.
Industry Challenges
- Guidance algorithm talent scarcity:Terminal homing against relocatable targets requires expertise in machine-vision discrimination and electronic counter-countermeasures, skills concentrated in a handful of defense primes and national laboratories.
- Integration complexity with legacy fire-control systems:NATO interoperability standards demand backward compatibility with 1990s-era ship combat management systems, consuming engineering resources that could advance next-generation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cruise Missile Market |
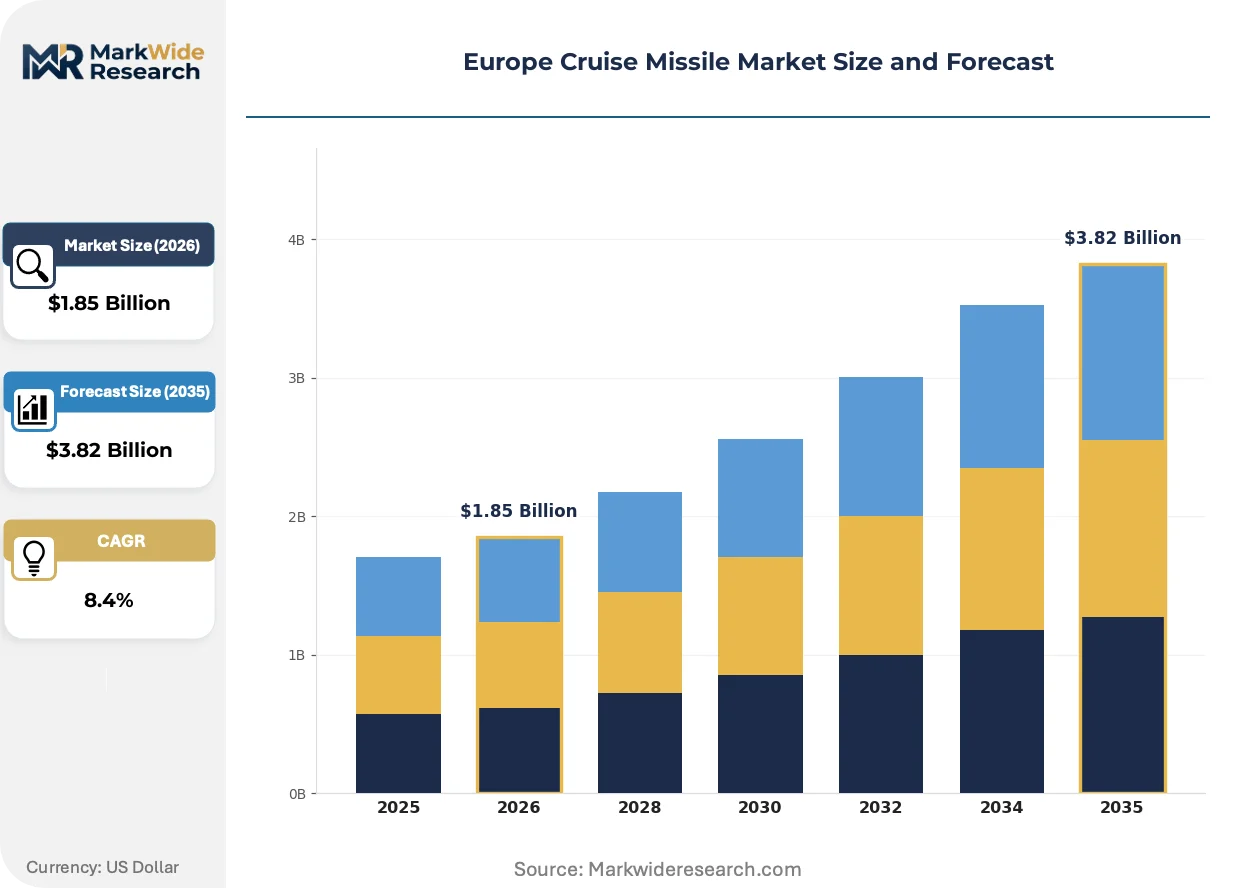
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: Naval, Airborne, Ground-Based, Submarine Range: Short-Range, Medium-Range, Long-Range, Extra Long-Range Guidance System: Inertial, GPS, Terminal Homing, Radar Warhead Type: Conventional, Nuclear, Electromagnetic, Fragmentation |
| Companies Covered | MBDA, Kongsberg Gruppen ASA, RTX Corporation, Lockheed Martin Corporation, BAE Systems, Thales Group, Saab AB, Leonardo, Rafael Advanced Defense Systems Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cruise Missile Market Shifts & Advancements
Precision stand-off weapons are undergoing fundamental redesign as layered air-defense networks proliferate and environmental compliance tightens, compressing development cycles while demanding higher discrimination at terminal phase.
Ramjet-augmented propulsion for supersonic terminal sprint is rendering obsolete subsonic-only cruise missiles in contested airspace. French and British air forces are prioritizing this capability for time-sensitive targeting against mobile launchers. The technology is rendering obsolete legacy inventory planning that assumed exclusive reliance on stealth and terrain masking.
The EU Green Deal's defense industrial carbon-footprint disclosure rules are forcing propulsion manufacturers to quantify and reduce lifecycle emissions from turbofan production. MBDA and Saab are redesigning combustor architectures to meet these thresholds ahead of contract awards. Naval strike platforms in the Baltic Sea corridor face the tightest compliance deadlines, accelerating supplier qualification processes.
Export-credit leasing is displacing traditional foreign military sales for stand-off weapons procurement. Nordic and Baltic navies now acquire missiles through 10-year operational service contracts rather than capital purchases, transferring sustainment risk to manufacturers. Poland and Romania have adopted this structure most aggressively, compressing vendor selection to primes with established credit backing from national export agencies.
Europe Cruise Missile Market Segmentation
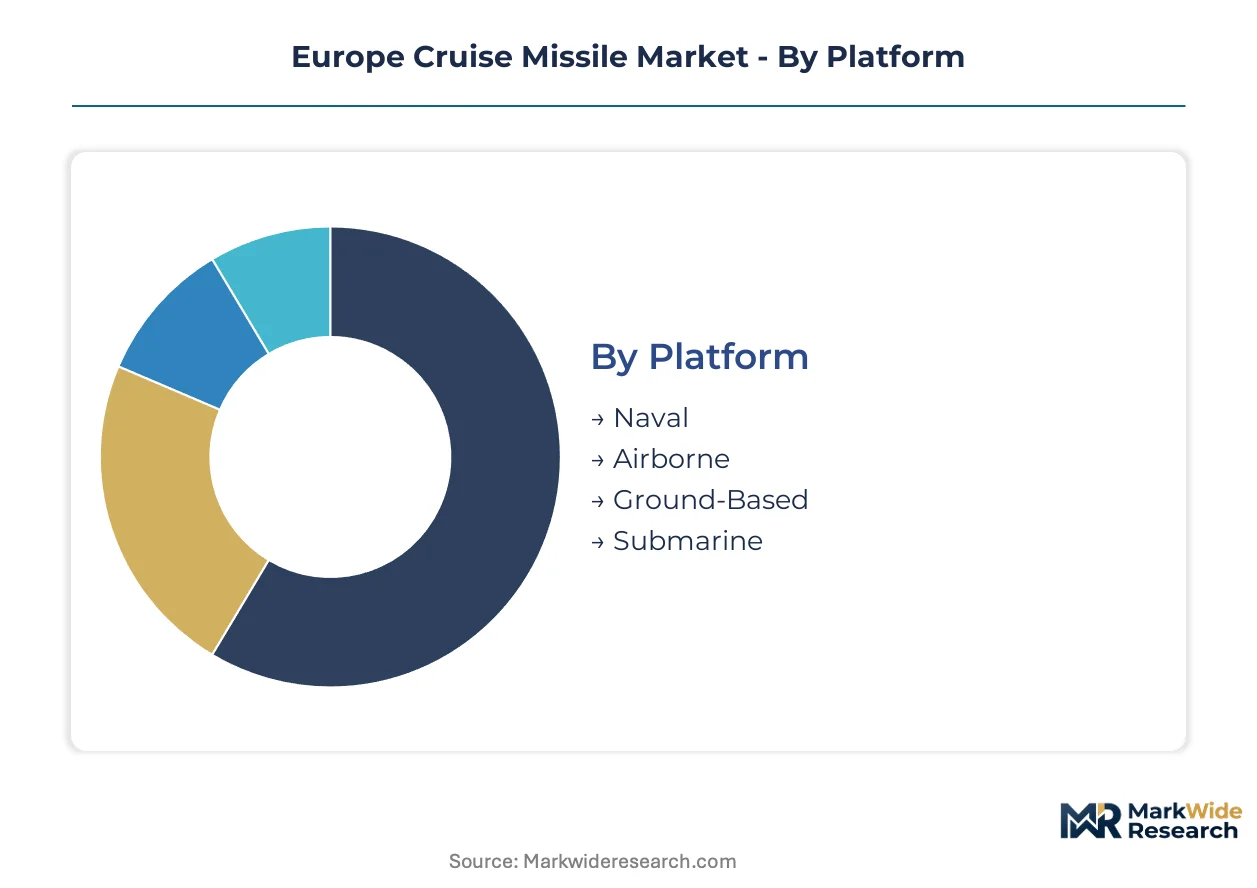
Cruise missile procurement patterns across Europe diverge sharply by launch platform and mission profile, with sustainment contracts and through-life support obligations creating distinct commercial architectures for each segment. Understanding these structural differences reveals where primes can capture recurring revenue versus one-time hardware sales.
Platform:
After-sales intensity varies dramatically across launch platforms, with naval and submarine systems demanding dockside maintenance infrastructure while airborne platforms concentrate spares logistics at airbase clusters.
- Naval:Surface combatants in the French, British, and Italian fleets drive procurement volume for deck-launched variants with vertical-launch compatibility. Polish naval modernization programs are accelerating demand for ship-borne stand-off weapons with integrated combat management system interfaces. Maintenance cycles align with dry-docking schedules, creating predictable service revenue windows for contractors.
- Airborne:Fighter-integrated carriage dominates this segment, with Rafale, Typhoon, and Gripen operators requiring pylon-compatible airframes with standardized electrical and data bus connections. French and British air forces prioritize this platform for deep-strike missions against integrated air-defense networks.
- Ground-Based:Mobile launchers on heavy trucks serve territorial defense requirements in Poland and Romania, with dispersed basing demanding ruggedized transport and rapid redeployment capabilities.
- Submarine:Torpedo-tube and vertical-launch variants for attack submarines require pressure-hull compatibility and saline-environment corrosion resistance, limiting qualified suppliers to established naval primes.
By volume, Naval leads. By growth pace, Airborne is expanding most quickly.
Range:
Cost tiers stratify cleanly across range bands, with propulsion system complexity and seeker sophistication driving exponential unit cost escalation from short-range to extra long-range variants.
- Short-Range:Tactical battlefield support weapons under 300 kilometers serve close-air-support substitution roles. Polish and Baltic militaries favor these for cost-effective saturation strikes against hardened point targets.
- Medium-Range:Extended reach for operational-level targeting bridges tactical and strategic applications, with French and British forces fielding these for theater-level interdiction.
- Long-Range:Penetration of layered air-defense systems demands turbofan efficiency and terrain-following navigation, concentrating demand in French and British deep-strike modernization programs. Terminal homing discrimination against relocatable targets commands premium positioning in this band.
- Extra Long-Range:Strategic reach exceeding 1,500 kilometers requires compact turbofan technology and precision inertial-GPS integration, with Franco-British joint programs representing the sole European developmental effort in this category.
By procurement volume, Long-Range dominates current European budgets. By trajectory steepness, Extra Long-Range is gaining share fastest as integrated air-defense networks proliferate.
Guidance System:
Application context determines guidance architecture selection, with terminal engagement requirements against hardened or mobile targets driving multi-mode integration complexity.
- Inertial:Self-contained navigation resistant to electronic countermeasures serves as the foundational layer for all European cruise missile designs, with ring-laser gyro and fiber-optic variants offering trade-offs between accuracy and cost.
- GPS:Satellite augmentation corrects inertial drift for mid-course guidance, though European militaries prioritize anti-jam receivers given contested electromagnetic spectrum expectations in Baltic and Eastern European scenarios.
- Terminal Homing:Electro-optical and imaging infrared seekers discriminate aimpoints within target complexes, with French and British forces demanding this capability for time-sensitive targeting against mobile launchers. Algorithm development for machine-vision recognition concentrates in MBDA and Saab engineering centers.
- Radar:Synthetic aperture and millimeter-wave seekers penetrate weather and camouflage for maritime strike and fixed-target applications, with Nordic navies prioritizing this mode for littoral engagements.
By installed base, Inertial-GPS combinations lead. By capability investment, Terminal Homing is climbing the fastest as counter-relocation requirements harden.
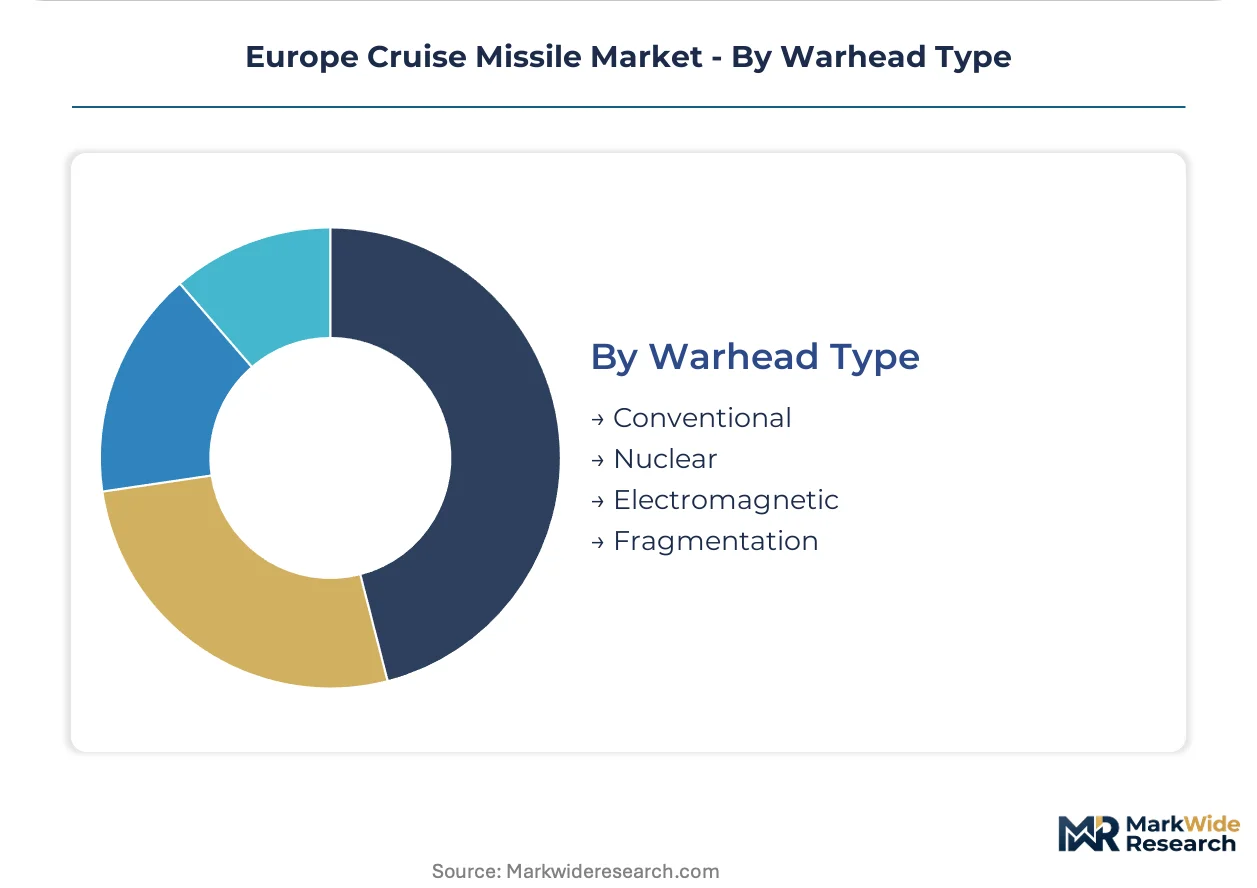
Warhead Type:
Customer type and mission authorization frameworks segment this category, with national nuclear postures and alliance obligations creating divergent procurement patterns.
- Conventional:Unitary and penetrator warheads for hardened structures represent the standard configuration across all European conventional forces, with blast-fragmentation variants optimized for area targets and bunker-busters for command facilities.
- Nuclear:Strategic deterrence integration limits this segment to French and British national arsenals, with specialized safety and command-and-control architectures governed by bilateral treaties and national authorization protocols.
- Electromagnetic:Non-kinetic effects against electronic infrastructure serve counter-C4ISR missions, with experimental deployment limited to specialized French and British test programs.
- Fragmentation:Optimized anti-personnel and soft-target effects see limited cruise missile application, with area-denial missions more commonly assigned to alternative munition types.
By procurement scale, Conventional dominates by orders of magnitude. By policy attention, Nuclear maintains steepest investment intensity given modernization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European cruise missile procurement tilts toward import substitution as domestic manufacturing scales, though Franco-British joint programs still dominate long-range categories. Nordic and Baltic states increasingly source from regional suppliers under export-credit arrangements.
France
Rafale fighter integration drives sustained demand for airborne stand-off weapons, with the Direction Générale de l'Armement managing qualification timelines. REACH compliance for propellant chemistry adds 12-18 months to development cycles. The Île-de-France cluster hosts MBDA's primary engineering centers for terminal homing algorithm development.
United Kingdom
Royal Navy surface combatant modernization prioritizes vertical-launch naval variants compatible with Type 26 and Type 31 frigates. The UK Ministry of Defence's Integrated Procurement Model extends contractor liability through operational service contracts. Stevenage and Bolton house concentrated seeker electronics and warhead integration facilities.
Poland
Accelerated defense spending under the Homeland Defence Act targets ground-based mobile launchers for territorial defense saturation. Poland's national export-credit agency backs 10-year leasing structures that transfer sustainment risk to manufacturers. The Warsaw-Łódź corridor attracts integration facility investments from Nordic primes seeking first-mover positioning.
Germany
Luftwaffe Tornado replacement programs drive fighter-integrated carriage requirements, though procurement timelines lag Franco-British peers. The KBA coordinates military airworthiness certification with EMA frameworks for dual-use propulsion components. Bavaria's Munich-Augsburg axis concentrates turbofan subsystem suppliers cleared for defense industrial base access.
Sweden
Gripen fighter operators across Nordic and Baltic states create networked procurement demand for modular seeker architectures. The Swedish Defence Materiel Administration mandates open mission system interfaces to reduce integration costs for smaller militaries. Linköping hosts Saab's engineering centers for multi-mode seeker convergence development.
Europe Cruise Missile Market Competitive Landscape
On the supply side, the industry is consolidating around primes with cleared defense industrial base access and established regulatory relationships. Two structural tiers have emerged: full-system integrators with end-to-end propulsion and guidance capabilities, and subsystem specialists feeding into prime contractor supply chains. Dominant competitive moves include strategic partnerships for export-credit backing and geographic expansion through local maintenance facility establishment.
Among European-based integrators, MBDA and Saab AB exemplify contrasting archetypes. MBDA occupies a position anchored in Franco-British joint-program economies of scale, while Saab AB sits within the modular-specialist tier serving smaller militaries with reduced integration burdens. Kongsberg Gruppen ASA represents the Nordic-Baltic regional anchor, leveraging geographic proximity for accelerated procurement timelines.
| Leading Market Players |
|---|
| MBDA |
| Kongsberg Gruppen ASA |
| RTX Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| Thales Group |
| Saab AB |
| Leonardo |
| Rafael Advanced Defense Systems Ltd. |
| Others |
Supply & Pricing Matrix
The Île-de-France engineering cluster's turbofan propulsion capacity constraints directly determine downstream pricing power for long-range cruise missile systems across European defense procurement. REACH compliance timelines and EMA certification bottlenecks amplify this concentration, allowing cleared primes to command sustained premiums while smaller militaries face extended delivery schedules.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in European cruise missile procurement. Price differentiation rests on certification grade for military airworthiness and volume scale of multi-year framework agreements. Pricing pressure stems from export-credit leasing arrangements that transfer sustainment risk to manufacturers, compressing upfront margins. Smaller Baltic and Nordic navies exhibit highest price sensitivity due to constrained procurement budgets, while Franco-British joint programs demonstrate lowest sensitivity given strategic deterrence imperatives.
Supply Chain Analysis
Single-source vulnerability in turbofan engine components dominates supply chain risk for European cruise missile production. Geographic supply concentration centers on France, the United Kingdom, and Norway for propulsion systems and seeker electronics. Raw material dependencies draw from specialized alloys for combustor housings, ring-laser gyro substrates, and precision-machined guidance frames. Distribution runs through prime contractor dockside maintenance facilities aligned with naval dry-docking cycles and airbase cluster logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European cruise missile market sits at a platform-economics inflection where open mission system interfaces are fragmenting traditional prime-lock-in, creating new competitive surface for modular subsystem specialists.
For Market Incumbents: Insulate terminal homing algorithm capabilities through selective hiring from national laboratory talent pools and accelerated patent filing around machine-vision discrimination architectures. MBDA and Saab should deepen backward integration into turbofan combustor manufacturing to capture EU Green Deal compliance premiums before Nordic tender deadlines. The emerging threat of modular seeker specialists disintermediating full-system integration demands preemptive channel control through exclusive maintenance facility joint ventures in Poland and Romania. For New Entrants and Emerging Players: Ground-based mobile launcher integration for Polish territorial defense programs represents the most penetrable entry point given Warsaw's accelerated procurement timeline ahead of continental peers. Baltic naval leasing structures favor subsystem specialists offering 10-year operational service contracts with embedded sustainment risk transfer. A go-to-market angle anchored in REACH pre-certified propulsion components reduces EMA validation burdens that otherwise delay fielding by 18-36 months against established primes. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because military airworthiness certification relationships and cleared defense industrial base access create durable moats that compound across procurement cycles. Acquisition targets should display established EMA correspondence files and existing export-credit agency relationships with Nordic or Baltic national lenders. The signal to watch is Poland's facility investment announcements, which indicate which primes have secured first-mover positioning in the Warsaw-Łódź corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Seeker Architecture Development | Saab's open mission system interfaces reduce integration costs for Gripen operators across Nordic states. |
| Export-Credit Leasing Structure Adoption | Kongsberg's 10-year operational service contracts transfer sustainment risk and accelerate Baltic procurement decisions. |
| REACH-Compliant Propulsion Redesign | MBDA's combustor architecture investments capture premium positioning in EU Green Deal tender evaluations. |
| Local Maintenance Facility Establishment | Poland's Warsaw-Łódź corridor investments anchor Nordic prime competitive access for ground-based launcher programs. |
| Terminal Homing Algorithm Talent Acquisition | Machine-vision discrimination expertise concentrated in French and Swedish engineering centers commands scarcity premiums. |
Research Methodology
A spread of perspectives from program managers at European naval procurement agencies, airworthiness certification leads at EMA and national military bodies, propulsion subsystem engineers at cleared defense industrial base suppliers, and export-credit agency defense sector underwriters converged on the working assumptions. Primary interview insights combined with secondary validation from EU defence procurement databases, EMA certification registries, REACH compliance filings, and national military framework agreement disclosures. Bottom-up build-ups of platform-specific procurement volumes triangulated against top-down defense budget allocation analysis across the analysis window.
Demand-supply balance modeling anchored forecast outputs, with segmentation across naval, airborne, ground-based, and submarine platforms intersecting with short-range through extra long-range capability tiers. Guidance system architecture evolution and warhead type authorization frameworks provided additional industry-specific dimensions. CAGRs derived from weighted scenario analysis of procurement timeline acceleration in Poland against Franco-British joint program sustainment patterns. Turbofan propulsion cost structure trajectories and export-credit leasing penetration rates served as key forecast inputs.
Practitioners should monitor Polish defense spending authorization delays, REACH propellant chemistry waiver decisions, and EMA certification timeline compressions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Land-Based Remote Weapon Stations Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market