
 Latin America Self -Monitoring Blood Glucose Market | 2026-2036
Latin America Self -Monitoring Blood Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Self -Monitoring Blood Glucose Market Foresight
Home care patients is rotating toward continuous and connected glucose monitoring solutions as healthcare systems across Latin America push chronic disease management outside hospital walls. Abbott Laboratories leverages its FreeStyle platform ecosystem to sustain brand loyalty among insulin-dependent users across Mexico and Colombia. F. Hoffmann-La Roche AG anchors its position through diagnostic center partnerships that extend professional-grade accuracy into patient-operated devices. LifeScan competes aggressively on test strip affordability, a decisive factor in price-sensitive public procurement channels throughout the region.
Self-monitoring blood glucose encompasses portable electrochemical biosensor systems that quantitatively measure capillary glucose concentration, typically via enzymatic oxidation reactions on disposable test strips with measurement ranges of 20–600 mg/dL and five-second readout protocols. These devices serve the primary commercial purpose of enabling real-time glycemic control decisions by diabetic patients outside clinical settings, reducing acute complications and long-term end-organ damage. Test strips generate the dominant revenue pool due to recurring consumable demand, while continuous glucose monitors capture the fastest expansion trajectory as sensor durability improves and calibration requirements diminish. Home care settings command the largest end-user volume, though specialized clinics retain premium pricing power through bundled educator support and device training services.
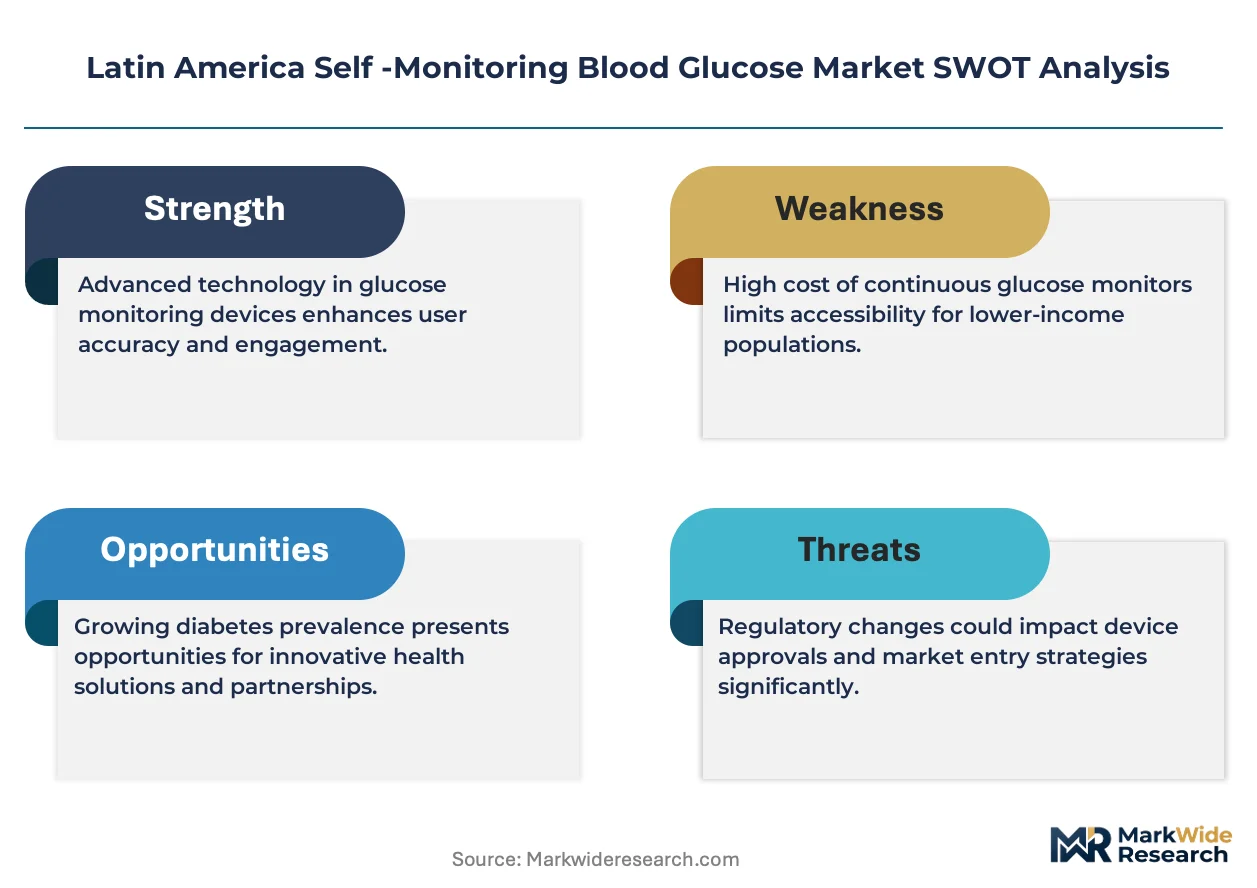
ANVISA in Brazil and COFEPRIS in Mexico enforce medical device registration and post-market surveillance requirements that shape product standardization and import timelines for glucose monitoring equipment across the region. Brazil's RDC 185/2001 and subsequent resolutions establish risk-classification frameworks that determine clinical evidence thresholds, directly influencing which sensor technologies achieve market access. Stakeholders must monitor evolving reimbursement list inclusions under national health systems, as coverage expansion for continuous monitoring in Type 1 diabetes patients would redirect volume toward higher-margin sensor platforms and away from conventional meter-strip configurations.
Market Dynamics
Continuous glucose monitoring technology is fragmenting traditional meter-strip economics across Latin America, forcing incumbents to defend consumable revenue pools against sensor-based alternatives that eliminate daily fingerstick requirements.
Growth Catalysts
- ANVISA registration streamlining:Brazil's simplified medical device pathways under RDC 185/2001 reduce clinical evidence burdens for Class II glucose sensors, cutting market entry timelines for international manufacturers.
- Home care migration:Public health systems in Mexico and Colombia actively discharge diabetic patients from hospital-based monitoring, expanding addressable populations for patient-operated devices.
- Enzymatic sensor advances:Improved glucose oxidase formulations extend test strip shelf stability in tropical climates, reducing distribution losses across humid supply corridors.
Market Restraints
- Import concentration risk:Over 70% of electrochemical biosensor chips enter Latin America through a single customs corridor at São Paulo-Guarulhos, creating vulnerability to port congestion.
- Reimbursement fragmentation:Brazil's SUS, Mexico's INSABI, and Colombia's EPS regimes maintain incompatible coverage codes for continuous versus intermittent monitoring, forcing manufacturers to maintain parallel product portfolios.
- Substitution acceleration:Factory-calibrated continuous sensors eliminate patient error variables that conventional meters rely upon for differentiation, compressing premium pricing power.
Strategic Opportunities
- Peru and Chile expansion:These markets remain underpenetrated relative to Brazil and Mexico, with private insurance channels showing willingness to pre-authorize continuous monitoring for Type 1 pediatric cases.
- Telemedicine integration:Remote glucose data transmission into national electronic health records creates stickiness for platform-locked device ecosystems.
- COFEPRIS fast-track incentives:Mexico's priority review for devices addressing non-communicable disease burdens offers timeline advantages for novel form factor submissions.
Industry Challenges
- Biomedical engineer scarcity:Local talent pools lack depth in electrochemical sensor calibration, forcing manufacturers to import technical support from Miami or Madrid.
- Legacy system integration:Hospital information systems across the region run incompatible data protocols, complicating cloud-connected glucose meter deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Self -Monitoring Blood Glucose Market |
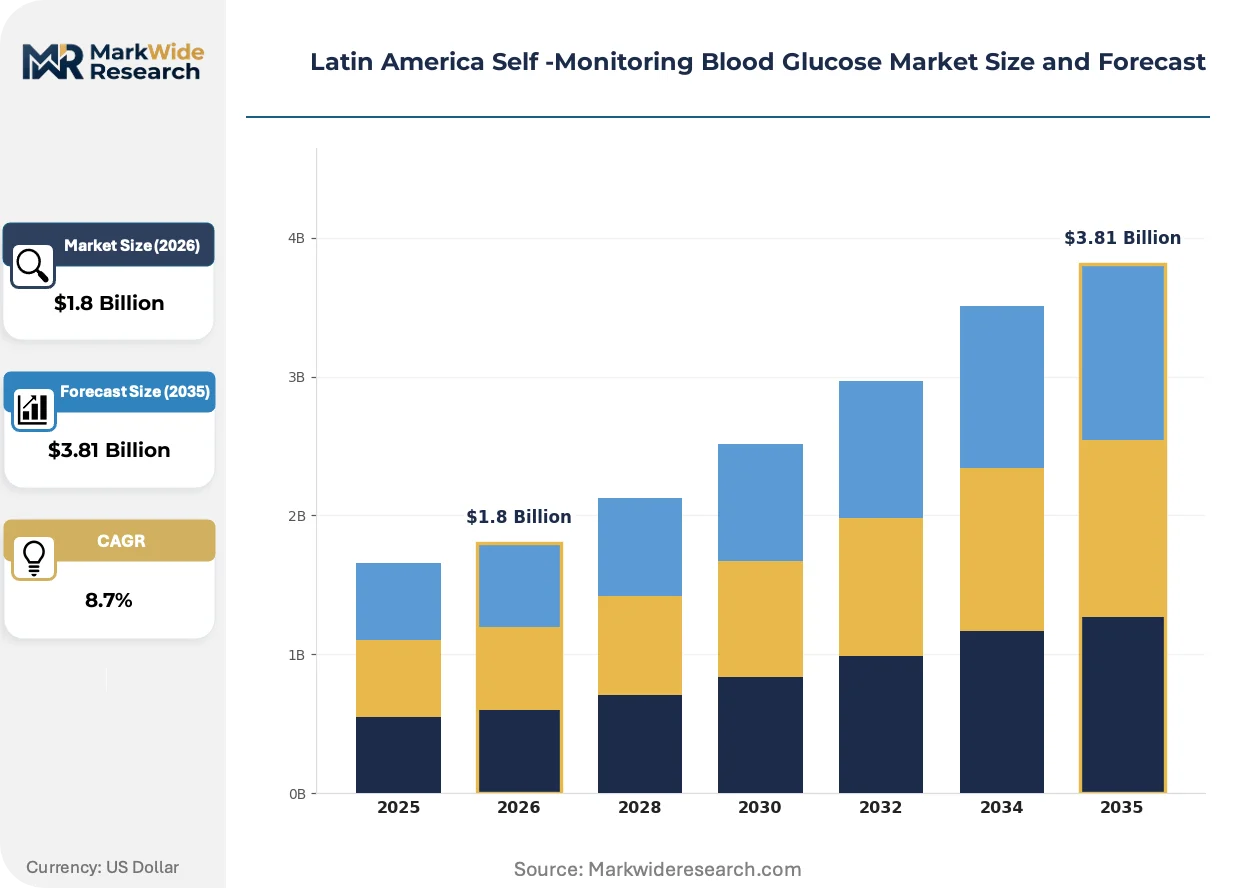
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Test Strips, Lancets, Control Solutions Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Hypoglycemia Management End User: Home Care, Diagnostic Centers, Pharmacies, Specialized Clinics, Endocrinology Practices Distribution Channel: Retail Pharmacies, Online Pharmacies, Medical Supply Stores, Hospitals, Diabetes Care Centers |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, LifeScan, Ascensia Diabetes Care, Arkray, AgaMatrix, Trividia Health, Bionime, Acon Laboratories, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Self -Monitoring Blood Glucose Market Shifts & Advancements
Sensor miniaturization and algorithmic calibration advances are collapsing the cost gap between continuous and traditional monitoring, reshaping competitive positioning across Latin American procurement channels.
Non-invasive optical glucose sensing is fragmenting R&D investment priorities among established players. Several consortia now pursue spectroscopic approaches using near-infrared or Raman scattering to eliminate consumable dependence entirely. Early-stage pilots with Brazilian university hospitals indicate measurement variance remains unacceptable for insulin dosing decisions, but the technology is compressing pricing power in wellness-adjacent segments where clinical accuracy requirements relax.
ANVISA's alignment with International Medical Device Regulators Forum (IMDRF) standards is harmonizing technical documentation requirements across Mercosur trading partners. This regulatory convergence enables single-registration strategies that previously required separate dossiers for Brazil, Argentina, and Paraguay. Multinational manufacturers with regional headquarters in São Paulo are consolidating quality management systems to capture these administrative efficiencies.
Patient-driven purchasing is displacing physician-directed procurement in Mexican pharmacy channels. Retail chains in Mexico City and Guadalajara now stock premium continuous monitors adjacent to over-the-counter test strips, enabling direct consumer selection based on smartphone app compatibility. This channel shift forces manufacturers to invest in point-of-sale education materials previously unnecessary in clinical-dispensing models.
Latin America Self -Monitoring Blood Glucose Market Segmentation
Segmentation in Latin American glucose monitoring reflects divergent reimbursement regimes and climate-driven supply constraints. Product categories split between consumable-dependent systems and durable sensor platforms, while end-user channels track the regional push toward decentralized diabetes management.
Product Type:
Domestic manufacturing concentrates in test strip assembly for Brazilian and Mexican markets, while continuous glucose monitors enter entirely through import channels regulated by ANVISA and COFEPRIS.
- Blood Glucose Meters:Handheld electrochemical analyzers with digital displays and memory storage for glucose readings. Demand clusters in Brazilian public procurement under SUS expansion programs, where device durability in tropical humidity drives specification requirements.
- Continuous Glucose Monitors:Factory-calibrated wearable sensors transmitting real-time glucose data to smartphone applications. Mexican private insurance channels show accelerating pre-authorization rates for Type 1 pediatric patients, displacing conventional meter-strip combinations in premium segments.
- Test Strips:Disposable enzymatic biosensors dominating recurring revenue pools across Latin American retail pharmacy networks.
- Lancets:Spring-loaded puncture devices for capillary blood sampling, standardizing around 28-30 gauge specifications.
- Control Solutions:Calibrated glucose suspensions for meter accuracy verification, concentrated in clinical training programs.
Test strips command the established base. The steepest expansion runs through continuous glucose monitors.
Application:
Cost tier differentiation separates intensive insulin therapy populations from lifestyle-managed cases, with reimbursement depth determining technology access across national health systems.
- Type 1 Diabetes:Autoimmune insulin-dependent condition requiring precise glycemic monitoring. Colombian EPS networks and Brazilian SUS are expanding continuous monitor coverage for this population, creating technology upgrade pathways previously limited to private payers.
- Type 2 Diabetes:Metabolic disorder representing the volume base across Latin American glucose monitoring. Home care migration in Mexico and Brazil drives demand for simplified meter interfaces among elderly populations with limited digital literacy.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring temporary monitoring protocols.
- Prediabetes:Elevated glucose levels below diabetes threshold, generating wellness-adjacent demand.
- Hypoglycemia Management:Recurrent low blood sugar episodes requiring rapid detection capabilities.
Type 2 diabetes generates the volume foundation. Type 1 diabetes is gaining share fastest through reimbursement expansion.
End User:
Customer type fragmentation tracks the shift from hospital-based diabetes education to patient-directed monitoring, with channel margins varying by service bundling intensity.
- Home Care:Patient-operated monitoring outside clinical settings. Brazilian municipal health secretariats are distributing meters directly to diagnosed populations, bypassing traditional pharmacy dispensing and compressing retail margins.
- Diagnostic Centers:Professional laboratory environments with certified accuracy standards. Mexican laboratory chains are deploying point-of-care analyzers with electronic health record integration, creating platform stickiness for affiliated meter brands.
- Pharmacies:Retail dispensing with over-the-counter and prescription channels.
- Specialized Clinics:Diabetes-focused care with educator-supported device training.
- Endocrinology Practices:Specialist-directed therapy adjustment with premium device recommendations.
Home care holds the volume concentration. Specialized clinics maintain the margin premium.
Distribution Channel:
Supply concentration in São Paulo-Guarulhos customs corridor shapes inventory strategies, with online channels gaining traction where regulatory documentation permits direct-to-patient shipment.
- Retail Pharmacies:Brick-and-mortar dispensing with pharmacist counseling. Mexican chains in Mexico City and Guadalajara are creating dedicated diabetes sections with continuous monitor displays, shifting consumer selection from clinical to retail environments.
- Online Pharmacies:E-commerce platforms with home delivery logistics. Brazilian regulatory frameworks are adapting to permit prescription verification for remote glucose monitor purchases, expanding addressable geography beyond urban pharmacy density.
- Medical Supply Stores:Durable medical equipment specialists with insurance billing expertise.
- Hospitals:Institutional procurement for inpatient and discharge programs.
- Diabetes Care Centers:Specialized facilities with integrated education and supply services.
Retail pharmacies anchor the established volume. Online pharmacies are climbing the fastest through regulatory adaptation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import corridors through São Paulo-Guarulhos channel over 70% of electrochemical biosensor chips entering Latin America, creating single-point vulnerability that shapes inventory strategies across the region's glucose monitoring supply chain.
Brazil
Municipal health secretariats distribute meters directly to diagnosed diabetic populations, bypassing pharmacy dispensing channels. ANVISA's RDC 185/2001 risk-classification framework determines clinical evidence thresholds for sensor technologies. São Paulo anchors domestic test strip assembly operations while serving as the primary customs entry point for imported continuous monitor components.
Mexico
Retail chains in Mexico City and Guadalajara stock continuous monitors adjacent to over-the-counter test strips, shifting consumer selection from clinical to retail environments. COFEPRIS maintains priority review pathways for devices addressing non-communicable disease burdens. The Bajío Region concentrates manufacturing partnerships that extend professional-grade accuracy into patient-operated devices.
Colombia
EPS networks are expanding continuous monitor coverage for Type 1 diabetes populations, creating technology upgrade pathways previously limited to private payers. The national health regulator enforces post-market surveillance requirements that shape product standardization timelines. Bogotá serves as the distribution hub for Andean corridor supply chains reaching Ecuador and Peru.
Argentina
ANVISA's alignment with IMDRF standards enables single-registration strategies that previously required separate dossiers for Mercosur trading partners. The national pharmaceutical regulator maintains incompatible coverage codes with Brazilian SUS for continuous versus intermittent monitoring. Buenos Aires concentrates regional headquarters operations for multinational quality management system consolidation.
Chile
Private insurance channels show willingness to pre-authorize continuous monitoring for Type 1 pediatric cases in this underpenetrated market relative to Brazil and Mexico. The national health system runs incompatible data protocols with hospital information systems across the region. Santiago anchors telemedicine integration pilots that transmit remote glucose data into national electronic health records.
Latin America Self -Monitoring Blood Glucose Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates that leverage platform ecosystems to sustain brand loyalty among insulin-dependent users. The vendor base spans three strategic tiers: multinational conglomerates with full-stack glucose monitoring portfolios, regional distributors specializing in test strip affordability for price-sensitive procurement channels, and emerging sensor technology specialists pursuing continuous monitoring form factors. Competitive moves center on diagnostic center partnerships that extend professional-grade accuracy into home care settings, alongside telemedicine platform integrations that create data transmission stickiness.
Among Switzerland-based diagnostics specialists, F. Hoffmann-La Roche AG exemplifies the conglomerate archetype through its positioning across professional laboratory and patient-operated device segments. Abbott Laboratories represents the platform-locked ecosystem approach, leveraging application compatibility to sustain recurring revenue relationships. LifeScan occupies a position within the affordability-focused tier, competing through test strip cost structures decisive in public procurement channels throughout the region.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| LifeScan |
| Ascensia Diabetes Care |
| Arkray |
| AgaMatrix |
| Trividia Health |
| Bionime |
| Acon Laboratories |
| Others |
Supply & Pricing Matrix
Factory-calibrated continuous sensors displacing enzymatic test strips redraw procurement geography across Latin America, compressing margins in Brazilian retail pharmacy networks while concentrating premium pricing power with Mexican private insurers pre-authorizing wearable platforms.
Pricing Analysis
Volume-discount tiering structures dominate public procurement channels, with Brazilian SUS municipal contracts commanding 40-60% price reductions on meter-strip bundles versus private pharmacy retail. Three-tier pricing structure across premium, standard, and economy levels separates Abbott's FreeStyle ecosystem from LifeScan's value-positioned strips and unbranded economy alternatives. Pricing pressure stems from COFEPRIS fast-track approvals accelerating generic sensor entry into Mexican retail chains. Public health systems exhibit extreme price sensitivity, while specialized endocrinology practices retain willingness to pay premium rates for continuous monitor training support.
Supply Chain Analysis
Inventory lead times extending 90-120 days force Brazilian distributors to maintain 8-10 week safety stocks of enzymatic test strips, inflating working capital requirements across humid climate corridors. Manufacturing concentrates in China for electrochemical biosensor chips, the United States for continuous monitor transmitters, and domestic Brazilian assembly for lancet and strip packaging. Raw material dependencies span glucose oxidase enzymes, palladium electrode substrates, and medical-grade adhesives. Single-source vulnerability runs through the São Paulo-Guarulhos customs corridor, where port congestion events have disrupted 70% of regional glucose monitor imports. Distribution runs through layered distributor networks serving retail pharmacy chains, with direct-to-patient online channels gaining regulatory clearance in selected Mexican states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where smartphone app interoperability determines patient lock-in, with ANVISA's IMDRF alignment enabling single-registration strategies that reward ecosystem consolidation across Mercosur trading partners.
For Market Incumbents: Compound platform stickiness through telemedicine EHR integration partnerships that raise switching costs for insulin-dependent users, while backward integration into enzymatic sensor manufacturing insulates margin structures against Chinese biosensor chip tariff exposure. Prioritize certification investment under ANVISA's streamlined Class II pathways to accelerate sensor durability improvements ahead of generic entrants. For New Entrants and Emerging Players: Telemedicine data transmission services represent a service-layer gap where Abbott and Roche under-serve small Colombian EPS networks lacking internal IT infrastructure. Target pediatric Type 1 diabetes cases in Chilean and Peruvian private insurance channels, where pre-authorization willingness exceeds supply of Spanish-language educator support. Pursue COFEPRIS priority review for factory-calibrated sensors addressing non-communicable disease burdens as the fastest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors sensor technology specialists with durable IP positions over legacy meter-strip incumbents. Long-term viability across the projection horizon hinges on continuous monitor platform economics displacing consumable-dependent revenue pools. Acquisition target archetype: emerging sensor developers with ANVISA registration progress and established Brazilian distribution relationships. The signal to watch is SUS reimbursement list expansion for continuous monitoring in Type 1 populations, which would redirect volume toward higher-margin sensor platforms.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Registration | Accelerated market entry under RDC 185/2001 cuts clinical evidence burdens for Class II glucose sensors. |
| Telemedicine Platform Integration | Remote glucose data transmission into Colombian EPS electronic health records creates patient ecosystem lock-in. |
| Domestic Test Strip Assembly Expansion | São Paulo-based manufacturing reduces import dependency and customs corridor vulnerability for Brazilian market coverage. |
| Continuous Monitor Reimbursement Strategy | SUS coverage expansion for Type 1 diabetes redirects procurement volume toward premium sensor platforms. |
| Enzymatic Sensor R&D Partnership | Brazilian university hospital pilots advance tropical climate stability formulations for extended strip shelf life. |
Research Methodology
Cross-validation between primary interviews with Brazilian biomedical engineers, Mexican pharmacy chain procurement directors, Colombian EPS formulary managers, and Argentine regulatory affairs specialists anchors the qualitative findings against secondary validation through ANVISA registration databases, COFEPRIS approval records, SUS procurement bulletins, and EPS coverage code publications. Bottom-up patient population estimates triangulate with top-down device shipment data from regional customs corridors.
Sensitivity analysis across the analysis window tests forecast robustness against reimbursement policy shifts, sensor technology substitution rates, and import corridor disruption scenarios. Segmentation dimensions modeled include product type, diabetes application, end-user channel, and distribution pathway. CAGRs derive from patient prevalence projections, technology penetration curves, and pricing trajectory assumptions specific to public versus private procurement channels. Industry-specific inputs span ANVISA registration timelines, COFEPRIS priority review throughput rates, and SUS municipal distribution program expansion schedules.
Underlying assumptions cover reimbursement stability in Brazilian SUS and Mexican INSABI frameworks, with deviation risk concentrated in regulatory harmonization delays across Mercosur trading partners and continuous sensor calibration accuracy improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market