
 United Kingdom Blood Glucose Monitoring Market | 2026-2036
United Kingdom Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Blood Glucose Monitoring Market Analytics
The NHS Net Zero Supplier Roadmap is pivoting procurement criteria toward lower-waste lancet designs and rechargeable monitoring hardware. Abbott leverages its FreeStyle portfolio to dominate pharmacy-led distribution across NHS Integrated Care Systems. Dexcom competes through sensor accuracy claims that sustain premium positioning among Type 1 diabetes patients. GlucoRx anchors value-tier supply through its exclusive retail partnerships with major UK pharmacy chains.
Blood glucose monitoring encompasses electrochemical biosensor systems that measure interstitial fluid or capillary glucose concentration, typically via glucose oxidase reactions producing microampere-level current signals proportional to substrate concentration. These devices serve primarily to enable insulin dosing decisions and hypoglycaemia prevention in diabetes management. Continuous glucose monitors capture the fastest expansion as real-time data streams displace fingerstick routines among tech-adopter patient cohorts. Testing strips still occupy the largest revenue pool due to massive prescription volumes under NHS tariff structures. Remote monitoring platforms are concentrating margin capture by reducing clinic visit burdens and enabling automated glycaemic alerts.
The Medicines and Healthcare products Regulatory Agency classifies connected glucose devices as software-as-medical-device, mandating clinical validation and cybersecurity documentation for market authorisation. NHS England's Technology Appraisal Programme sets reimbursement thresholds that directly determine which sensor formats achieve routine commissioning. BSI Group administers UKCA marking conformity assessments for post-Brexit device certification, replacing prior CE-marking reliance. Stakeholders must monitor evolving interoperability standards between hospital electronic health records and patient-owned monitoring apps to anticipate procurement specification shifts.
Market Dynamics
NHS England's Technology Appraisal Programme is compressing reimbursement timelines for continuous glucose monitors while MHRA software-as-medical-device rules reshape platform compliance costs. This regulatory dual-track is forcing manufacturers to split development resources between sensor accuracy claims and cloud security documentation.
Growth Catalysts
- NHS Net Zero Supplier Roadmap:Procurement criteria now mandate lower-waste lancet designs and rechargeable hardware specifications. This framework is redirecting R&D budgets toward sustainable material sourcing.
- Type 1 diabetes patient cohorts:Real-time data streaming is displacing fingerstick routines among tech-adopter populations concentrated in Greater London and the South East. Specialist diabetes centre density in these regions accelerates premium device uptake.
- Hospital electronic health record integration:Interoperability mandates from NHS England are pulling cloud-integrated platforms into inpatient glycaemic control protocols. Procurement specifications increasingly require automated alert transmission to clinical dashboards.
Market Restraints
- Testing strip tariff structures:NHS prescription volumes lock revenue pools in legacy consumable formats. This concentration limits capital available for continuous monitor sensor production scaling.
- UKCA marking transition costs:BSI Group conformity assessments for post-Brexit certification are extending product launch timelines. Small manufacturers face disproportionate documentation burdens relative to large portfolio holders.
- Interstitial fluid measurement lag:Physiological delay between blood and tissue glucose readings creates clinical scepticism in acute care settings. This technical limitation slows hospital procurement committee approvals.
Strategic Opportunities
- Remote monitoring platform expansion:Automated glycaemic alerts are reducing clinic visit burdens for NHS Integrated Care Systems. Margin capture concentrates in software layers that aggregate patient-owned device data.
- Pharmacy-led distribution channels:Exclusive retail partnerships with major UK pharmacy chains are opening direct-to-patient pathways outside hospital procurement. This channel bypasses traditional tender processes.
- Scotland and Northern England penetration:Specialist diabetes centre density gaps in these regions represent underdeveloped demand for premium continuous monitors. Targeted deployment could replicate South East adoption patterns.
Industry Challenges
- Cybersecurity documentation complexity:MHRA software-as-medical-device guidance requires clinical validation evidence that many legacy platform architectures cannot readily generate. Retrofitting existing systems is stretching engineering capacity.
- Legacy electronic health record integration:Hospital IT infrastructure heterogeneity is forcing bespoke API development for each NHS trust. This fragmentation is consuming implementation resources that could scale standardised deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Blood Glucose Monitoring Market |
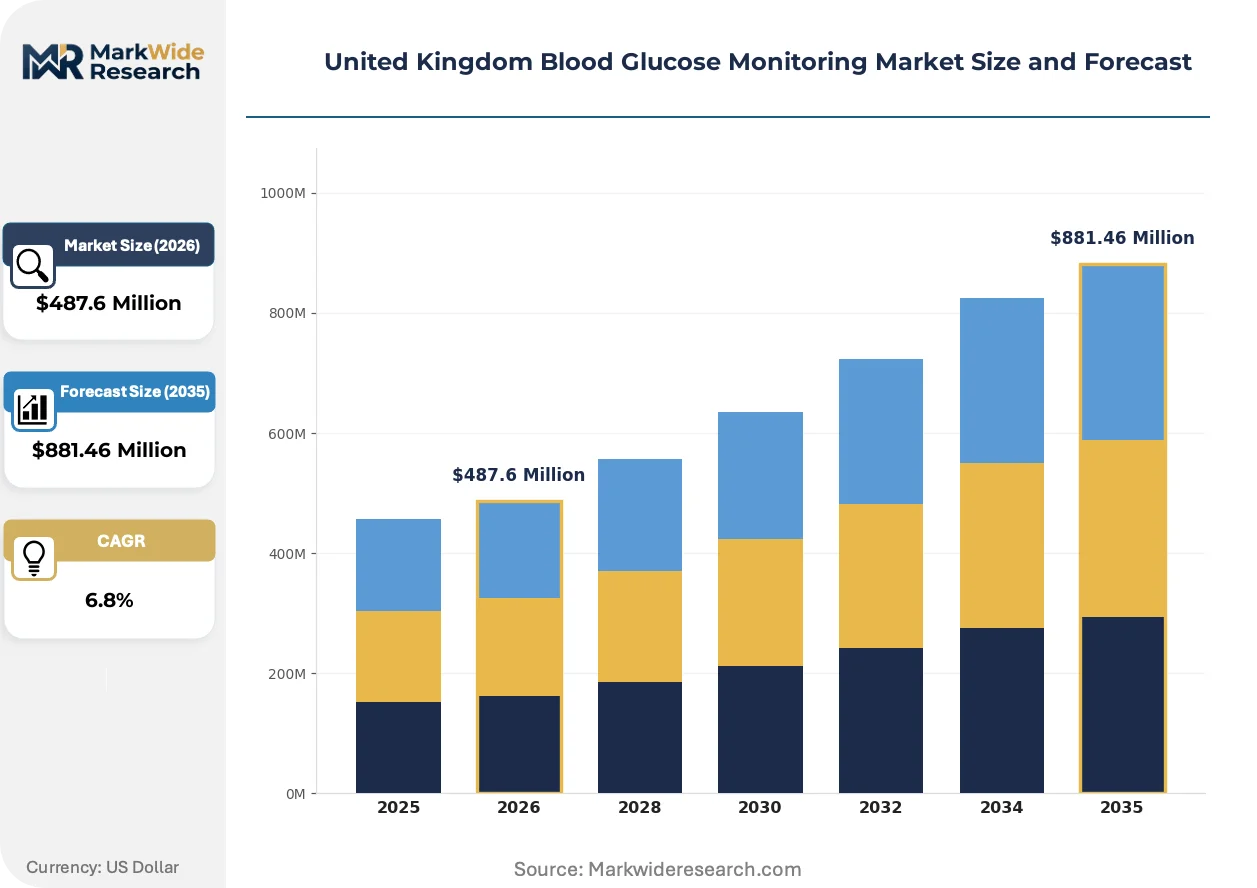
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Blood Glucose Meters, Testing Strips, Lancets End User: Diabetes Patients, Healthcare Professionals, Laboratories, Home Care Settings Technology: Self-Monitoring, Remote Monitoring, Mobile Apps, Cloud Integration Distribution Channel: Pharmacies, Online Retail, Hospitals, Specialty Stores |
| Companies Covered | Medtronic, Lifescan, Abbott, GlucoRx, Nemaura Medical, Dexcom, Ascensia Diabetes Care, Senseonics, Roche Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Blood Glucose Monitoring Market Evolving Landscape
Sensor miniaturisation and algorithmic glucose prediction are compressing the boundary between consumer wellness devices and regulated medical equipment. Manufacturers now face choices about which regulatory pathway to pursue.
Non-invasive optical glucose sensing is converging with machine learning calibration models to reduce fingerstick dependency. Early adopters in Type 1 diabetes self-management cohorts are trialling smartphone-integrated prototypes. This convergence is blurring competitive positioning between traditional electrochemical biosensor manufacturers and consumer electronics entrants.
MHRA's updated software-as-medical-device guidance is accelerating cloud-integrated platform approvals while tightening cybersecurity audit requirements. Connected glucose devices must now demonstrate clinical validation across multiple patient demographics before market authorisation. Continuous glucose monitor formats are most affected, with manufacturers adding dedicated compliance teams to manage documentation throughput.
Patients are consolidating device selection authority through direct pharmacy purchasing rather than clinician-mediated prescriptions. This pattern disrupts traditional hospital procurement hierarchies and shifts influence toward retail channel relationships. Greater London and the South East exhibit the strongest self-directed buying behaviour, driven by higher digital health literacy and disposable income concentration.
United Kingdom Blood Glucose Monitoring Market Segmentation
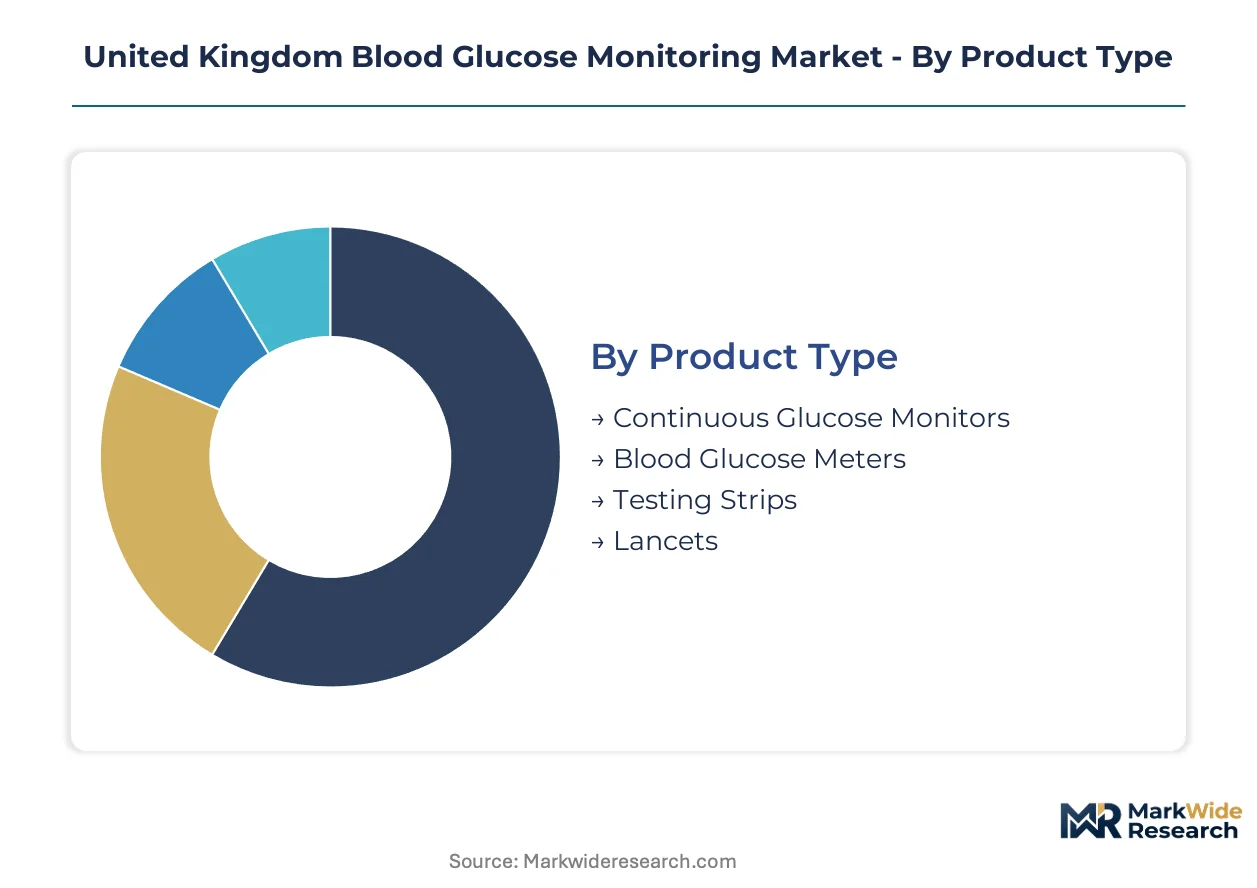
Segmentation reveals how NHS procurement hierarchies and patient self-direction split demand across contrasting access pathways. Supply concentration in pharmacy-led channels versus hospital tender processes creates divergent margin structures for manufacturers.
Product Type:
Supply concentration clusters around consumable formats with recurring prescription volumes, while capital-intensive sensor platforms require differentiated manufacturing scale.
- Continuous Glucose Monitors:Electrochemical biosensor systems capture interstitial fluid glucose through glucose oxidase reactions producing microampere-level current signals. NHS England's Technology Appraisal Programme reimbursement expansion in Greater London and the South East specialist diabetes centres accelerates premium uptake among Type 1 cohorts.
- Testing Strips:Single-use electrochemical strips dominate prescription volumes under NHS tariff structures, locking revenue pools in legacy consumable formats. Massive dispensing volumes through pharmacy channels sustain manufacturer cash flows despite compressed per-unit margins.
- Blood Glucose Meters:Handheld capillary sampling devices serve insulin dosing decisions across home care settings.
- Lancets:Lower-waste designs are gaining procurement preference under NHS Net Zero Supplier Roadmap criteria.
Testing strips absorb the bulk of installed capacity; continuous glucose monitors are expanding most quickly.
End User:
Cost tier stratification separates acute care procurement from direct-to-patient retail acquisition, with divergent price sensitivity and decision authority.
- Diabetes Patients:Self-directed purchasing through pharmacy channels is consolidating device selection authority outside clinician-mediated prescriptions. Greater London and South East populations exhibit strongest digital health literacy and disposable income concentration for premium continuous monitor adoption.
- Healthcare Professionals:Hospital electronic health record integration mandates from NHS England pull cloud-integrated platforms into inpatient glycaemic control protocols with automated alert requirements.
- Home Care Settings:Remote monitoring deployment reduces clinic visit burdens for NHS Integrated Care Systems.
- Laboratories:Centralised testing facilities maintain reference standard calibration for point-of-care device validation.
Diabetes patients represent the highest volume endpoint; healthcare professionals command the steepest expansion trajectory through interoperability mandates.
Technology:
Application urgency distinguishes real-time acute care alerts from retrospective self-management data review, shaping regulatory pathway choices.
- Remote Monitoring:Cloud-integrated platforms aggregate patient-owned device data for automated glycaemic alerts, concentrating margin capture in software layers. MHRA software-as-medical-device guidance accelerates approvals while tightening cybersecurity audit documentation burdens.
- Self-Monitoring:Fingerstick routines persist among cost-sensitive populations and clinical sceptics regarding interstitial fluid measurement lag in acute settings.
- Mobile Apps:Patient-facing interfaces require clinical validation across multiple demographics under updated MHRA market authorisation rules.
- Cloud Integration:Bespoke API development for each NHS trust consumes implementation resources due to hospital IT infrastructure heterogeneity.
Self-monitoring retains the largest user base; remote monitoring is gaining share fastest through NHS England interoperability mandates.
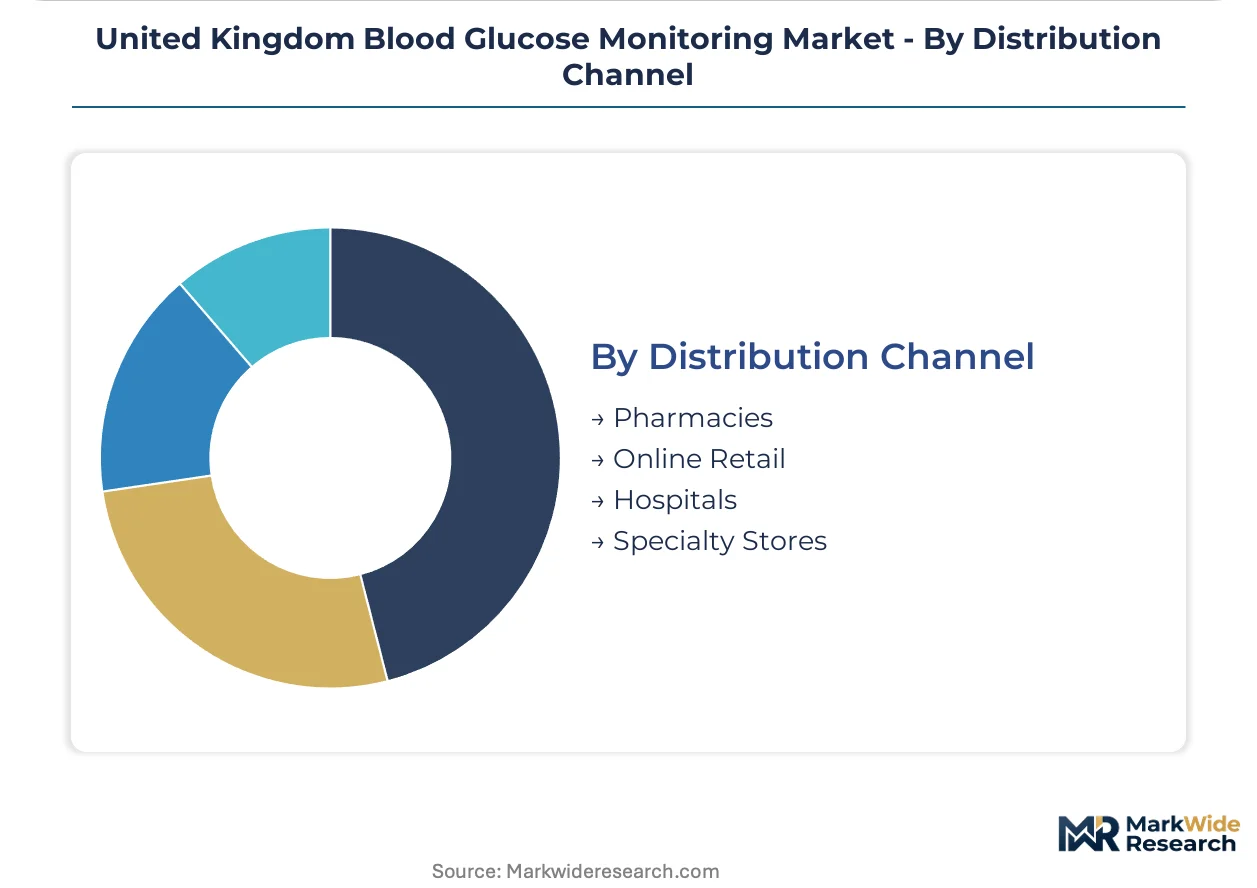
Distribution Channel:
Customer type fragmentation splits between institutional procurement committees and individual pharmacy transactions, with distinct working capital and relationship intensity requirements.
- Pharmacies:Exclusive retail partnerships with major UK pharmacy chains open direct-to-patient pathways bypassing traditional hospital tender processes. Abbott leverages FreeStyle portfolio dominance across NHS Integrated Care Systems through this channel.
- Hospitals:Procurement specifications increasingly require automated alert transmission to clinical dashboards and electronic health record compatibility.
- Online Retail:Digital health literacy concentration in Greater London and South East drives self-directed continuous monitor purchases.
- Specialty Stores:Diabetes-focused retailers serve tech-adopter patient cohorts seeking premium device consultation.
Pharmacies command the deepest volume penetration; hospitals are climbing the fastest through glycaemic control protocol tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London and the South East specialist diabetes centre clusters dominate procurement volumes for continuous glucose monitoring systems. NHS England's Technology Appraisal Programme reimbursement expansion concentrates premium device uptake in these metropolitan corridors. Regional procurement patterns diverge sharply between these southern hubs and peripheral NHS Integrated Care Systems.
London and South East England
Tech-adopter Type 1 diabetes patient cohorts drive real-time data streaming adoption through pharmacy-led distribution channels. NHS England's interoperability mandates pull cloud-integrated platforms into hospital electronic health record systems across this region. Specialist diabetes centre density in Greater London accelerates premium continuous monitor deployment faster than any other UK sub-region.
Midlands
Industrial manufacturing heritage supports electrochemical biosensor component supply chains serving domestic device assembly. MHRA software-as-medical-device guidance compliance costs weigh more heavily on smaller regional manufacturers lacking dedicated regulatory teams. Birmingham and Coventry clusters host testing strip production facilities optimized for NHS prescription volume fulfillment.
North England
Underdeveloped specialist diabetes centre density creates penetration gaps for premium continuous monitors relative to southern benchmarks. NHS Net Zero Supplier Roadmap procurement criteria redirect hospital trust purchasing toward lower-waste lancet designs and rechargeable hardware. Manchester and Leeds academic medical centres pilot remote monitoring platform integration with variable electronic health record compatibility.
Scotland
NHS Scotland Technology Appraisal Programme operates parallel reimbursement frameworks with distinct commissioning thresholds from England. Scottish Health Technologies Group assessments determine continuous glucose monitor availability through territorial health boards. Edinburgh and Glasgow specialist centres concentrate glycaemic control protocol development for inpatient settings.
Wales
All-Wales Medicines Strategy Group appraisal processes create additional regulatory navigation requirements for device manufacturers. Rural geography fragments pharmacy-led distribution reach, privileging hospital procurement channels for continuous monitor access. Cardiff and Swansea health board clusters demonstrate lower digital health literacy penetration than London benchmarks.
United Kingdom Blood Glucose Monitoring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor accuracy and software integration capabilities. The vendor base stratifies into three tiers: multinational portfolio holders with NHS Integrated Care System pharmacy dominance, mid-scale specialists competing through exclusive retail partnerships, and regional value-tier suppliers capturing prescription volume. Two strategic archetypes predominate: technology licensors leveraging sensor accuracy claims for premium positioning, and distribution-integrated players controlling direct-to-patient pathways. Competitive moves concentrate on exclusive pharmacy chain partnerships and cloud platform interoperability certifications.
Within the multinational portfolio holder tier, Abbott and Dexcom exemplify contrasting positioning strategies. Abbott anchors pharmacy-led distribution across NHS Integrated Care Systems through its FreeStyle portfolio dominance. Dexcom occupies a premium-tier position sustained by sensor accuracy claims among Type 1 diabetes patient cohorts. GlucoRx represents the value-tier archetype through exclusive retail partnerships with major UK pharmacy chains.
| Leading Market Players |
|---|
| Medtronic |
| Lifescan |
| Abbott |
| GlucoRx |
| Nemaura Medical |
| Dexcom |
| Ascensia Diabetes Care |
| Senseonics |
| Roche Diabetes Care |
| Others |
Value Network & Pricing Analysis
NHS Net Zero Supplier Roadmap mandates gate qualified supply and premium-tier pricing access, forcing manufacturers to absorb sustainable material sourcing costs or surrender high-margin procurement slots to compliant rivals. This environmental framework stratifies the vendor base between accredited premium suppliers and excluded commodity players.
Pricing Analysis
Sensor accuracy claims anchor value-based pricing for continuous glucose monitors, with Dexcom and Abbott commanding premium positioning through glycaemic prediction performance validated against laboratory reference standards. Three-tier pricing structure across premium, standard, and economy levels separates hospital-integrated platforms from pharmacy-distributed meters and prescription-fulfillment strips. Cost compression in testing strip tiers is intensifying because NHS tariff structures cap reimbursement rates while raw material input costs fluctuate. Diabetes patients in Greater London and the South East exhibit lowest price sensitivity, driven by digital health literacy and disposable income concentration; rural Wales and Northern England populations remain most cost-conscious.
Supply Chain Analysis
Post-Brexit UKCA marking requirements are reshaping sourcing toward domestic assembly capacity and EU-27 component suppliers with established BSI Group conformity pathways. Electrochemical biosensor production draws from German precision manufacturing for glucose oxidase electrodes, Malaysian polymer facilities for sensor substrates, and Chinese electronics for signal processing chips. Single-source vulnerability concentrates in glucose oxidase enzyme supply, where fermentation capacity is tethered to three global producers. Distribution runs through NHS Integrated Care System procurement hierarchies for hospital tenders and exclusive pharmacy chain partnerships for direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
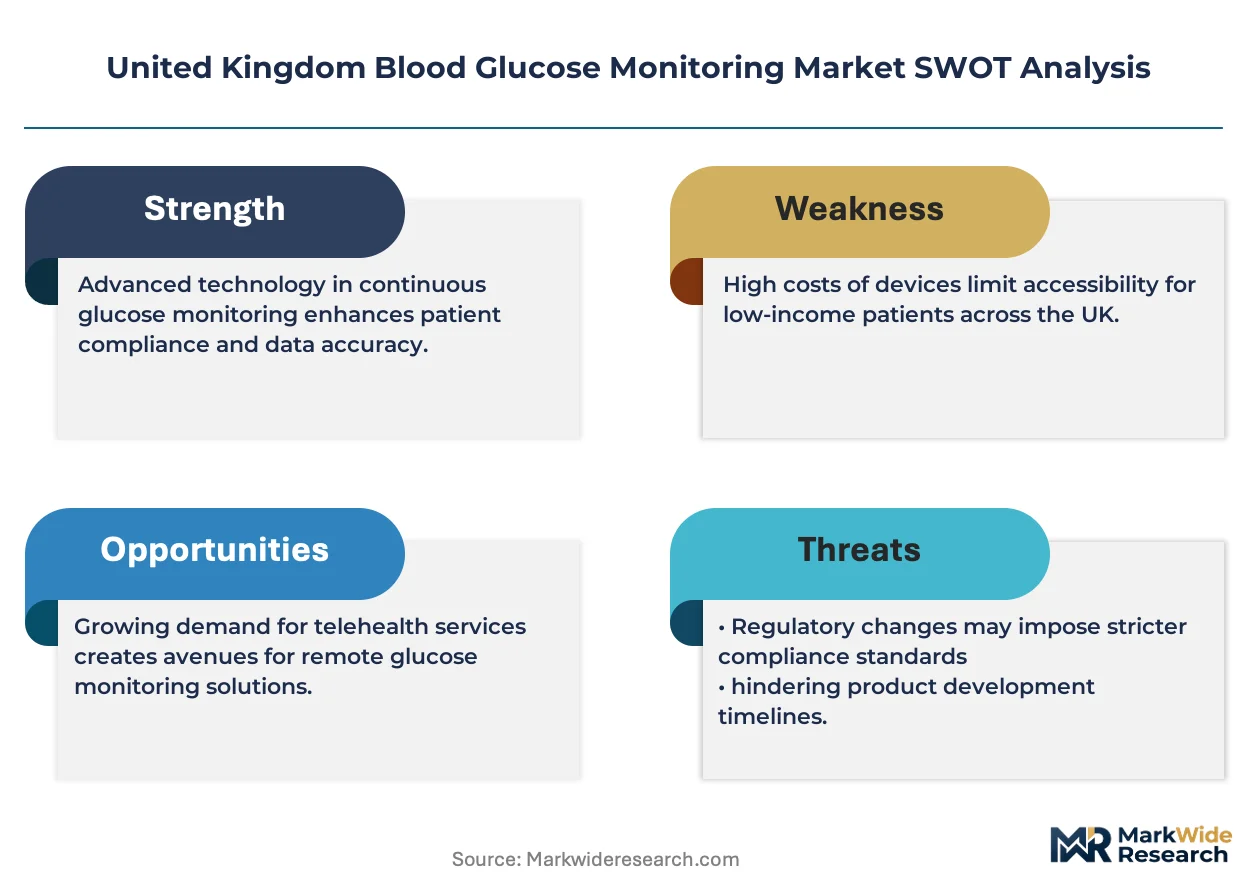
This market represents a consolidation play as MHRA software-as-medical-device compliance costs force smaller manufacturers toward acquisition or exit, concentrating share among portfolio holders with dedicated regulatory teams.
For Market Incumbents: Hedge against cloud platform commoditization by deepening exclusive pharmacy chain partnerships that bypass tender processes and lock patient data flows. Prioritize backward integration into electrochemical biosensor component manufacturing to reduce German and Malaysian supplier dependency. MHRA cybersecurity documentation burdens favor incumbents with existing compliance infrastructure over resource-constrained challengers. For New Entrants and Emerging Players: Enter via remote monitoring software layers where margin capture concentrates and hardware manufacturing scale is not required. Scotland and Northern England specialist diabetes centre density gaps offer the most penetrable geography for premium continuous monitor deployment. Pursue direct-to-patient online retail pathways in Greater London, where digital health literacy and self-directed purchasing behavior bypass traditional clinician-mediated prescription hierarchies. For Investors and Strategic Acquirers: NHS England Technology Appraisal Programme reimbursement expansion for continuous glucose monitors is the leading indicator that hospital procurement volumes will accelerate, validating premium sensor platform valuations. Target mid-scale specialists with exclusive retail pharmacy partnerships but limited regulatory team scale, as these assets complement multinational portfolio holders seeking channel control. Watch for BSI Group UKCA marking backlog clearance as the inflection signal for product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Software-as-Medical-Device Compliance Investment | Accelerates cloud platform approvals while erecting documentation barriers against undercapitalized rivals. |
| Exclusive Pharmacy Chain Partnership | Locks direct-to-patient distribution outside NHS Integrated Care System tender processes. |
| Hospital Electronic Health Record Integration | Captures inpatient glycaemic control protocol procurement through automated alert mandates. |
| Rechargeable Hardware R&D Pivot | Aligns product portfolios with NHS Net Zero Supplier Roadmap procurement criteria. |
| Scotland and Northern England Market Development | Replicates South East adoption patterns in underpenetrated specialist diabetes centre geographies. |
Research Methodology
Multi-period observation of NHS Technology Appraisal Programme reimbursement decisions, MHRA approval timelines, and pharmacy dispensing volumes anchored the trend analysis, supplemented by interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Secondary validation drew from NHS prescription databases, BSI Group conformity assessment registers, hospital procurement tender records, and MHRA software-as-medical-device guidance documents. Bottom-up sensor shipment estimates and top-down NHS expenditure allocations were triangulated to cross-verify market sizing.
Segment-weighting across product type, end user, technology, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves applied to each segment's historical trajectory and forward-looking reimbursement policy assumptions. Continuous glucose monitor adoption curves incorporated specialist diabetes centre density and patient digital health literacy indices as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NHS funding allocation shocks or MHRA cybersecurity requirement escalations. Forecasts reflect assumptions about Technology Appraisal Programme reimbursement expansion continuity and UKCA marking transition completion pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Germany Continuous Glucose Monitoring Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Japan Insulin Infusion Pump Market