
 Worldwide EV Range Extender Market | 2026-2036
Worldwide EV Range Extender Market Size, Share, and Industry Trends Forecast 2026-2036
Worldwide EV Range Extender Market Insights
Silicon carbide power electronics is recalibrating range extender system economics by slashing inverter losses and enabling higher thermal operating ceilings. MAHLE GmbH leverages its thermal management portfolio to integrate compact auxiliary power units into modular vehicle platforms. Rheinmetall AG anchors its position through precision-engineered engine components optimized for intermittent duty cycles in series-hybrid architectures. Schaeffler specializes in bearing and mechatronic systems that reduce friction losses in high-speed generator assemblies.
A range extender is an auxiliary energy conversion device that supplements a battery-electric vehicle's traction battery, typically comprising a small internal combustion engine or fuel cell paired with a generator to produce electricity on demand. Systems rated between 15 kW and 40 kW dominate passenger car applications, enabling 300-600 km additional range without increasing battery mass proportionally. Internal combustion engine technology still occupies the largest installed base due to manufacturing maturity and fuel infrastructure ubiquity, though fuel cell variants represent the fastest-expanding segment as hydrogen distribution networks mature in clustered corridors. Commercial vehicles generate concentrated margin pools because fleet operators prioritize total cost of ownership over upfront capital expenditure, creating durable aftermarket service revenue for auxiliary power unit maintenance and overhaul.
The EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates in the United States, combined with the EU Green Deal's 2035 new combustion vehicle phase-out, are redirecting OEM engineering resources toward certified low-emission range extender architectures that qualify for transitional compliance pathways. China's MIIT new energy vehicle regulations enforce minimum electric range thresholds that incentivize lightweight range extender integration in plug-in hybrid designs. Stakeholders must monitor how evolving multi-country certification requirements for auxiliary power unit emissions and noise standards reshape product development roadmaps and supplier qualification timelines.
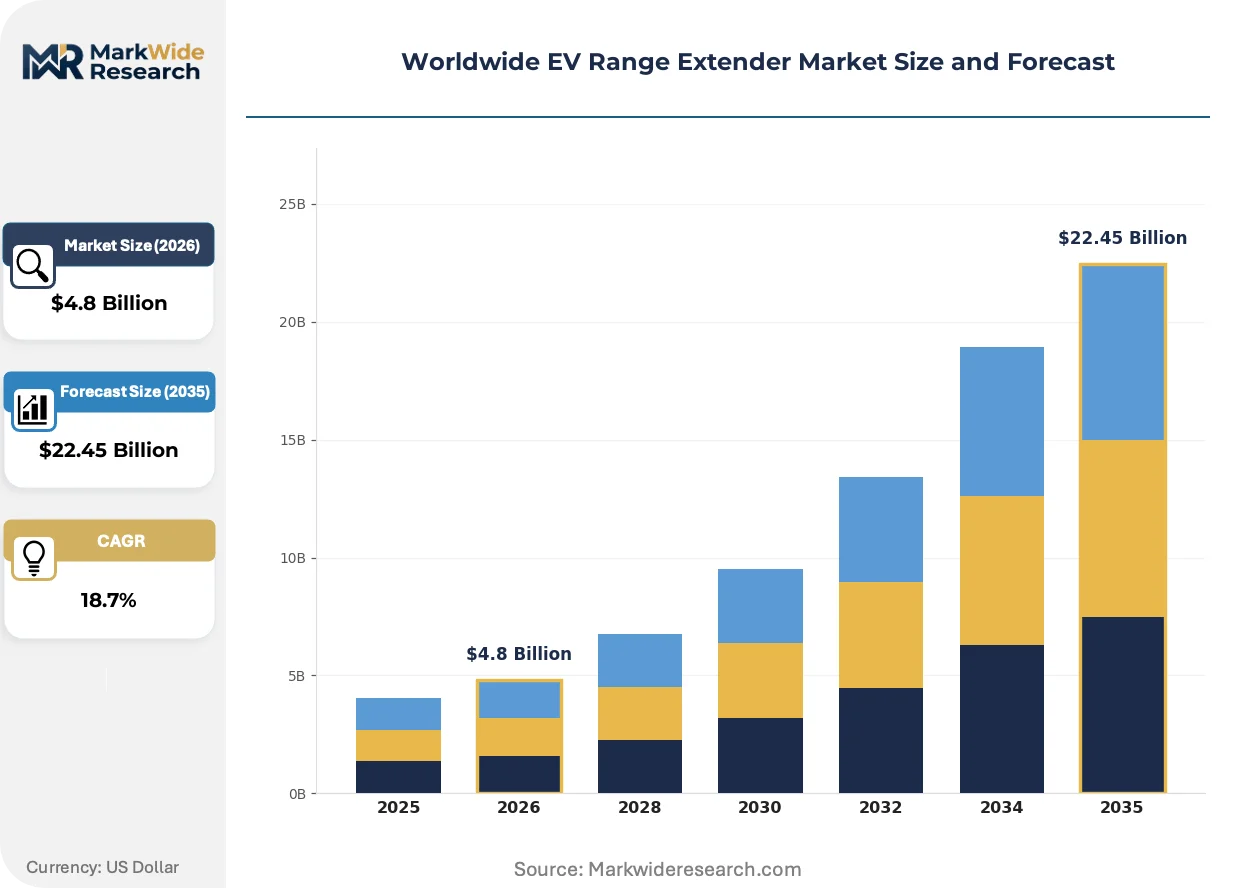
Market Dynamics
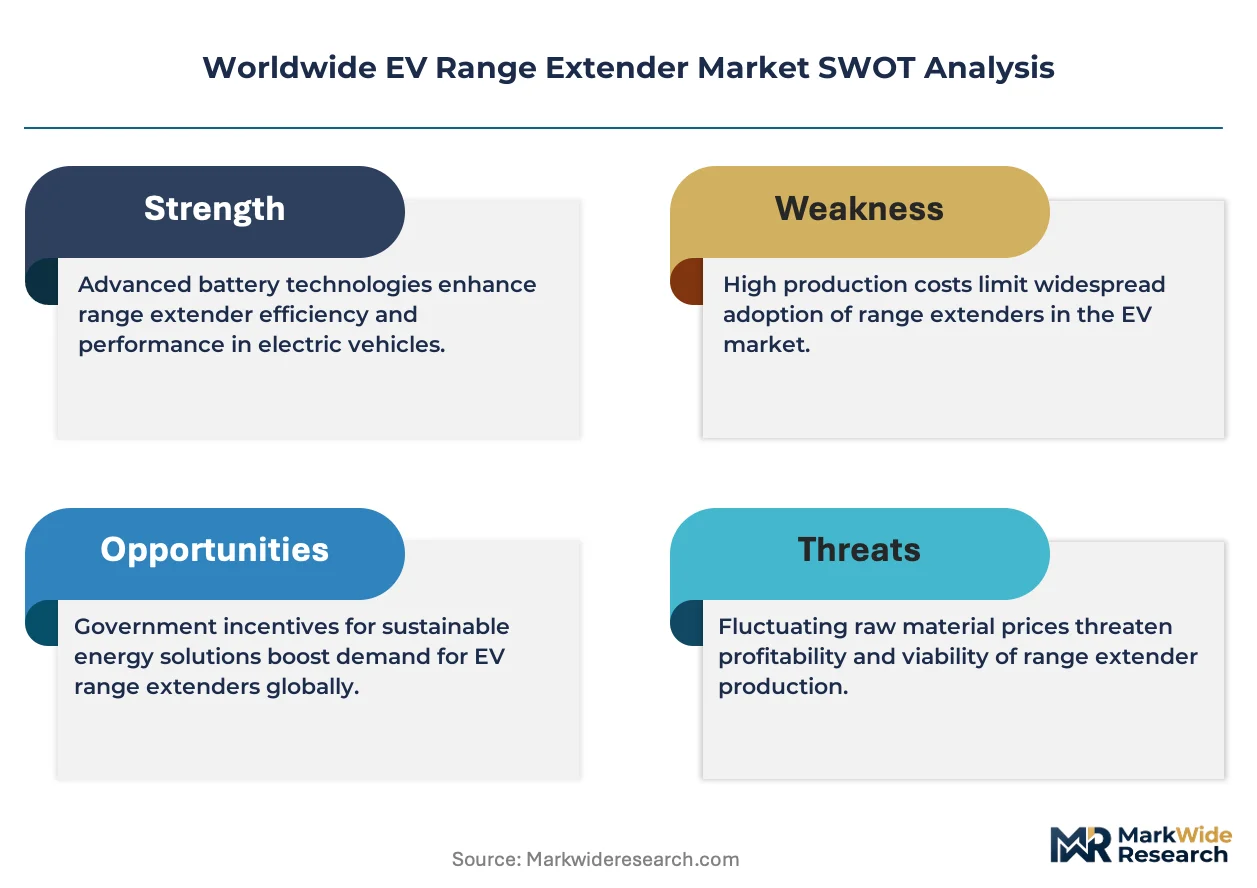
Silicon carbide power electronics is compressing thermal management costs while raising operating ceilings, forcing incumbent suppliers to requalify generator architectures around higher switching frequencies and reduced inverter mass.
Growth Catalysts
- China's MIIT NEV credit mandate:Minimum electric range thresholds push OEMs toward lightweight range extender integration in plug-in hybrid platforms, sustaining engineering investment in compact auxiliary power units.
- Fleet operator TCO prioritization:Commercial vehicle buyers across Germany's industrial corridor favor total cost of ownership calculations over upfront capital expenditure, generating durable aftermarket revenue streams for auxiliary power unit maintenance.
- Hydrogen corridor maturation:Clustered hydrogen distribution networks in the EU and China accelerate fuel cell range extender adoption, displacing pure battery-electric configurations in heavy-duty route applications.
Market Restraints
- Neodymium-dysprosium supply concentration:Rare earth magnet dependence for high-speed generator rotors concentrates sourcing risk in China's refining and processing infrastructure.
- EU F-Gas Regulation phase-down:Refrigerant restrictions complicate thermal loop design for range extender cooling circuits, extending validation timelines for new vehicle platforms.
- Direct-injection ICE efficiency gains:Improved conventional powertrain economics narrow the operating cost gap for fleet operators in markets with weak carbon pricing.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced automotive technology attract range extender system assembly to offset battery import dependence in commercial vehicle segments.
- Modular skateboard platforms:Standardized vehicle architectures enable plug-and-play auxiliary power unit integration across multiple OEM programs, amortizing development costs.
- EU Green Deal transitional compliance:Certified low-emission range extender architectures qualify for 2035 phase-out exemptions, preserving engineering relevance through the compliance window.
Industry Challenges
- Multi-country certification synchronization:Divergent EPA, CARB, and EU type-approval timelines for auxiliary power unit emissions and noise standards fragment product development roadmaps.
- High-speed bearing tribology expertise:Generator assemblies operating above 15,000 rpm require specialized lubrication and sealing knowledge concentrated in German and Japanese supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Worldwide EV Range Extender Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Internal Combustion Engine, Fuel Cell, Battery, Hybrid Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Buses Application: Urban Use, Highway Navigation, Emergency Backup, Racing End User: Fleet Operators, Individual Consumers, OEMs, Aftermarket Providers |
| Companies Covered | MAHLE GmbH, Rheinmetall AG, AVL List GmbH, Ballard Power Systems Inc, Ceres Power Holdings plc, Magna International Inc, Plug Power Inc, Horse Powertrain, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Worldwide EV Range Extender Market Trends and Innovations
Power semiconductor evolution and regulatory compliance pathway engineering are converging to redefine range extender system architecture, compressing development cycles while expanding addressable vehicle segments.
Silicon carbide MOSFETs enable inverter switching frequencies above 50 kHz, slashing filter magnetics mass and thermal rejection requirements. Tier 1 suppliers are adopting these devices for 30-40 kW generator inverters in series-hybrid commercial vehicles. This unifying technology platform collapses the distinction between passenger car and heavy-duty auxiliary power unit designs, permitting component reuse across vehicle classes.
The EU Green Deal's 2035 new combustion vehicle phase-out creates a transitional compliance category for certified low-emission range extenders. OEMs are redirecting engineering resources toward architectures that qualify for this pathway while maintaining ZEV credit accumulation. Germany's KBA and France's type-approval authorities are processing the first wave of range-extended electric vehicle certifications under tightened CO2 fleet standards.
Fleet procurement committees now require 10-year total cost of ownership models incorporating residual value risk and energy price volatility. This analytical discipline favors range-extended electric trucks over pure battery-electric alternatives in variable-route logistics operations. The shift is most pronounced in North American and European long-haul segments where charging infrastructure gaps persist on interstate corridors.
Worldwide EV Range Extender Market Segmentation
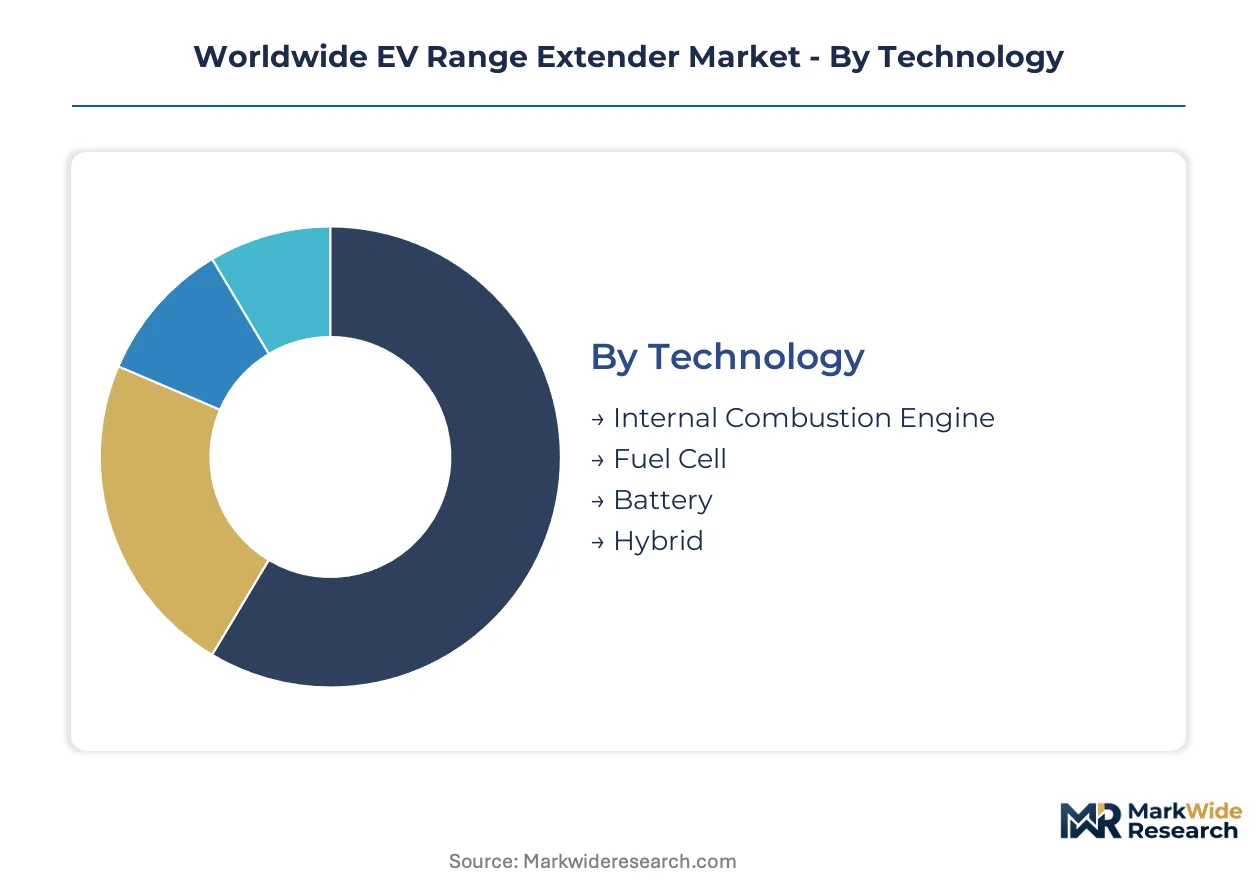
Range extender procurement patterns diverge sharply across duty cycles, powertrain architectures, and buyer sophistication. Segment boundaries are blurring as silicon carbide inverters enable modular designs that span passenger cars through heavy-duty commercial platforms.
Technology:
Cost tier separates incumbent manufacturing scale from emerging efficiency gains.
- Internal Combustion Engine:Small-displacement engines paired with high-speed generators dominate current installations. Fleet operators in Germany's industrial corridor specify these systems for their established service networks and fuel infrastructure access.
- Fuel Cell:Proton-exchange membrane stacks deliver zero-emission electricity generation for heavy-duty routes. Hydrogen corridor maturation in the Netherlands and China's Yangtze River Delta accelerates pilot deployments in long-haul trucking.
- Battery:Supplementary battery packs extend range through energy density improvements rather than combustion. NEV credit calculations in China favor this approach for urban delivery vehicles with predictable duty cycles.
- Hybrid:Combined thermal-electric architectures optimize load-following performance. Japanese OEMs lead integration of compact turbine generators for premium passenger applications.
Volume sits with Internal Combustion Engine; growth tilts toward Fuel Cell.
Vehicle Type:
Application intensity and route predictability reshape buyer specifications across weight classes.
- Passenger Cars:Compact 15-30 kW units address range anxiety in markets with sparse fast-charging coverage. Individual consumers in France and Italy prioritize seamless electric driving with occasional combustion backup.
- Commercial Vehicles:30-50 kW auxiliary power units sustain refrigerated transport and variable-route logistics. Fleet procurement committees in the United States mandate 10-year total cost of ownership models that favor range-extended configurations over pure battery-electric alternatives.
- Motorcycles:Ultra-compact 5-10 kW generators extend urban commuter range without chassis redesign. Southeast Asian manufacturers integrate these units to meet tightening emission standards while preserving two-wheeler affordability.
- Buses:High-capacity fuel cell range extenders serve intercity routes beyond charging infrastructure reach. Municipal operators in South Korea specify these for mountain corridor services.
Commercial Vehicles command the dominant revenue share; Passenger Cars are climbing the fastest as mass-market OEMs standardize range-extended platforms.
Application:
Route predictability and duty cycle severity determine power output and thermal management specifications.
- Urban Use:Frequent stop-start operation demands rapid generator response and minimal noise emission. London's Ultra Low Emission Zone and Milan's Area B restrictions compel delivery fleets toward certified low-emission auxiliary power units.
- Highway Navigation:Sustained high-speed operation prioritizes thermal efficiency and aerodynamic integration. German autobahn corridor operators specify fuel cell range extenders for 600+ km uninterrupted range.
- Emergency Backup:Standby power systems for critical infrastructure vehicles require instant-start reliability. Japanese disaster response agencies procure these for mobile command centers.
- Racing:Lightweight turbine generators deliver burst power for endurance competition without battery mass penalties. FIA-sanctioned series in Belgium and Italy pilot these for hybrid prototype classes.
Urban Use absorbs the highest unit volume; Highway Navigation shows the steepest expansion trajectory as charging gaps persist on transcontinental corridors.
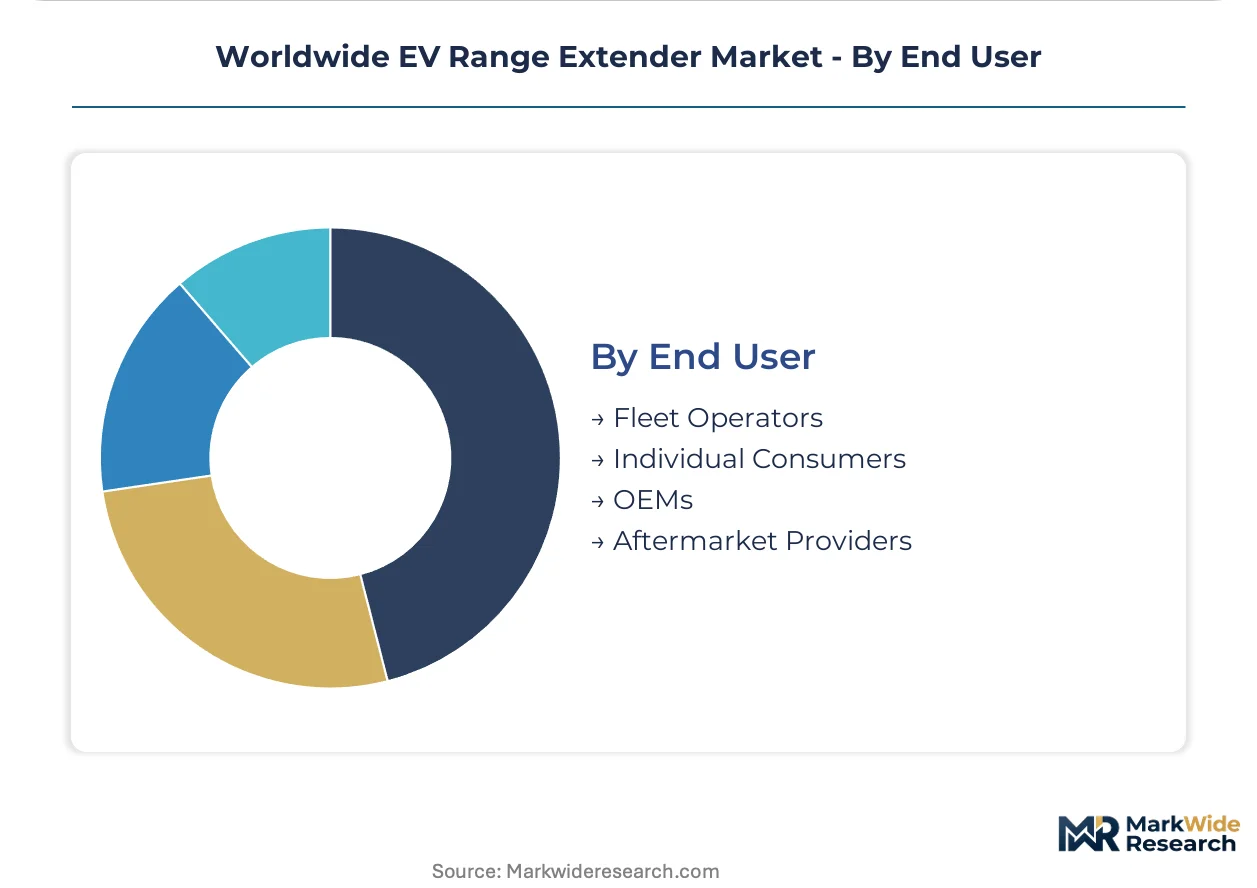
End User:
Procurement sophistication and lifecycle cost modeling capabilities separate institutional buyers from retail demand.
- Fleet Operators:Centralized purchasing with total cost of ownership analytics favors range-extended electric trucks. North American logistics companies specify auxiliary power units to eliminate route downtime on interstate corridors.
- Individual Consumers:Range anxiety mitigation drives adoption in markets with nascent charging infrastructure. Italian and Spanish buyers prioritize plug-in hybrid architectures with integrated range extenders over pure battery-electric vehicles.
- OEMs:Platform engineering teams integrate modular auxiliary power units across multiple vehicle programs. Volkswagen Group and Stellantis amortize development costs through standardized skateboard architectures.
- Aftermarket Providers:Retrofit specialists serve existing electric vehicle fleets seeking range extension without platform replacement. Australian mining operators commission these conversions for remote site access vehicles.
Fleet Operators dominate current procurement; OEMs are gaining share fastest as factory-integrated designs displace retrofit alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate battery-grade silicon carbide wafer production, drawing range extender inverter suppliers to co-locate with power semiconductor foundries.
China
MIIT's NEV credit mandate enforces minimum electric range thresholds that OEMs satisfy through lightweight range extender integration in plug-in hybrid platforms. Yangtze River Delta engineering clusters in Shanghai and Suzhou prototype compact auxiliary power units with 15-40 kW output ratings for domestic manufacturers.
Germany
Fleet operators along the industrial corridor prioritize total cost of ownership calculations favoring range-extended electric trucks over pure battery alternatives. KBA processes certifications under tightened EU CO2 fleet standards for low-emission auxiliary power units qualifying for 2035 phase-out exemptions.
United States
North American logistics companies specify auxiliary power units to eliminate route downtime on interstate corridors with persistent charging infrastructure gaps. EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates redirect OEM engineering toward certified transitional compliance architectures.
Japan
METI supports hydrogen corridor development accelerating fuel cell range extender pilot deployments in heavy-duty long-haul applications. Kanto region engineering teams integrate compact turbine generators for premium passenger vehicle platforms targeting 600 km extended range.
South Korea
Municipal operators specify high-capacity fuel cell range extenders for intercity bus routes beyond charging infrastructure reach. Busan-Ulsan manufacturing clusters produce proton-exchange membrane stacks for zero-emission electricity generation in mountain corridor services.
Worldwide EV Range Extender Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with component suppliers dominating generator and thermal management subsystems while full-system integrators capture vehicle platform contracts. The supplier base concentrates around German precision engineering clusters and Chinese manufacturing scale, creating tiered access to high-speed bearing tribology and silicon carbide packaging expertise. Three archetypes define competitive positioning: thermal management specialists leveraging HVAC portfolios, precision component manufacturers with intermittent-duty engine expertise, and fuel cell stack suppliers anchoring hydrogen corridor deployments. Dominant competitive moves include strategic partnerships for modular skateboard platform integration and geographic expansion through India's PLI scheme for automotive technology assembly.
Within the thermal and precision component tier, MAHLE GmbH and Rheinmetall AG exemplify German engineering-centric positioning, while Schaeffler occupies a bearing and mechatronic specialization niche. These GmbH and AG structures represent established continental European industrial archetypes with deep integration into automotive supply chains. Ballard Power Systems Inc and Plug Power Inc anchor North American fuel cell range extender development, their Inc. suffixes signaling public-market capitalization profiles distinct from the privately held German competitors. Ceres Power Holdings plc represents UK-listed fuel cell technology positioning within the hydrogen transition segment.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Rheinmetall AG |
| AVL List GmbH |
| Ballard Power Systems Inc |
| Ceres Power Holdings plc |
| Magna International Inc |
| Plug Power Inc |
| Horse Powertrain |
| Schaeffler |
| Others |
Pricing and Supply Chain Analysis
Family-owned German precision engineering clusters anchor the supplier base, translating multi-generational technical debt into pricing discipline that resists commoditization pressure from Chinese manufacturing scale. Their ownership structure insulates long-term R&D cycles from quarterly margin compression, sustaining premium positioning for high-speed bearing and thermal management subsystems.
Pricing Analysis
Lead-time-driven pricing stratification separates premium tiers for certified low-emission architectures qualifying for EU Green Deal transitional compliance from economy tiers for retrofit aftermarket conversions. OEM-integrated auxiliary power units command standard-tier positioning through volume scale, while spot procurement for fleet emergency replacements triggers surcharge premiums. Cost compression in silicon carbide inverter sourcing is intensifying because Yangtze River Delta foundry expansion is flooding the merchant wafer market. Fleet operators exhibit the sharpest price sensitivity, prioritizing ten-year total cost of ownership models that amortize upfront capital expenditure across residual value risk.
Supply Chain Analysis
Freight cost volatility from Red Sea corridor disruptions is rerouting silicon carbide wafer shipments around the Cape of Good Hope, extending inventory cycles for European inverter assemblers. Geographic concentration centers on China for rare earth magnet processing, Germany for precision bearing tribology, and Japan for high-speed generator rotor laminations. Raw material dependencies include neodymium-dysprosium magnet alloys, silicon carbide substrates, and aluminum-silicon thermal interface materials. Single-source vulnerability in Chinese rare earth refining infrastructure poses structural risk. Distribution runs through Tier 1 system integrators holding platform engineering contracts with multinational OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around silicon carbide packaging expertise and high-speed bearing tribology knowledge, with MIIT NEV credit threshold tightening and EU F-Gas refrigerant phase-downs forcing capital-constrained component suppliers toward exit or acquisition.
For Market Incumbents: Deploy backward integration into silicon carbide wafer supply to secure inverter cost positioning against Chinese merchant foundry pricing. MAHLE GmbH and Rheinmetall AG should anchor generator architectures around 50 kHz switching frequencies to qualify for EU transitional compliance certification, insulating against pure battery-electric platform displacement. Certification investment in KBA and CARB dual-approval pathways creates switching costs for fleet operator procurement committees. For New Entrants and Emerging Players: Silicon carbide MOSFET packaging expertise offers entry into 30-40 kW commercial vehicle inverter supply, where incumbent requalification timelines create temporary white space. India's PLI scheme for automotive technology assembly presents the most penetrable geography, offsetting battery import dependence for domestic commercial vehicle manufacturers. A technology-licensing go-to-market angle to Tier 1 thermal management specialists accelerates qualification without captive manufacturing investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor fuel cell stack specialists with proton-exchange membrane IP in South Korean and Dutch hydrogen corridor deployments, where METI and EU Green Deal funding is sustaining pilot-scale revenue. Long-term viability hinges on auxiliary power unit relevance through the 2035 combustion phase-out compliance window. Watch for KBA certification queue acceleration as an inflection indicator for German fleet operator procurement conversion from pilot to volume deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | 50 kHz switching frequencies slash filter magnetics mass for series-hybrid commercial vehicles. |
| Modular Skateboard Platform Standardization | Volkswagen Group and Stellantis amortize auxiliary power unit development across multiple vehicle programs. |
| Hydrogen Corridor Infrastructure Partnership | Netherlands and Yangtze River Delta clustered distribution accelerates fuel cell range extender pilot deployments. |
| Dual-Certification Investment Pathway | Simultaneous KBA and CARB approval reduces fleet operator procurement friction in transatlantic logistics segments. |
| Rare Earth Magnet Recycling Capability | In-house neodymium-dysprosium recovery mitigates Chinese refining concentration risk for generator rotor supply. |
Research Methodology
Trade association technical filings, MIIT NEV credit compliance disclosures, and EU type-approval authority certification registers formed the secondary backbone for market sizing and regulatory trajectory mapping. Primary interviews with OEM platform engineering directors, Tier 1 thermal management procurement leads, and fleet operator total cost of ownership analysts validated technology adoption timelines and pricing elasticity assumptions. Bottom-up and top-down triangulation cross-checked auxiliary power unit shipment data against vehicle registration databases and hydrogen corridor infrastructure deployment records.
Bottom-up modeling aggregated segment-level unit economics across passenger car, commercial vehicle, and bus applications, while top-down analysis calibrated aggregate market value against automotive powertrain engineering expenditure disclosures. Segmentation dimensions span technology architecture, vehicle weight class, duty cycle intensity, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and fleet procurement committee conversion patterns. Forecast inputs incorporated silicon carbide inverter cost curves and hydrogen distribution network buildout schedules.
Several conditions sit outside the modeled scope, including potential EPA tailpipe standard stringency revisions, breakthrough solid-state battery commercialization timelines, and geopolitical trade restriction escalations affecting rare earth magnet supply. Forecasts reflect assumptions about OEM engineering resource allocation between pure electric and range-extended platform development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market