
 Global Solar Powered Car Market | 2026-2036
Global Solar Powered Car Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Powered Car Market Outlook
Chinese photovoltaic module producers is restructuring supply chains for automotive-grade cell efficiency, redirecting capacity toward vehicle-integrated applications. Sono Motors GmbH leverages polymer-based solar body panel manufacturing to sustain cost curves below traditional silicon rooftop arrays. Lightyear Technologies B.V. anchors its position through in-wheel motor architecture paired with curved solar roof surfaces. Aptera Motors Corp. differentiates via ultra-lightweight composite chassis design that reduces energy draw per kilometer traveled.
A solar powered car integrates photovoltaic cells into body surfaces to generate electricity for propulsion or supplementary battery charging, typically achieving conversion efficiencies between twenty and twenty-six percent for monocrystalline automotive-grade panels. These vehicles serve commercial and consumer mobility segments seeking grid-independent operation or extended electric range without charging infrastructure dependency. Pure Electric Vehicles command the primary revenue pool where battery capacity and solar yield achieve operational parity with conventional charging cycles. Energy Storage Solutions represent the fastest-expanding technology segment as solid-state and lithium-metal chemistries reduce mass penalties. Fleet Operators constitute the most concentrated end-user category due to predictable duty cycles and centralized maintenance economics that amortize solar hardware premiums across high-utilization schedules.
The US NHTSA and EPA coordinate crashworthiness and emissions classification standards that determine solar vehicle road certification and zero-emission credit eligibility. EMA REACH compliance and EU Green Deal automotive CO2 benchmarks shape material selection and end-of-life recycling obligations for European manufacturers. China's MIIT issues new energy vehicle catalog listings that qualify solar-assisted models for license plate privileges and purchase subsidies. Stakeholders must monitor evolving battery-solar integration safety protocols and subsidy phase-out calendars to time capacity commitments and geographic market entries.
Market Dynamics
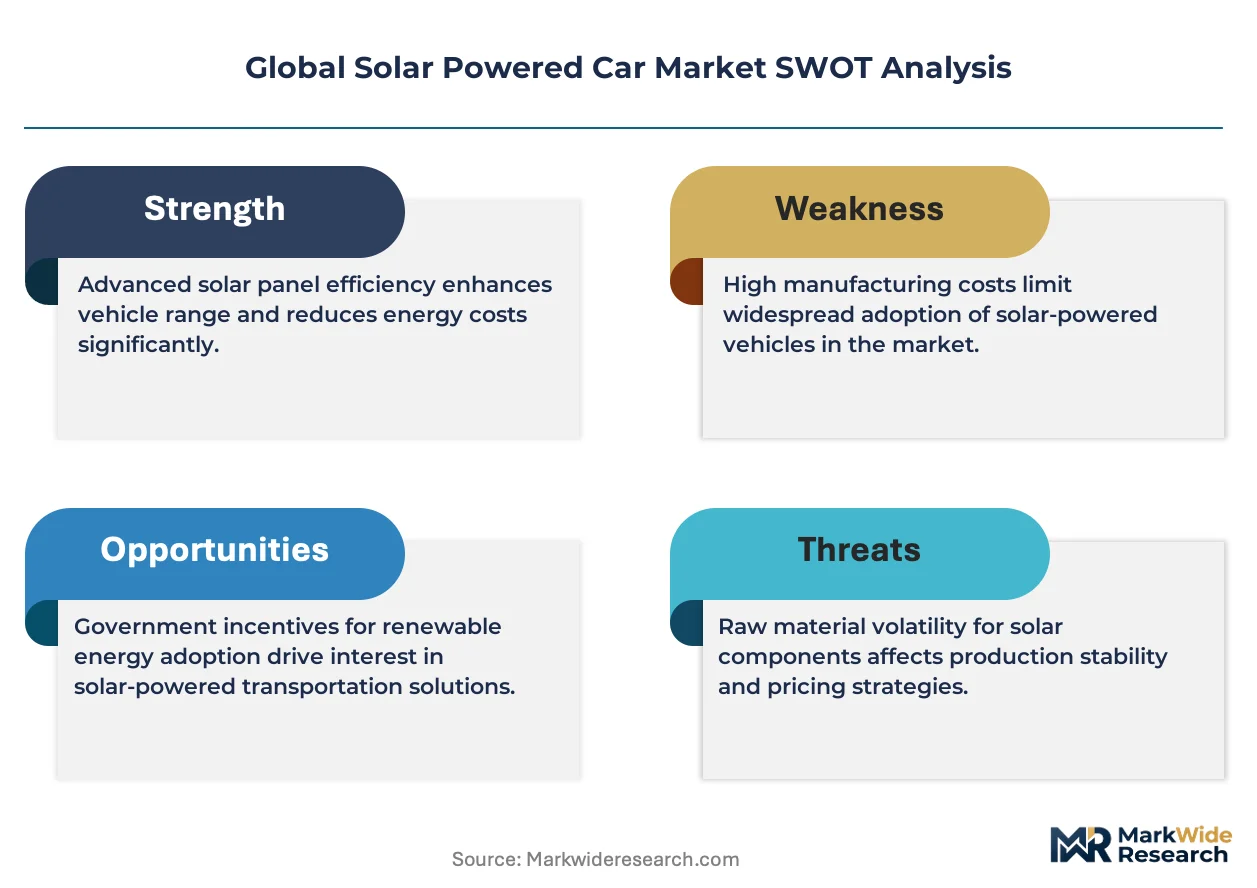
Thin-film photovoltaic integration is compressing weight-to-range ratios while solid-state battery chemistry advances simultaneously reduce mass penalties, creating a structural inflection point where solar yield achieves operational parity with conventional charging cycles.
Growth Catalysts
- EU Green Deal automotive CO2 benchmarks:Manufacturers redesign vehicle architectures to qualify for zero-emission credit eligibility and end-of-life recycling obligations.
- Fleet operator procurement:Centralized maintenance economics amortize solar hardware premiums across high-utilization schedules with predictable duty cycles.
- Automotive-grade monocrystalline efficiency gains:Conversion improvements between twenty and twenty-six percent narrow the performance gap with grid-charged alternatives.
Market Restraints
- Silicon input cost volatility:Polysilicon price swings compress margins for integrated solar body panel manufacturers dependent on semiconductor-grade feedstock.
- Chinese photovoltaic supply concentration:Automotive-grade cell capacity restructuring creates single-source dependency risks for vehicle-integrated applications.
- NHTSA crashworthiness certification friction:Solar roof surface integration triggers extended timeline uncertainty for street-legal fleet trial approvals.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Domestic manufacturing incentives attract solar-battery integration investments for license plate privilege eligibility.
- Curved solar surface architecture:In-wheel motor pairings enable aerodynamic optimization previously incompatible with flat rooftop arrays.
- Composite chassis ultra-lightweighting:Energy draw per kilometer reductions expand addressable range for grid-independent commercial mobility.
Industry Challenges
- Battery-solar integration safety protocol gaps:Evolving thermal runaway standards delay product certification timelines for solid-state chemistry deployments.
- Polymer-based manufacturing skill scarcity:Specialized workforce shortages constrain scale-up of solar body panel production below traditional silicon cost curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Powered Car Market |
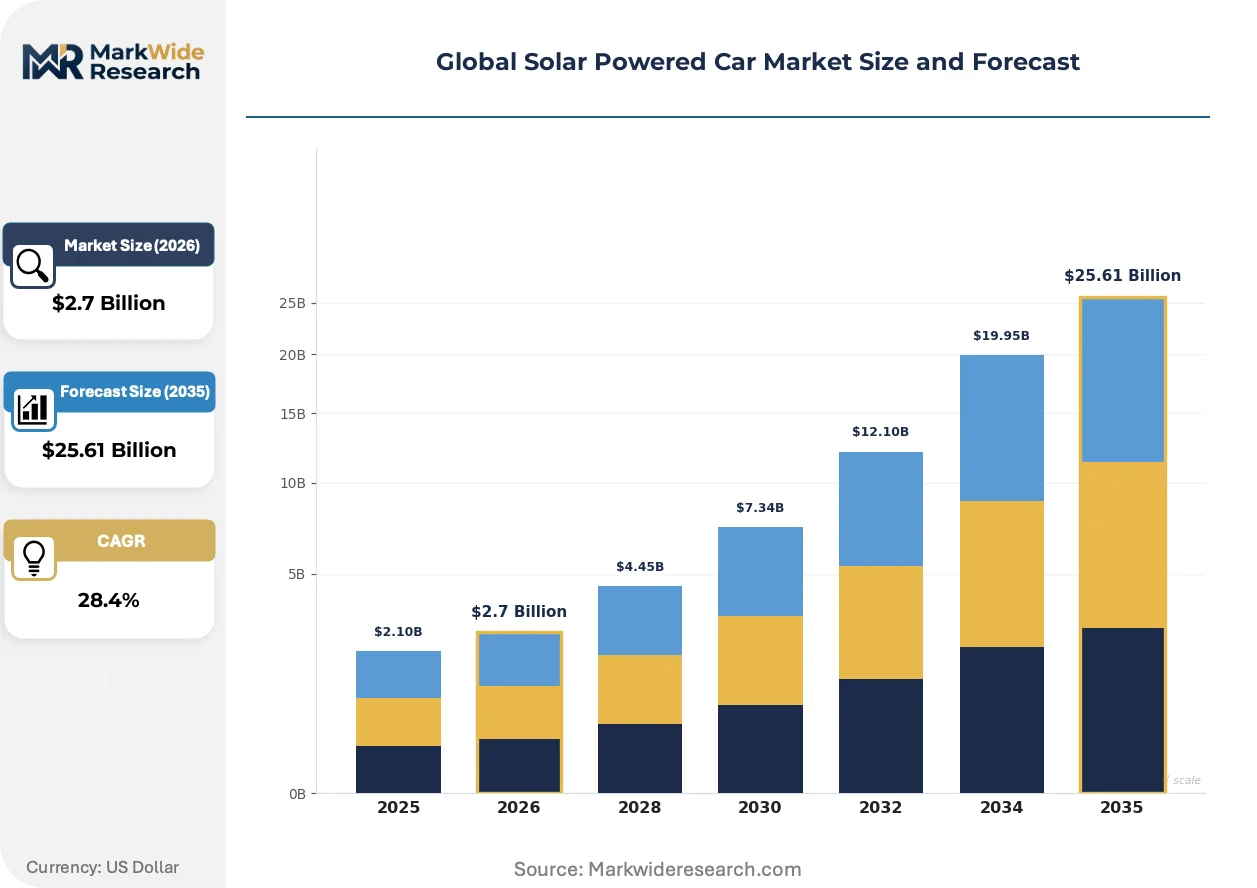
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $25.61 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Vehicles, Pure Electric Vehicles, Plug-in Hybrids, Lightweight Models Technology: Solar Charging Systems, Energy Storage Solutions, Solar Photovoltaic Panels, Smart Grids End User: Individual Users, Fleet Operators, Government Agencies, Ride-Sharing Services Sales Channel: Direct Sales, Online Retail, Dealerships, Automotive Expos |
| Companies Covered | Sono Motors GmbH, Lightyear Technologies B.V., Aptera Motors Corp., Toyota Motor Corporation, Ford Motor Company, Volkswagen AG, Mahindra & Mahindra Limited, General Motors, Hanergy Thin Film Power Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Powered Car Market Strategic Shifts
Vehicle-integrated photovoltaics is modularizing across multiple surface applications simultaneously, dissolving the boundary between energy generation and structural design in automotive engineering.
Perovskite tandem cell architectures is modularizing the solar surface from a single rooftop plane into distributed body-integrated arrays. Fleet operators in Germany pilot door and hood installations that capture oblique-angle irradiation throughout operating hours. This distributed approach is modularizing the energy yield model from peak-sun-hour dependence toward cumulative daily generation accounting.
REACH compliance and ECHA substance restrictions are forcing material substitutions in encapsulant chemistries for curved solar surfaces. Manufacturers reformulate polymer backsheet compositions to maintain optical transmission while eliminating restricted phthalate plasticizers. German KBA type-approval processes now incorporate accelerated UV degradation testing that favors fluoropolymer alternatives.
Long-term lease structures are displacing outright purchase for solar-assisted commercial fleets. Logistics operators in the Netherlands bundle vehicle, maintenance, and energy yield guarantees into single contracts with residual value risk transferred to lessors. This financial packaging concentrates in urban delivery segments where route predictability enables accurate solar contribution modeling.
Global Solar Powered Car Market Segmentation
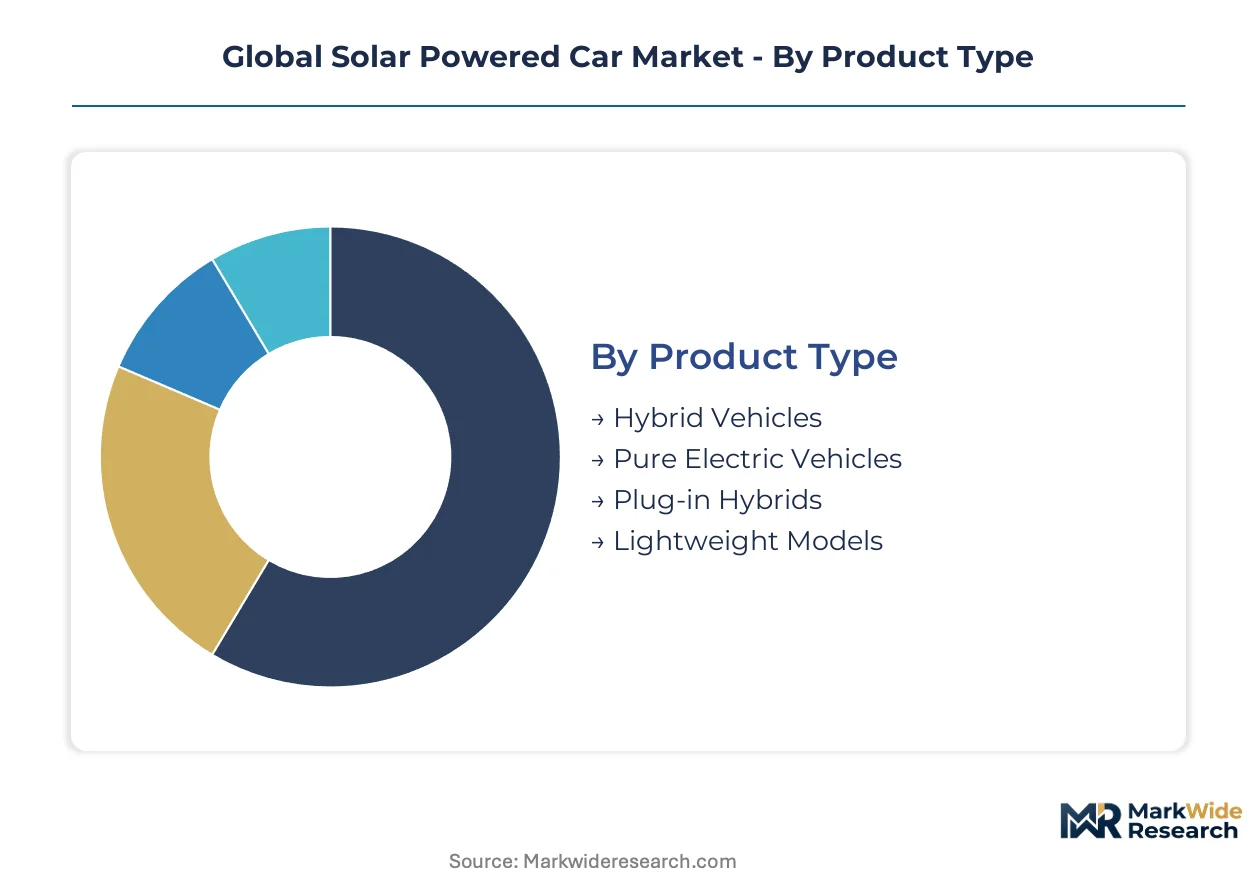
Segmentation reveals how solar vehicle architectures align with distinct operational economics and infrastructure dependencies. Product configuration, energy system design, and procurement channel each determine addressable use cases and total cost of ownership calculations.
Product Type:
Upgrade cycles in fleet procurement favor architectures that minimize charging infrastructure dependency while maximizing daily solar yield per surface area.
- Pure Electric Vehicles:Battery-dominant architectures with integrated photovoltaic body panels achieve operational parity with conventional charging cycles in high-irradiance geographies. Fleet operators in Australia and the southwestern United States concentrate procurement here due to predictable duty cycles and centralized maintenance economics.
- Hybrid Vehicles:Dual-powertrain configurations pair small-displacement combustion engines with solar-assisted electric ranges, bridging infrastructure gaps in emerging markets. Demand clusters in India and Brazil where grid reliability varies across operating territories.
- Plug-in Hybrids:Larger battery packs than conventional hybrids enable meaningful solar contribution to daily commuting ranges without range anxiety penalties.
- Lightweight Models:Ultra-light composite chassis designs reduce energy draw per kilometer traveled, expanding addressable range for grid-independent commercial mobility.
Pure Electric Vehicles sits at the top of the volume ranking, with Lightweight Models climbing the fastest.
Technology:
Cost tier differentiation separates premium solid-state deployments from incumbent lithium-ion architectures across fleet procurement decisions.
- Energy Storage Solutions:Solid-state and lithium-metal chemistries reduce mass penalties while improving thermal stability for vehicle-integrated applications. German KBA type-approval processes now incorporate accelerated degradation testing that favors fluoropolymer alternatives in encapsulant formulations.
- Solar Photovoltaic Panels:Monocrystalline automotive-grade panels achieve conversion efficiencies between twenty and twenty-six percent, narrowing performance gaps with grid-charged alternatives. Chinese module producers are restructuring supply chains for automotive-grade cell efficiency.
- Solar Charging Systems:Power electronics manage DC-DC conversion between panel output and battery input, optimizing yield across varying irradiance conditions.
- Smart Grids:Vehicle-to-grid integration enables bidirectional energy flows, monetizing solar generation beyond propulsion requirements.
Energy Storage Solutions holds the steepest expansion trajectory as solid-state chemistry deployments accelerate, while Solar Photovoltaic Panels maintains installed base dominance.
End User:
Customer type determines utilization intensity and thus the amortization calculus for solar hardware premiums.
- Fleet Operators:High-utilization schedules with predictable duty cycles amortize solar hardware premiums across centralized maintenance economics. Logistics operators in the Netherlands bundle vehicles, maintenance, and energy yield guarantees into single contracts with residual value risk transferred to lessors.
- Government Agencies:Public procurement programs prioritize zero-emission credit eligibility and license plate privileges under China's MIIT catalog listings and EU Green Deal benchmarks.
- Individual Users:Consumer adoption depends on charging infrastructure independence and extended electric range without grid dependency.
- Ride-Sharing Services:Urban delivery segments with route predictability enable accurate solar contribution modeling for fleet financing structures.
Fleet Operators commands revenue concentration, with Government Agencies gaining share fastest through regulatory procurement mandates.
Sales Channel:
Supply concentration in direct manufacturer relationships contrasts with fragmented dealership networks across emerging markets.
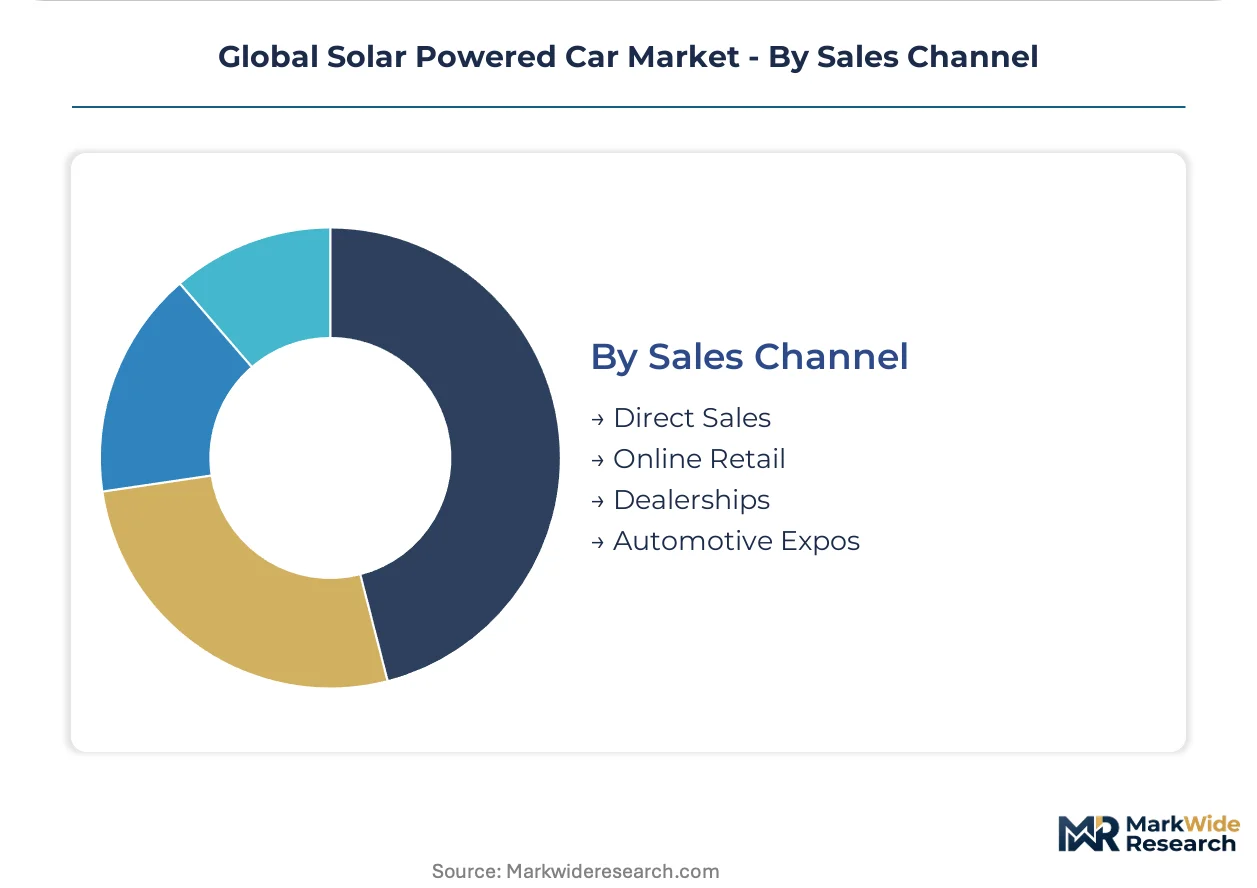
- Direct Sales:Manufacturer-controlled channels capture long-term lease structures displacing outright purchase, bundling maintenance and energy yield guarantees. This financial packaging concentrates residual value risk with lessors.
- Dealerships:Traditional automotive retail networks require education investments for solar-specific value propositions and total cost of ownership calculations.
- Online Retail:Digital channels reduce customer acquisition costs for pre-configured vehicle specifications with standardized solar panel integrations.
- Automotive Expos:Exhibition platforms demonstrate curved solar surface architectures and in-wheel motor pairings to fleet procurement decision-makers.
Direct Sales leads channel volume, with Online Retail expanding most quickly as digital-native fleet operators streamline procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates solar vehicle development through Sono Motors and Lightyear Technologies, while the United States scales fleet trials through Aptera Motors and emerging commercial operators seeking charging infrastructure independence.
Germany
Fleet operators in Munich and Stuttgart expand procurement of solar-assisted commercial vehicles as total cost of ownership advantages crystallize. The KBA type-approval process incorporates accelerated UV degradation testing that favors fluoropolymer alternatives in encapsulant formulations. The Stuttgart industrial cluster anchors active development programs and regulatory sandbox approvals for street-legal solar fleet trials.
United States
Southwestern fleet operators concentrate procurement where predictable duty cycles and high irradiance maximize solar yield amortization. The NHTSA coordinates crashworthiness certification standards that determine solar vehicle road approval timelines. California's technology corridor hosts ultra-lightweight composite chassis developers reducing energy draw per kilometer traveled.
China
Photovoltaic module producers restructure supply chains for automotive-grade cell efficiency, redirecting capacity toward vehicle-integrated applications. The MIIT issues new energy vehicle catalog listings that qualify solar-assisted models for license plate privileges and purchase subsidies. The Yangtze River Delta manufacturing belt concentrates thin-film integration capacity serving domestic and export markets.
Netherlands
Logistics operators bundle vehicles, maintenance, and energy yield guarantees into single long-term lease contracts. EU Green Deal automotive CO2 benchmarks shape material selection and end-of-life recycling obligations for manufacturers. The Randstad urban delivery corridor pilots distributed solar surface installations capturing oblique-angle irradiation throughout operating hours.
India
Dual-powertrain configurations bridge infrastructure gaps where grid reliability varies across operating territories. The PLI scheme for advanced chemistry cells attracts solar-battery integration investments for license plate privilege eligibility. The Maharashtra-Gujarat industrial corridor concentrates lightweight model development targeting grid-independent commercial mobility.
Global Solar Powered Car Market Competitive Environment
German producers anchor one tier through polymer-based solar body panel manufacturing; United States specialists hold ultra-lightweight composite chassis positions. The vendor base splits between integrated photovoltaic-vehicle manufacturers and traditional automakers adding solar-assisted variants. Three archetypes dominate: dedicated solar-first developers, legacy OEMs with solar option programs, and thin-film technology suppliers. Capacity expansion and strategic partnerships constitute the primary competitive vectors as players secure automotive-grade cell supply and certification expertise.
Within the dedicated solar-first tier, Sono Motors GmbH exemplifies polymer-based manufacturing approaches, while Lightyear Technologies B.V. occupies a position emphasizing aerodynamic optimization architectures. Aptera Motors Corp. represents the ultra-lightweight composite chassis specialization. These three entities anchor distinct technical vectors—body-integrated photovoltaics, curved surface aerodynamics, and mass reduction engineering—that collectively define the competitive frontier for grid-independent vehicle development.
| Leading Market Players |
|---|
| Sono Motors GmbH |
| Lightyear Technologies B.V. |
| Aptera Motors Corp. |
| Toyota Motor Corporation |
| Ford Motor Company |
| Volkswagen AG |
| Mahindra & Mahindra Limited |
| General Motors |
| Hanergy Thin Film Power Group |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed Chinese photovoltaic producers anchor upstream capacity, compressing module costs while fleet operator procurement concentration downstream extracts volume discounts that reshape margin distribution across the value chain.
Pricing Analysis
Capacity additions in the Yangtze River Delta are reshaping price floors for automotive-grade monocrystalline panels. Three-tier pricing structure across premium solid-state, standard lithium-ion, and economy hybrid configurations differentiates on battery chemistry grade and KBA type-approval certification. Cost compression in polymer-based solar body panels is intensifying because Sono Motors scales manufacturing below traditional silicon rooftop cost curves. Fleet operators exhibit lowest price sensitivity due to centralized maintenance economics, while individual consumers remain most responsive to upfront capital outlays.
Supply Chain Analysis
Specialized polymer-backsheet manufacturing skills concentrate in Germany's Stuttgart industrial cluster and China's Jiangsu province, constraining scale-up of curved solar surface production. Automotive-grade polysilicon feeds from Xinjiang and Inner Mongolia smelters, solid-state electrolytes from Japanese chemical specialists, and fluoropolymer encapsulants from Belgian suppliers. Single-source vulnerability runs through Chinese photovoltaic wafer concentration. Distribution runs through direct manufacturer channels capturing long-term lease structures, with residual value risk transferred to lessors bundling maintenance and energy yield guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as fleet operator procurement concentrates demand around predictable duty cycles that amortize solar hardware premiums across high-utilization schedules.
For Market Incumbents: Lock in automotive-grade cell supply through captive offtake agreements with Chinese module producers restructuring capacity for vehicle-integrated applications. Invest in KBA and NHTSA certification expertise to compress street-legal approval timelines that currently delay fleet trials. Defend against ultra-lightweight composite chassis entrants by accelerating polymer-based solar body panel cost curve progression below Aptera's mass-reduction engineering economics. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the lowest customer acquisition cost route for pre-configured solar vehicle specifications with standardized panel integrations. Target urban delivery segments in the Netherlands and Germany where route predictability enables accurate solar contribution modeling for residual value guarantees. White-space exists in India's PLI-attracted solar-battery integration investments for license plate privilege eligibility under grid-reliability-varying operating conditions. For Investors and Strategic Acquirers: Valuations sit cheapest among thin-film technology suppliers with automotive-grade efficiency trajectories but unproven vehicle-integration scale. Long-term viability hinges on solid-state chemistry deployments achieving thermal stability certification under evolving battery-solar integration safety protocols. Monitor NHTSA crashworthiness certification timeline clarity and EU Green Deal CO2 benchmark enforcement stringency as inflection indicators for capacity commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Cell Supply Agreement | Captures Chinese photovoltaic capacity restructuring toward vehicle-integrated applications before competitor offtake. |
| KBA Type-Approval Certification Investment | Accelerates street-legal solar fleet trial timelines under German accelerated UV degradation testing protocols. |
| Long-Term Fleet Lease Structure Launch | Bundles vehicles, maintenance, and energy yield guarantees for Dutch logistics operators transferring residual value risk. |
| Polymer Backsheet Manufacturing Scale-Up | Reduces solar body panel costs below traditional silicon rooftop arrays through Sono Motors process licensing. |
| In-Wheel Motor Architecture Partnership | Enables Lightyear's curved solar roof aerodynamic optimization previously incompatible with flat rooftop arrays. |
Study Parameters
Coverage spans Germany, the United States, China, the Netherlands, and India, with primary inputs from each market gathered through structured interviews with fleet procurement directors, photovoltaic module manufacturing executives, automotive platform engineers, and regulatory affairs specialists at KBA and NHTSA. Secondary validation draws from MIIT new energy vehicle catalog listings, EU Green Deal automotive CO2 benchmark documentation, EPA emissions classification standards, and vehicle production registration databases. Bottom-up segment sizing triangulates against top-down market construction across technology and end-user dimensions.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window, modeling pure electric vehicle, hybrid, plug-in hybrid, and lightweight model architectures alongside energy storage solution, solar photovoltaic panel, solar charging system, and smart grid technology segments. CAGRs derive from segment-level growth trajectory analysis incorporating solid-state chemistry deployment pace, thin-film integration yield improvements, and fleet operator procurement cycle timing. Forecast inputs include polysilicon price volatility indices and regulatory sandbox approval velocity.
The model assumes a particular technology adoption path; alternative pathways for perovskite tandem cell architectures would alter the outlook if conversion efficiency gains outpace automotive-grade monocrystalline maturation. Forecasts reflect assumptions about subsidy phase-out calendars and battery-solar integration safety protocol finalization timelines. Practitioners should monitor NHTSA crashworthiness certification friction resolution and Chinese photovoltaic supply chain restructuring announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
BEV On-Board Charger Market