
 Mexico Automotive Electric Bus Market | 2026-2036
Mexico Automotive Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Electric Bus Market Foresight
Aftermarket service revenue is narrowing as manufacturers extend battery and drivetrain warranties to capture lifecycle value. BYD Co Ltd leverages its integrated battery-cell-to-chassis architecture to control service intervals and parts flow. Dina anchors domestic assembly capacity in Ciudad Sahagún, competing on localization compliance and federal procurement eligibility. Zhongtong Bus Co Ltd extends its position through standardized fast-charge interfaces that reduce operator downtime.
Mexico automotive electric buses are heavy-duty passenger vehicles powered by electric traction motors, typically employing lithium-ion battery packs with energy densities between 250 and 300 watt-hours per kilogram, designed for high-cycle urban duty patterns with regenerative braking recovery. Battery electric technology dominates current deployment, while hydrogen fuel cell configurations remain nascent due to hydrogen infrastructure gaps and higher capital requirements. Single-deck buses occupy the volume tier given route flexibility and lower per-unit cost, whereas articulated variants concentrate in Mexico City's Metrobús corridors where passenger loads justify extended platforms and dual-axle electric drivetrains.
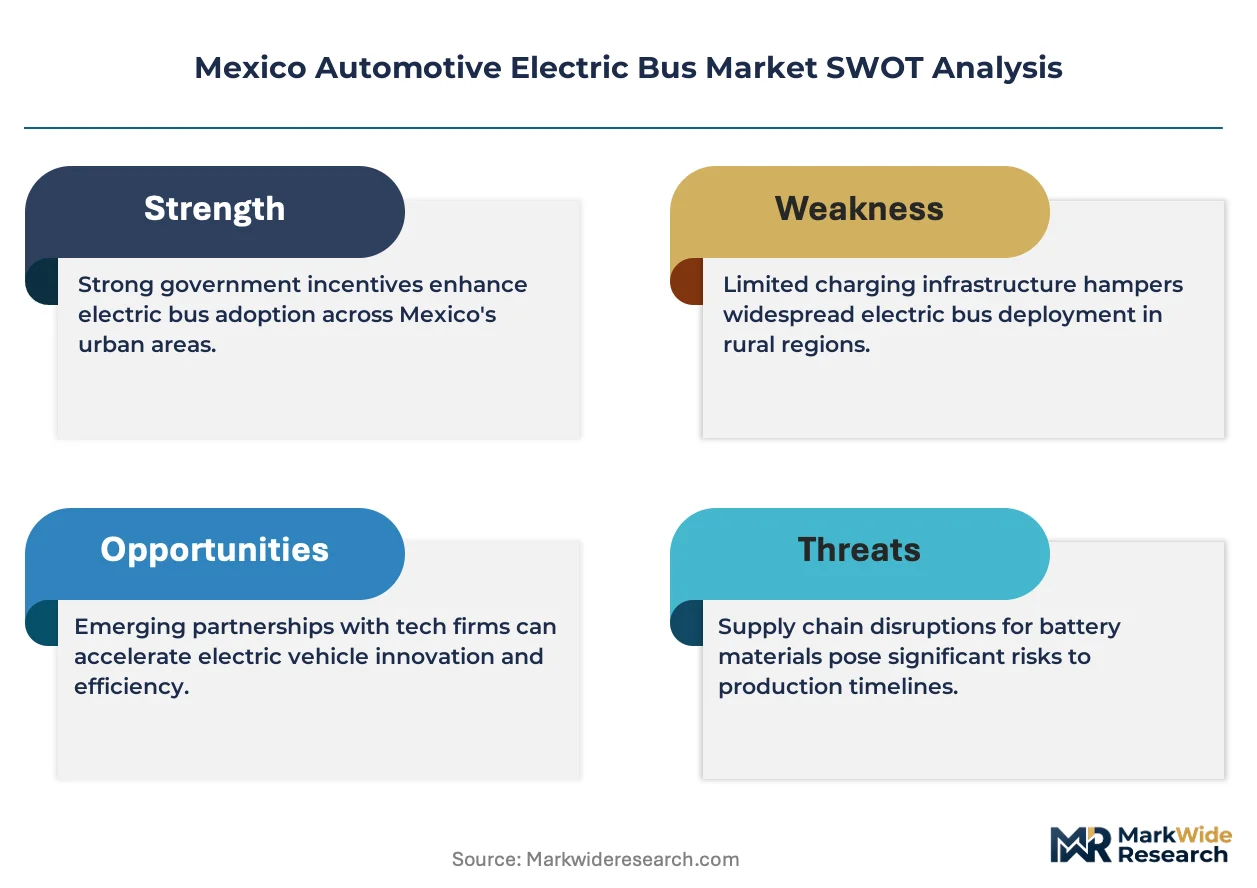
SEMARNAT enforces emissions benchmarks that phase out diesel bus registrations in metropolitan zones, while the Ministry of Economy's Fondo para la Transición Energética directs capital toward charging infrastructure and fleet replacement. NOM-044-SEMARNAT-2015 establishes particulate matter limits that electric buses satisfy without aftertreatment systems, easing type-approval pathways. Stakeholders must monitor state-level concession renewals and subsidy continuity, as procurement decisions hinge on federal fiscal commitment rather than technology maturation alone.
Market Dynamics
Federal subsidy continuity under Fondo para la Transición Energética and SEMARNAT emissions phase-out timelines are compressing procurement cycles for municipal transit agencies across Mexico's three largest metropolitan zones.
Growth Catalysts
- Fondo para la Transición Energética:Capital allocation toward charging infrastructure and fleet replacement is accelerating deployment timelines for state-level clean mobility programs in Mexico City, Guadalajara, and Monterrey.
- Air quality mandates:NOM-044-SEMARNAT-2015 particulate matter limits are eliminating aftertreatment system requirements for electric buses, streamlining type-approval pathways for domestic manufacturers.
- Lithium-ion energy density:Battery packs achieving 250-300 watt-hours per kilogram are extending route range without platform redesign, enabling high-cycle urban duty patterns with regenerative braking recovery.
Market Restraints
- Hydrogen infrastructure gaps:Capital requirements for fuel cell configurations remain prohibitive due to absent refueling networks and higher per-unit procurement costs relative to battery-electric alternatives.
- Charging hardware concentration:Standardized fast-charge interface deployment depends on limited domestic suppliers, creating bottleneck risk for fleet-scale electrification timelines.
- SEMARNAT enforcement variance:State-level concession renewal processes introduce regulatory friction that delays zero-emission fleet procurement in secondary metropolitan zones.
Strategic Opportunities
- Articulated platform expansion:Metrobús corridor extensions in Mexico City are creating demand for dual-axle electric drivetrains in high-passenger-load applications previously served by diesel articulated units.
- Battery-cell-to-chassis integration:Pack architecture innovation is converging with localized assembly capacity in Ciudad Sahagún to reduce import dependency and capture federal procurement eligibility.
- Service interval extension:Extended warranty structures covering drivetrain and battery systems are opening lifecycle value capture models that shift revenue from aftermarket parts to upfront platform sales.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance operations face skill gaps in lithium-ion pack diagnostics and electric motor controller servicing that outpace vocational training program output.
- Charging depot capex intensity:Grid interconnection upgrades and on-site energy storage requirements for overnight fleet charging are straining municipal capital budgets beyond vehicle procurement costs.
- Legacy fleet integration:Mixed-operation depots managing diesel and electric assets simultaneously are encountering workflow complexity in maintenance bay allocation and parts inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Electric Bus Market |
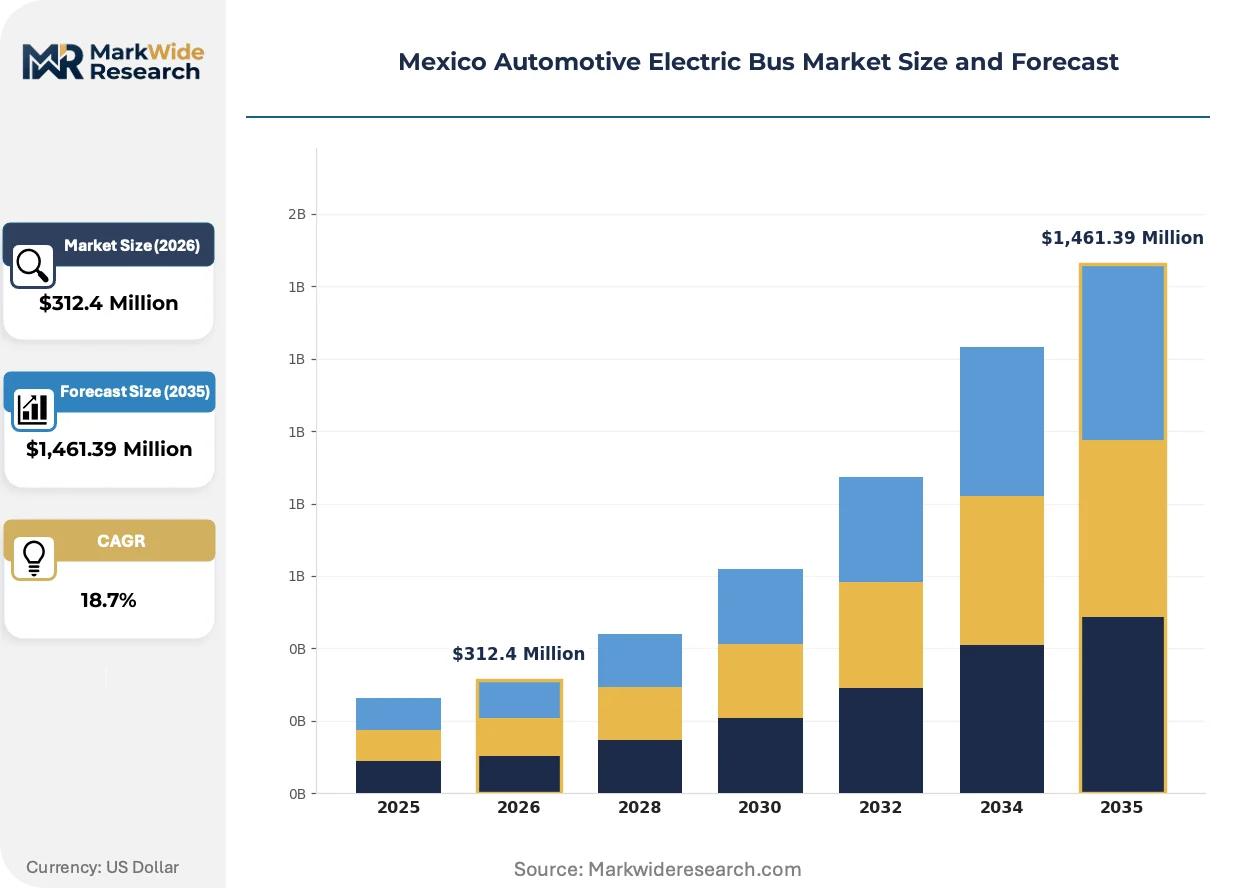
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Deck, Double Deck, Articulated, Mini Bus Technology: Battery Electric, Plug-in Hybrid, Hydrogen Fuel Cell, Others End User: Public Transport, School Transportation, Corporate Fleets, Ride-Sharing Services Application: Urban Transit, Intercity Travel, Commuter Services, Shuttle Services |
| Companies Covered | Daimler AG, Zhongtong Bus Co Ltd, BYD Co Ltd, Megaflux, Higer Bus Co Ltd, Yutong Bus, King Long Bus United Automotive Industries Co Ltd, Dina, Volvo AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Electric Bus Market Shifts & Advancements
Bus architecture is converging around integrated battery-pack designs that eliminate traditional chassis rails, while procurement patterns shift toward lifecycle-cost evaluation frameworks.
Cell-to-chassis battery architecture is digitizing vehicle control systems by embedding battery management modules directly into structural floor panels. Municipal transit agencies in Mexico City are adopting these platforms for Metrobús corridor renewals. The technology is digitizing maintenance scheduling through real-time state-of-health telemetry that compresses unplanned downtime intervals.
SEMARNAT's phased diesel registration restrictions are mandating zero-emission fleet percentages in metropolitan air quality non-attainment zones. The industrial consequence is accelerated concession renewal timelines that favor electric platform incumbents. Articulated bus operators in Mexico City's BRT network are responding by consolidating procurement volumes to secure pricing leverage.
Municipal buyers are migrating from capital-expenditure procurement to availability-based contracting that transfers operational risk to manufacturers. Fleet operators in Guadalajara and Monterrey are displacing traditional purchase models with performance-guaranteed service agreements. This shift is most visible in state-level transit agencies where federal subsidy structures now favor multi-year total-cost-of-ownership evaluation over upfront unit pricing.
Mexico Automotive Electric Bus Market Segmentation
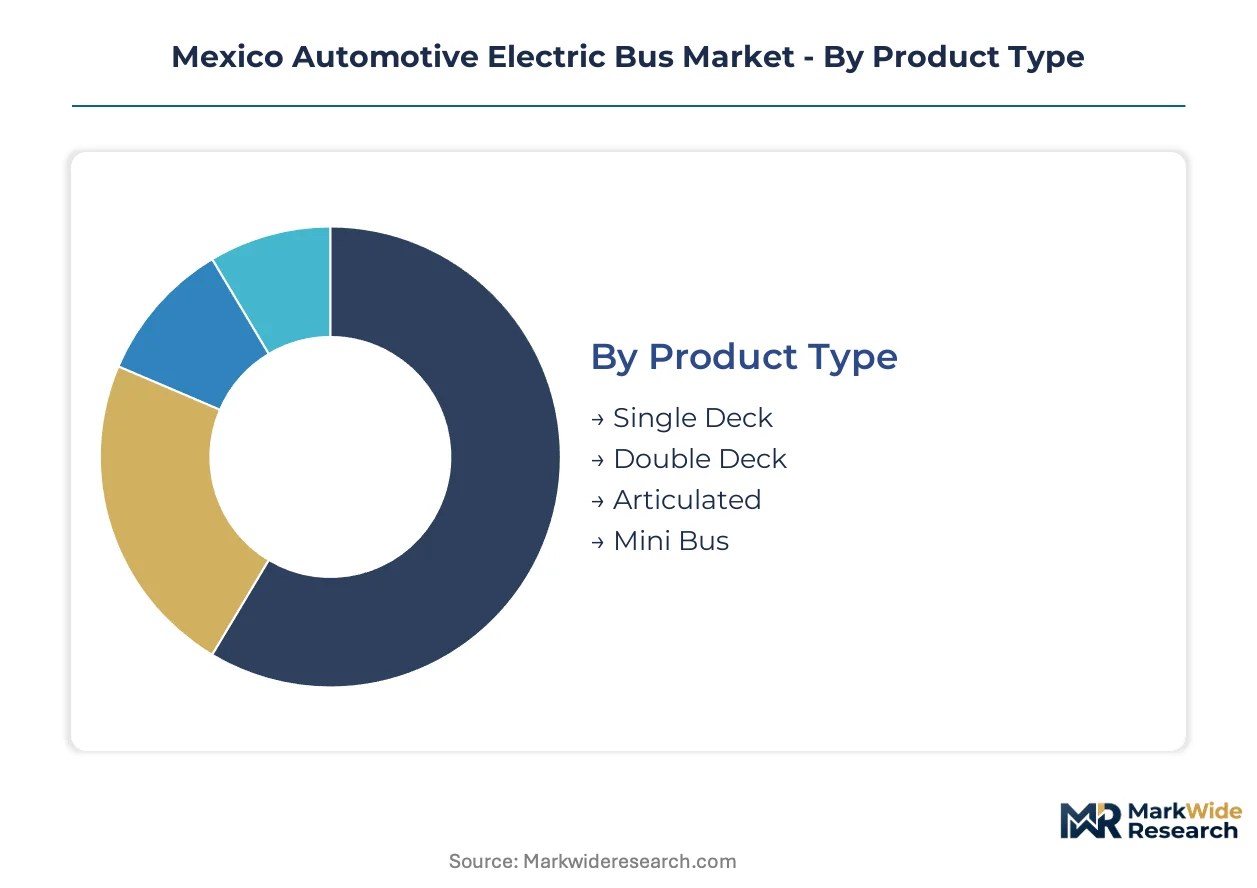
Mexico's electric bus procurement patterns diverge sharply across product configurations and duty cycles. Fleet managers prioritize platform geometry and energy system architecture based on route density, passenger volume, and depot charging constraints.
Product Type:
Single-deck units turn over fastest in Mexico City's peripheral corridor renewals, while articulated platforms cycle slowly through decade-long BRT concession terms. Double-deck and mini bus segments occupy intermediate replacement rhythms tied to specialized route economics.
- Single Deck:Standard 12-meter platforms dominate Mexico City Metrobús line extensions and Guadalajara's Mi Macro Calzada network. SEMARNAT emissions phase-out deadlines are compressing procurement timelines for these configurations in metropolitan non-attainment zones.
- Articulated:Dual-axle 18-meter platforms with centralized or distributed electric drivetrains serve high-volume BRT corridors where passenger loads exceed 250 per vehicle. Mexico City's Insurgentes and Reforma corridors anchor demand for these extended platforms.
- Double Deck:Limited deployment concentrates in Monterrey's mountainous terrain where grade-climbing torque requirements favor high-floor battery placement.
- Mini Bus:7-9 meter configurations penetrate Guadalajara's hillside colonias and Monterrey's industrial satellite routes where narrow street geometry excludes standard platforms.
Single Deck dominates installed base. Articulated is where expansion concentrates.
Technology:
Cost tiers separate procurement eligibility across federal subsidy programs and state-level clean mobility budgets. Battery-electric platforms access Fondo para la Transición Energética capital pools while hydrogen configurations remain outside current funding envelopes.
- Battery Electric:Lithium-ion packs with 250-300 watt-hour per kilogram energy densities power high-cycle urban duty patterns. Regenerative braking recovery systems extend effective range across Mexico City's stop-and-go corridor topography.
- Plug-in Hybrid:Range-extender architectures with downsized diesel or CNG generators serve intercity routes beyond depot charging radius. Nuevo León state transit agencies evaluate these for Monterrey-Saltillo commuter corridors.
- Hydrogen Fuel Cell:Proton-exchange membrane stacks face capital cost barriers and absent hydrogen refueling infrastructure across Mexican metropolitan zones.
- Others:Trolleybus and catenary-electric configurations persist in legacy Mexico City routes where overhead wire infrastructure remains operational.
Battery Electric captures federal procurement eligibility. Plug-in Hybrid is where route flexibility requirements are expanding most quickly.
End User:
Customer type determines financing structure and lifecycle accountability. Public agencies deploy availability-based contracting while corporate fleets favor outright purchase with accelerated depreciation schedules.
- Public Transport:Municipal transit agencies in Mexico City, Guadalajara, and Monterrey deploy performance-guaranteed service agreements that transfer operational risk to manufacturers. SEMARNAT concession renewals mandate zero-emission fleet percentages.
- School Transportation:State education ministry contracts in Jalisco and Nuevo León specify wheelchair-accessible single-deck platforms with extended warranty coverage.
- Corporate Fleets:Mining and manufacturing campus shuttles in Sonora and Coahuila prioritize 24-hour operational availability with battery swap or opportunity charging protocols.
- Ride-Sharing Services:App-based operators in Mexico City's peripheral municipalities test mini bus configurations for first-mile feeder routes to Metrobús stations.
Public Transport dominates installed base. Corporate Fleets is where procurement flexibility is expanding most rapidly.
Application:
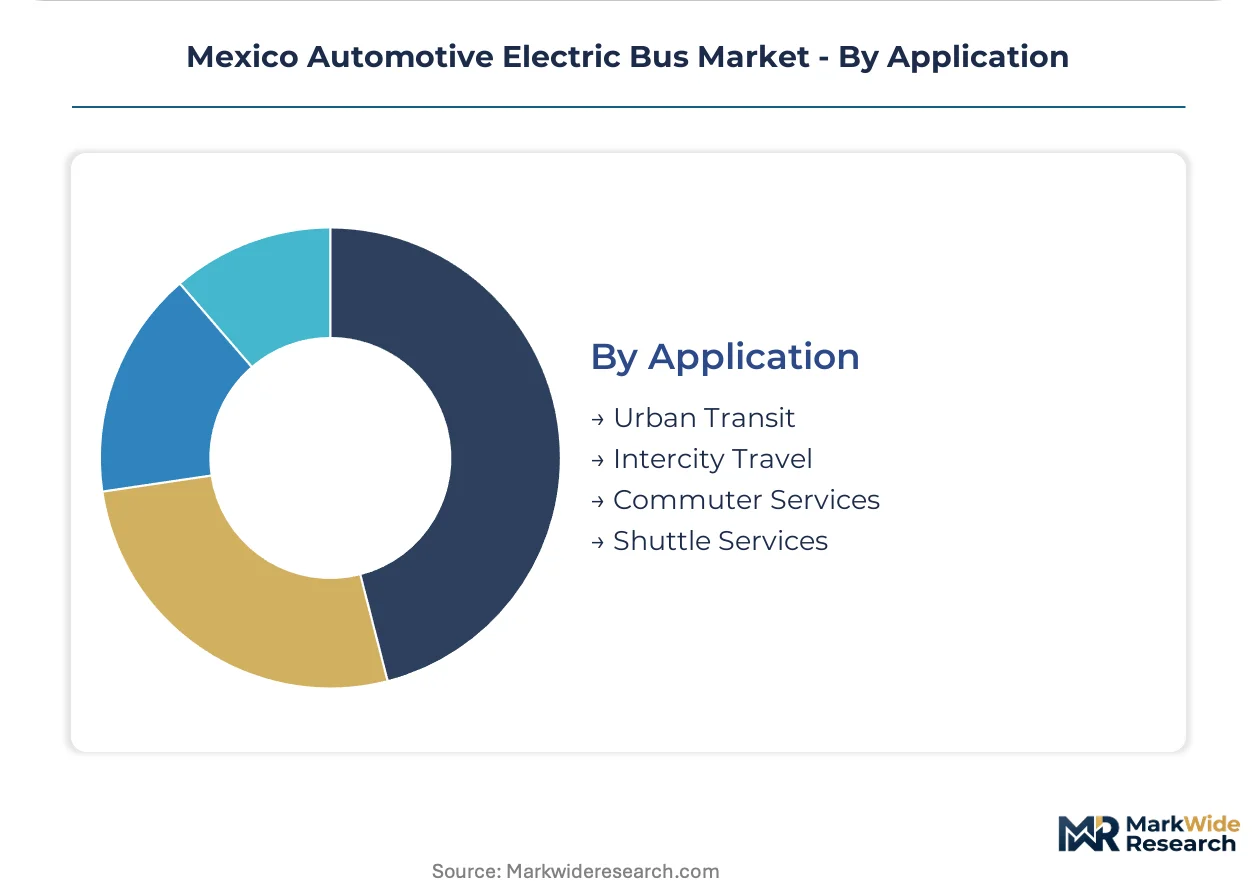
Volume concentration varies by duty cycle intensity and passenger throughput requirements. Urban transit corridors generate platform-scale procurement while intercity applications remain nascent due to range and charging infrastructure gaps.
- Urban Transit:High-frequency corridor operations with 15-20 hour daily duty cycles demand fast-charge interfaces and battery thermal management systems calibrated for tropical altitude conditions in Mexico City's 2,240-meter elevation.
- Intercity Travel:Long-haul electric coach applications face range limitations on Mexico City-Querétaro and Guadalajara-Morelia corridors where 300-kilometer distances exceed single-charge capability.
- Commuter Services:Suburban rail feeder routes in Estado de México and Jalisco operate on fixed schedules that accommodate overnight depot charging with lower power draw requirements.
- Shuttle Services:Airport and hotel circuit routes in Cancún and Los Cabos prioritize passenger experience specifications including low-floor entry and USB charging infrastructure.
Urban Transit dominates installed base. Shuttle Services is where premium specification demand is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City Metro deploys battery-electric single-deck buses for high-frequency corridor duty, while Nuevo León prioritizes articulated platforms for BRT expansion and Jalisco tests mini bus configurations for hillside feeder routes.
Mexico City Metro
SEMANAT emissions phase-out deadlines compress procurement timelines for 12-meter single-deck units across peripheral corridor renewals. The Fondo para la Transición Energética directs capital toward charging infrastructure in the metropolitan non-attainment zone. Metrobús line extensions on Insurgentes and Reforma anchor articulated platform demand where passenger loads exceed 250 per vehicle.
Nuevo León
Monterrey's mountainous terrain generates grade-climbing torque requirements that favor high-floor battery placement in double-deck configurations. State-level clean mobility programs under SEMARNAT guidelines accelerate concession renewal timelines for zero-emission fleet percentages. The Monterrey-Saltillo commuter corridor evaluates plug-in hybrid range-extender architectures for intercity distances beyond depot charging radius.
Jalisco
Guadalajara's Mi Macro Calzada network standardizes 12-meter single-deck platforms for urban transit corridors with 15-20 hour daily duty cycles. Federal subsidies through Fondo para la Transición Energética enable performance-guaranteed service agreements that transfer operational risk to manufacturers. Hillside colonias in the metropolitan periphery test 7-9 meter mini bus configurations where narrow street geometry excludes standard platforms.
Bajío Region
Industrial satellite routes around León and Querétaro prioritize corporate fleet procurement for mining and manufacturing campus shuttles. State education ministry contracts specify wheelchair-accessible single-deck platforms with extended warranty coverage for school transportation. The region's lower population density delays charging depot capex commitments relative to Mexico's three largest metropolitan zones.
Northern Border States
Cross-border logistics corridors in Sonora and Coahuila emphasize 24-hour operational availability with battery swap protocols for corporate fleet applications. Grid interconnection upgrades for overnight fleet charging strain municipal capital budgets beyond vehicle procurement costs. Secondary metropolitan zones encounter SEMARNAT enforcement variance that delays zero-emission fleet procurement timelines.
Mexico Automotive Electric Bus Market Competitive Landscape
Capability concentration sits with integrated battery-cell-to-chassis specialists; scale advantage sits with established commercial vehicle manufacturers with localized assembly footprints. The market structures around three tiers: domestic assemblers competing on federal procurement eligibility, Chinese battery-electric platform exporters leveraging fast-charge standardization, and European premium chassis providers. Dominant competitive moves include warranty extension to capture lifecycle value and backward integration into battery pack assembly to reduce import dependency.
Within the integrated architecture tier, BYD Co Ltd and Zhongtong Bus Co Ltd occupy positions exemplifying cell-to-chassis battery management systems that embed control modules directly into structural floor panels. Dina anchors domestic assembly capacity in Ciudad Sahagún, representing localization compliance strategies that secure federal procurement eligibility under SEMARNAT guidelines. These three companies illustrate the competitive tension between import-dependent technology transfer and captive supply chain development.
| Leading Market Players |
|---|
| Daimler AG |
| Zhongtong Bus Co Ltd |
| BYD Co Ltd |
| Megaflux |
| Higer Bus Co Ltd |
| Yutong Bus |
| King Long Bus United Automotive Industries Co Ltd |
| Dina |
| Volvo AB |
| Others |
Supply & Pricing Matrix
Undercapacity in domestic battery pack assembly at Ciudad Sahagún is compressing procurement timelines and amplifying pricing leverage for integrated cell-to-chassis specialists. SEMARNAT's phased diesel restrictions are accelerating municipal fleet replacement cycles, forcing transit agencies into shorter-dated contracts that absorb premium pricing for guaranteed delivery slots.
Pricing Analysis
Long-term offtake agreements dominate procurement for Mexico City Metrobús corridor renewals, locking unit pricing across multi-year concession terms. Three-tier pricing structure across premium, standard, and economy levels separates articulated platforms with dual-axle drivetrains from single-deck configurations and mini bus variants. Cost compression in standard-tier battery-electric units is intensifying because Chinese exporters are absorbing tariff exposure to secure volume. State-level transit agencies exhibit highest price sensitivity due to Fondo para la Transición Energética subsidy caps, while corporate mining campus fleets accept premium positioning for 24-hour availability guarantees.
Supply Chain Analysis
Export-control restrictions on advanced battery management semiconductors are constraining flows from US and Taiwanese foundries into Mexican assembly operations. Lithium-ion cell supply concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Chinese chemical hubs. The supply chain rests on high-purity lithium carbonate, copper foil current collectors, and thermal management ceramics as critical inputs. Single-source vulnerability in battery management system firmware creates chokepoint risk for fleet-scale deployments. Distribution runs through regional commercial vehicle dealerships with certified high-voltage service bays, bypassing traditional aftermarket parts networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Availability-based service contracts are expanding faster than unit sales, creating attach-rate opportunities in predictive maintenance software and battery health telemetry subscriptions.
For Market Incumbents: Build warranty-duration moats by extending drivetrain coverage to capture lifecycle value previously lost to aftermarket service providers. BYD's integrated architecture demonstrates how controlling battery-to-chassis integration locks out third-party service competition. Dina should add dedicated high-voltage technician training capacity at Ciudad Sahagún to defend against Chinese exporters establishing localized service networks. SEMARNAT enforcement variance across secondary metropolitan zones represents a regulatory arbitrage threat that favors early movers with established state-level relationships. For New Entrants and Emerging Players: Corporate campus shuttle contracts in Sonora and Coahuila represent the most penetrable entry point, where 24-hour operational requirements and battery-swap protocols favor nimble specialists over incumbent transit OEMs. Jalisco's hillside colonia feeder routes offer secondary white-space for mini bus configurations excluded from standard platform procurement. A go-to-market angle anchored on performance-guaranteed uptime contracts—transferring operational risk from mining operators to vehicle suppliers—bypasses capital-budget constraints that stall municipal procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-cell-to-chassis integration tiers as pack assembly localizes in Mexican free-trade zones. Long-term viability over the coming decade hinges on capturing recurring revenue from telemetry-enabled predictive maintenance rather than hardware margins alone. Acquisition targets should display captive battery pack assembly capability or exclusive fast-charge interface licensing. The signal to watch is Fondo para la Transición Energética reauthorization levels, which determine subsidy continuity and procurement acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Korean or Chinese suppliers under long-term offtake terms. |
| Charging Infrastructure Partnership | Aligns depot grid upgrades with CFE interconnection timelines to prevent deployment bottlenecks. |
| Software-Defined Vehicle Investment | Enables over-the-air battery management updates that extend pack lifecycle and reduce warranty exposure. |
| Geographic Manufacturing Footprint | Establishes SEMARNAT-compliant assembly in Ciudad Sahagún to access federal procurement eligibility. |
| Platform Standardization | Reduces parts inventory complexity for mixed diesel-electric depots transitioning to zero-emission fleets. |
Research Methodology
Operator-level perspectives from municipal transit fleet managers, charging infrastructure developers, and high-voltage service technicians anchored the qualitative base. Primary interviews with SEMARNAT regulatory officials and Fondo para la Transición Energética program administrators were cross-referenced against secondary sources including vehicle registration databases, state concession renewal filings, and customs import records for lithium-ion cells. Bottom-up unit deployment tracking across Mexico City, Guadalajara, and Monterrey was triangulated with top-down federal subsidy allocation data.
Scenario-bracketing around SEMARNAT enforcement intensity and Fondo reauthorization probability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform geometry, propulsion architecture, end-user financing structure, and regional regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to concession renewal timelines and charging depot capex cycles. Forecast inputs incorporated battery energy density improvement trajectories and fast-charge interface standardization adoption rates.
Practitioners should monitor subsidy continuity signals and hydrogen infrastructure pilot announcements for early indicators of technology pathway shifts. Forecasts reflect documented assumptions regarding federal fiscal commitment persistence and lithium carbonate supply elasticity. Material shifts in SEMARNAT enforcement uniformity or Fondo capital allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
Mexico Solar E-Bike Market