
 Poland E-Bike Market | 2026-2036
Poland E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Poland E-Bike Market Analytics
Mid-drive motor specifications above 250W nominal output is unwinding the entry-level commuter segment toward premium urban mobility. KROSS anchors its domestic production in Kielce, leveraging Polish manufacturing scale to control regional distribution costs. Giant Manufacturing competes through R&D intensity in battery integration systems, while ROMET specializes in value-engineered frames for the local mass market.
Poland e-bikes are electrically assisted bicycles incorporating rechargeable battery packs, hub or mid-drive motors, and pedal-assist sensors to augment human propulsion up to 25 km/h under EU type-approval rules. City E-Bikes dominate unit sales as Warsaw and Łódź expand segregated cycle lanes, while Cargo E-Bikes capture expanding margin pools from last-mile delivery services replacing diesel vans. Lithium-Ion battery configurations lead the power segment due to energy density advantages, though Nickel-Metal Hydride retains niche positioning in rental fleet applications prioritizing cost over weight.
Poland's Office of Technical Inspection (UDT) enforces periodic safety certification for e-bike electrical systems, while EU Regulation 168/2013 governs type-approval thresholds that determine whether vehicles qualify as bicycles or require motorcycle homologation. The National Fund for Environmental Protection and Water Management shapes demand through purchase subsidies tied to domestic assembly requirements. Stakeholders must monitor whether proposed EU Battery Regulation amendments will mandate recycled content quotas that reshape Polish supply chain sourcing from Asian cell manufacturers.
Market Dynamics
The National Fund for Environmental Protection and Water Management's "Mój Elektryk" subsidy program is compressing payback periods for urban commuters while Warsaw's congestion pricing zones mechanically displace car trips toward pedal-assist alternatives.
Growth Catalysts
- EU Regulation 168/2013:The 25 km/h type-approval threshold keeps e-bikes in the bicycle category, avoiding motorcycle homologation costs and licensing friction for Polish buyers.
- Last-mile delivery services:Courier fleets in Łódź and Kraków are replacing diesel vans with cargo e-bikes to navigate historic city centers with vehicle restrictions.
- Lithium-ion energy density:Improved cell chemistry extends range per charge, reducing range anxiety among suburban commuters in the Masovian Voivodeship.
Market Restraints
- Asian cell concentration:Polish assemblers depend on imported battery cells from East Asian manufacturers, exposing margins to shipping cost volatility and currency fluctuation.
- UDT certification timelines:The Office of Technical Inspection's electrical safety verification creates multi-week delays between assembly completion and retail availability.
- Internal combustion substitution:Used conventional bicycles and second-hand scooters compete for the same household mobility budget in price-sensitive segments.
Strategic Opportunities
- Lesser Poland Voivodeship:Kraków's cycling infrastructure investments lag Warsaw, creating whitespace for early-mover retail and service network establishment.
- Battery-swapping stations:Integration of automated exchange kiosks with commercial real estate addresses apartment-dwellers without home charging access.
- EU Battery Regulation amendments:Proposed recycled content quotas would advantage Polish assemblers with European cell sourcing relationships over pure importers.
Industry Challenges
- Mechatronics technician scarcity:The shortage of qualified repair specialists for mid-drive motor systems limits after-sales service capacity outside Warsaw and Kraków metropolitan areas.
- Legacy inventory obsolescence:Rapid motor power specification upgrades strand 250W nominal units in distributor warehouses, compressing working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland E-Bike Market |
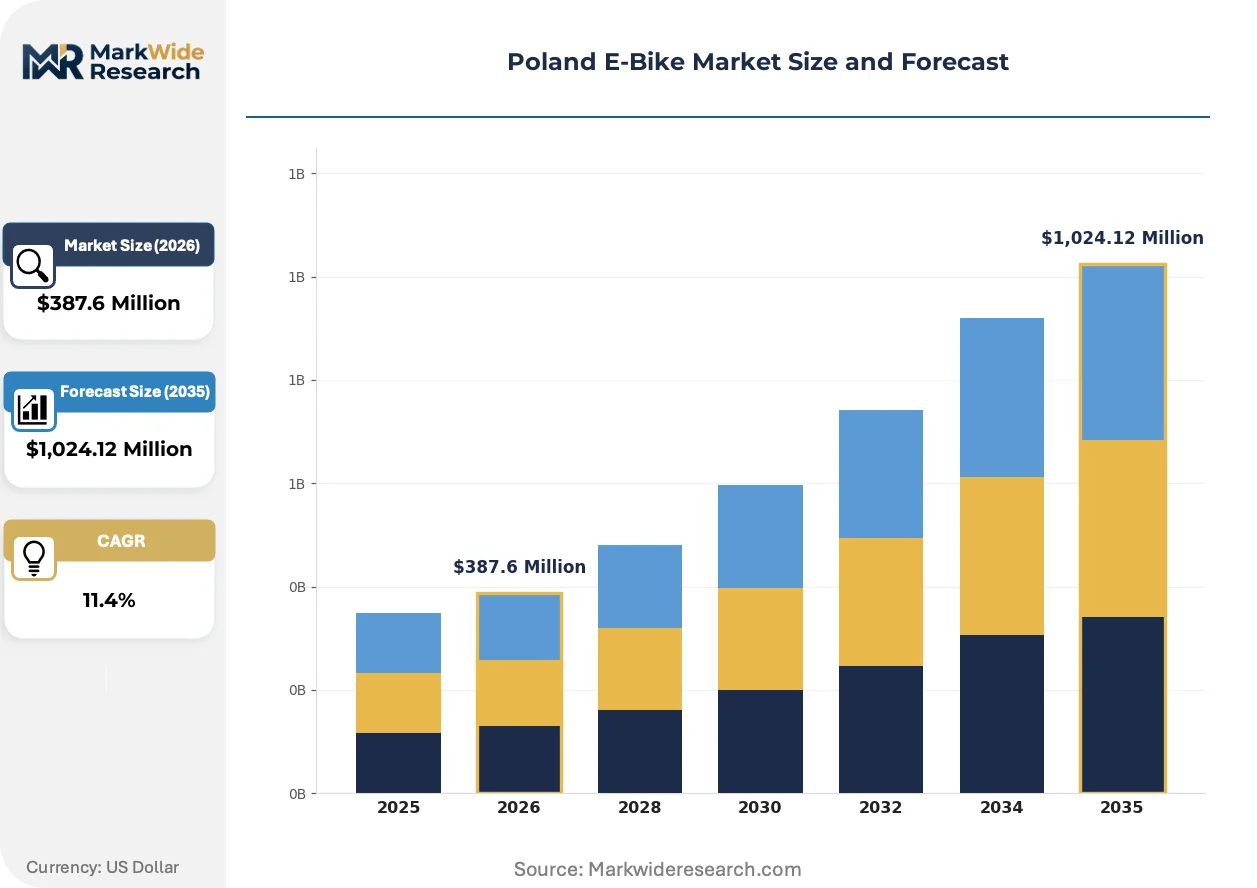
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer End User: Commuters, Recreational Users, Delivery Services, Tourists Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Giant Manufacturing, Accell Group, KROSS, Specialized, Trek Bikes, ROMET, Merida Industry, Yamaha Motor, Ecoride, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland E-Bike Market Evolving Landscape
Polish e-bike configuration is pivoting from hub-mounted toward mid-drive motor architectures as torque-sensor precision improves and frame-integrated battery design becomes standard.
Mid-drive motor systems are miniaturizing while maintaining 80 Nm peak torque output, enabling frame designers to reduce bottom-bracket intrusion and improve ground clearance for urban curbs. Cargo fleet operators in Warsaw are specifying these compact units for loaded hill starts. The form-factor reduction is miniaturizing the mechanical distinction between commuter and performance segments, collapsing premium pricing tiers.
Poland's Office of Technical Inspection is harmonizing electrical safety testing protocols with EU-wide UNECE standards, reducing duplicate certification costs for exporters. Domestic manufacturers serving German and Benelux markets face simplified homologation. The Masovian Voivodeship assembly plants are responding by consolidating variant production around unified electrical architectures.
Subscription-based fleet access is displacing outright ownership among corporate mobility programs in Silesian industrial zones. Employers contract operating leases inclusive of maintenance and insurance rather than capitalizing bicycle assets. The model is most visible in Katowice-Gliwice corridor manufacturing campuses where shift-worker transportation benefits are standardized.
Poland E-Bike Market Segmentation
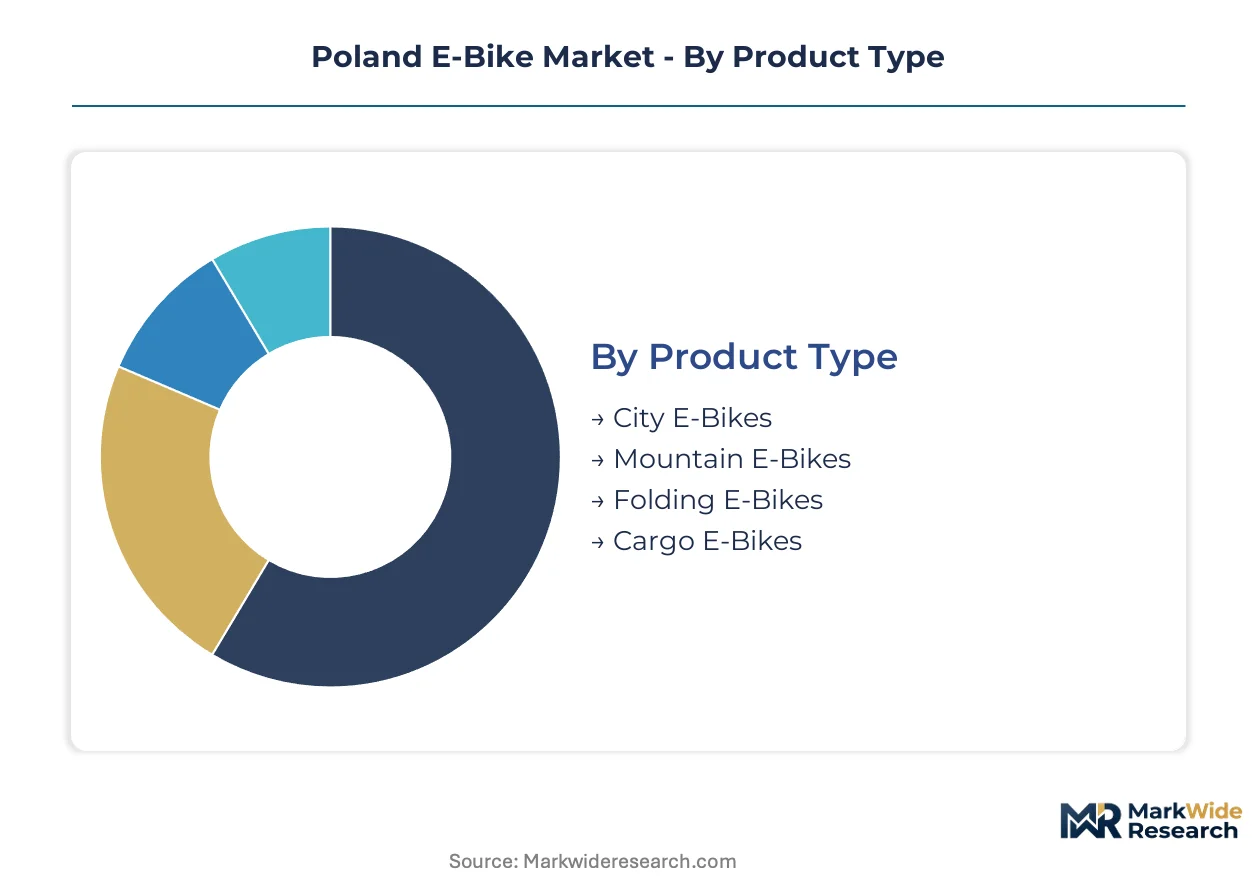
Poland's e-bike segmentation reveals how subsidy programs and infrastructure investments concentrate demand in specific configurations. Each dimension carries distinct substitution pressures from conventional mobility alternatives.
Product Type:
Substitution pressure from second-hand conventional bicycles and internal combustion scooters hits entry-level configurations hardest, while premium segments defend through performance differentiation.
- City E-Bikes:Frame-integrated battery designs with hub or mid-drive motors dominate Warsaw and Kraków commuter corridors. Masovian Voivodeship segregated cycle lane expansion mechanically displaces car trips toward these pedal-assist configurations.
- Cargo E-Bikes:Extended wheelbase frames with dual-battery architectures and 500W+ peak output motors serve last-mile delivery fleets in Łódź and Kraków historic centers. Vehicle restriction zones in municipal cores force diesel van substitution toward these heavy-load platforms.
- Mountain E-Bikes:Full-suspension frames with torque-sensor mid-drive systems target recreational trail access in Polish upland regions.
- Folding E-Bikes:Compact hinge-frame designs with reduced battery capacity address apartment storage constraints in dense urban districts.
City E-Bikes retain volume leadership; Cargo E-Bikes hold the steepest expansion curve.
Battery Type:
Cost tier stratification separates energy-dense premium configurations from weight-tolerant economy alternatives in rental and fleet applications.
- Lithium-Ion:NMC and LFP cell chemistries deliver 500+ Wh energy density for range-extended suburban commuting. Polish assemblers source these cells from East Asian manufacturers, exposing margins to shipping cost volatility and currency fluctuation.
- Lithium Polymer:Pouch-cell form factors enable frame-integrated battery designs with irregular mounting geometries. Premium urban mobility specifications in Warsaw favor these configurations for aesthetic integration.
- Nickel-Metal Hydride:Lower energy density tolerates rental fleet duty cycles where capital cost outweighs weight penalties.
- Lead-Acid:Legacy flooded-cell designs persist in price-sensitive segments and agricultural auxiliary power applications.
Lithium-Ion dominates value concentration; Lithium Polymer is climbing the fastest on design flexibility premiums.
End User:
Application-specific duty cycles differentiate reliability requirements and service network density needs across user categories.
- Commuters:Daily round-trip specifications with weather-sealed electrical systems and integrated lighting prioritize reliability over performance. Warsaw congestion pricing zones mechanically expand this segment through car trip displacement.
- Delivery Services:Commercial-duty frame reinforcements and swappable battery configurations support 12-hour operational cycles. Courier fleets in Kraków and Łódź specify these platforms for historic center access where diesel vans face restrictions.
- Recreational Users:Weekend trail and tourism corridor applications with torque-sensor precision for variable terrain engagement.
- Tourists:Short-term rental specifications with simplified controls and theft-deterrent hardware for seasonal demand in Baltic coast and mountain resort zones.
Commuters retain volume leadership; Delivery Services hold the steepest expansion curve.
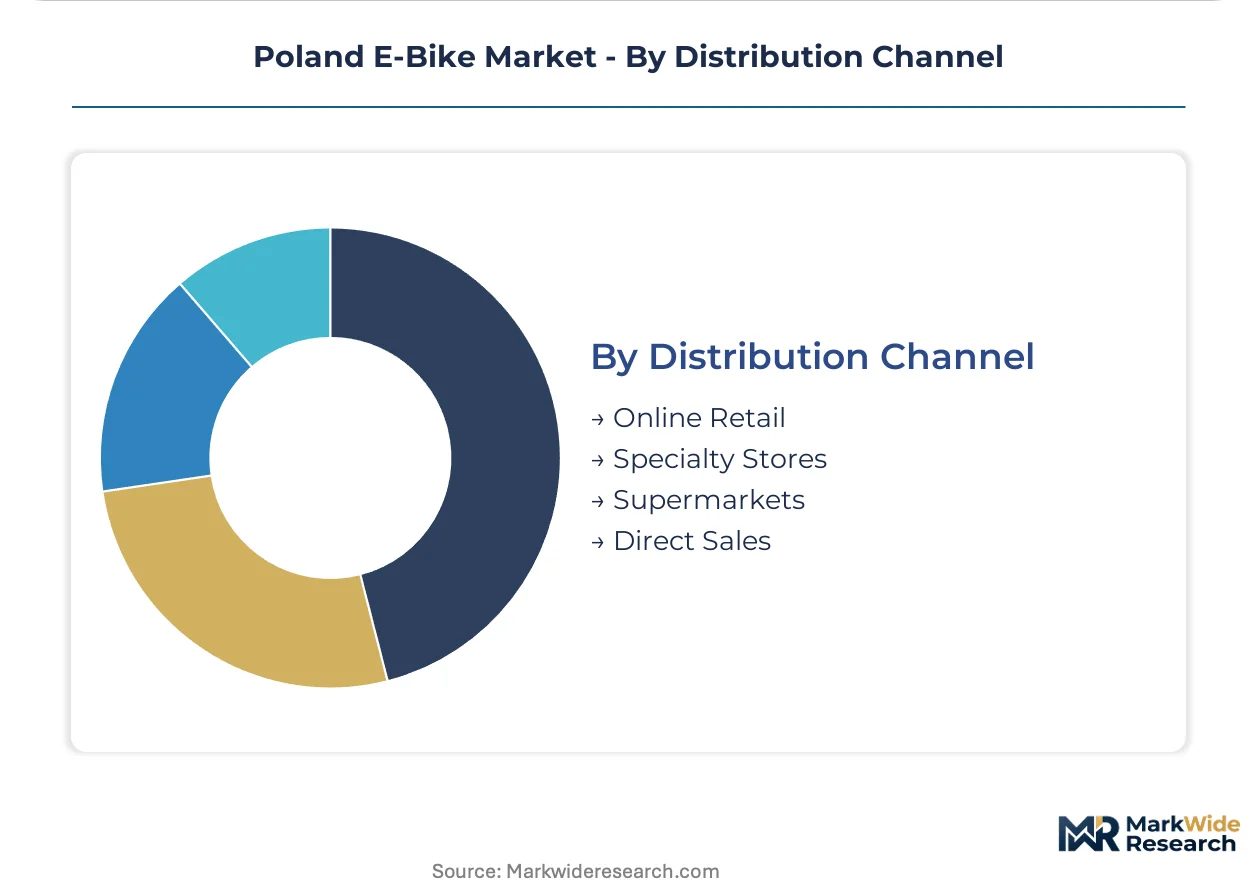
Distribution Channel:
Customer type and purchase complexity determine whether transactions complete through high-touch service networks or direct digital fulfillment.
- Specialty Stores:Technical consultation, test ride facilities, and after-sales service capacity concentrate in Warsaw and Kraków metropolitan areas. UDT certification requirements and mid-drive motor complexity sustain this channel's relevance for premium configurations.
- Online Retail:Direct-to-consumer platforms with specification comparison tools and home delivery capture price-sensitive segments. Entry-level hub-motor configurations with standardized sizing tolerate remote purchase without fitting services.
- Direct Sales:Manufacturer-owned showrooms and subscription fleet programs serve corporate mobility contracts in Silesian industrial zones.
- Supermarkets:Mass-market retail with limited technical support handles basic commuter specifications and seasonal promotional inventory.
Specialty Stores retain volume leadership; Online Retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Dutch component exports flow into Polish assembly plants serving Central European distribution networks. Warsaw and Kraków metropolitan zones concentrate domestic demand through congestion pricing and subsidy programs. Regional production clusters in Kielce and Silesia leverage proximity to German engineering supply chains.
Masovian Voivodeship
Warsaw's congestion pricing zones mechanically displace car trips toward pedal-assist alternatives. The National Fund for Environmental Protection and Water Management channels "Mój Elektryk" subsidies through domestic assembly requirements. Kielce anchors manufacturing scale for KROSS production serving regional distribution.
Lesser Poland Voivodeship
Kraków's historic center vehicle restrictions force courier fleet substitution toward cargo platforms. EU Regulation 168/2013 preserves bicycle-category status for 25 km/h configurations avoiding motorcycle homologation. Cycling infrastructure investment lags Warsaw, creating whitespace for early-mover retail establishment.
Łódź Voivodeship
Last-mile delivery services in Łódź replace diesel vans with heavy-load cargo specifications for historic district access. The Office of Technical Inspection enforces UDT electrical safety certification creating multi-week retail delays. Segregated cycle lane expansion connects residential zones to central business districts.
Silesian Voivodeship
Corporate mobility programs in Katowice-Gliwice manufacturing campuses standardize subscription-based fleet access. Shift-worker transportation benefits displace outright bicycle ownership through operating lease structures. Industrial zone density supports centralized maintenance and battery-swapping station economics.
Pomeranian Voivodeship
Seasonal tourism demand in Baltic coast resort zones drives short-term rental specifications with theft-deterrent hardware. Gdańsk metropolitan cycling infrastructure investments expand commuter adoption beyond summer peaks. Port logistics connectivity enables component import efficiency for regional assemblers.
Poland E-Bike Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and distribution reach. The vendor base separates into three tiers: multinational volume manufacturers with integrated R&D pipelines, regional assemblers exploiting domestic subsidy qualifications, and component specialists controlling motor or battery subsystems. Strategic moves concentrate on backward integration into cell sourcing and forward integration into subscription fleet services.
Within the domestic assembly tier, KROSS and ROMET exemplify Polish-based fabricators leveraging proximity to Warsaw and Kraków demand concentrations. Giant Manufacturing represents multinational volume players competing through battery integration R&D intensity. Specialized occupies the premium-performance archetype with torque-sensor precision positioning.
| Leading Market Players |
|---|
| Giant Manufacturing |
| Accell Group |
| KROSS |
| Specialized |
| Trek Bikes |
| ROMET |
| Merida Industry |
| Yamaha Motor |
| Ecoride |
| Others |
Value Network & Pricing Analysis
EU Regulation 168/2013 gates both supply qualification and price differentiation in Poland's e-bike market by establishing the 25 km/h type-approval threshold that separates bicycle-category units from motorcycle-homologated alternatives. This regulatory boundary compresses pricing tiers at the entry level while enabling premium segmentation through motor specification and battery integration sophistication.
Pricing Analysis
Delivery services anchor pricing structure through commercial-duty cargo specifications with dual-battery architectures and 500W+ peak output motors. Three-tier pricing structure across premium, standard, and economy levels separates torque-sensor mid-drive systems from hub-motor commuter configurations and basic rental fleet units. Cost compression in the entry-level segment is intensifying because second-hand conventional bicycles and scooters compete for household mobility budgets. Price sensitivity concentrates among recreational users and tourist rental operators, while courier fleets prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Multi-week UDT certification timelines strain inventory turnover and compress working capital cycles for Polish assemblers awaiting electrical safety verification. Cell sourcing concentrates in China, South Korea, and Japan, with Polish manufacturers drawing from East Asian suppliers for lithium-ion configurations. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare-earth magnet materials for motor assemblies. Single-source vulnerability in battery cell supply exposes margins to shipping cost volatility and currency fluctuation. Distribution runs through specialty retail networks in Warsaw and Kraków metropolitan zones, supplemented by direct-to-consumer platforms for standardized hub-motor configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's e-bike market sits within a cyclical recovery driven by National Fund for Environmental Protection and Water Management subsidy program renewals that mechanically expand addressable demand across voivodeship-level deployment.
For Market Incumbents: Compound defensive position through backward integration into European cell sourcing relationships ahead of proposed EU Battery Regulation recycled content quotas, while expanding service network density in Lesser Poland Voivodeship to preempt emerging entrant retail establishment. Certification investment in UDT electrical safety protocols creates switching costs against import competitors facing multi-week homologation delays. Capacity addition in Kielce production clusters leverages proximity to Masovian Voivodeship demand concentration. For New Entrants and Emerging Players: Differentiate on battery-swapping station integration with commercial real estate partners, addressing apartment-dwellers without home charging access in dense Warsaw districts. White-space targets concentrate in Łódź Voivodeship last-mile delivery fleet specifications and Silesian Voivodeship corporate mobility subscription programs. The most penetrable segment is cargo e-bike platforms for historic center vehicle restriction zones. Go-to-market execution should prioritize automated exchange kiosk partnerships over traditional retail channel builds. For Investors and Strategic Acquirers: EU Battery Regulation amendment passage reshapes the acquisition landscape by advantaging assemblers with European cell sourcing relationships over pure importers dependent on Asian supply. Long-term viability centers on subscription-based fleet ownership models displacing outright purchase in industrial zone transportation benefit programs. Acquisition target archetypes include mechatronics service networks with technician training pipelines and regional assemblers qualifying for domestic content subsidies. The signal to watch is UDT certification queue length as indicator of supply constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into European Cell Sourcing | EU Battery Regulation recycled content quotas would advantage Polish assemblers with regional supply relationships. |
| Battery-Swapping Station Network Deployment | Automated exchange kiosks in Warsaw commercial real estate address apartment-dweller charging access constraints. |
| UDT Certification Capacity Expansion | Reduced electrical safety verification timelines compress working capital cycles and accelerate retail availability. |
| Corporate Mobility Subscription Programs | Operating lease structures in Silesian industrial zones displace outright ownership and standardize fleet replacement. |
| Lesser Poland Voivodeship Retail Establishment | Kraków cycling infrastructure investment lags create whitespace for early-mover service network positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, customs trade data, National Fund for Environmental Protection and Water Management subsidy disbursement records, and UDT certification databases. Primary interviews engaged product managers at domestic assemblers, procurement leads at courier fleet operators, retail channel heads in Warsaw and Kraków metropolitan zones, and mechatronics technicians servicing mid-drive motor systems. Bottom-up unit demand estimates triangulate against top-down voivodeship-level infrastructure investment projections.
Segmentation dimensions modeled include product type configuration, battery chemistry architecture, end-user application duty cycle, and distribution channel structure across the analysis window. CAGRs derive from installed base replacement rates, subsidy program renewal assumptions, and congestion pricing zone expansion schedules. Forecast inputs incorporate cycling lane kilometer additions by voivodeship and commercial fleet electrification mandates in historic city centers.
The analysis sits within stated boundaries; outcomes outside sustained subsidy program funding or accelerated EU Battery Regulation implementation would require recalibration. Forecasts reflect documented assumptions regarding cell chemistry cost curves and technician training pipeline expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market