
 ASEAN EV Battery Pack Market | 2026-2036
ASEAN EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN EV Battery Pack Market Insights
ASEAN's certified battery engineer pool is unwinding as a bottleneck, with vocational programs in Thailand and Vietnam only now scaling to feed module-assembly lines. CATL leverages its integrated cell-to-pack architecture to compress landed costs for Thai OEM contracts. Samsung SDI sustains premium positioning through high-nickel cathode R&D intensity aimed at tropical climate durability. BYD anchors downstream demand through its vertical reach into electric passenger and commercial vehicle sales across Indonesia and Malaysia.
An ASEAN EV battery pack comprises assembled lithium-ion cells, thermal management hardware, battery management circuitry, and structural enclosures engineered to deliver DC power output between 50 kWh and 150 kWh for traction applications. Cell chemistry selection and pack-level thermal runaway mitigation determine cycle life and safety certification under tropical operating conditions. Lithium-ion chemistry dominates current production volumes while solid-state configurations represent the fastest-growing product category as Korean and Japanese suppliers advance oxide-electrolyte pilot lines for Southeast Asian OEM qualification. Passenger vehicles command the largest end-user segment, though commercial vehicle electrification for last-mile logistics in Jakarta and Bangkok is expanding faster in percentage terms.
Thailand's Board of Investment, Indonesia's Ministry of Industry, and Vietnam's Ministry of Transport collectively shape market access through local content thresholds, import duty structures, and EV registration incentives that directly influence pack sourcing decisions. BIS-equivalent national standards bodies across ASEAN member states are converging cell safety testing protocols, reducing duplicate certification burdens for multi-country suppliers. Stakeholders must monitor how Indonesia's nickel ore export restrictions and Thailand's carbon border adjustment preparations will redistribute cell material flows and pack assembly economics across the region.
Market Dynamics
Indonesia's nickel ore export restrictions are redrawing cathode supply geography across Southeast Asia, forcing pack assemblers in Thailand and Vietnam to renegotiate precursor sourcing terms and accelerate alternative feedstock partnerships.
Growth Catalysts
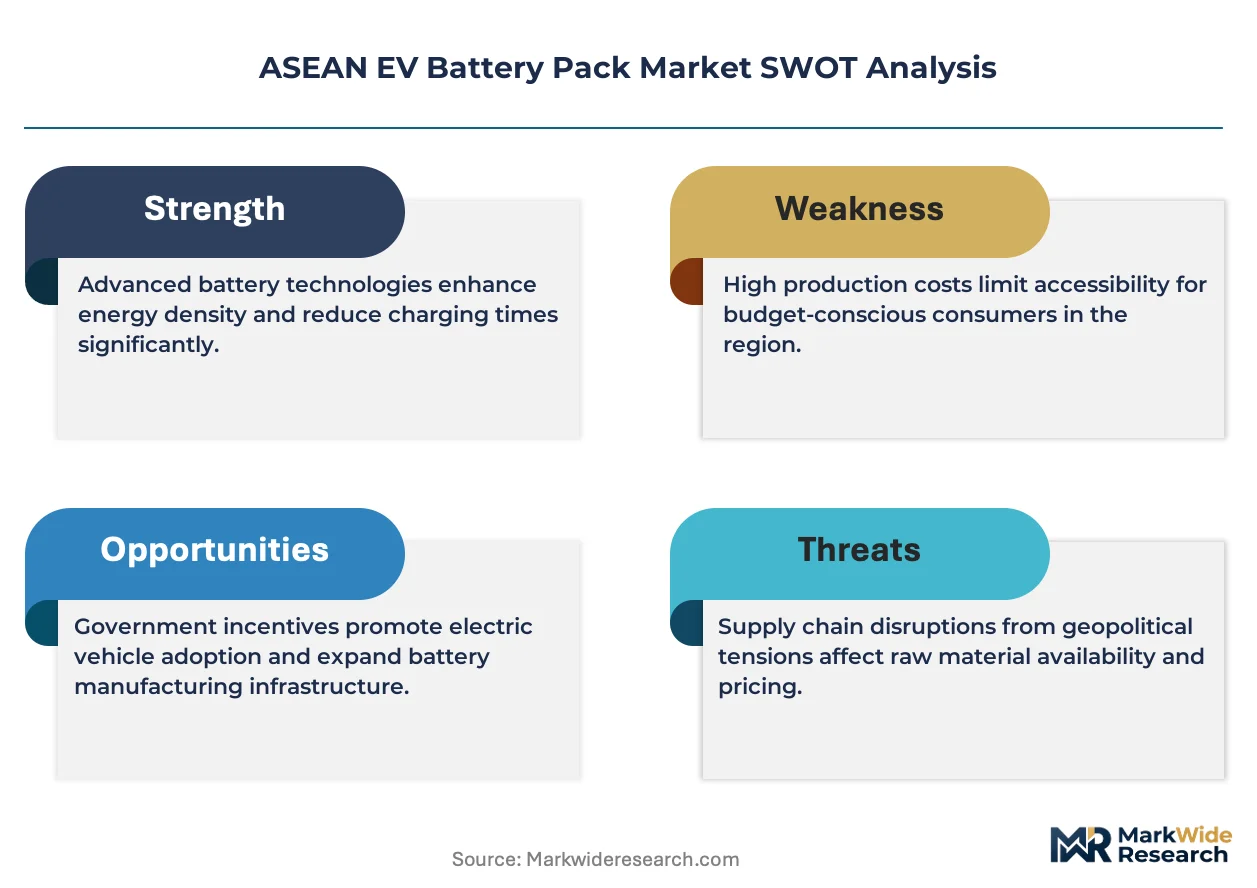
- Thailand's EV tax incentive structure:The Board of Investment's eight-year corporate income tax exemption for battery production facilities compresses capital recovery timelines for module assembly investments.
- Last-mile logistics electrification:Fleet operators in Jakarta and Bangkok are converting diesel vans to electric powertrains, generating concentrated pack procurement volumes from commercial vehicle integrators.
- Cell-to-pack architecture adoption:Integrated designs eliminate module housings and busbar assemblies, reducing pack weight and manufacturing steps for tropical climate applications.
Market Restraints
- Lithium carbonate price volatility:Cell-grade lithium compound costs fluctuate with South American brine expansion delays, squeezing pack margin structures for price-locked OEM contracts.
- Nickel supply concentration:Indonesia's dominance in laterite ore processing creates single-point vulnerability for high-nickel cathode chemistry availability across ASEAN assembly lines.
- Thermal runaway mitigation complexity:Tropical ambient temperatures exceed standard cell testing baselines, requiring redundant cooling hardware that adds pack mass and cost.
Strategic Opportunities
- Vietnam's nascent passenger EV segment:Domestic OEM VinFast is localizing cell production, creating tier-two pack assembly opportunities for Vietnamese component suppliers.
- Battery swapping infrastructure:Two-wheeled electric motorcycle fleets in Indonesia and the Philippines are piloting standardized pack formats that decouple vehicle purchase from battery ownership.
- Malaysia's green technology tax allowance:The Ministry of Finance's 100% capital allowance for energy-efficient equipment imports reduces landed cost for Korean and Japanese cell suppliers establishing regional distribution hubs.
Industry Challenges
- Certified battery engineer scarcity:Thailand's vocational training institutes and Vietnam's technical universities are graduating insufficient technicians qualified for high-voltage pack assembly and diagnostic protocols.
- Multi-country homologation timelines:Divergent national safety testing requirements across ASEAN member states force suppliers to duplicate cell validation cycles, extending product launch schedules.
- Recyclate feedstock uncertainty:End-of-life pack collection networks remain fragmented, limiting black mass availability for hydrometallurgical recovery operations planned by Thai precursor refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN EV Battery Pack Market |
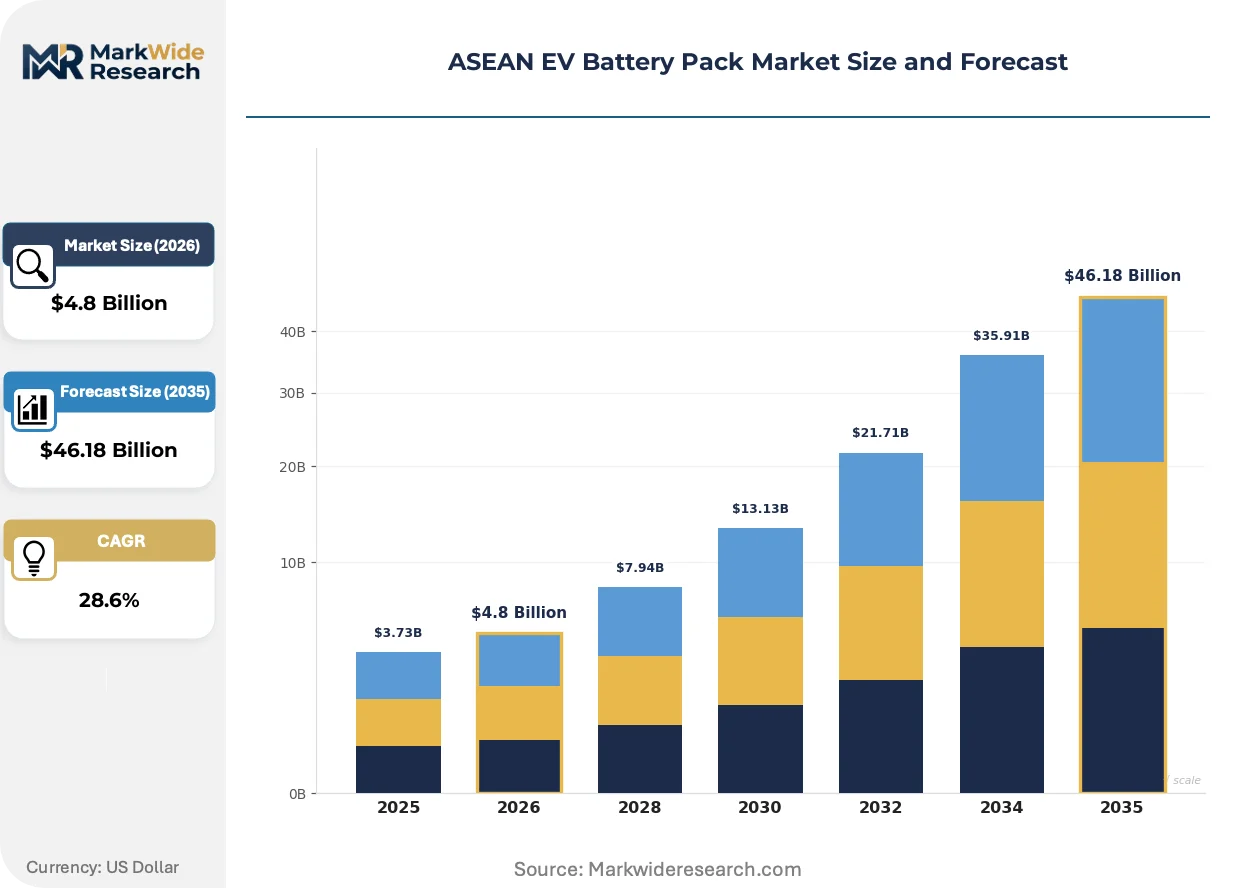
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lead-Acid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Materials Handling Equipment Connection Technology: Wired, Wireless, Fast Charging, Standard Charging Distribution Channel: Direct Sales, Online Retail, Authorized Dealers, Third-Party Distributors |
| Companies Covered | Samsung SDI Co Ltd, SK Innovation Co Ltd, Contemporary Amperex Technology Co Ltd (CATL), Ningde E-CON Power System Co Ltd, Denso Corporation, BYD Company Ltd, Panasonic Holdings Corporation, Guoxuan High-tech Co Ltd, LG Energy Solution Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN EV Battery Pack Market Trends and Innovations
Solid-state electrolyte development and thermal management hardware miniaturization are converging to redefine pack architecture assumptions, while procurement patterns shift toward long-term cathode supply agreements that bypass spot market exposure.
Cell chemistry selection is bifurcating across ASEAN pack lines. Lithium iron phosphate formulations dominate entry-level passenger vehicles where cost sensitivity outweighs energy density requirements. Nickel manganese cobalt variants retain premium positioning in long-range SUVs and commercial vans. This chemistry split is compressing supplier negotiation leverage, as cathode precursor specialists must qualify dual production streams to serve divergent OEM specifications.
Thailand's carbon border adjustment preparation is accelerating domestic renewable energy sourcing mandates for battery production facilities. The Ministry of Industry's draft clean electricity verification rules would disqualify coal-heavy grid power from green export certification. Pack assemblers in the Eastern Economic Corridor are responding with on-site solar-plus-storage installations and direct power purchase agreements with Thai renewable developers.
Fleet operators in Jakarta and Bangkok are consolidating procurement decisions through centralized tender platforms that bypass traditional distributor networks. Large logistics groups now issue multi-year pack supply contracts with performance guarantees on cycle life and thermal stability. This buyer concentration is visible most acutely in Indonesia, where Gojek and Grab's electric motorcycle conversion programs aggregate sufficient volume to dictate cell format standards to suppliers.
ASEAN EV Battery Pack Market Segmentation
ASEAN pack procurement splits between domestic OEM assembly lines and export-oriented precursor processing, with segment performance tied to Thailand's Eastern Economic Corridor concentration versus Indonesia's nickel-driven cathode integration. Chemistry selection and connection architecture determine whether suppliers serve tropical passenger vehicle fleets or last-mile commercial logistics operators.
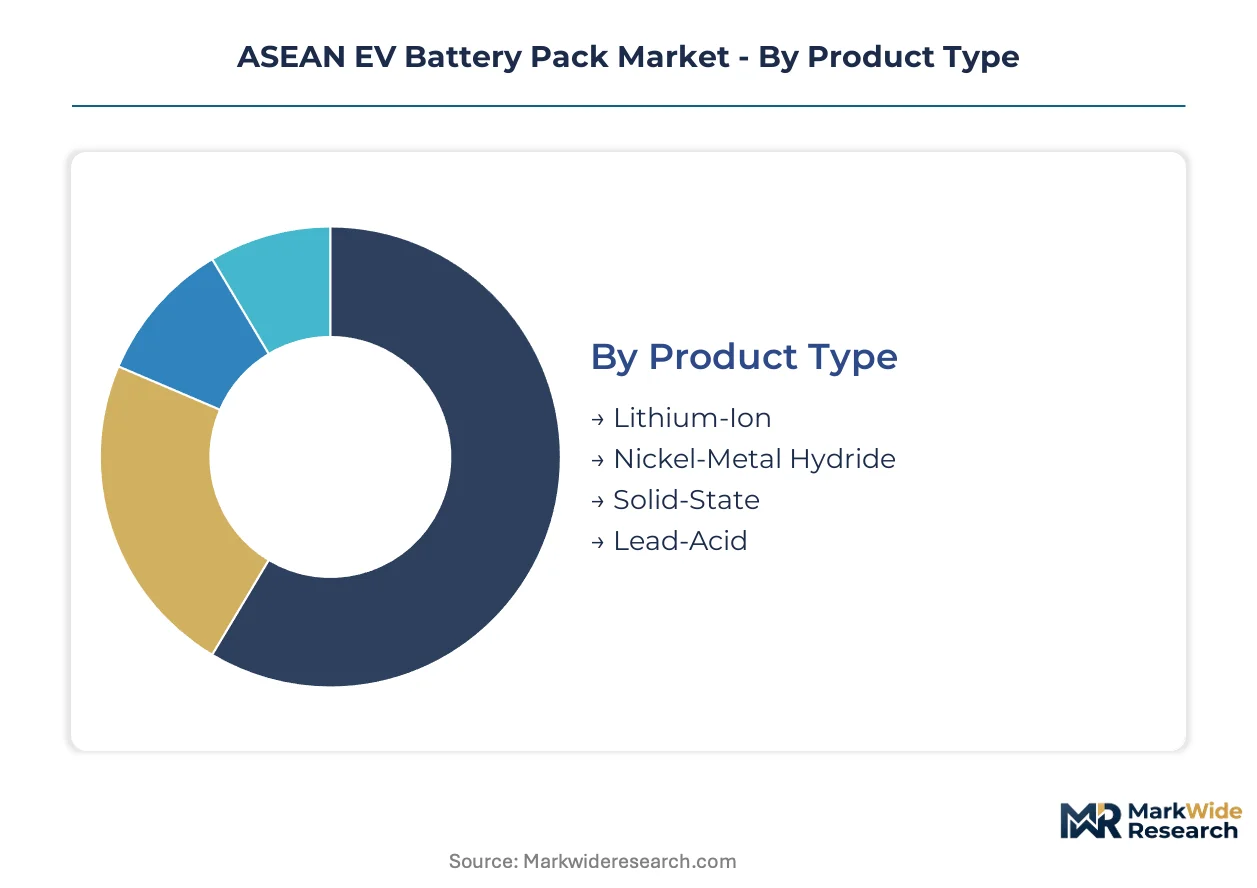
Product Type:
Domestic demand concentrates on lithium-ion configurations serving Thai and Vietnamese OEM contracts, while solid-state development targets premium export positioning through Korean and Japanese pilot line partnerships.
- Lithium-Ion:Dominant cell chemistry employs nickel manganese cobalt and lithium iron phosphate cathodes engineered for 50-150 kWh traction output. Thai passenger vehicle OEMs and Jakarta commercial fleet operators anchor procurement volumes, though lithium carbonate price volatility squeezes margin structures on price-locked contracts.
- Solid-State:Oxide-electrolyte configurations eliminate liquid electrolyte thermal runaway risks for tropical ambient conditions exceeding standard testing baselines. Korean suppliers advance pilot qualification with Southeast Asian OEMs seeking premium positioning through climate durability certification.
- Nickel-Metal Hydride:Legacy chemistry retains niche application in hybrid auxiliary power systems and materials handling equipment where energy density requirements remain modest.
- Lead-Acid:Entry-level two-wheeler and low-speed electric vehicle segments in Indonesia and the Philippines utilize flooded and AGM variants for cost-sensitive replacement cycles.
Lithium-ion holds the largest share; momentum sits with solid-state as Korean and Japanese suppliers advance oxide-electrolyte pilot qualification.
End User:
Cost tier stratification separates premium long-range passenger specifications from economy commercial vehicle procurement concentrated in Jakarta and Bangkok fleet conversions.
- Passenger Vehicles:Thai and Vietnamese OEM assembly lines drive module procurement for 50-100 kWh pack configurations, with VinFast localization creating tier-two assembly opportunities for domestic component suppliers.
- Commercial Vehicles:Last-mile logistics electrification in Jakarta and Bangkok generates concentrated procurement from van and light truck integrators. Gojek and Grab's electric motorcycle programs aggregate sufficient volume to dictate cell format standards.
- Two-Wheelers:Battery swapping pilots in Indonesia and the Philippines decouple vehicle purchase from pack ownership through standardized format agreements.
- Materials Handling Equipment:Warehouse and port electrification across Singapore and Malaysia drives industrial pack demand with duty cycle specifications distinct from road-going applications.
Passenger vehicles command dominant procurement volumes; commercial vehicle electrification climbs the fastest as fleet operators consolidate tender decisions through centralized platforms.
Connection Technology:
Volume distribution favors wired architectures for OEM assembly integration, while margin concentration shifts toward fast charging infrastructure serving commercial fleet depot operations.
- Wired:Permanent high-voltage harness connections dominate OEM pack integration for passenger and commercial vehicle production lines across Thailand and Vietnam.
- Wireless:Inductive charging pilots target premium passenger segments and automated guided vehicle applications in Malaysian industrial zones.
- Fast Charging:150 kW+ DC infrastructure deployment concentrates in Bangkok and Jakarta corridor networks serving commercial fleet depot charging requirements.
- Standard Charging:AC Level 2 configurations retain residential and workplace installation dominance across ASEAN urban centers with grid capacity constraints.
Wired connections retain the largest installed base; fast charging infrastructure gains share fastest as fleet operators mandate depot turnaround specifications.
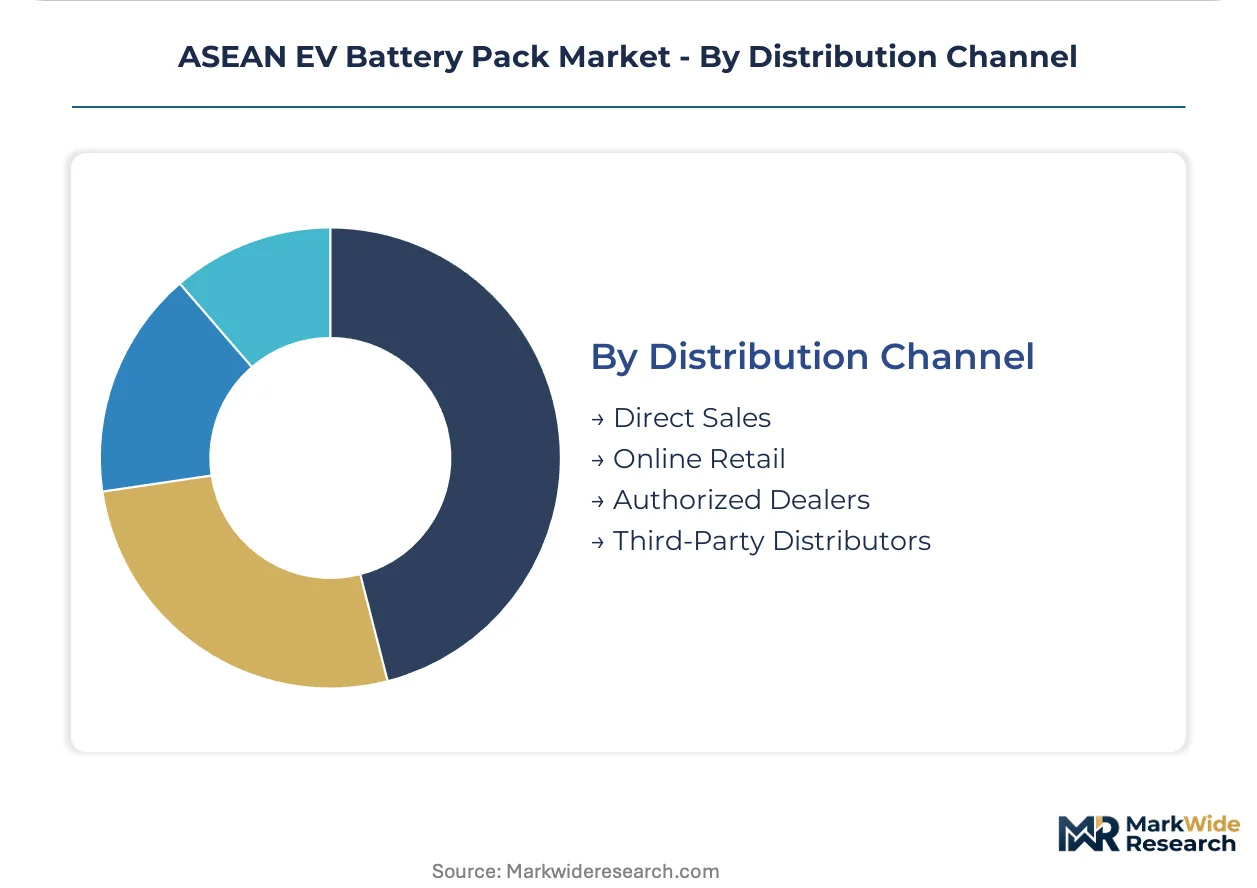
Distribution Channel:
Supply concentration runs through direct OEM contracts for new vehicle pack integration, with aftermarket fragmentation creating channel conflict for replacement and retrofit segments.
- Direct Sales:Tier-one cell suppliers and pack assemblers contract directly with Thai and Vietnamese OEMs for assembly line integration, bypassing distributor markups on volume commitments.
- Online Retail:E-commerce platforms serve replacement pack demand for two-wheeler and low-speed vehicle segments in Indonesia and the Philippines with limited technical support integration.
- Authorized Dealers:OEM-certified service networks handle warranty pack replacements and diagnostic services for passenger vehicle segments across Malaysia and Singapore.
- Third-Party Distributors:Independent channels supply commercial fleet retrofit integrators and materials handling equipment operators with non-warranty pack configurations.
Direct sales capture the largest revenue concentration; online retail expands most quickly as two-wheeler battery swapping decouples ownership from vehicle purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand concentrates pack assembly capacity for export-oriented passenger vehicle production, while Indonesia and Vietnam diverge toward cathode precursor refining and domestic OEM integration respectively.
Thailand
Thailand's Eastern Economic Corridor hosts module assembly lines feeding Thai OEM passenger vehicle contracts. The Board of Investment extends eight-year corporate income tax exemptions for battery production facilities, compressing capital recovery timelines. Rayong and Chonburi provinces concentrate cathode precursor refining capacity alongside final vehicle assembly plants.
Indonesia
Indonesia leverages nickel laterite ore reserves to anchor cathode supply geography for regional pack assemblers. The Ministry of Industry enforces local content thresholds and EV registration incentives that redirect pack sourcing toward domestic precursor producers. Morowali Industrial Park in Central Sulawesi hosts integrated nickel-to-cathode processing complexes serving ASEAN cell manufacturers.
Vietnam
Vietnam's passenger EV segment generates tier-two pack assembly demand as domestic OEM VinFast localizes cell production. The Ministry of Transport coordinates EV-specific registration incentives that compress payback periods for battery investments. Bac Ninh and Hai Phong provinces concentrate electronics manufacturing infrastructure now repurposing for module assembly lines.
Malaysia
Malaysia attracts Korean and Japanese cell suppliers establishing regional distribution hubs through green technology tax allowances. The Ministry of Finance permits 100% capital allowance for energy-efficient equipment imports, reducing landed costs for high-volume cell shipments. Penang and Selangor states host industrial zones transitioning toward battery pack integration for commercial vehicle retrofits.
Singapore
Singapore's materials handling equipment electrification drives industrial pack demand with duty cycle specifications distinct from road-going applications. The Economic Development Board coordinates R&D partnerships for thermal management hardware miniaturization. Jurong Island's chemical processing infrastructure supports electrolyte formulation for specialty cell configurations.
ASEAN EV Battery Pack Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in ASEAN pack procurement. Korean and Chinese cell manufacturers anchor direct OEM contracts through scale advantages in cathode precursor supply, while Japanese suppliers occupy premium positioning via solid-state development partnerships. Three archetypes define competitive positioning: integrated chemistry-to-pack operators, module assembly specialists, and thermal management component vendors. Capacity expansion and strategic partnerships dominate competitive moves as suppliers co-locate near Thailand's vehicle assembly corridors.
Among Korean fabricators, Samsung SDI Co Ltd and LG Energy Solution Ltd exemplify premium-tier positioning through high-nickel cathode development. Contemporary Amperex Technology Co Ltd anchors the integrated archetype with cell-to-pack architecture compressing landed costs for Thai OEM contracts. SK Innovation Co Ltd occupies a position between these vectors, supplying both passenger vehicle and commercial fleet segments across Indonesia and Vietnam.
| Leading Market Players |
|---|
| Samsung SDI Co Ltd |
| SK Innovation Co Ltd |
| Contemporary Amperex Technology Co Ltd (CATL) |
| Ningde E-CON Power System Co Ltd |
| Denso Corporation |
| BYD Company Ltd |
| Panasonic Holdings Corporation |
| Guoxuan High-tech Co Ltd |
| LG Energy Solution Ltd |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cathode precursor inventory buffers in Thai pack assembly lines signal supply-chain shape translating directly into pricing power concentration among integrated Korean and Chinese cell suppliers. This lead-time band compresses negotiation leverage for ASEAN module assemblers locked into long-term OEM contracts with fixed lithium carbonate escalators.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one cell suppliers and Thai OEM assembly lines, insulating volume commitments from spot lithium carbonate volatility while compressing margins on price-locked agreements. Pricing stratifies across premium high-nickel cathode tiers, standard LFP configurations for economy passenger vehicles, and economy lead-acid replacements for two-wheeler segments. Cost compression in standard-tier packs is intensifying because Indonesian nickel ore export restrictions force Thai assemblers to absorb precursor premiums. Fleet operators in Jakarta and Bangkok exhibit highest price sensitivity through centralized tender platforms, while premium SUV OEMs in Thailand demonstrate lowest sensitivity to cell-grade cost fluctuations.
Supply Chain Analysis
Indonesia anchors laterite ore processing and cathode precursor refining, China dominates cell manufacturing and LFP chemistry output, and South Korea supplies high-nickel cathode materials and solid-state pilot lines to ASEAN pack assemblers. The supply chain draws from lithium carbonate brine operations, nickel laterite smelting, and copper foil rolling as critical inputs. Single-source vulnerability concentrates in Indonesian nickel processing, where export restriction policies create chokepoint exposure for regional high-nickel cathode availability. Distribution runs through direct OEM contracts for new vehicle integration, with aftermarket channels fragmenting across online retail for two-wheeler replacement and authorized dealer networks for warranty service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation through centralized tender platforms in Jakarta and Bangkok has shifted buyer power toward volume aggregators, compressing supplier margin structures across ASEAN pack assembly tiers.
For Market Incumbents: Compound cathode precursor refining capacity in Thailand's Eastern Economic Corridor to capture local content incentives and defend against Indonesian nickel supply disruption. Expand cell-to-pack architecture adoption to eliminate module assembly steps and preserve margin structure against price-locked OEM contract pressure. Secure renewable energy verification under Thailand's draft clean electricity rules to maintain green export certification eligibility. For New Entrants and Emerging Players: Anchor in Vietnam's tier-two pack assembly segment surrounding VinFast cell localization, where domestic component supplier qualification creates white-space opportunity. Target battery swapping infrastructure for Indonesian and Philippine two-wheeler fleets, where standardized pack formats decouple vehicle purchase from battery ownership and bypass entrenched OEM direct sales channels. Pursue commercial fleet retrofit integrators in Malaysia's Penang and Selangor industrial zones as initial beachhead. For Investors and Strategic Acquirers: Long-term, this sits as a cathode chemistry transition play because ASEAN's shift from LFP-dominated entry vehicles toward high-nickel and solid-state premium configurations will redistribute value capture toward precursor specialists and electrolyte innovators. Acquisition targets should concentrate on Vietnamese module assembly specialists with VinFast qualification and Thai thermal management component vendors with tropical climate certification. Monitor Indonesia's nickel ore export policy enforcement as the critical inflection signal for regional cathode supply geography.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | CATL's integrated designs eliminate module housings, reducing landed costs for Thai OEM contracts. |
| Cathode Precursor Refining Expansion | Thailand's Eastern Economic Corridor concentrates capacity to serve regional high-nickel chemistry demand. |
| Battery Swapping Infrastructure Deployment | Gojek and Grab's electric motorcycle programs in Indonesia aggregate volume to dictate cell format standards. |
| Solid-State Pilot Line Qualification | Korean suppliers advance oxide-electrolyte partnerships with Southeast Asian OEMs seeking tropical durability certification. |
| Renewable Energy Sourcing Mandate Compliance | Thailand's draft clean electricity verification rules drive on-site solar-plus-storage installations for pack assemblers. |
Research Methodology
Desk research of customs trade data, ASEAN national standards body filings, and vehicle production databases preceded structured interviews with OEM platform engineers, tier-one cell supplier procurement leads, commercial fleet operators, and thermal management component vendors. Primary fieldwork across Thailand's Eastern Economic Corridor, Indonesia's Morowali Industrial Park, and Vietnam's Bac Ninh manufacturing zones validated secondary findings on capacity expansion timelines and local content threshold compliance. Bottom-up pack procurement volume estimates triangulated against top-down EV registration projections from national transport ministries.
Variance decomposition across chemistry selection, vehicle class adoption curves, and connection technology penetration shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include cell chemistry type, end-use application, and regional production cluster concentration. CAGRs derived from unit economics trajectories incorporating lithium carbonate price band sensitivity and nickel supply restriction scenarios. Industry-specific forecast inputs encompassed Thai Board of Investment incentive utilization rates and Indonesian Ministry of Industry local content enforcement patterns.
Underlying assumptions cover sustained EV tax incentive continuity across Thailand, Indonesia, and Vietnam, with deviation risk concentrated in lithium carbonate supply expansion delays and ASEAN member state safety standard harmonization failures. Forecasts reflect these documented assumptions without forward-year precision. Recalibration cycles align with material shifts in nickel export policy enforcement and solid-state pilot line qualification outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
EV Eaxle Market