
 Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market | 2026-2036
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market Intelligence
The consolidation of vehicle functions into integrated, software-defined control units is narrowing the performance gap between traditional golf carts and street-legal low-speed vehicles. Club Car leverages its established brand and extensive dealer network to secure premium fleet contracts in North America. Meanwhile, E-Z-GO competes on manufacturing scale and its proprietary AC drive system technology. Yamaha differentiates through a reputation for reliability derived from its broader powersports and engine manufacturing expertise.
Golf carts and neighborhood electric vehicles (NEVs) are compact, low-speed electric vehicles designed for short-distance transport. Defined by speed limits under 25 mph and powered by 48V to 72V battery packs, they serve recreational and utility roles. Electric propulsion systems command the market, while gasoline models are relegated to niche heavy-duty utility applications. Low-speed vehicles for campus transportation and commercial fleets represent the fastest-growing application, expanding beyond the traditional recreational use case.
Vehicle standards are governed by distinct national regulations, including the U.S. NHTSA's Federal Motor Vehicle Safety Standard 500 for low-speed vehicles. Manufacturers must also comply with Europe's CE marking directives for machinery safety and China's specific GB standards for electric vehicle components. This patchwork of regional street-legal requirements versus off-road classifications remains a central strategic challenge for global product development.
Market Dynamics
The fundamental market dynamic is the industry-wide powertrain transition from lead-acid to lithium-ion battery systems. This technological shift improves vehicle range, reduces maintenance, and extends operational lifespan, directly enabling expansion into more demanding commercial and fleet applications beyond traditional recreational use.
Growth Catalysts
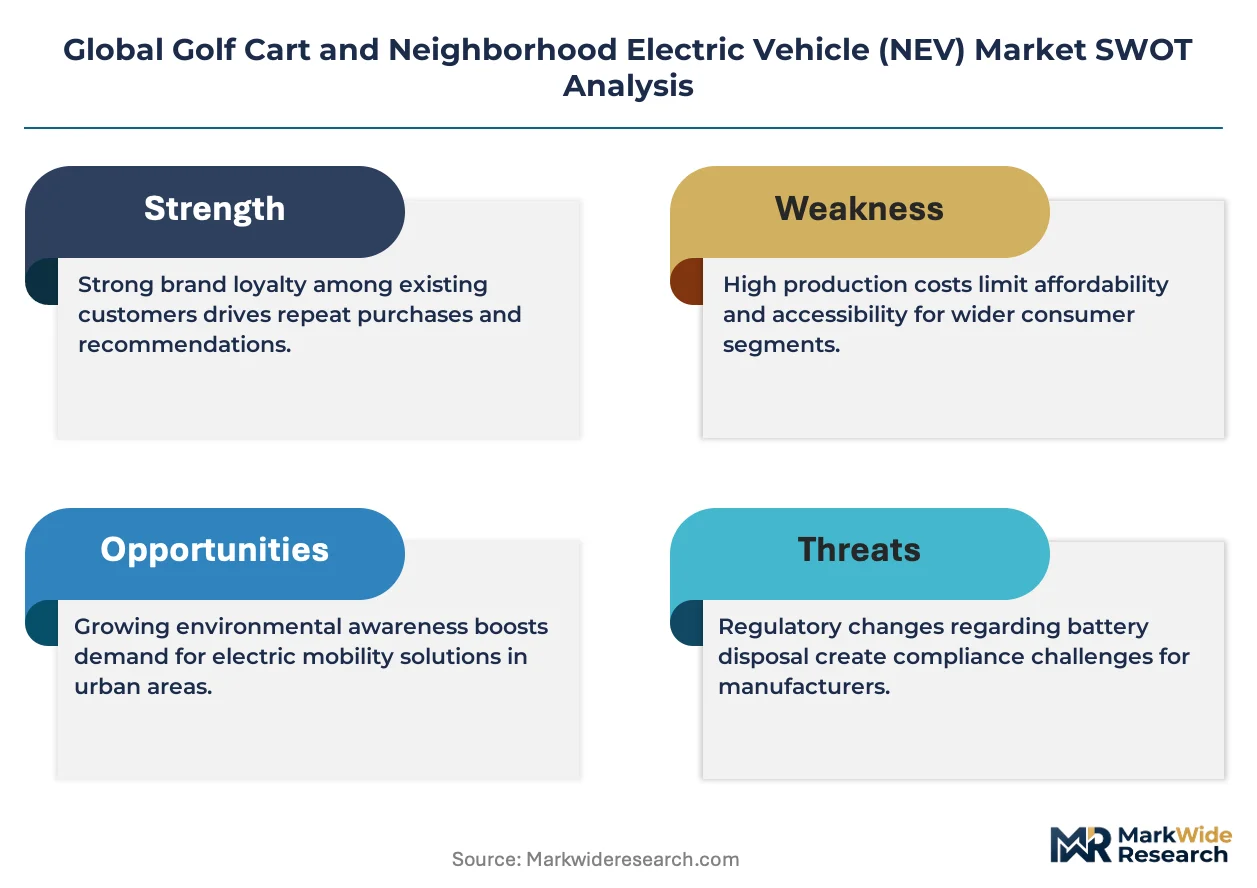
- Lithium-Ion Battery Adoption:The shift to lithium-ion power systems provides significant improvements in vehicle performance, including faster charging, longer range, and a higher power-to-weight ratio, which is critical for commercial fleet operators seeking maximum uptime.
- Expanding Commercial Applications:Demand from large-scale hospitality operations, university campuses, and industrial sites provides a consistent commercial revenue stream, diversifying the market away from its reliance on seasonal, recreational golf course sales.
- Master-Planned Community Growth:The development of large, self-contained residential communities, particularly in the United States, creates captive markets where NEVs are a primary mode of internal transportation, supported by dedicated path infrastructure.
Market Restraints
- Regulatory Fragmentation:A patchwork of national and local regulations, such as the U.S. NHTSA's FMVSS 500 versus Europe's CE marking directives, creates significant compliance costs and design challenges for manufacturers aiming for a single global platform.
- Upfront Cost Premium:Vehicles equipped with advanced lithium-ion battery systems carry a higher initial purchase price compared to traditional lead-acid models, posing a barrier for price-sensitive individual buyers and smaller commercial operators.
- Substitution from Utility Vehicles:In certain heavy-duty commercial and agricultural settings, gasoline or diesel-powered utility task vehicles (UTVs) offer superior payload capacity and off-road capability, presenting a direct substitution threat.
Strategic Opportunities
- Last-Mile Delivery Services:The compact size and zero-emission profile of NEVs make them ideal for deployment in dense urban centers for last-mile logistics and package delivery, an underpenetrated application with significant volume potential.
- Telematics and Fleet Management Integration:Embedding advanced telematics and software-as-a-service (SaaS) fleet management tools into vehicles offers new recurring revenue streams and provides commercial customers with valuable operational data on usage and maintenance.
- Incentives for Urban Mobility:Government incentives and urban planning policies in certain European cities that restrict passenger car access create a regulatory tailwind for street-legal low-speed vehicles as an alternative mode of transport.
Industry Challenges
- Battery Supply Chain Complexity:Securing a stable and cost-effective supply of automotive-grade lithium-ion battery cells and associated battery management system (BMS) components presents a significant operational challenge for vehicle manufacturers.
- Service Technician Skill Gaps:The transition to advanced electric powertrains and software-defined controls requires a new set of diagnostic and repair skills, creating a training gap for technicians at dealerships and service centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market |
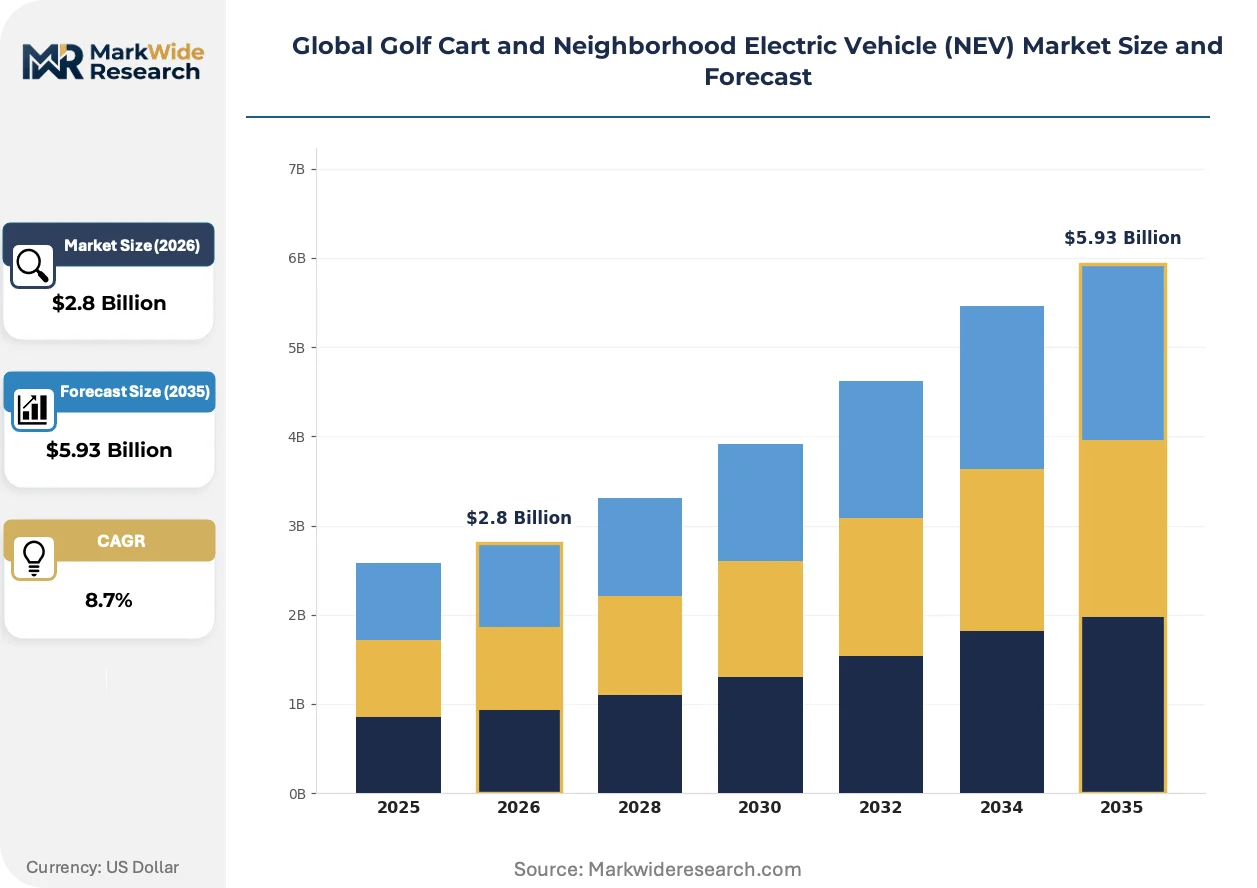
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Golf Carts, Low-Speed Vehicles, Utility Vehicles, Personal Transporters Propulsion: Electric, Gasoline, Hybrid, Solar Powered Application: Recreational, Commercial, Hospitality, Campus Transportation, Industrial Customer Type: Resort Operators, Campus Managers, Industrial Facilities, Fleet Services |
| Companies Covered | Lvtong, Kandi, Club Car, Marshell, Excar, E-Z-GO, Evolution, Massimo Group, Yamaha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market Strategic Shifts & Innovations
The convergence of software, connectivity, and electrification is fundamentally altering vehicle architecture and capability. This integration blurs the lines between recreational golf carts and street-legal NEVs, enabling new business models centered on fleet management and user experience features delivered via software.
Vehicle control architecture is a key area of innovation, managing everything from motor performance to battery health. Commercial fleet operators and premium recreational buyers are the earliest adopters, seeking enhanced performance, safety, and remote diagnostic capabilities. The market is migrating from discrete, hardware-based controllers for each vehicle subsystem to unified, software-defined electronic control units (ECUs) that govern the entire vehicle.
Regulatory frameworks like China's GB standards for electric vehicle components impose strict requirements on battery safety, thermal management, and electrical systems. This directly influences component sourcing and vehicle design for any manufacturer intending to compete in the Chinese market. The NEV segment is most affected, as compliance is mandatory for market access and impacts engineering decisions from the earliest stages of product development.
A notable shift in acquisition models is occurring, moving from traditional outright ownership to more flexible leasing, subscription, and fleet-as-a-service arrangements. This change disrupts the conventional dealer sales channel, empowering fleet management companies that offer comprehensive packages including maintenance and charging infrastructure. This pattern is most pronounced within large corporate campuses in Germany and resort fleets across North America.
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market Segmentation
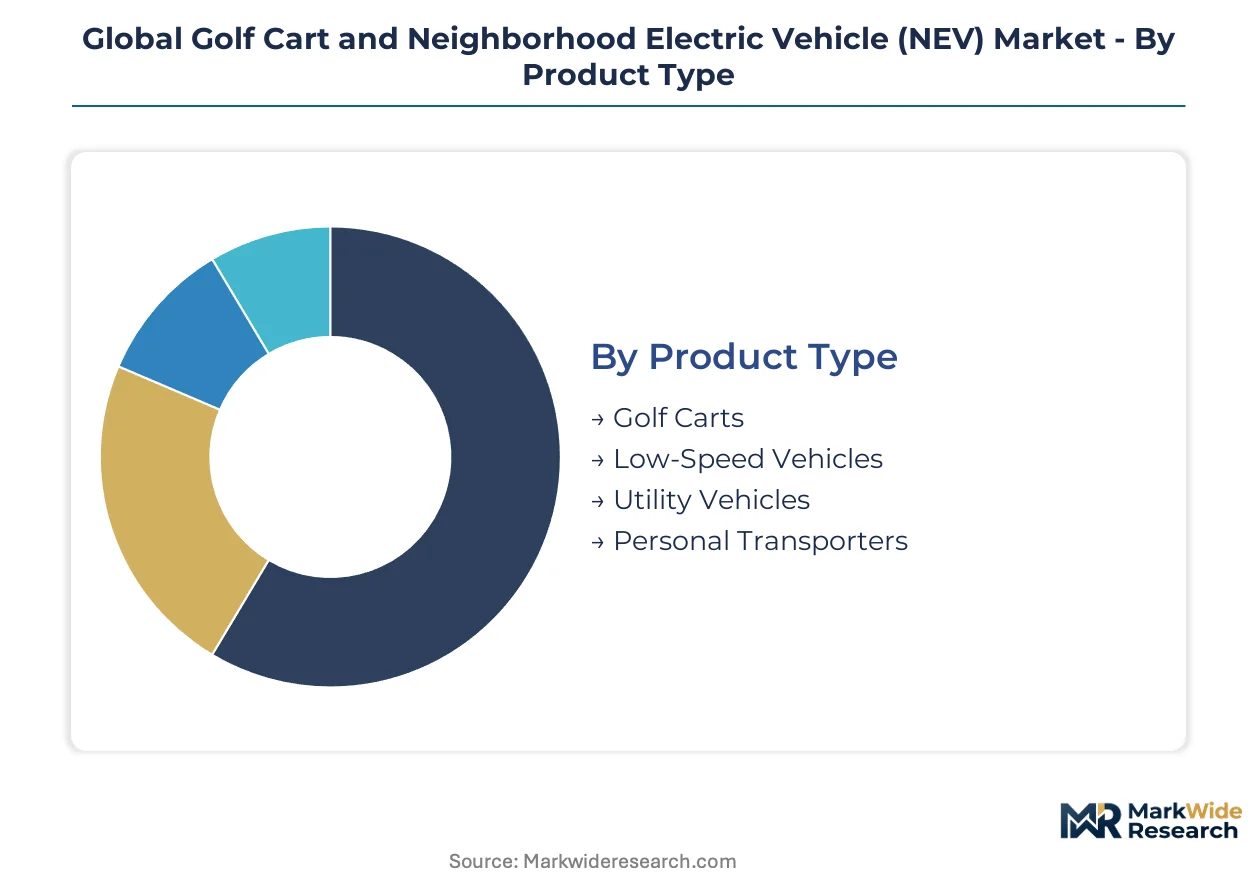
Segmentation clarifies the distinct functional requirements and operational lifecycles across the golf cart and NEV market. Understanding these diverse segments allows manufacturers to tailor product development and service offerings. This granular view reveals where specialized engineering and after-sales support are most critical for market success.
Product Type:
The varying complexity and usage patterns across product types directly influence the intensity of required after-sales service and maintenance programs.
- Golf Carts:Primarily designed for recreational use on golf courses, these vehicles prioritize ease of operation and passenger comfort.
- Low-Speed Vehicles:These are street-legal vehicles designed for public road use with speed limits under 25 mph, often equipped with safety features like seatbelts and headlights. Demand concentrates in master-planned communities across the United States, driven by the need for compliant internal transportation.
- Utility Vehicles:Engineered for heavy-duty tasks, these vehicles often feature larger cargo beds and towing capabilities for industrial and commercial sites. Demand is strong in specialized industrial sites in Germany, where robust payload capacity is essential for logistics.
- Personal Transporters:Compact and often single-user, these vehicles serve specific niche applications like security patrols or large facility internal transport.
By volume, Golf Carts lead the market. By growth pace, Low-Speed Vehicles are ahead.
Propulsion:
The propulsion technology directly impacts the vehicle's initial acquisition cost and its long-term operational expenditures across different performance tiers.
- Electric:These vehicles rely on battery packs and electric motors, offering zero-emission operation and lower running costs. Demand is concentrating in campus transportation applications, where environmental mandates and quiet operation are critical.
- Gasoline:These models use internal combustion engines, typically found in niche heavy-duty utility applications requiring high power output.
- Hybrid:Combining an electric motor with a small internal combustion engine, these systems offer extended range and flexible refueling options. Demand is present in specific commercial fleets requiring longer operational periods without frequent recharging infrastructure.
- Solar Powered:These vehicles integrate photovoltaic panels for supplemental battery charging, extending range in sunny climates for specific applications.
Electric propulsion dominates market share due to widespread adoption and performance benefits. Hybrid systems exhibit rapid expansion as operators seek extended range capabilities.
Application:
The volume of vehicles deployed within each application segment varies significantly, influencing manufacturing scale and distribution channels.
- Recreational:The traditional use case for golf carts on courses and personal mobility within private communities.
- Commercial:This broad segment includes various business uses beyond traditional golf, such as last-mile delivery and general utility tasks in urban centers. Demand is expanding rapidly in dense urban centers for last-mile logistics, driven by zero-emission mandates.
- Hospitality:Vehicles deployed at resorts, hotels, and theme parks for guest transport and operational duties.
- Campus Transportation:Dedicated fleets for universities, corporate parks, and large institutional facilities, providing efficient internal mobility. Demand is particularly strong in large corporate campuses in Germany, where efficient internal movement is a priority.
- Industrial:Heavy-duty applications within manufacturing plants, warehouses, and specialized industrial sites for material handling.
Commercial applications are driving overall market growth due to their diverse utility requirements. Recreational applications maintain a stable base demand.
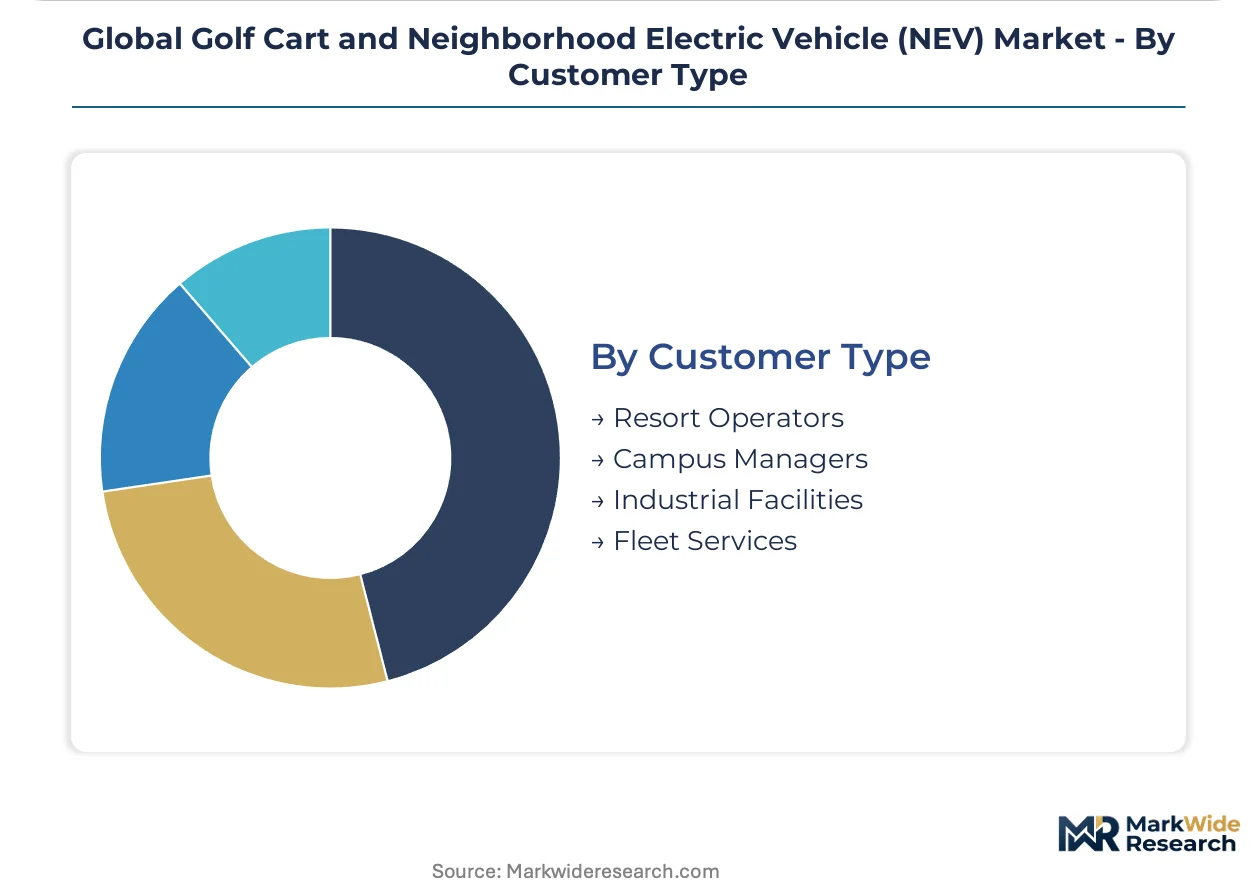
Customer Type:
Each customer type exhibits distinct purchasing behaviors and operational needs, shaping product features and service expectations.
- Resort Operators:Businesses managing hospitality properties that utilize golf carts and NEVs for guest transport and property maintenance.
- Campus Managers:Administrators responsible for transportation logistics within universities, corporate parks, and large institutional grounds. Demand is consistent from university campuses seeking efficient and environmentally friendly internal transport solutions.
- Industrial Facilities:Manufacturing plants and warehouses requiring utility vehicles for material handling and personnel movement.
- Fleet Services:Companies specializing in managing and leasing vehicle fleets to various end-users, offering comprehensive maintenance and operational support. Demand is pronounced in North America, where flexible leasing models are gaining traction among commercial clients.
Fleet Services holds significant future potential as flexible acquisition models proliferate. Resort Operators represent a foundational and stable customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes like master-planned communities and large corporate campuses drive significant demand for golf carts and NEVs globally. These specialized buyers seek efficient, low-speed transportation solutions for internal mobility and last-mile logistics. The market's geographic concentration reflects these specific application needs and regional regulatory frameworks.
United States
Demand concentrates in master-planned communities across the United States, where NEVs are a primary mode for compliant internal transportation. The U.S. NHTSA's Federal Motor Vehicle Safety Standard 500 specifically regulates low-speed vehicles for public road use. In Florida's rapidly expanding residential developments, new communities often integrate dedicated NEV path infrastructure to support resident mobility and accessibility.
Germany
Specialized industrial sites in Germany require robust utility vehicles with strong payload capacity for internal logistics and material handling. Europe's CE marking directives ensure machinery safety and operational compliance for these commercial applications. Large corporate campuses near Stuttgart are increasingly adopting NEV fleets for efficient internal movement, aligning with sustainability goals.
China
China's expanding urban centers present significant opportunities for last-mile delivery services using compact NEVs. The country's GB standards impose strict requirements on electric vehicle components, including battery safety and thermal management systems. In the Yangtze River Delta, major cities are actively promoting zero-emission transport options for urban logistics, driving NEV adoption.
Japan
Japanese hospitality operations and university campuses are increasing their NEV fleet deployments for guest transport and operational duties. METI guidelines influence vehicle design, safety standards, and energy efficiency for electric mobility solutions. Near Tokyo, resort operators are investing in quiet, electric personal transporters to enhance guest experience within their expansive properties.
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market Key Industry Players
Channel-controlling players compete with product-specialist players in the golf cart and NEV market, creating a dynamic competitive landscape. The market structure exhibits a blend of established brands with extensive dealer networks and agile manufacturers focusing on specific technology niches or application areas. Strategic archetypes include diversified powersports conglomerates, dedicated electric vehicle manufacturers, and specialized utility vehicle producers. Competitive moves center on manufacturing scale advantages, securing premium fleet contracts, and expanding into new commercial applications.
Within the established brand tier, Club Car exemplifies a strong North American presence, leveraging its extensive dealer network to secure premium fleet contracts and service agreements. Yamaha, a Japanese conglomerate, occupies a position rooted in broader powersports and engine manufacturing expertise, lending a reputation for reliability across its diverse product portfolio. E-Z-GO, another prominent player, competes effectively on manufacturing scale and its proprietary AC drive system technology, which differentiates its offerings for various commercial and recreational uses. These companies represent different strategic approaches to market penetration and customer retention within the industry, emphasizing brand loyalty and technological innovation.
| Leading Market Players |
|---|
| Lvtong |
| Kandi |
| Club Car |
| Marshell |
| Excar |
| E-Z-GO |
| Evolution |
| Massimo Group |
| Yamaha |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery cost volatility, influenced by global raw material markets, determines both vehicle pricing tier spreads and the geographic shape of the supply chain. This extends from premium commercial fleets valuing uptime to price-sensitive individual buyers.
Pricing Analysis
Cost-plus contract patterns, often indexed to battery cell prices, govern large fleet procurements. The dominant pricing structure across the market is value-based, differentiating by performance tiers and after-sales service bundles. Price differentiation stems from battery chemistry (lead-acid vs. lithium-ion) and brand premium associated with reliability. Pricing pressure stems from the higher upfront cost of lithium-ion systems, impacting smaller commercial operators. Individual buyers exhibit the most price sensitivity, while large institutional fleet managers prioritize total cost of ownership.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support component procurement for vehicle manufacturers. Geographic supply concentration centers on China for lithium-ion cells and key electronic components, alongside Germany for specialized industrial vehicle parts. Raw material dependencies include lithium, cobalt, and nickel for advanced battery chemistries, plus semiconductors for integrated control units. Single-source vulnerability for specific battery management systems presents a structural risk. Distribution runs through established dealer networks for recreational and smaller commercial sales, complemented by direct-to-fleet sales for large institutional clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a defensive moat, primarily due to regulatory entrenchment around street-legal vehicle classifications and safety standards. These established frameworks create significant barriers to entry for new players.
For Market Incumbents:
Harden existing dealer networks through enhanced service technician training for advanced electric powertrains. Invest in proprietary software-defined control units to differentiate vehicle performance and remote diagnostic capabilities. This defends against emerging EV manufacturers focused solely on low-cost alternatives. Expand capacity in North America for lithium-ion battery integration to mitigate supply chain complexities and reduce lead times.
For New Entrants and Emerging Players:
Pursue underpenetrated commercial segments like last-mile delivery services in dense urban centers. Target specialized utility applications requiring custom payload configurations in Europe's industrial sites. A compelling go-to-market angle involves offering comprehensive fleet-as-a-service packages, bundling vehicles with telematics, maintenance, and charging infrastructure. Focus on regions with strong government incentives for urban low-emission transport.
For Investors and Strategic Acquirers:
Specialized component manufacturers, particularly those in battery management systems and advanced motor controllers, represent attractive acquisition targets. The market demonstrates long-term viability, driven by the sustained transition to electric powertrains and expanding commercial applications. A signal to watch is the standardization of charging infrastructure protocols, which would accelerate broader NEV adoption. Strategic acquisitions should prioritize companies with proven intellectual property in electrification or fleet management software.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enhances vehicle functionality and enables new business models through over-the-air updates. |
| Battery Supply Agreement | Secures stable, cost-effective access to critical lithium-ion battery cells for production. |
| Charging Infrastructure Partnership | Expands charging accessibility for commercial fleets and private users, removing a key barrier. |
| Fleet Management SaaS Integration | Creates recurring revenue streams and provides operational insights for commercial customers. |
| CE Marking Pathway | Ensures product compliance and market access for commercial vehicles across European markets. |
Research Approach
Initial hypotheses were tested against primary input from fleet managers, golf course operators, master-planned community developers, and battery suppliers, then refined through iterative analysis. This involved combining in-depth interviews with secondary validation from sources like NHTSA publications, CE marking guidelines, and corporate sustainability reports. Bottom-up data collection was triangulated with top-down market sizing to ensure robust estimates.
Demand-supply balance modeling formed the core of the quantitative forecast framework across the analysis window. Segmentation dimensions included product type, propulsion, application, customer type, and battery chemistry. Compound annual growth rates were derived from historical trends, technology adoption rates, and application expansion. Key industry-specific forecast inputs included lithium-ion battery cost curves and evolving urban planning policies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging EV manufacturers or large technology conglomerates would shift outcomes. Forecasts reflect assumptions regarding technological advancements and market dynamics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Bus Pantograph Charger Market