
 Solar Powered Electric Vehicle Market | 2026-2036
Solar Powered Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Electric Vehicle Market Analytics
Commercial fleet procurement is realigning toward solar-augmented light commercial vehicles as logistics operators seek to reduce grid dependency during daytime routes. Lightyear leverages advanced photovoltaic integration to extend single-charge range for premium passenger applications. Toyota Motor Corporation anchors its strategy in hybrid solar-electric architectures that bridge current infrastructure gaps. Sono Motors specializes in retrofit-friendly solar bodywork for existing commercial van platforms.
A solar powered electric vehicle integrates photovoltaic surfaces into body panels, roof assemblies, or deployable arrays to supplement battery charge through direct solar-to-electric conversion, typically achieving 15-45 km of additional daily range under optimal irradiance. The primary purpose is to reduce charging frequency, lower lifetime energy costs, and extend operational autonomy for vehicles with predictable daytime utilization patterns. Passenger cars dominate current deployment volume, though commercial vehicles represent the fastest-expanding segment as fleet managers prioritize total cost of ownership over upfront capital outlay. Photovoltaic cells remain the leading solar technology category, while bifacial modules are gaining traction in high-sunlight markets due to their ability to capture reflected irradiance from road surfaces.
The EPA tailpipe emissions standards and the EU Green Deal's transport decarbonization mandates are compelling automakers to certify solar-assisted range extensions as qualifying zero-emission miles. NHTSA safety protocols for integrated solar surfaces are shaping crash-test requirements and insurance classification frameworks. Stakeholders must monitor how regulatory credit treatment for solar-derived kilometers evolves across jurisdictions, as this will determine whether solar integration becomes standard equipment or remains a premium configuration.
Market Dynamics
Fleet operators in logistics and last-mile delivery are recalibrating procurement criteria to prioritize solar-augmented range autonomy, compressing total cost of ownership calculations against upfront capital thresholds.
Growth Catalysts
- EU Green Deal transport mandates:The EU Green Deal's decarbonization framework compels OEMs to certify solar-assisted kilometers as qualifying zero-emission miles, accelerating integration timelines for light commercial vehicles.
- Bifacial module adoption:Bifacial photovoltaic technology captures reflected irradiance from road surfaces, extending effective daily range in high-sunlight corridors where fleet density concentrates.
- Last-mile delivery electrification:Urban logistics operators with predictable daytime routes leverage solar supplementation to reduce grid dependency during peak electricity pricing windows.
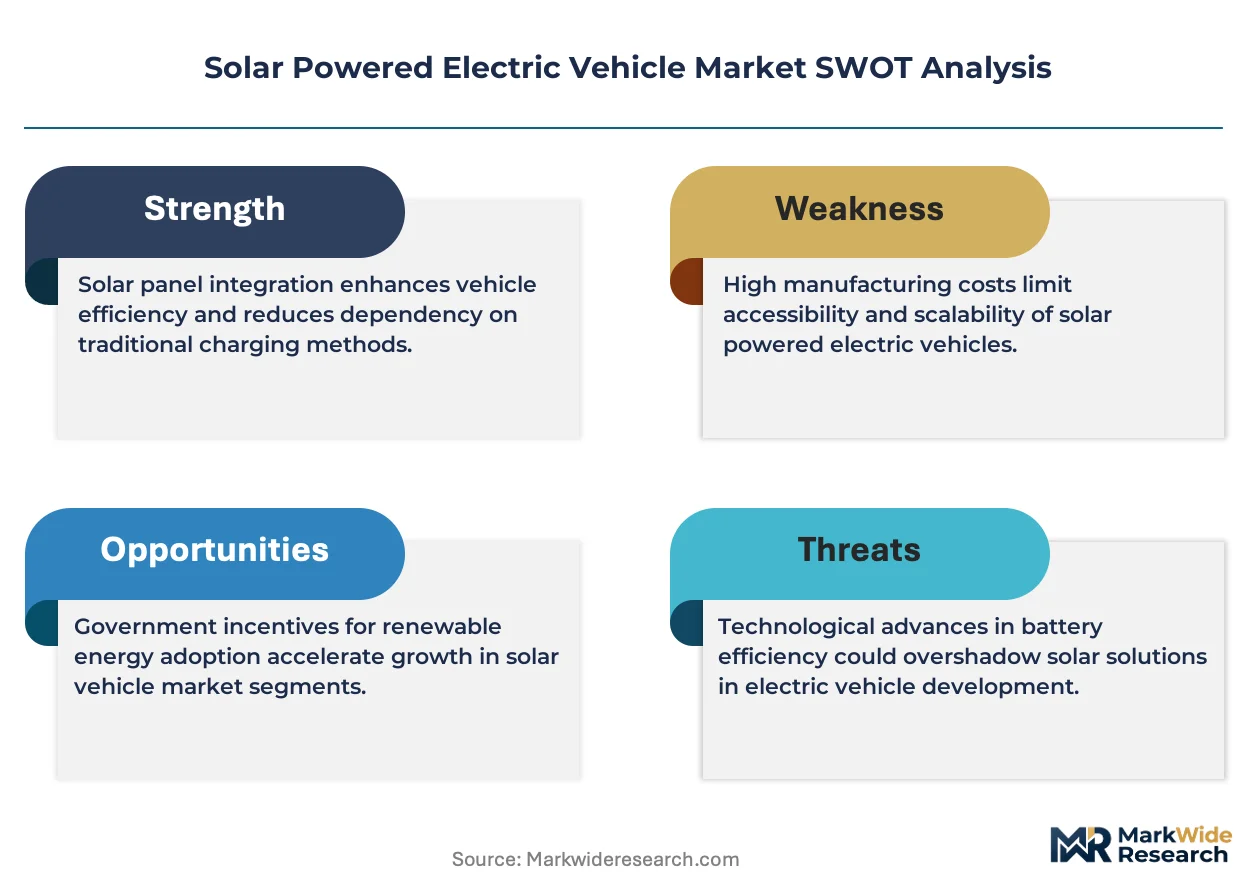
Market Restraints
- Silicon wafer cost volatility:Polysilicon price fluctuations transmit directly to solar body panel manufacturing, compressing margin structures for vehicle-integrated photovoltaics.
- Photovoltaic conversion ceiling:Current silicon cell efficiencies plateau below 26% in automotive form factors, constraining meaningful range extension without substantial surface area expansion.
- NHTSA crash-test recertification:Integrated solar surfaces trigger extended safety validation protocols, elongating model launch timelines and insurance classification disputes.
Strategic Opportunities
- Retrofit solar bodywork:Aftermarket solar panel integration for existing commercial van fleets opens addressable volume without requiring platform redesign.
- India's PLI scheme for solar manufacturing:Production-linked incentives for photovoltaic cell manufacturing could localize supply chains for solar-integrated vehicle exports.
- Vehicle-to-grid solar arbitrage:Bidirectional charging infrastructure enables fleet operators to monetize excess solar generation during peak grid pricing periods.
Industry Challenges
- Photovoltaic thermal management:Automotive body panel temperatures degrade cell efficiency, requiring active cooling systems that consume auxiliary power.
- Standardized solar range certification:Absence of harmonized test protocols across EPA, KBA, and MIIT regimes complicates cross-border vehicle homologation.
- Automotive-grade encapsulation:Long-term weatherproofing of solar surfaces against stone chip and chemical exposure remains unresolved at commercial vehicle price points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Electric Vehicle Market |
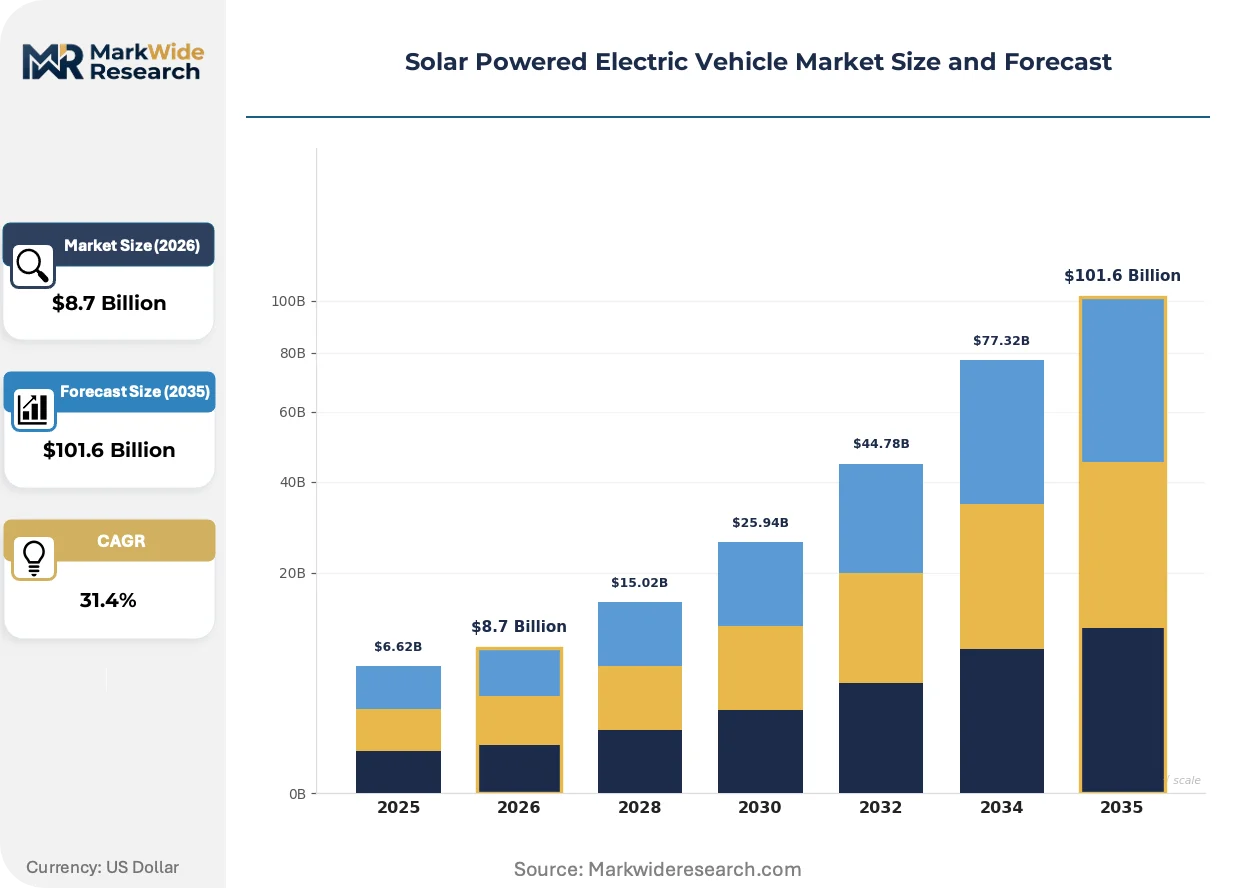
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, Buses, Motorcycles Solar Technology: Photovoltaic Cells, Thin-Film Technology, Concentrated Solar Power, Bifacial Modules Power Capacity: Low Power, Medium Power, High Power, Ultra-High Power Charging Method: Solar Charging Stations, Home Solar Systems, Public Charging Networks, Hybrid Charging |
| Companies Covered | Lightyear, Sono Motors, Aptera, Toyota Motor Corporation, Ford Motor Company, Volkswagen, Fisker, Hyundai, Mercedes-Benz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Electric Vehicle Market Evolving Landscape
Photovoltaic integration is migrating from premium passenger showcases to commercial vehicle workhorses, rewiring how fleet managers evaluate capital deployment against operational autonomy.
Perovskite-silicon tandem cells are integrating into prototype solar roof assemblies, stacking light-harvesting layers to push conversion efficiency toward 30% in automotive footprints. German van manufacturers are piloting these stacks on refrigerated delivery vehicles where roof real estate supports meaningful daily range extension. The technology is integrating range calculations directly into route optimization software, collapsing the boundary between energy generation and logistics planning.
The EPA tailpipe emissions standards and California's Advanced Clean Trucks regulation are tightening certification requirements for zero-emission vehicle credit eligibility. Solar-derived kilometers now qualify toward compliance thresholds in proposed rulemaking, forcing OEMs to instrument and verify solar contribution metrics. Light commercial vehicles in the United States face the most immediate pressure to document solar-assisted range for regulatory credit accounting.
Fleet procurement committees are elevating total cost of ownership models over sticker price comparisons, weighting lifetime charging cost avoidance against solar panel premiums. Third-party fleet management platforms are embedding solar yield forecasting into vehicle selection algorithms, replacing traditional fuel economy benchmarking. This behavioral pivot is most pronounced in Germany and the Netherlands where electricity price volatility and carbon pricing mechanisms amplify solar autonomy value.
Solar Powered Electric Vehicle Market Segmentation
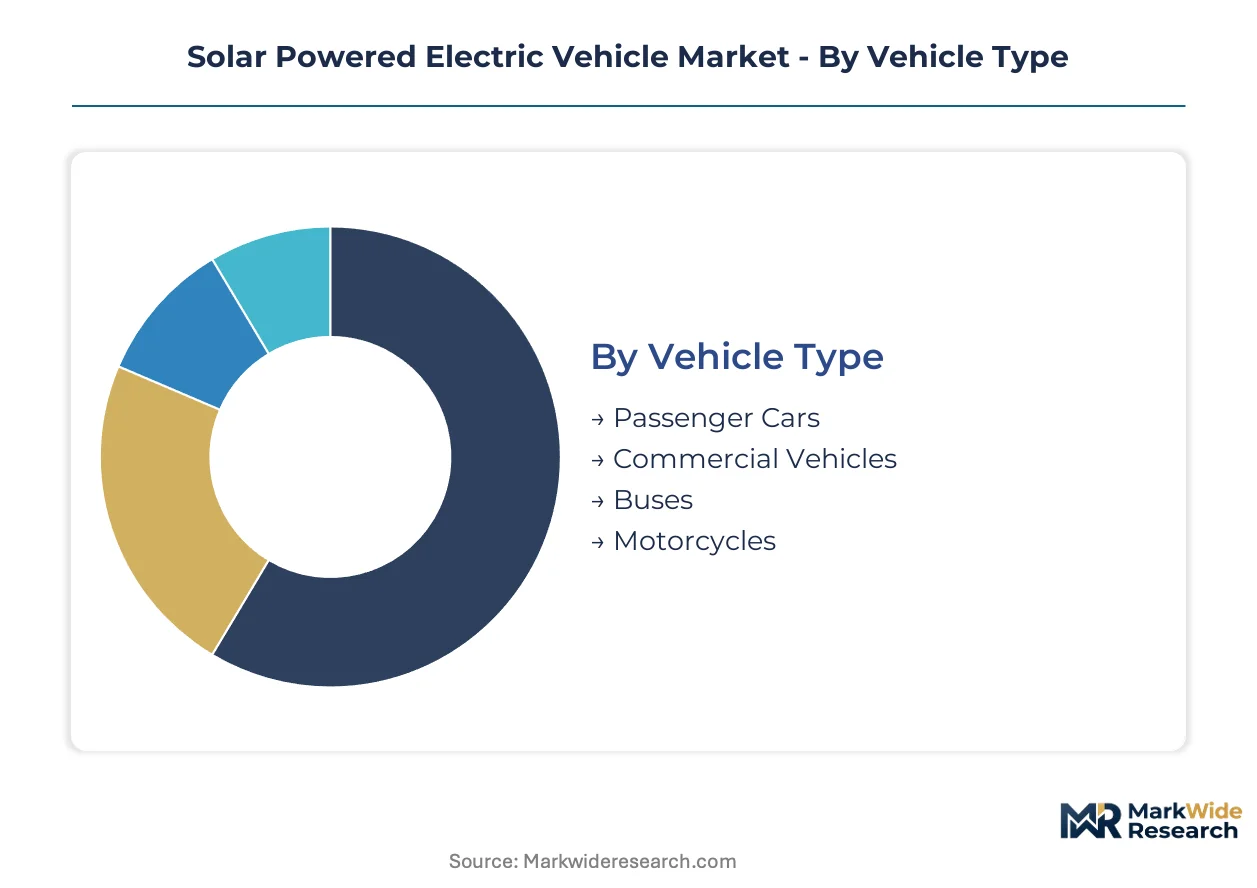
Segmentation in the solar powered electric vehicle market reveals how photovoltaic integration depth varies by vehicle architecture and operational profile. Fleet managers and OEMs use these categories to match solar augmentation levels against route predictability, surface area availability, and total cost of ownership targets.
Vehicle Type:
Standalone solar bodywork dominates commercial applications where roof and hood real estate supports meaningful range extension, while embedded photovoltaic surfaces concentrate in premium passenger segments seeking aesthetic integration.
- Passenger Cars:Photovoltaic cells integrate into roof assemblies and hood panels, prioritizing aesthetic continuity over maximum surface area. German and Dutch premium OEMs concentrate development here as regulatory credit treatment for solar-derived kilometers tightens under EU Green Deal transport mandates.
- Commercial Vehicles:Light vans and delivery trucks deploy expansive roof-mounted arrays for predictable daytime route supplementation. Last-mile logistics operators in the United States and Germany prioritize these configurations to compress lifetime charging costs against upfront solar premiums.
- Buses:Roof surface area supports substantial photovoltaic deployment, though thermal management challenges degrade cell efficiency during peak irradiance hours.
- Motorcycles:Limited surface area constrains meaningful range extension; thin-film integration concentrates on premium touring models with auxiliary power needs.
Commercial vehicles lead volumes today; passenger cars are gaining share fastest as regulatory credit frameworks mature.
Solar Technology:
Cost tier separation drives technology selection, with silicon-based solutions anchoring commercial viability and emerging stacks commanding premium positioning.
- Photovoltaic Cells:Crystalline silicon cells dominate automotive integration for their proven durability and manufacturing scale. Chinese and German manufacturing clusters supply the majority of vehicle-grade cells, with efficiency ceilings near 26% constraining range extension per unit area.
- Bifacial Modules:Dual-sided light capture harvests reflected irradiance from road surfaces, extending effective daily range in high-sunlight corridors. Fleet operators in the United States deploy these on refrigerated delivery vehicles where roof height maximizes ground reflection capture.
- Thin-Film Technology:Flexible substrates conform to curved body panels, opening integration on surfaces unsuitable for rigid silicon.
- Concentrated Solar Power:Tracking assemblies and lens systems remain impractical for mobile applications; stationary charging stations represent the sole viable deployment.
Photovoltaic cells anchor commercial deployment today; bifacial modules are climbing the fastest as fleet density concentrates in high-irradiance logistics corridors.
Power Capacity:
Application intensity determines capacity tier selection, with urban logistics favoring low-to-medium configurations and long-haul platforms requiring high-output stacks.
- Low Power:Sub-500W arrays supplement auxiliary systems and trickle-charge traction batteries during extended parking. Urban delivery fleets in Germany deploy these on compact vans where route distances minimize propulsion energy demand.
- Medium Power:500W-2kW systems deliver meaningful daily range extension for light commercial vehicles with predictable daytime utilization. Chinese OEMs concentrate procurement here for domestic last-mile electrification programs.
- High Power:2kW-5kW configurations support substantial propulsion energy contribution on larger van and small truck platforms.
- Ultra-High Power:Exceeding 5kW, these arrays require extensive surface area and active thermal management; prototype deployment concentrates on specialty commercial chassis.
Medium power configurations dominate fleet procurement today; high power systems show steepest expansion trajectory as battery-electric commercial vehicle weights climb.
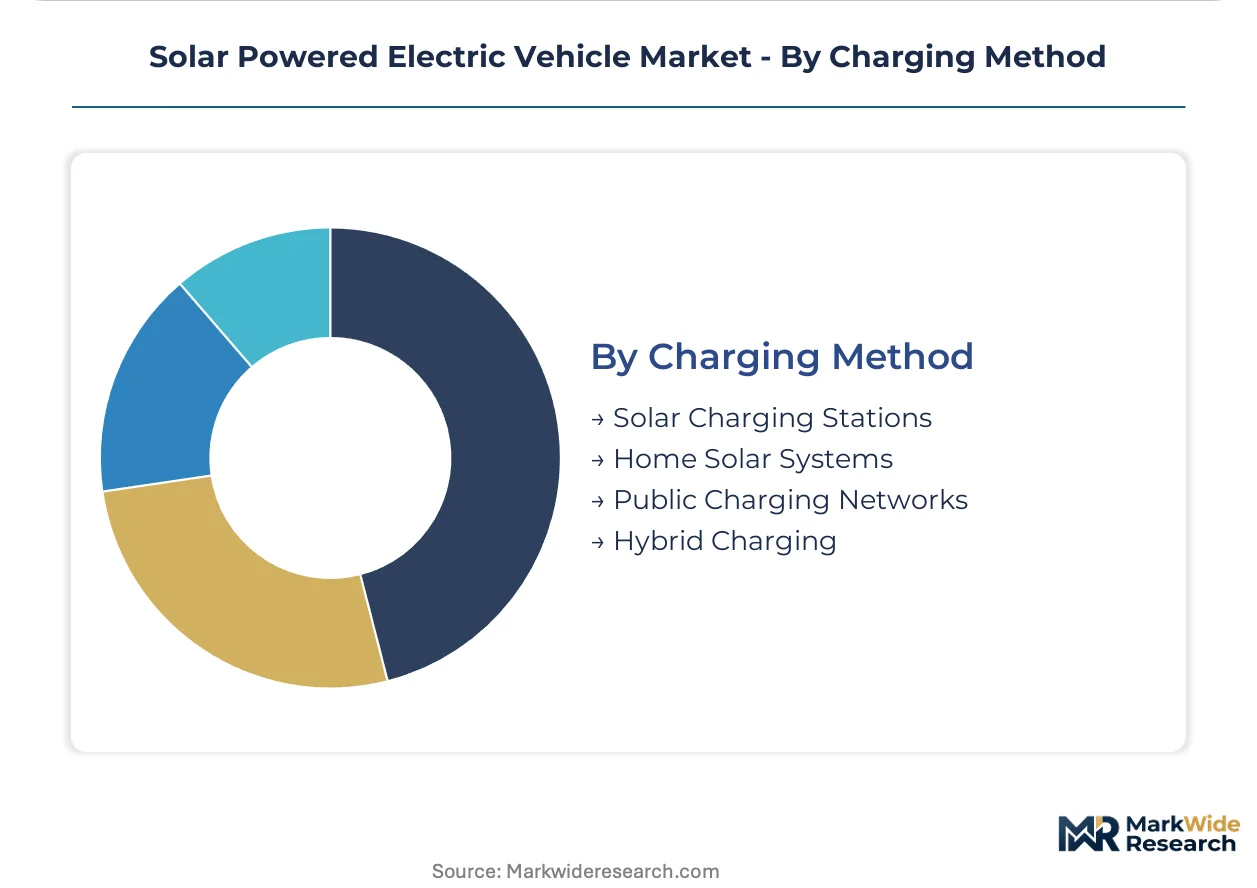
Charging Method:
Customer type and infrastructure access shape charging architecture preferences, with fleet operators prioritizing controlled solar generation and retail buyers relying on hybrid flexibility.
- Home Solar Systems:Residential photovoltaic arrays pair with garage-mounted vehicle charging, collapsing grid dependency for commuter vehicles. German households with existing rooftop solar concentrate demand here as net metering regulations evolve.
- Hybrid Charging:Simultaneous solar supplementation and grid charging maximizes operational flexibility for unpredictable route patterns. United States consumers favor this configuration to bridge infrastructure gaps while retaining solar autonomy benefits.
- Solar Charging Stations:Canopy-mounted arrays shade parked vehicles while delivering direct current charging; commercial fleet depots anchor deployment.
- Public Charging Networks:Grid-tied infrastructure with solar augmentation remains limited; pilot programs concentrate in California and the Netherlands.
Hybrid charging leads consumer adoption today; home solar systems are expanding most quickly as residential photovoltaic penetration deepens in Germany and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor anchors photovoltaic-integrated vehicle development, with solar manufacturing clusters in Saxony and Baden-Württemberg supplying cells to domestic OEMs. Fleet electrification mandates across major economies are redrawing procurement geography toward jurisdictions with overlapping solar resource and charging infrastructure density.
United States
California's Advanced Clean Trucks regulation compels logistics operators to document zero-emission miles, accelerating solar-augmented van deployment in the Central Valley. The EPA tailpipe emissions standards treat solar-derived kilometers as qualifying credits in proposed rulemaking. Phoenix and Dallas logistics hubs concentrate pilot programs for bifacial-equipped delivery fleets.
Germany
The KBA homologation framework shapes crash-test requirements for integrated solar surfaces, elongating certification timelines for domestic van manufacturers. EU Green Deal transport mandates pressure OEMs to certify solar-assisted range extensions. Stuttgart and Wolfsburg engineering centers prototype perovskite-silicon tandem stacks for light commercial platforms.
China
MIIT efficiency standards push domestic OEMs toward photovoltaic bodywork for last-mile delivery electrification programs. Dual carbon goals compress timelines for renewable energy integration in automotive manufacturing. Yangtze River Delta solar cell clusters supply vehicle-grade silicon to Shanghai and Hefei assembly plants.
Netherlands
Carbon pricing mechanisms amplify solar autonomy value for urban logistics operators with predictable daytime routes. National charging infrastructure density supports hybrid solar-grid deployment strategies. Eindhoven's high-tech automotive ecosystem hosts validation centers for solar yield forecasting integration into fleet management platforms.
India
The PLI scheme for solar manufacturing could localize photovoltaic supply chains for solar-integrated vehicle exports. National logistics electrification targets concentrate demand in Delhi-NCR and Mumbai corridors. Tamil Nadu solar manufacturing parks position to supply automotive-grade cells as domestic commercial EV adoption accelerates.
Solar Powered Electric Vehicle Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEMs bridge photovoltaic integration gaps through technology licensing and joint development agreements. The vendor base organizes around three tiers: established automakers with hybrid solar-electric architectures, venture-backed specialists in dedicated solar vehicle platforms, and component suppliers advancing automotive-grade encapsulation. Competitive positioning hinges on regulatory credit capture capabilities and fleet management software integration rather than manufacturing scale alone. Technology licensing and capacity expansion represent the dominant competitive vectors as players race to certify solar-derived kilometers under divergent national protocols.
Among established automakers, Toyota Motor Corporation and Ford Motor Company occupy positions bridging current infrastructure constraints through hybrid architectures. Volkswagen anchors European development within the premium passenger segment. Lightyear exemplifies the venture-backed specialist archetype, while Sono Motors represents retrofit-focused commercial vehicle integration. These players collectively illustrate how competitive advantage is concentrating around regulatory navigation capabilities and fleet software integration rather than pure photovoltaic efficiency metrics.
| Leading Market Players |
|---|
| Lightyear |
| Sono Motors |
| Aptera |
| Toyota Motor Corporation |
| Ford Motor Company |
| Volkswagen |
| Fisker |
| Hyundai |
| Mercedes-Benz |
| Others |
Value Network & Pricing Analysis
Perovskite-silicon tandem cell manufacturing is scaling from laboratory pilot lines to automotive-qualified production, simultaneously compressing cost-per-watt trajectories and redrawing supplier concentration toward German and Chinese photovoltaic clusters with certified automotive encapsulation capabilities.
Pricing Analysis
Polysilicon wafer cost pass-through dominates solar body panel economics, with crystalline silicon tier pricing tethered to Yangtze River Delta spot markets. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated systems from aftermarket retrofit kits and commercial fleet volume contracts. Price differentiation centers on automotive-grade encapsulation certification and thermal management integration depth. Margins are tightening due to NHTSA crash-test recertification overhead, while fleet procurement committees exhibit lowest price sensitivity among buyer archetypes.
Supply Chain Analysis
End-of-life photovoltaic module recovery flows are emerging as a structural consideration, with German and Chinese regulators drafting extended producer responsibility frameworks for automotive-integrated solar surfaces. Raw material draws from metallurgical-grade polysilicon, ethylene-vinyl acetate encapsulant, and tempered solar glass feedstocks. Single-source vulnerability concentrates in automotive-grade cell metallization pastes. Distribution runs through Tier 1 supplier networks directly into OEM platform engineering teams, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal transport mandates and EPA tailpipe emissions standards creating durable demand pull for solar-assisted range certification.
For Market Incumbents: Extend platform standardization efforts to accommodate modular solar bodywork across van and light truck architectures, defending against venture-backed specialists with dedicated solar vehicle platforms. Deepen backward integration into photovoltaic encapsulation capabilities to capture margin currently lost to automotive-grade glass suppliers. Prioritize KBA and NHTSA pre-certification investments to compress model launch timelines. For New Entrants and Emerging Players: Capture aftermarket retrofit white space for existing commercial van fleets in Germany and the United States, where fleet managers prioritize total cost of ownership over upfront capital thresholds. Target refrigerated delivery vehicle operators with bifacial roof arrays optimized for high-sunlight logistics corridors. Lead with route-optimization software integration that collapses solar yield forecasting into logistics planning workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with automotive-grade encapsulation capabilities and dormant OEM relationships. Long-term viability hinges on regulatory credit treatment harmonization across EPA, KBA, and MIIT regimes. Monitor proposed rulemaking for solar-derived kilometer eligibility as the primary inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Scale-Up | German van manufacturers pilot 30% efficiency stacks for refrigerated delivery platforms. |
| Fleet Management Software Integration | Third-party platforms embed solar yield forecasting into vehicle selection algorithms. |
| Automotive-Grade Encapsulation Certification | Stone chip and chemical resistance standards remain unresolved at commercial price points. |
| Retrofit Solar Bodywork Development | Aftermarket integration opens volume without requiring platform redesign for existing vans. |
| Vehicle-to-Grid Solar Arbitrage Infrastructure | Bidirectional charging enables fleet monetization of excess generation during peak pricing windows. |
Research Methodology
Coverage spans Germany, the United States, China, and the Netherlands, with primary inputs from each market informing cross-border regulatory divergence analysis. Primary interviews with OEM platform engineers, Tier 1 photovoltaic procurement leads, fleet operations directors, and automotive encapsulation R&D heads combined with secondary validation from MIIT efficiency filings, EPA proposed rulemaking dockets, EU Green Deal transport mandate texts, and vehicle production registration databases. Bottom-up fleet deployment modeling and top-down OEM revenue attribution were triangulated for segment sizing.
Rate-of-change decomposition across vehicle type, solar technology, power capacity tier, and charging method segments drove analytical framework construction. CAGRs were derived from installed base accumulation curves and replacement cycle assumptions. Industry-specific forecast inputs incorporated polysilicon price trajectory scenarios and regulatory credit treatment evolution across jurisdictions. Volume and value outputs reflect convergence between fleet procurement pipeline visibility and OEM platform launch timelines.
Polysilicon supply disruption, regulatory credit eligibility reversals, and bifacial module thermal degradation in automotive form factors are the dominant revision risks across the modeling period. Forecasts reflect documented assumptions regarding homologation timeline compression and fleet manager behavioral pivot durability. Practitioners should monitor KBA perovskite certification progress and NHTSA solar surface crash-test protocol finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
E-Bike Market