
 China NEV Taxi Market | 2026-2036
China NEV Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
China NEV Taxi Market Outlook
Fleet procurement authority is shifting from fragmented municipal taxi companies toward consolidated ride-hailing platforms and state-backed fleet operators. BYD Company Limited leverages its vertically integrated battery supply chain to dominate taxi-spec vehicle output. SAIC Motor Corporation Limited sustains partnerships with municipal governments for fleet electrification contracts. Geely Automobile Holdings Limited competes through its dedicated taxi subsidiary and battery-swapping subsidiary networks.
China NEV taxi denotes battery-electric, plug-in hybrid, and fuel-cell passenger vehicles purpose-built or retrofitted for commercial for-hire passenger transport, typically featuring reinforced suspension, extended-duty cycle thermal management, and duty-cycle-optimized battery packs rated between 30-90 kWh for 300-500 kilometer daily range. Battery Electric vehicles anchor volume due to lower per-kilometer energy costs and simpler maintenance profiles. Fast Charging Stations capture disproportionate infrastructure investment as fleet operators prioritize turnaround time over residential charging convenience. The 60-90 kWh battery capacity band leads unit economics by balancing vehicle cost against daily duty cycle requirements.
MIIT vehicle-type approval rules and GB standards dictate NEV taxi homologation, battery safety testing, and onboard data telemetry requirements. SAMR pricing oversight and municipal dual-carbon implementation timelines shape fleet replacement schedules and subsidy structures. MEE emissions monitoring enforces retirement deadlines for legacy combustion taxis in key urban zones. Stakeholders must track regulatory alignment between national subsidy phase-outs and local fleet electrification mandates.
Market Dynamics
Fleet procurement authority is consolidating under ride-hailing platforms and state-backed operators, compressing traditional municipal taxi company influence. Battery swapping infrastructure from NIO and State Grid rapid charging networks are altering capital deployment patterns across fleet operations.
Growth Catalysts
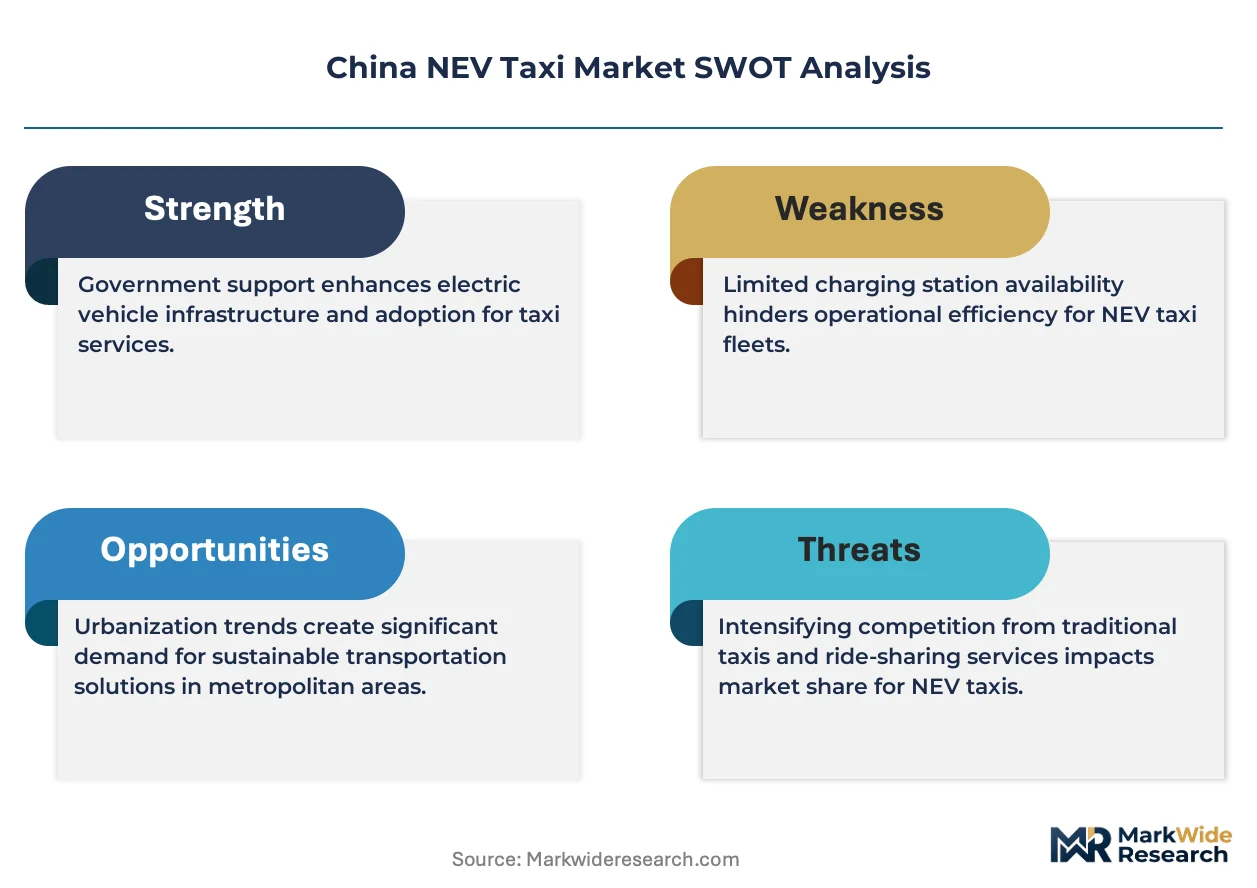
- Dual carbon goals:Municipal retirement deadlines for combustion taxis in Shanghai, Beijing, and Shenzhen accelerate fleet turnover timelines.
- Battery swapping protocols:Standardized swap stations reduce downtime to under three minutes, improving vehicle utilization rates for high-mileage operators.
- Yangtze River Delta cluster density:Concentrated demand across Shanghai, Hangzhou, and Suzhou creates network effects for charging infrastructure investment.
Market Restraints
- Lithium carbonate price volatility:Battery pack costs remain exposed to raw material swings, pressuring fleet procurement budgets.
- Charging infrastructure concentration:State Grid and regional grid operators control critical fast-charging node placement, limiting operator flexibility.
- MIIT homologation timelines:Extended vehicle-type approval cycles delay new model deployment for taxi-specific configurations.
Strategic Opportunities
- Fuel-cell taxi pilots:Municipal hydrogen corridor programs in Foshan and Zhengzhou open alternative powertrain deployment channels.
- Second-life battery integration:Retired EV packs repurposed for stationary charging buffers reduce grid upgrade costs at fleet depots.
- GB standard harmonization:Unified connector and communication protocols enable cross-platform interoperability for swapping networks.
Industry Challenges
- Thermal management engineering talent:Extended-duty cycle battery cooling system design expertise concentrates at BYD and CATL, creating hiring bottlenecks for smaller fleet operators.
- Onboard telemetry compliance:Real-time data transmission to municipal transport authorities requires hardware retrofits for legacy fleet assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China NEV Taxi Market |
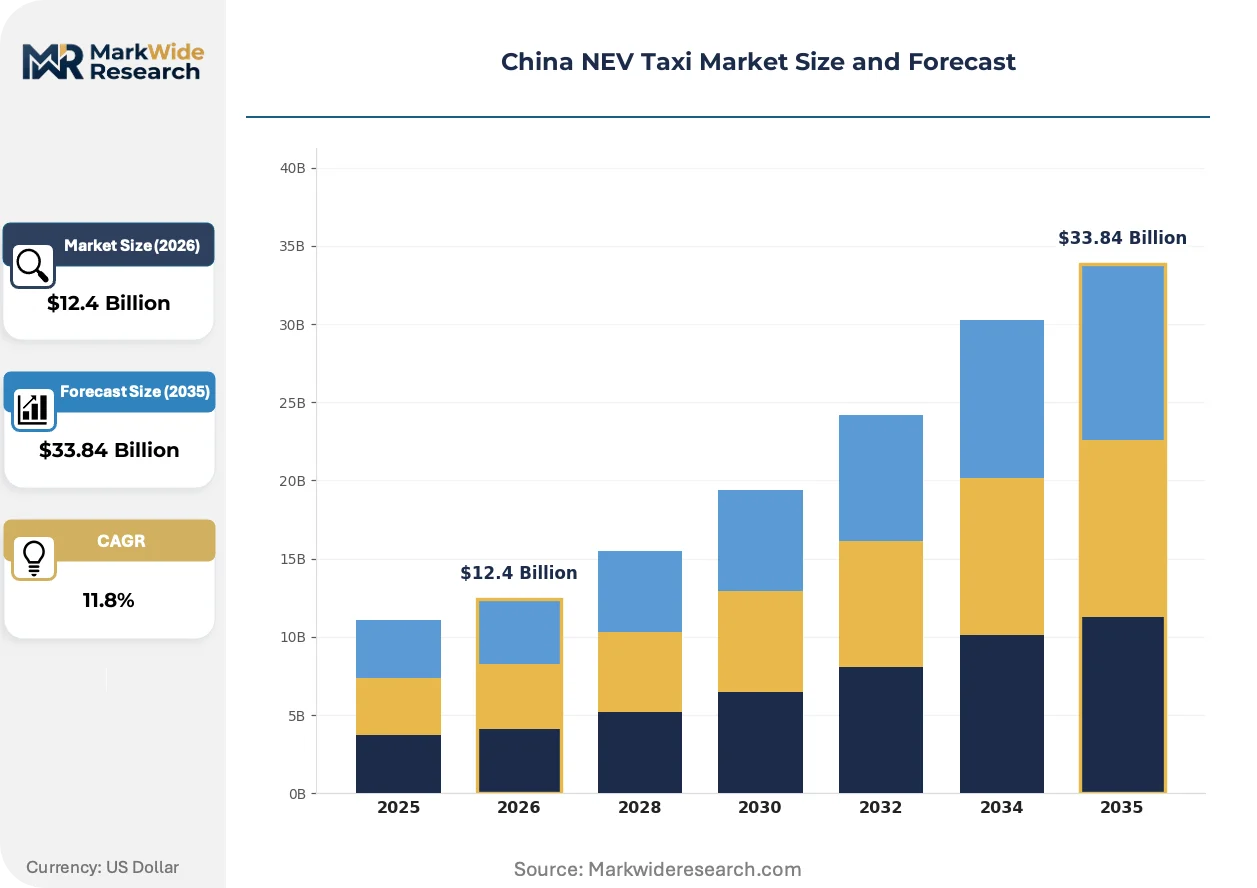
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.84 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric, Plug-in Hybrid, Fuel Cell, Others Charging Infrastructure: Fast Charging Stations, Standard Charging Points, Home Charging, Public Charging Hubs Service Model: Ride-Hailing, Fleet Management, Shuttle Service, On-Demand Transport Battery Capacity: Less than 30 kWh, 30-60 kWh, 60-90 kWh, More than 90 kWh |
| Companies Covered | BYD Company Limited, Tesla Inc., NIO Inc., Xpeng Motors, Geely Automobile Holdings Limited, SAIC Motor Corporation Limited, Anhui Jianghuai Automobile Co., Ltd., Beijing Automotive Industry Holding Co., Ltd., Changan Automobile Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China NEV Taxi Market Strategic Shifts
Operational technology is converging around battery-swappable architectures and intelligent fleet management platforms. These shifts are compressing vehicle downtime and redefining asset ownership models across commercial passenger transport.
Lithium iron phosphate cell chemistry is absorbing cost-sensitive fleet demand due to superior cycle life and thermal stability. Municipal operators in Chengdu and Xi'an are specifying LFP-dominant packs for their replacement programs. This chemistry shift is absorbing volume from nickel-cobalt-manganese alternatives in the 60-90 kWh duty-cycle-optimized segment.
MEE emissions monitoring enforcement is tightening retirement deadlines for legacy combustion taxis in designated low-emission zones. Municipal governments are responding with accelerated replacement quotas tied to operating license renewals. The policy pressure falls most heavily on tier-two city fleets that lagged tier-one electrification timelines.
Fleet management platforms are unbundling vehicle ownership from driver access through subscription-based battery service models. Ride-hailing platforms are displacing direct driver purchases with all-inclusive monthly packages covering swap access and maintenance. This restructuring is most visible in Shenzhen and Guangzhou where platform-affiliated vehicles dominate new registrations.
China NEV Taxi Market Segmentation
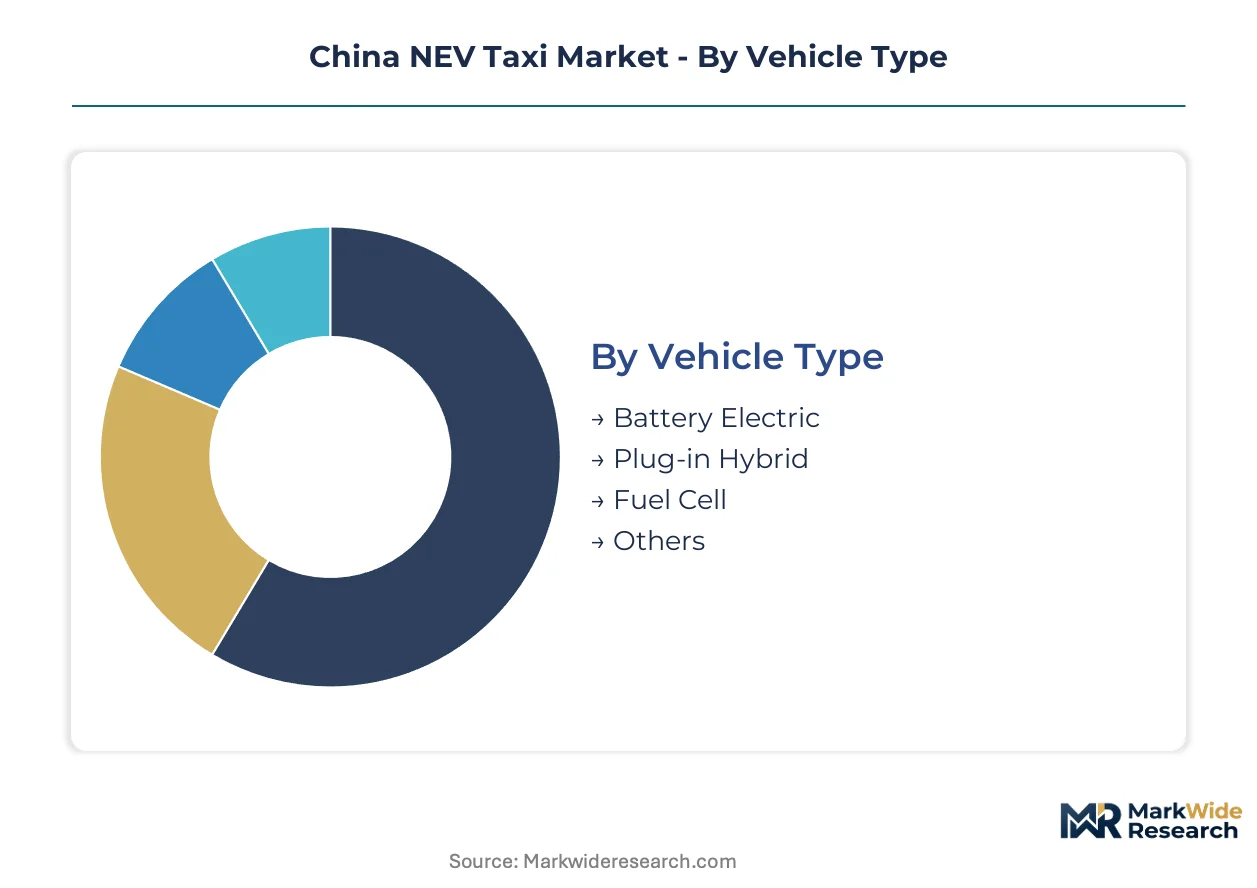
Fleet procurement decisions in China's NEV taxi market hinge on matching vehicle specifications to duty cycle intensity, charging access constraints, and total cost of ownership thresholds. Municipal operators and ride-hailing platforms evaluate segments through divergent lenses—durability for high-mileage fleet deployment versus flexibility for driver-owned assets.
Vehicle Type:
Fleet managers prioritize total cost per kilometer and maintenance predictability when selecting powertrain architecture for commercial passenger service.
- Battery Electric:Purpose-built BEVs with duty-cycle-optimized thermal management and reinforced suspension systems dominate municipal fleet tenders in Shanghai and Shenzhen. Lithium iron phosphate cell chemistry absorbs cost-sensitive demand due to superior cycle life and thermal stability under extended daily operation.
- Plug-in Hybrid:PHEV configurations with 50-80 kilometer electric range serve operators in charging infrastructure gaps across tier-two cities, bridging the transition from combustion dependence without full electrification risk. Chengdu and Xi'an procurement programs specify PHEV options for routes with irregular charging access.
- Fuel Cell:Hydrogen fuel-cell taxis pilot in Foshan and Zhengzhou municipal hydrogen corridor programs, targeting high-utilization operators with sub-10-minute refueling requirements.
- Others:Range-extended electric vehicles and experimental solid-state prototypes occupy niche trial deployments under MIIT vehicle-type approval frameworks.
Battery Electric leads on scale; Fuel Cell leads on momentum.
Charging Infrastructure:
Capital deployment patterns across fleet operations track turnaround time economics and grid upgrade feasibility rather than residential convenience.
- Fast Charging Stations:State Grid and regional operators prioritize 120-350 kW DC fast charging nodes at fleet depots and highway corridors, compressing vehicle downtime to 30-45 minutes for 60-90 kWh packs. Yangtze River Delta cluster density creates network effects for infrastructure investment.
- Standard Charging Points:7-22 kW AC installations serve overnight depot charging for lower-mileage fleet segments and driver-owned vehicles with predictable dwell periods.
- Home Charging:Residential wallbox penetration remains limited in taxi applications due to rental driver demographics and apartment dwelling patterns in tier-one cities.
- Public Charging Hubs:Mixed-use stations combining taxi-dedicated bays with general NEV access operate at transport terminals and commercial districts under municipal planning mandates.
Fast Charging Stations anchor fleet economics; Public Charging Hubs gain share through municipal integration mandates.
Service Model:
Platform consolidation is restructuring asset ownership, unbundling vehicle access from driver employment through subscription-based operational packages.
- Ride-Hailing:Platform-affiliated vehicles dominate new registrations in Shenzhen and Guangzhou, with all-inclusive monthly packages covering battery swap access, maintenance, and insurance displacing direct driver purchases.
- Fleet Management:State-backed operators and consolidated municipal companies centralize procurement authority, negotiating volume contracts with BYD and SAIC for standardized vehicle specifications across hundreds of units.
- Shuttle Service:Fixed-route airport and intercity connectors specify higher-capacity vehicles with luggage accommodations, operating under dedicated service licenses.
- On-Demand Transport:App-dispatched microtransit and accessibility services utilize smaller-format NEVs with wheelchair accessibility modifications.
Ride-Hailing commands volume growth; Fleet Management retains procurement leverage.
Battery Capacity:
Daily duty cycle requirements and vehicle cost tradeoffs determine optimal pack sizing for commercial operators targeting 300-500 kilometer range thresholds.
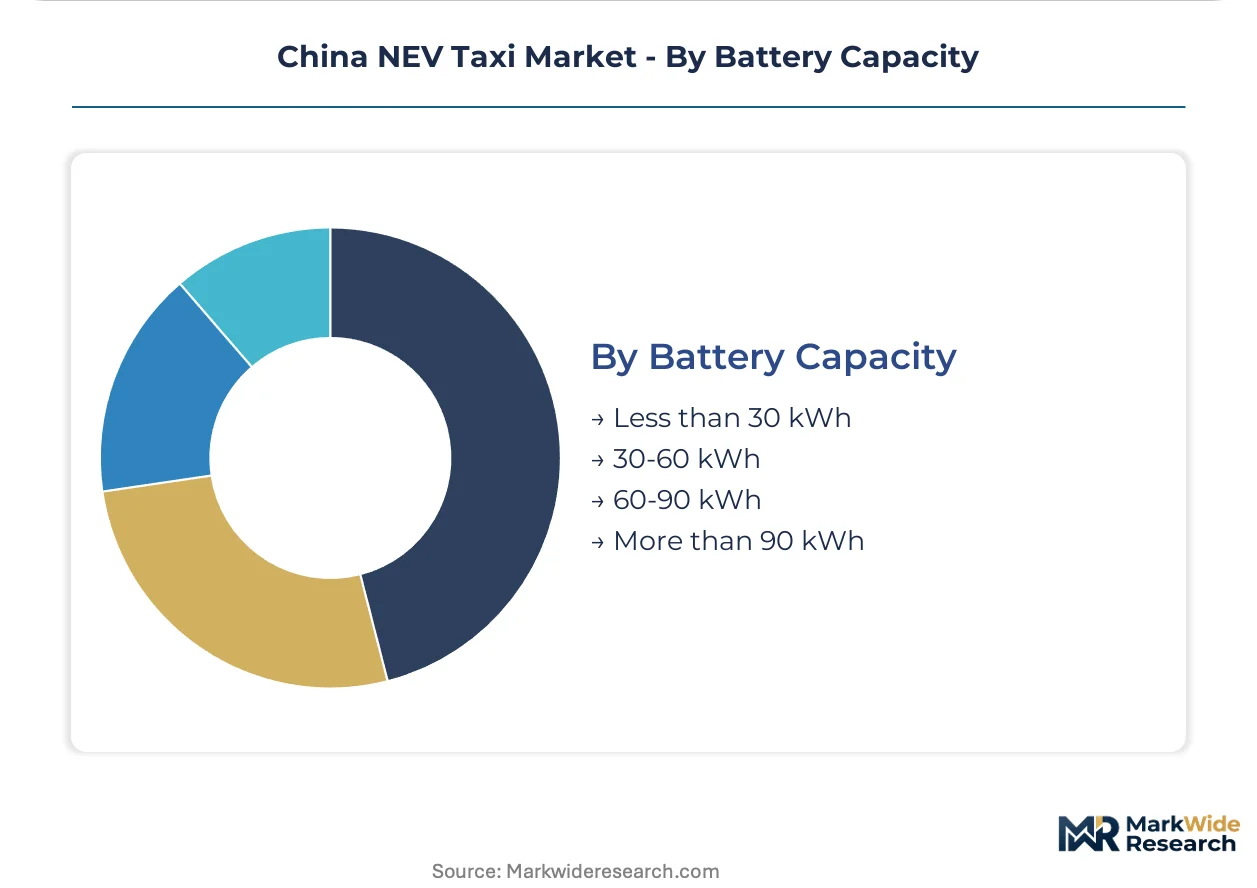
- 60-90 kWh:The dominant configuration balances upfront vehicle cost against single-shift range adequacy, absorbing the majority of fleet procurement in Beijing and Shanghai replacement programs. LFP chemistry dominance in this band reduces thermal runaway risk under sustained fast-charging regimens.
- 30-60 kWh:Compact urban taxis and second-shift vehicles in dense city centers utilize smaller packs with mid-shift swapping or opportunity charging, minimizing capital deployment per unit.
- Less than 30 kWh:Micro-taxis and three-wheel NEV conversions serve last-mile connectivity in historic districts with restricted vehicle dimensions.
- More than 90 kWh:Extended-range configurations support intercity shuttle routes and cold-climate operations where heating loads degrade effective range.
60-90 kWh defines mainstream fleet economics; 30-60 kWh climbs fastest through battery-swapping platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent for extended-duty cycle thermal management concentrates in the Yangtze River Delta, Pearl River Delta, and Beijing-Tianjin-Hebei corridor. These clusters anchor fleet electrification deployment and battery-swapping infrastructure rollout.
Yangtze River Delta
Shanghai, Hangzhou, and Suzhou municipal fleets drive replacement demand under dual carbon implementation timelines. MIIT vehicle-type approval rules govern NEV taxi homologation for vehicles operating across this cluster. Battery swapping protocols from NIO and State Grid rapid charging networks reshape operational economics for high-mileage operators in this region.
Pearl River Delta
Shenzhen and Guangzhou ride-hailing platforms dominate new registrations through subscription-based battery service models. SAMR pricing oversight shapes fleet procurement budgets and subsidy structures for commercial operators. Platform-affiliated vehicles displace direct driver purchases as consolidation accelerates across Guangdong province.
Beijing-Tianjin-Hebei
Capital region municipal governments enforce accelerated retirement deadlines for legacy combustion taxis in designated low-emission zones. MEE emissions monitoring tightens enforcement timelines tied to operating license renewals. Fleet operators in Beijing negotiate volume contracts with state-backed manufacturers for standardized vehicle specifications.
Sichuan-Chongqing
Chengdu procurement programs specify plug-in hybrid options for routes with irregular charging access across mountainous terrain. Municipal dual-carbon goals compress replacement schedules despite infrastructure gaps in western districts. Local operators balance electrification targets against grid upgrade feasibility in this interior cluster.
Shandong Peninsula
Qingdao and Jinan taxi companies pilot second-life battery integration for stationary charging buffers at fleet depots. GB standards harmonization efforts enable cross-platform interoperability for regional swapping networks. Lithium iron phosphate chemistry dominance absorbs cost-sensitive fleet demand in these replacement programs.
China NEV Taxi Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's NEV taxi supply base. Vertically integrated automotive groups leverage captive battery supply chains against dedicated fleet-vehicle subsidiaries and ride-hailing platform affiliates. Three archetypes dominate: state-backed conglomerates with municipal government relationships, pure-play electric vehicle specialists with swapping infrastructure, and platform-integrated fleet operators unbundling asset ownership. Competitive moves center on strategic partnerships for charging network access and portfolio diversification into battery service subscriptions.
Among diversified automotive groups, BYD Company Limited and SAIC Motor Corporation Limited occupy positions anchored by vertical integration into battery cell production and state procurement relationships. Geely Automobile Holdings Limited sits within the specialist tier through its dedicated taxi subsidiary and battery-swapping subsidiary networks. These three enterprises exemplify divergent pathways for securing fleet electrification contracts across municipal tender processes.
| Leading Market Players |
|---|
| BYD Company Limited |
| Tesla Inc. |
| NIO Inc. |
| Xpeng Motors |
| Geely Automobile Holdings Limited |
| SAIC Motor Corporation Limited |
| Anhui Jianghuai Automobile Co., Ltd. |
| Beijing Automotive Industry Holding Co., Ltd. |
| Changan Automobile Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Ride-hailing platform consolidation has compressed municipal taxi company procurement authority into volume-based contract structures. State-backed fleet operators negotiate standardized vehicle specifications through multi-year framework agreements, unbundling battery service subscriptions from upfront capital deployment.
Pricing Analysis
Bundled subscription models covering battery swap access, maintenance, and insurance now dominate platform-affiliated vehicle economics, displacing direct driver purchases. Three-tier pricing structure across premium, standard, and economy levels reflects battery capacity bands and thermal management sophistication. Cost compression in the 30-60 kWh segment is intensifying because battery-swapping platform expansion drives capital efficiency demands. Tier-two city municipal operators exhibit highest price sensitivity due to constrained procurement budgets, while Yangtze River Delta fleet managers prioritize total cost per kilometer over upfront vehicle cost.
Supply Chain Analysis
Dual-sourcing requirements from State Grid and NIO battery-swapping networks mandate multi-supplier qualification for cathode active material and cell production. Manufacturing gravity centers on China, South Korea, and Japan for lithium-ion cell supply, with lithium carbonate and nickel sulfate feedstock drawing from Australian and Chilean extraction. Single-source vulnerability concentrates in high-purity electrolyte additives and separator membranes. Distribution runs through consolidated fleet procurement channels and ride-hailing platform affiliate networks, bypassing traditional dealership structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery service subscription unbundling creates margin expansion through recurring revenue streams and lithium iron phosphate chemistry cost-down curves. Platform-affiliated fleet models shift value capture from vehicle sales toward operational service tiers.
For Market Incumbents: Anticipate ride-hailing platform vertical integration into captive battery-swapping infrastructure as the primary competitive threat. Secure long-term cathode material offtake agreements to defend procurement leverage. Deepen MIIT homologation expertise to accelerate vehicle-type approval cycles for taxi-specific configurations.
For New Entrants and Emerging Players: Tier-two city municipal operators with irregular charging access represent the most penetrable buyer archetype. Target Chengdu and Xi'an procurement programs specifying plug-in hybrid bridging options. Enter through battery-swapping network partnership rather than direct vehicle sales to compress customer acquisition cost.
For Investors and Strategic Acquirers: State-backed automotive conglomerates are the most active acquirer in this space, consolidating battery cell production and fleet management platform assets. Five-to-ten year viability hinges on second-life battery integration capabilities and GB standard harmonization positioning. Monitor MIIT subsidy phase-out alignment with municipal dual-carbon enforcement timelines as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Network Expansion | NIO and State Grid protocols reduce vehicle downtime below three minutes for high-utilization operators. |
| Lithium Iron Phosphate Chemistry Transition | LFP cell dominance in 60-90 kWh packs absorbs cost-sensitive fleet demand through superior cycle life. |
| Second-Life Battery Integration | Retired EV packs repurposed as stationary charging buffers reduce grid upgrade costs at fleet depots. |
| Platform Subscription Model Deployment | Ride-hailing platforms displace direct driver purchases with all-inclusive monthly service packages. |
| GB Standard Harmonization | Unified connector protocols enable cross-platform interoperability for regional swapping networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged fleet procurement directors at state-backed operators, platform operations executives at ride-hailing companies, battery cell engineering leads, and municipal transport authority officials. Secondary validation drew from MIIT vehicle-type approval filings, State Grid infrastructure investment disclosures, SAMR pricing oversight bulletins, and municipal dual-carbon implementation timelines. Bottom-up fleet deployment tracking and top-down market sizing triangulated volume estimates.
Historical reference periods anchored projections across the modeling period through comparable-period growth rate analysis. Segmentation dimensions modeled include vehicle type, battery capacity band, charging infrastructure category, and service model archetype. CAGRs derived from regression analysis against fleet replacement schedules and subsidy phase-out trajectories. Forecast inputs incorporated lithium carbonate price volatility indices and MIIT homologation cycle duration assumptions.
Underlying measurement precision varies by segment; Yangtze River Delta cluster data carries tighter precision than interior province estimates. Forecasts incorporate assumptions around municipal enforcement timelines and platform consolidation velocity. Deviation in MIIT subsidy extension or lithium supply contract renegotiation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market