
 Asia-Pacific Electric Vehicle Market | 2026-2036
Asia-Pacific Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Market Analysis
Battery engineering talent is collapsing across Southeast Asian manufacturing hubs, forcing automakers to relocate training centers or recruit from Chinese universities. BYD Auto Co., Ltd leverages its in-house cell production to control cost curves that rivals cannot match. Toyota Motor Corporation anchors its regional strategy around hybrid electric systems while building solid-state battery pilot lines in Japan. Hyundai Motor Company competes through dedicated EV platforms manufactured at its Indonesian and Indian plants.
An electric vehicle converts stored electrical energy into mechanical propulsion through one or more traction motors, with energy density, thermal management, and regenerative braking efficiency determining real-world range and performance. Battery Electric vehicles command the dominant share of new registrations as lithium-ion pack costs decline and fast charging networks proliferate across urban corridors. Fleet Operators represent the fastest-expanding customer segment, driven by total-cost-of-ownership advantages in high-utilization commercial applications where vehicles accumulate substantial daily mileage.
China's MIIT enforces GB standards for battery safety and vehicle connectivity, while India's BIS mandates local testing protocols that shape product certification timelines for foreign manufacturers. Japan's METI coordinates charging infrastructure subsidies with grid stability requirements, creating interdependencies between utility planning and automotive deployment schedules. Stakeholders must monitor how divergent national subsidy phase-out calendars reshape cross-border manufacturing location decisions before committing to greenfield capacity investments.
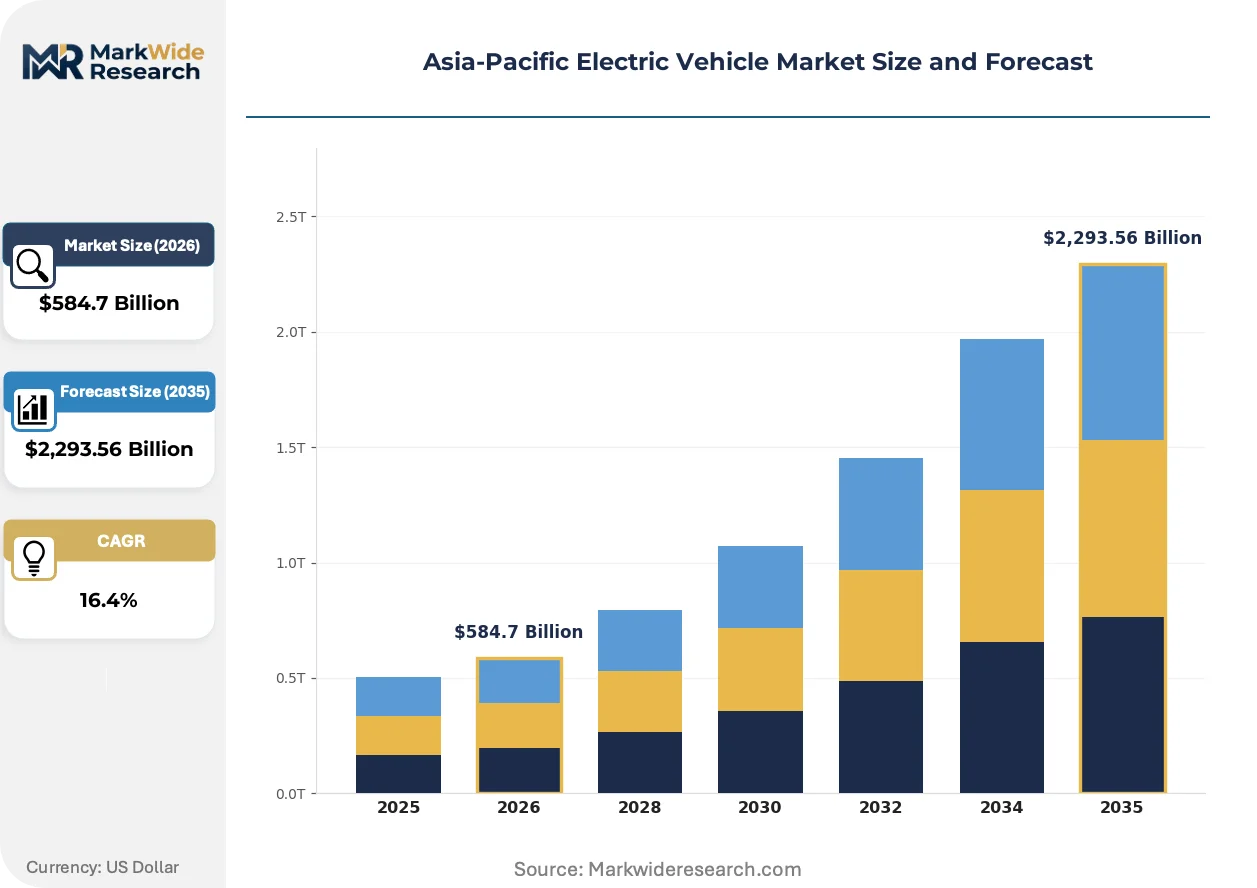
Market Dynamics
Fleet electrification in China, India, and Southeast Asia is compressing total-cost-of-ownership payback periods below internal combustion thresholds, redirecting capital flows from consumer retail toward commercial procurement channels.
Growth Catalysts
- Dual carbon goals:China's MIIT enforcement of GB standards for battery safety and vehicle connectivity mandates fleet conversion timelines that accelerate replacement cycles in logistics and ride-hailing.
- Advanced chemistry cell incentives:India's PLI scheme for battery manufacturing reduces import dependency and localizes pack production for commercial vehicle integrators.
- Charging density concentration:Eastern coastal provinces in China deploy fast-charging corridors at densities that eliminate range anxiety for high-utilization fleet operators.
Market Restraints
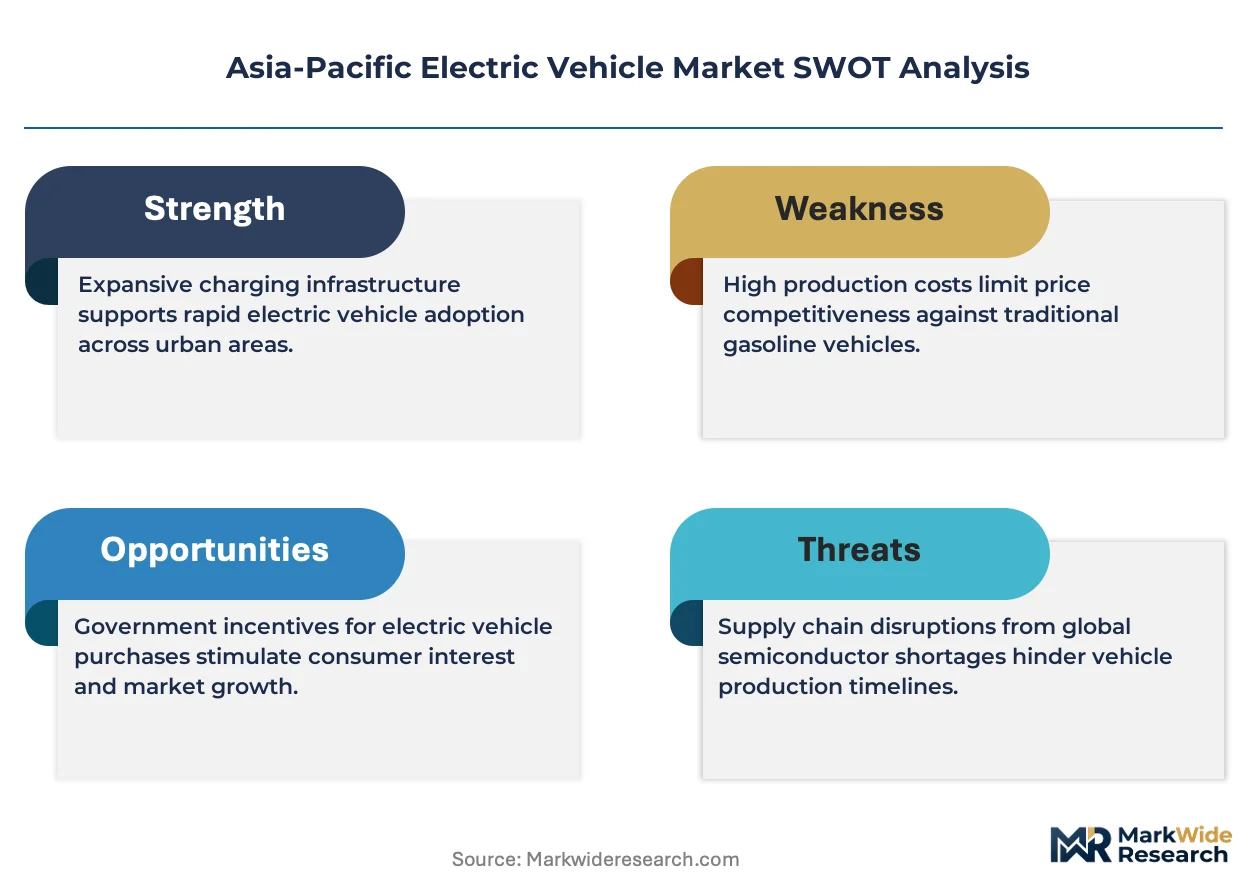
- Lithium price volatility:Raw material cost swings in cathode active materials compress margin buffers for pack assemblers without captive mining offtake.
- Semiconductor supply concentration:Power electronics fabrication clusters in Taiwan and South Korea create single-point vulnerability for traction inverter availability.
- Grid interconnection queues:Utility approval timelines for depot charging infrastructure in India stretch 18-24 months, freezing fleet expansion schedules.
Strategic Opportunities
- Indonesian nickel integration:Vertical capture of laterite ore processing into cathode precursor production shortens supply chains for regional cell manufacturers.
- Battery swapping for two-wheelers:Standardized pack formats enable asset-light fleet models in Vietnam and Thailand where home charging penetration remains minimal.
- V2G revenue stacking:Grid services contracts in Japan's deregulated power markets monetize idle commercial vehicle capacity during peak demand windows.
Industry Challenges
- Thermal management engineering scarcity:Southeast Asian manufacturing hubs face collapsing talent pools for battery pack thermal design, forcing training center relocation or Chinese university recruitment.
- Multi-standard certification complexity:Divergent BIS testing protocols in India, GB standards in China, and JIS requirements in Japan fragment product development roadmaps.
- Legacy fleet integration:Telematics retrofitting of existing diesel assets with electrification planning tools strains IT infrastructure at mid-sized logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Market |
| Market Size in 2026 | $584.7 Billion |
| Market Size in 2035 | $2,293.56 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric, Plug-in Hybrid, Fuel Cell Electric, Hybrid Electric Customer Segment: Individual Buyers, Fleet Operators, Government, Ride-sharing Services Charging Infrastructure: Home Charging, Public Charging, Fast Charging, Wireless Charging Battery Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Lead Acid |
| Companies Covered | BYD Auto Co., Ltd, Tesla Inc., Toyota Motor Corporation, Honda Motor Co., Ltd., BMW AG, Hyundai Motor Company, Geely Auto Group, Nissan Motor Co., Ltd., Tata Motors Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Market Emerging Trajectories
Electrification architecture is bifurcating between dedicated skateboard platforms and retrofit powertrains, with cell chemistry and thermal management emerging as the primary competitive differentiators rather than vehicle styling or brand heritage.
Lithium iron phosphate chemistry is supplanting nickel-manganese-cobalt formulations in commercial vehicle applications. Fleet operators prioritize cycle life and thermal stability over energy density. This shift is compressing cathode material supplier margins while expanding cell production capacity in China.
Japan's METI coordinates charging infrastructure subsidies with grid stability requirements, creating interdependencies between utility planning and automotive deployment schedules. Industrial consequence includes synchronized investment timelines that delay rollout in regions without grid reinforcement commitments. Commercial fleet segments in Kansai and Kanto regions respond by clustering depots near substations with excess capacity.
Asset-light procurement models are displacing direct vehicle ownership among logistics operators. Leasing providers bundle charging infrastructure, maintenance, and energy costs into per-kilometer contracts. This transformation concentrates buyer power with fleet management platforms in China's Yangtze River Delta and India's National Capital Region.
Asia-Pacific Electric Vehicle Market Segmentation
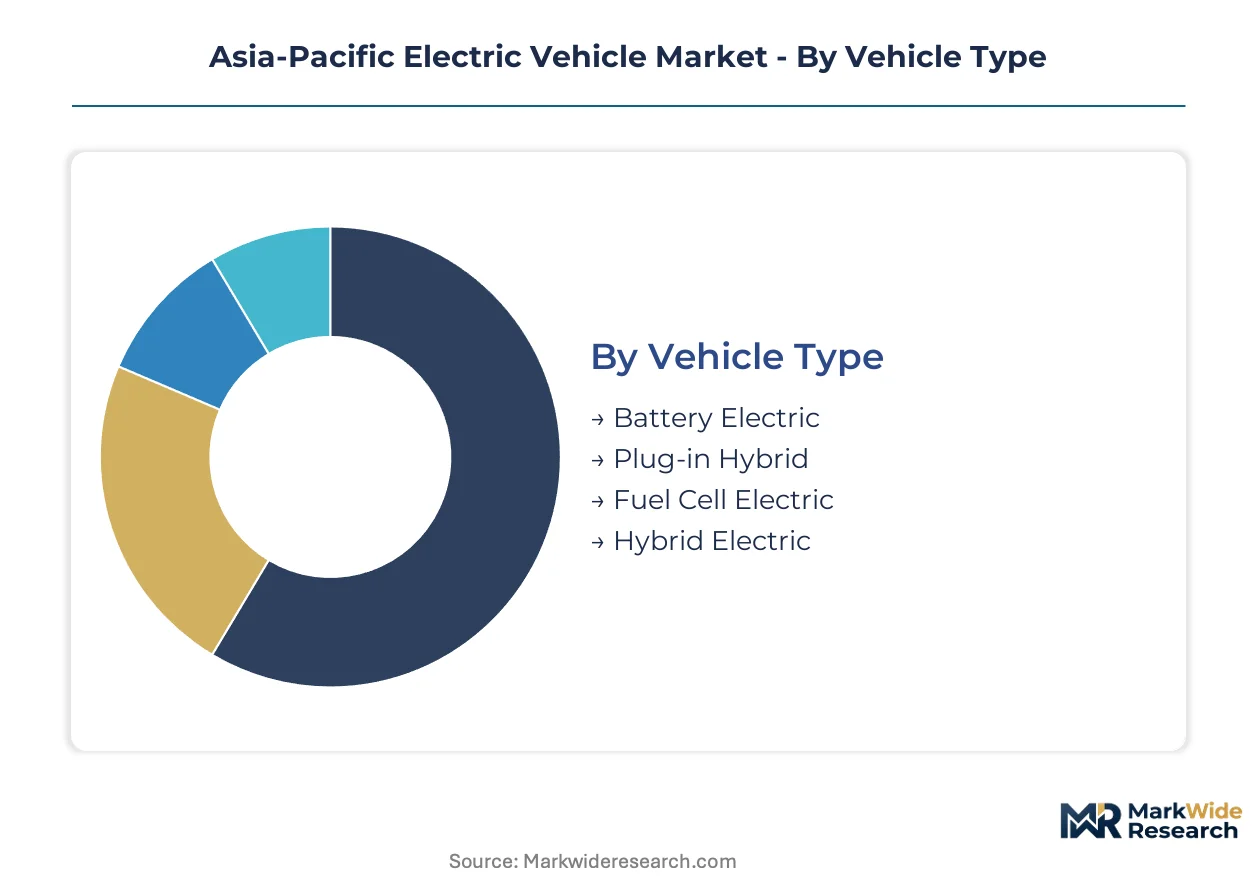
Segmentation reveals how capital allocation diverges between high-volume consumer retail and margin-rich commercial procurement channels across the Asia-Pacific region. Fleet operators and battery technology choices concentrate profit pools, while charging infrastructure investments determine geographic penetration limits.
Vehicle Type:
Margin pools concentrate in powertrain architectures that balance battery cost curves with regulatory compliance timelines across Chinese, Indian, and Japanese certification frameworks.
- Battery Electric:Traction motors draw energy from lithium-ion packs sized for commercial duty cycles, with thermal management systems determining warranty costs. Demand clusters in China's eastern coastal provinces where fast-charging density eliminates range anxiety for logistics operators running fixed depot-to-depot routes.
- Plug-in Hybrid:Dual powertrains combine combustion range extension with electric urban operation, appealing to fleet operators facing intermittent charging access. Indian commercial adopters favor this architecture where grid interconnection queues stretch 18-24 months and depot infrastructure remains undeveloped.
- Fuel Cell Electric:Proton exchange membrane stacks convert hydrogen to electricity for heavy-duty applications with minimal refueling downtime.
- Hybrid Electric:Toyota's regional strategy anchors on these systems while solid-state pilot lines advance in Japanese manufacturing clusters.
The dominant share belongs to Battery Electric, while Plug-in Hybrid is closing the gap fastest.
Customer Segment:
Procurement volume scales inversely with price sensitivity, creating tiered margin structures across ownership models.
- Fleet Operators:High-utilization commercial vehicles accumulate substantial daily mileage that compresses total-cost-of-ownship payback periods below internal combustion thresholds. Asset-light leasing models bundle charging infrastructure into per-kilometer contracts across China's Yangtze River Delta and India's National Capital Region.
- Individual Buyers:Private purchasers prioritize purchase price and residential charging feasibility over lifetime operating economics. Southeast Asian markets show minimal penetration where home charging infrastructure remains sparse and apartment dwelling predominates.
- Government:Municipal procurement mandates drive standardization in bus and utility vehicle segments.
- Ride-sharing Services:Platform economics favor rapid-charge capability and durability under continuous duty cycles.
Fleet Operators command the steepest expansion trajectory, though Individual Buyers retain absolute volume leadership in aggregate registrations.
Charging Infrastructure:
Capital deployment intensity varies by location ownership and power delivery speed, with grid interdependencies shaping rollout feasibility.
- Fast Charging:Direct current systems delivering 50-350 kW enable depot turnaround times compatible with commercial fleet scheduling. Japan's METI coordinates subsidies with grid stability requirements, creating synchronized investment timelines that cluster deployment near substations with excess capacity in Kansai and Kanto regions.
- Public Charging:Curbside and retail location networks serve ride-hailing and individual buyers without residential access. China's MIIT enforcement of GB standards for connector compatibility reduces fragmentation across provincial borders.
- Home Charging:Alternating current Level 2 systems dominate private ownership economics where dwelling type permits installation.
- Wireless Charging:Inductive pad systems eliminate connector wear in high-frequency fleet applications.
Fast Charging infrastructure attracts disproportionate capital allocation, while Public Charging networks expand most quickly in urban corridors.
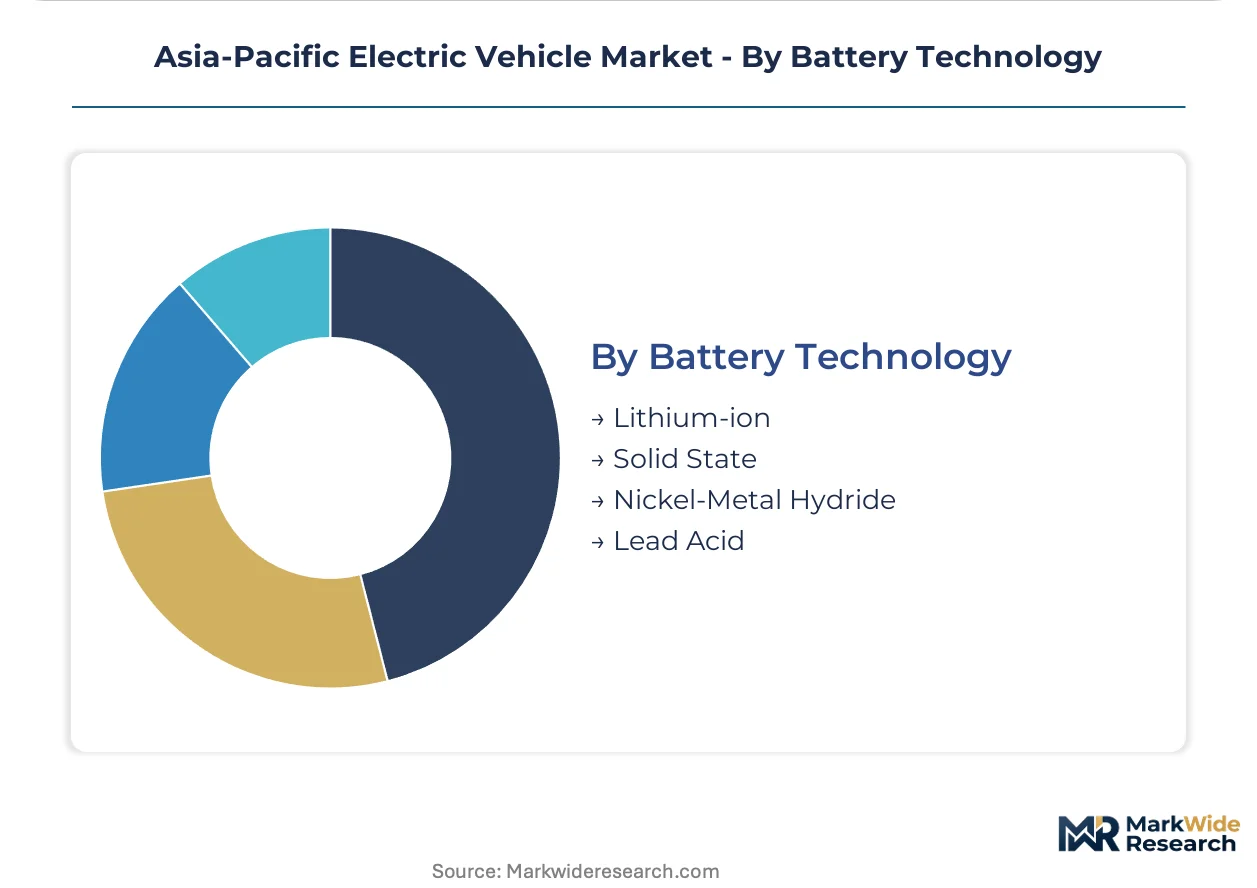
Battery Technology:
Cell chemistry selection determines thermal stability, cycle life, and supply chain vulnerability to raw material price swings.
- Lithium-ion:Lithium iron phosphate formulations supplant nickel-manganese-cobalt in commercial applications where cycle life and thermal stability outweigh energy density priorities. China's in-house cell production controls cost curves that rivals cannot match, compressing cathode material supplier margins while expanding regional capacity.
- Solid State:Ceramic electrolyte architectures promise energy density improvements and fire risk reduction. Toyota's pilot lines in Japan target automotive qualification timelines ahead of mass production commitments.
- Nickel-Metal Hydride:Mature chemistry retains cost advantages in hybrid applications with moderate electric range requirements.
- Lead Acid:Auxiliary power applications persist in low-voltage systems despite energy density limitations.
Lithium-ion retains absolute technology leadership, while Solid State is gaining share fastest among next-generation development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's eastern coastal provinces where cell production scale and charging density outmatch Indian and Southeast Asian sub-markets. Fleet procurement contracts in Jiangsu and Zhejiang lock in per-kilometer rates that undercut comparable Indonesian or Thai commercial deployments by double-digit margins. This asymmetry redirects foreign capital toward coastal Chinese manufacturing clusters rather than greenfield investments elsewhere in the region.
China
Fleet operators in the Yangtze River Delta and Pearl River Delta dominate commercial procurement volumes through asset-light leasing models. MIIT enforcement of GB standards for battery safety and vehicle connectivity mandates replacement timelines that accelerate logistics fleet turnover. Shenzhen and Shanghai anchor the densest fast-charging corridor networks, eliminating range anxiety for depot-to-depot operators running fixed routes at maximum daily utilization.
India
Commercial adopters favor plug-in hybrid architectures where grid interconnection queues for depot infrastructure stretch eighteen to twenty-four months. The PLI scheme for advanced chemistry cell batteries localizes pack production and reduces import dependency for vehicle integrators. The National Capital Region and Maharashtra concentrate procurement activity, with logistics operators clustering near substations with confirmed excess capacity to bypass utility approval delays.
Japan
METI coordinates charging infrastructure subsidies with grid stability requirements, creating synchronized investment timelines that cluster deployment near substations with excess capacity. Kansai and Kanto regions respond by concentrating commercial fleet depots around reinforced substations. Toyota's solid-state battery pilot lines in domestic manufacturing clusters target automotive qualification ahead of mass production commitments.
South Korea
Power electronics fabrication clusters create single-point vulnerability for traction inverter availability across regional supply chains. Domestic battery manufacturers expand cathode precursor capacity to secure nickel and cobalt offtake. The Seoul Capital Area and Busan-Ulsan corridor dominate R&D concentration and export-oriented production for regional automakers.
Indonesia
Laterite ore processing integration into cathode precursor production shortens supply chains for regional cell manufacturers seeking nickel security. Domestic fleet electrification lags due to minimal charging density outside Jakarta and Surabaya. The government prioritizes downstream beneficiation policies that attract battery material investments over finished vehicle assembly.
Asia-Pacific Electric Vehicle Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific electric vehicle market. The structure bifurcates between vertically integrated cell manufacturers and platform-focused assemblers relying on external pack supply. Three archetypes dominate: captive battery producers controlling cost curves, dedicated EV platform specialists, and hybrid-system incumbents transitioning powertrain portfolios. Competitive moves concentrate on backward integration into cathode materials and geographic expansion through dedicated regional plants.
Within the integrated manufacturer tier, BYD Auto Co., Ltd and Geely Auto Group exemplify archetypes combining in-house cell production with vehicle assembly. Tesla Inc. occupies a position as a platform-focused specialist dependent on external cell supply relationships. Toyota Motor Corporation anchors the hybrid-transition archetype while advancing solid-state development through domestic pilot lines. These three represent distinct strategic postures rather than direct comparable competitors.
| Leading Market Players |
|---|
| BYD Auto Co., Ltd |
| Tesla Inc. |
| Toyota Motor Corporation |
| Honda Motor Co., Ltd. |
| BMW AG |
| Hyundai Motor Company |
| Geely Auto Group |
| Nissan Motor Co., Ltd. |
| Tata Motors Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for lithium carbonate and cathode precursors lock in supply access for Chinese cell manufacturers while freezing price visibility for fleet operators running per-kilometer leasing models across the Yangtze River Delta. This contract-structure pattern concentrates pricing power with vertically integrated producers possessing captive mining offtake, leaving pack assemblers exposed to spot-market volatility in nickel and cobalt feedstock.
Pricing Analysis
The customization-premium spread between configured-to-order battery packs and standard-format cells has widened as fleet operators demand thermal management modifications for tropical climates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under MIIT GB standards versus BIS testing protocols. Pricing pressure stems from lithium iron phosphate chemistry substitution compressing cathode material supplier margins. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership scrutiny, while ride-hailing platforms absorb premium pricing for rapid-charge capability.
Supply Chain Analysis
Inventory buffers for power electronics extend lead times to twenty-six weeks as fabrication clusters in Taiwan and South Korea face capacity constraints. Geographic supply concentration centers on China for cell production, Indonesia for laterite ore processing, and Australia for spodumene concentrate. Raw material dependencies include lithium carbonate, nickel sulfate, and cobalt hydroxide. Single-source vulnerability in semiconductor fabrication creates chokepoint risk for traction inverter availability. Distribution runs through captive battery subsidiaries supplying OEM assembly plants rather than merchant market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific electric vehicle market sits in early-cycle expansion as fleet electrification compresses payback periods below internal combustion thresholds across logistics and ride-hailing applications. China's dual carbon goals and India's PLI scheme for advanced chemistry cells accelerate commercial adoption timelines.
For Market Incumbents: Fortify cost position through backward integration into cathode precursor production in Indonesian nickel processing zones. Secure long-term offtake agreements for lithium spodumene from Australian hard-rock mines to offset spot-price volatility. Defend against emerging platform-focused specialists by expanding fast-charging infrastructure partnerships in the Yangtze River Delta. For New Entrants and Emerging Players: Anchor in India's plug-in hybrid commercial segment where grid interconnection queues delay pure-electric depot infrastructure. Target mid-sized logistics operators in Maharashtra and Gujarat lacking capital for direct fleet ownership. Pursue asset-light leasing models bundling charging infrastructure into per-kilometer contracts. For Investors and Strategic Acquirers: Thermal management engineering boutiques with Chinese university recruitment pipelines represent acquisition targets with scarce capability. Long-term viability hinges on qualification timelines for solid-state automotive applications. Monitor Japan's METI subsidy synchronization with grid stability commitments as inflection indicator for infrastructure rollout feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive cell offtake from Chinese producers secures cost curves unavailable to merchant market buyers. |
| Charging Infrastructure Partnership | METI-coordinated subsidies in Kansai and Kanto cluster deployment near substations with excess capacity. |
| Platform Standardization | Dedicated skateboard architectures reduce development fragmentation across GB, BIS, and JIS certification frameworks. |
| Geographic Manufacturing Footprint | Indonesian plants capture laterite ore integration benefits for regional cathode precursor supply. |
| Software-Defined Vehicle Investment | Telematics retrofitting enables legacy diesel fleet integration with electrification planning tools. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers, OEM platform engineers, battery cell manufacturing executives, and charging infrastructure developers. Secondary validation drew from MIIT GB standard filings, BIS certification registries, vehicle production databases, and customs trade records for lithium carbonate and nickel sulfate. Bottom-up triangulation across fleet deployment schedules and top-down reconciliation against national electrification targets anchored volume estimates.
Across the analysis window, the forecasting framework modeled vehicle type, customer segment, battery chemistry, and charging infrastructure format as core segmentation dimensions. CAGRs were derived from replacement cycle acceleration under China's dual carbon enforcement and PLI scheme localization effects. Industry-specific inputs included grid interconnection queue timelines from Indian utility disclosures and METI subsidy synchronization schedules from Japanese regulatory filings.
Material uncertainties — lithium price volatility, semiconductor fabrication capacity constraints, and divergent national subsidy phase-out calendars — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding cathode chemistry substitution rates and fleet utilization intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Scooter Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
New Energy Vehicle (NEV) Market